Key Takeaways
- A $5.9 billion fund more than tripled its Alphabet stake and added heavily to Danaher and Visa in the quarter ended June 30.
- Danaher and Visa have gained more than 20% each since, while Alphabet is down 17% after its capital spending outran its operating cash flow.
- Analysts’ average target sits 35% above Alphabet’s price, against 12% for Danaher and 5% for Visa.
- Alphabet is the one of the three the numbers back best today, as long as its spending turns into revenue.
A fund that more than tripled its Alphabet (GOOGL) stake by June 30 has watched the stock fall 17% since. Its other two big adds, Danaher (DHR) and Visa (V), are up more than 20% each.
The fund is Anomaly Capital Management, which manages $5.88 billion in all, according to its latest Form ADV. Its 13F for the quarter ended June 30, filed Aug. 14, is still its latest, with $2.62 billion of US stocks in 24 positions. Alphabet, Danaher and Visa were its No. 2, No. 3 and No. 4 holdings.
Alphabet fell, and the targets didn’t
The fund held 899,813 Alphabet shares worth $322 million at June 30, 12.3% of its 13F stocks, after adding 249% more in the quarter. The stock now sits 28% below its 52-week high. The steepest drop came after its third-quarter report on Oct. 28: Google Cloud revenue rose 103% to $31 billion, but capital spending of $51.4 billion outran $42.3 billion of operating cash flow, and Alphabet said it would spend significantly more in 2027. The stock fell 13% the next day.
Analysts haven’t followed it down. Their consensus target rose from $317 a year ago to $400 today, though it’s off its $433 peak in July:
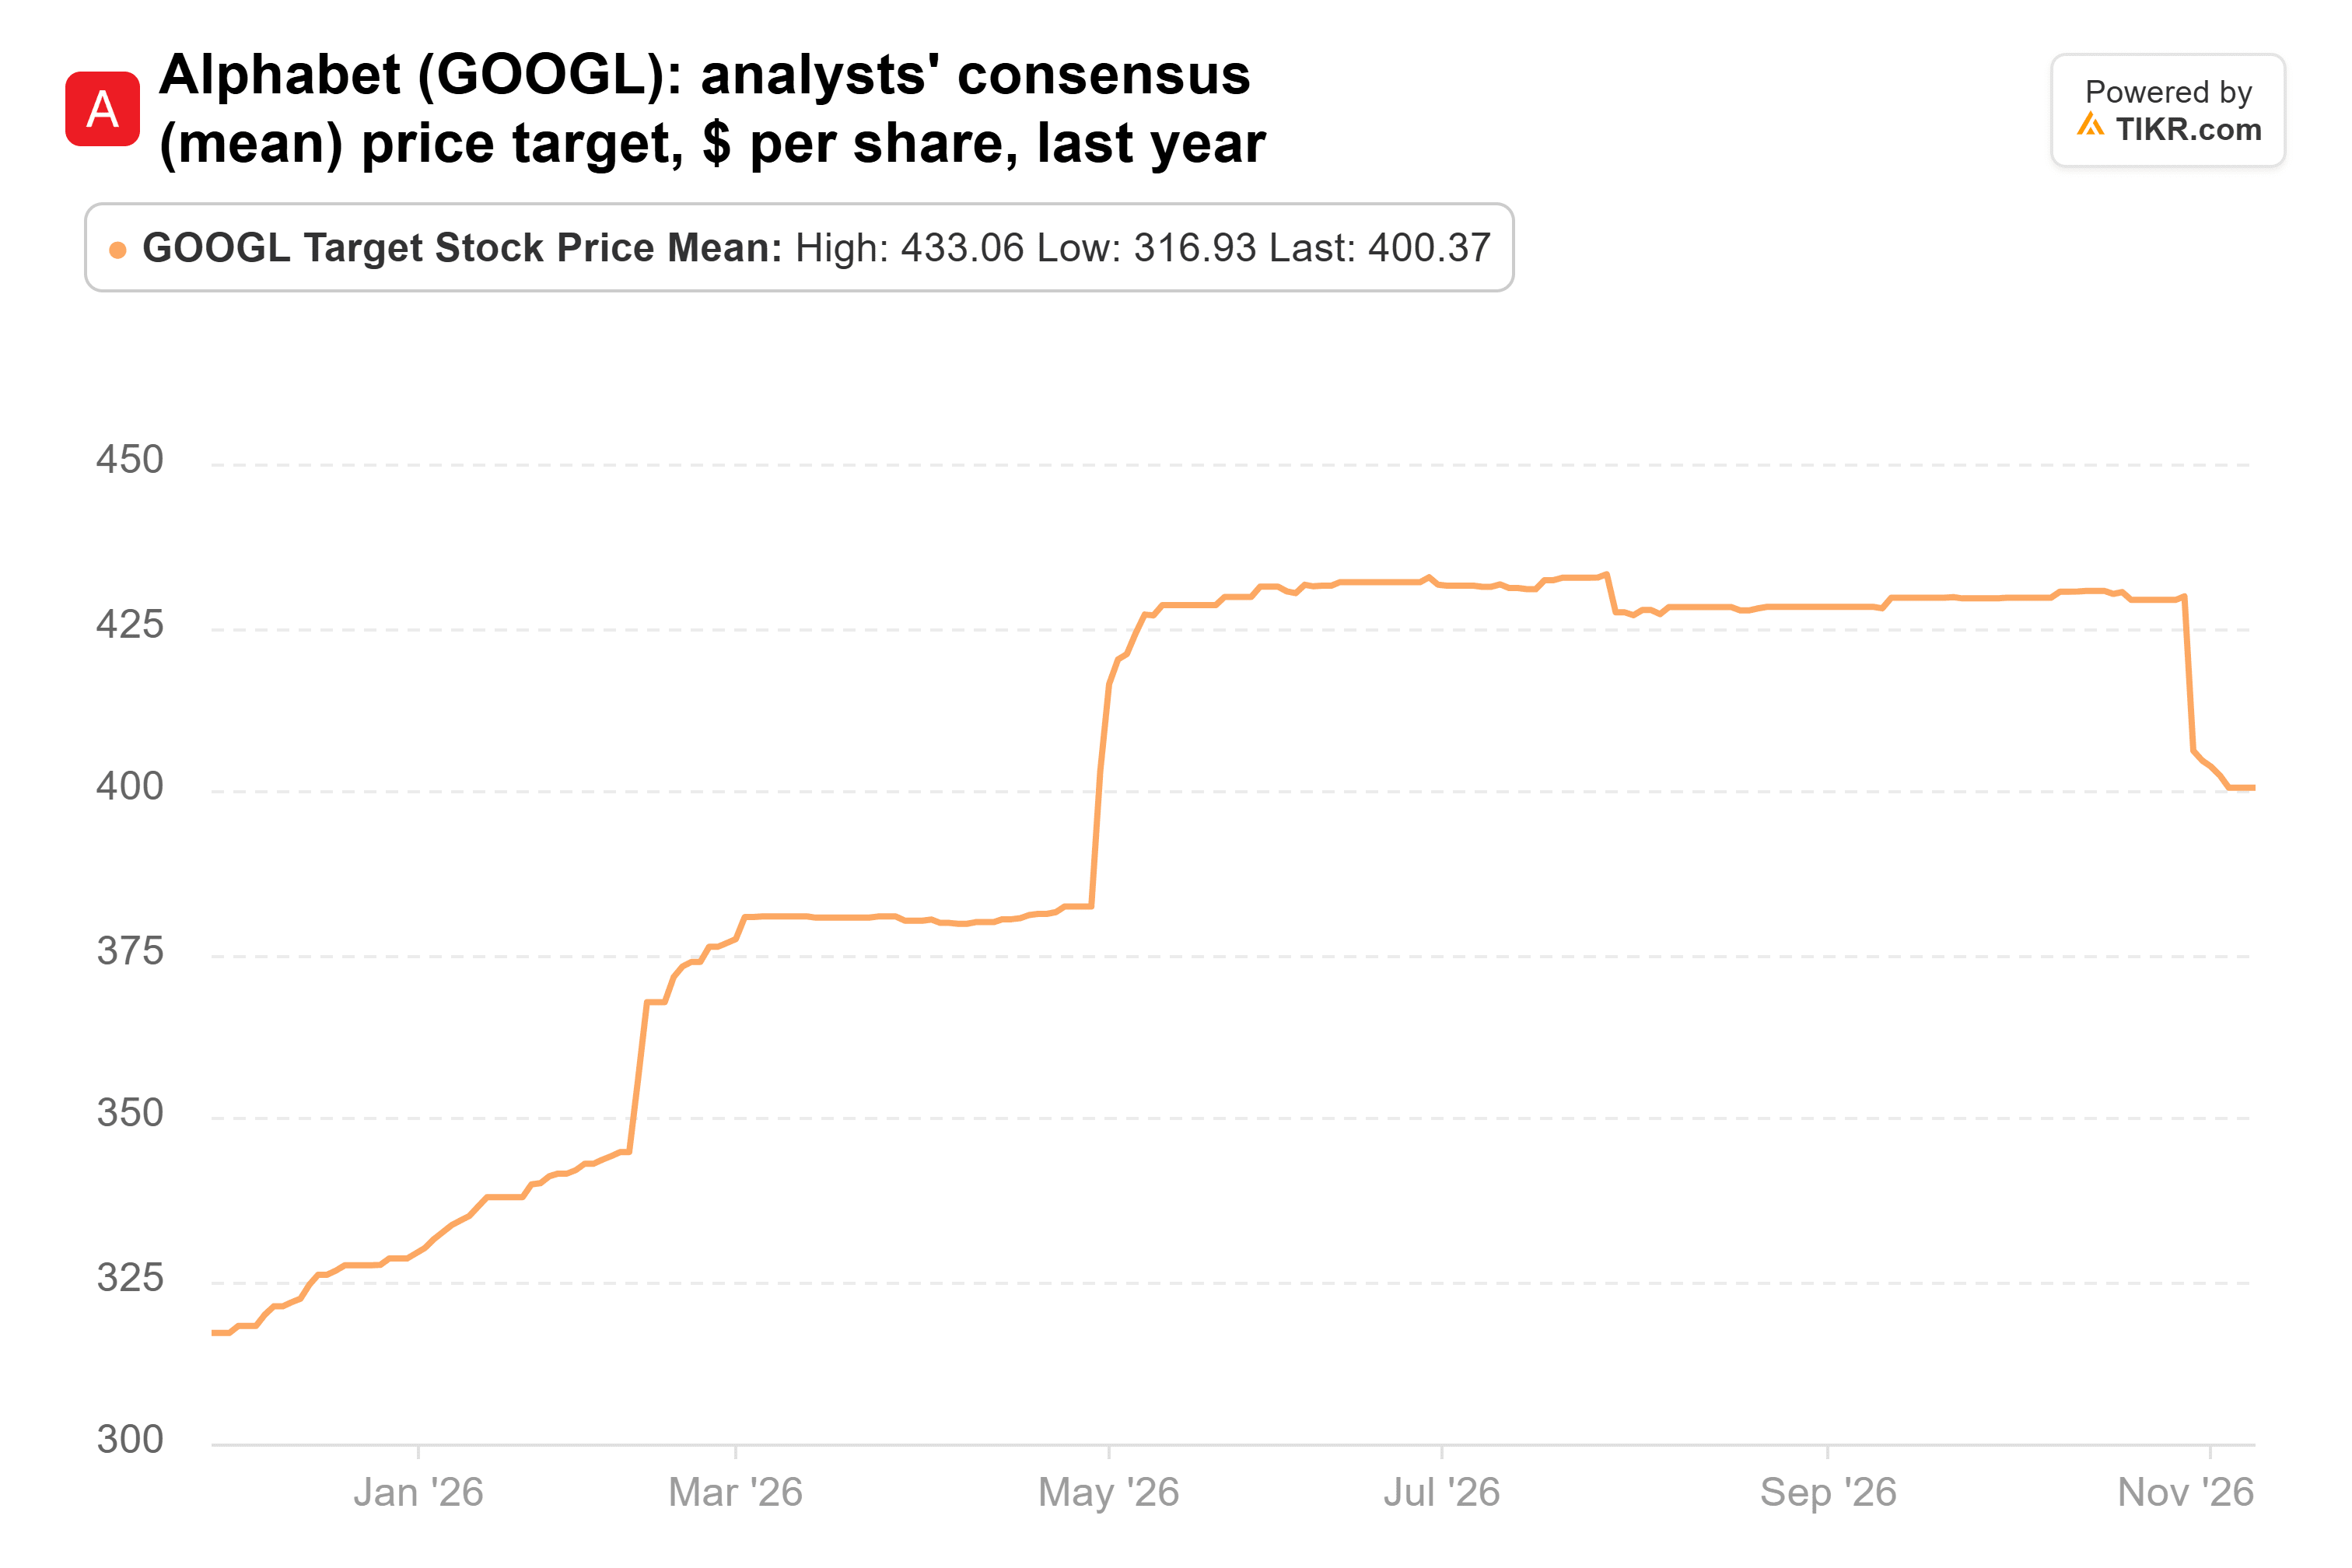
Even the lowest of the 58 analysts’ targets, $300, is above the stock’s $295.77 close. And Alphabet trades at about 21x forward earnings.
TIKR tracks 58 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Danaher’s orders are turning
Danaher was the fund’s No. 3 holding at June 30: 1.37 million shares worth $260 million, 9.9% of its 13F stocks, after it added 79% more in the quarter. The stock is up 22% since and sits 4% below its 52-week high. Its third-quarter report on Oct. 21 beat expectations as trends improved across its end markets. Core revenue growth excluding respiratory products picked up to 5.5% from 4.5% in the second quarter, bioprocessing orders grew in the mid-teens, and Danaher raised its 2026 adjusted EPS guidance to $8.57-$8.62, from $8.45-$8.60. On the call, management said those orders point to faster bioprocessing growth in 2027.
The consensus target has come back with the stock, from a low of $228 in July to $260 today, a bit above the $254 of a year ago:
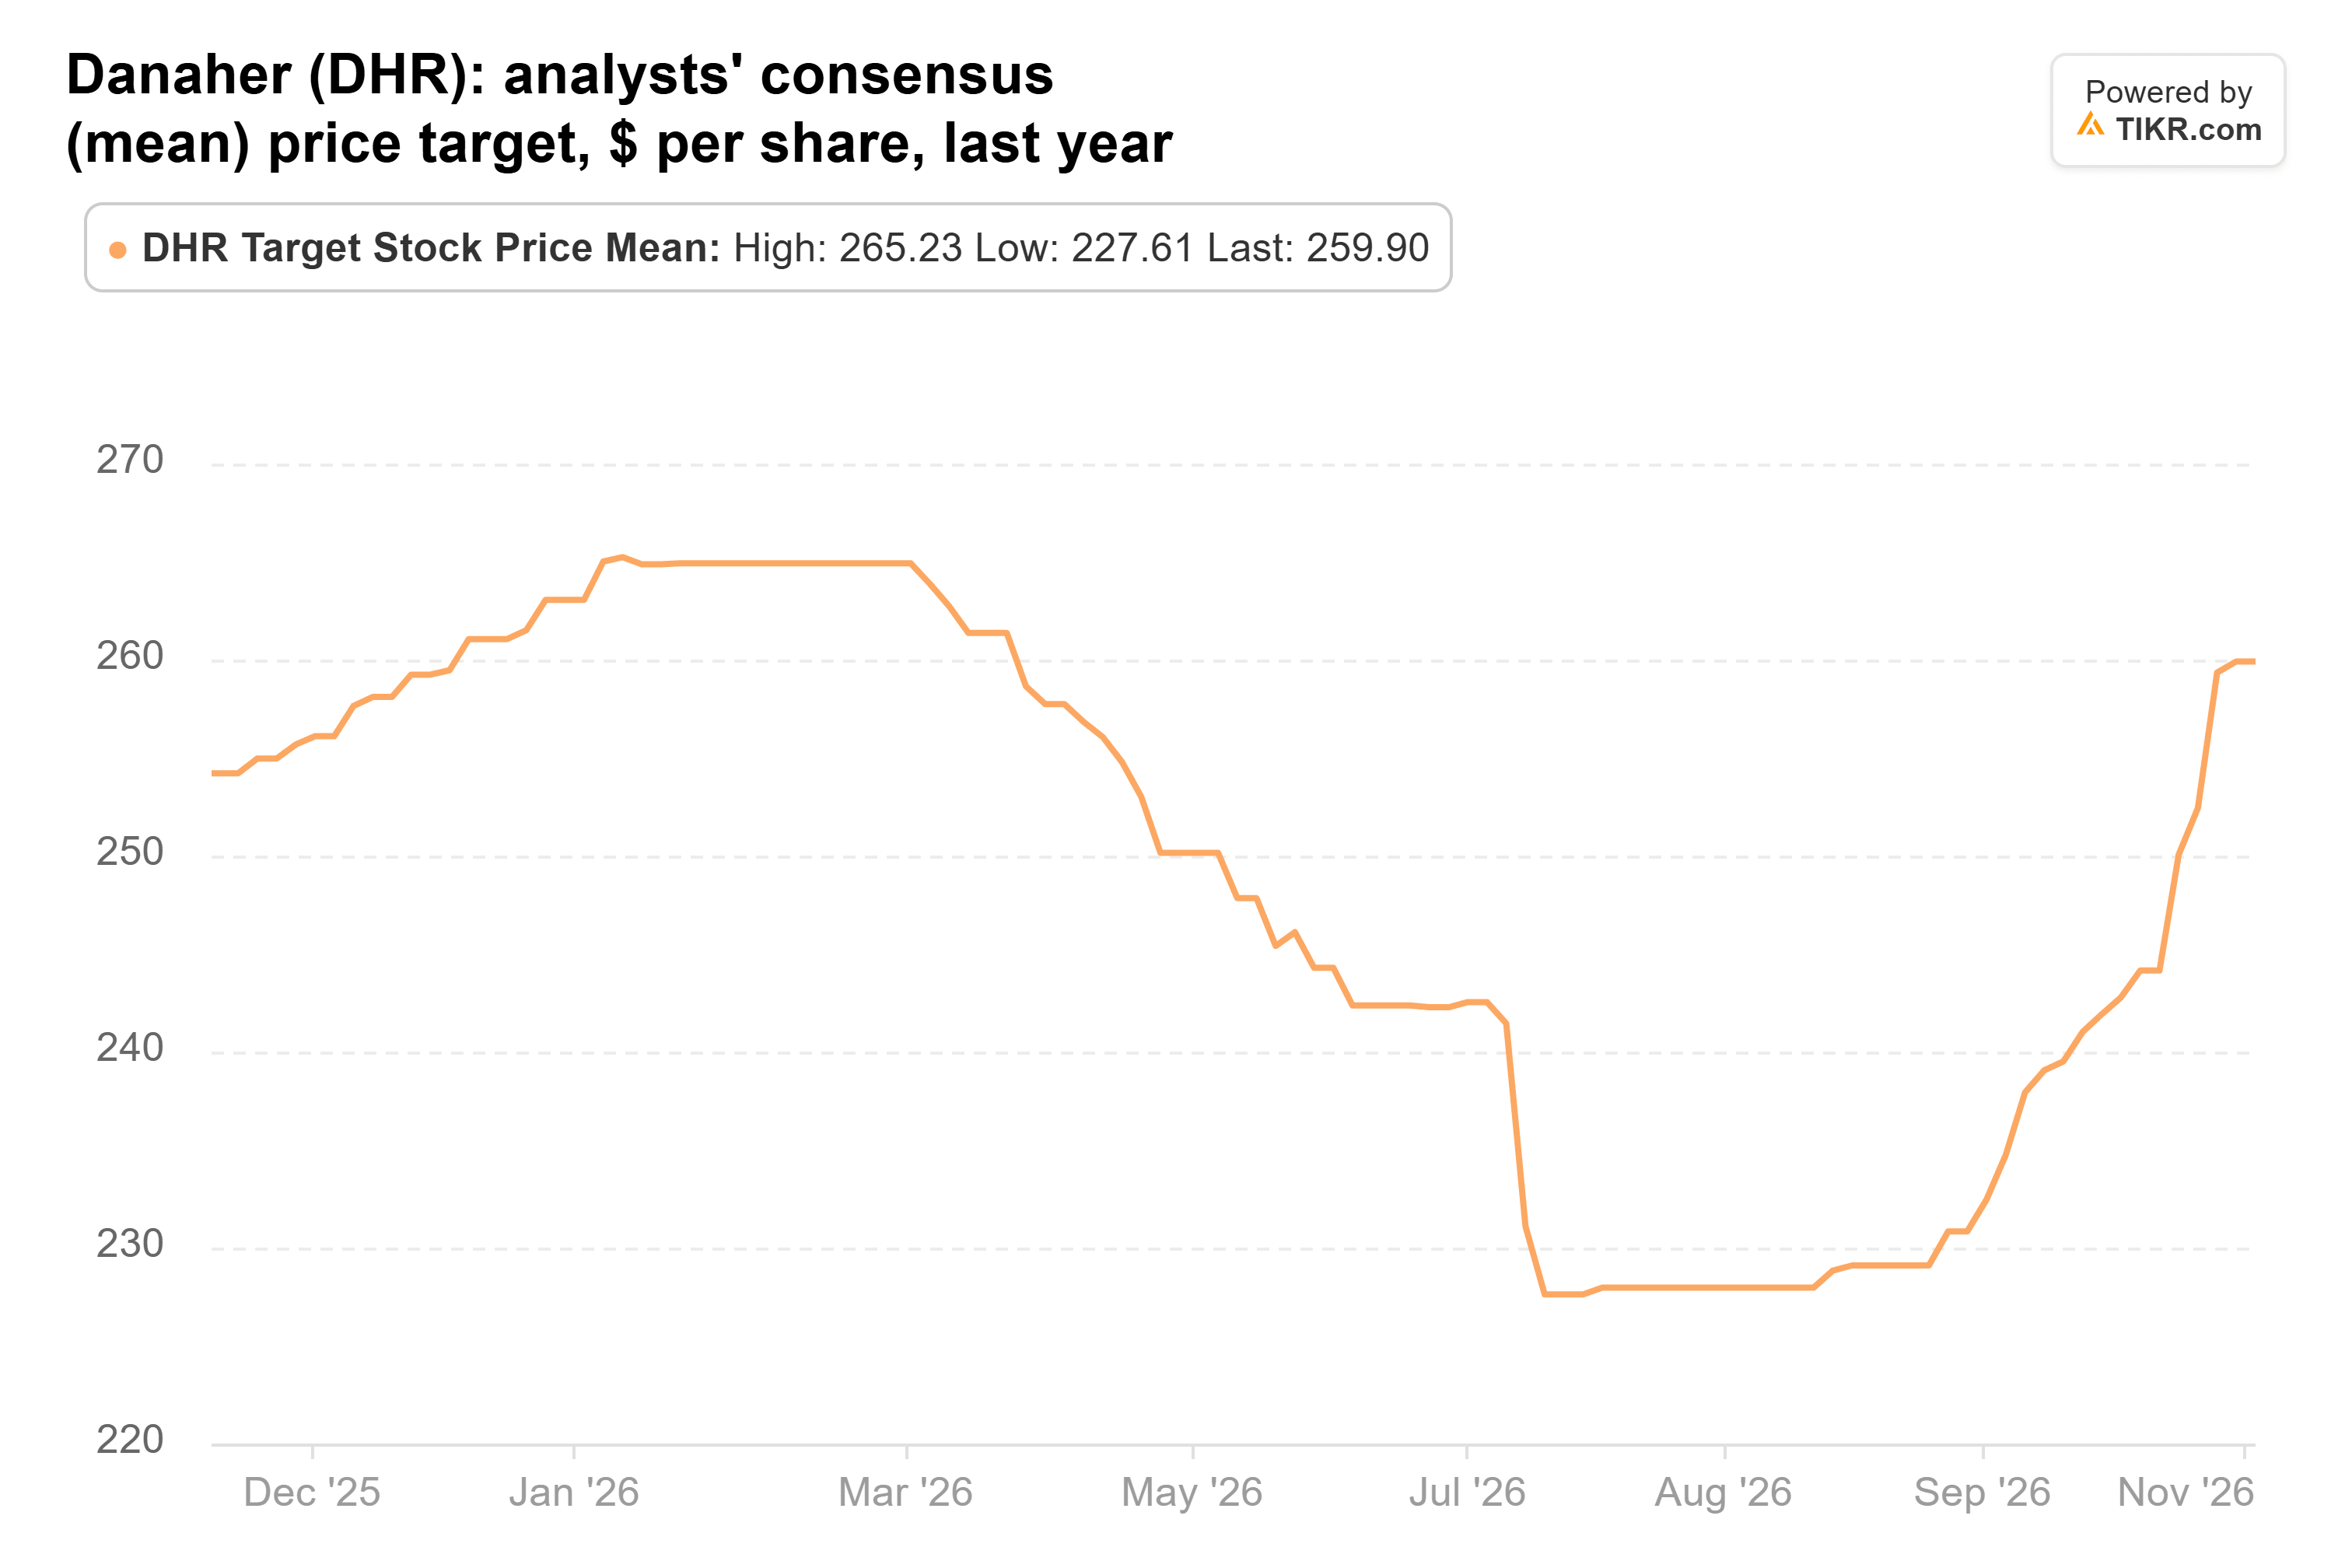
That average of 24 analysts’ targets is 12% above the stock’s $233.02 close, and Danaher trades at about 26x forward earnings. Much of the recovery is already in the price.
Visa has run up to its targets
Visa was No. 4: 717,707 shares worth $246 million, 9.4% of its 13F stocks, after the fund nearly tripled its stake. It’s up 24% since June 30. Visa’s fiscal year ended Sept. 30 with net revenue up 15%, though free cash flow rose just 2% to $22.1 billion. It guided to low double-digit revenue growth for fiscal 2027 as the incentives it pays banks rise faster. On Oct. 19, President Trump pledged to sign the Credit Card Competition Act, which would let merchants send credit card payments over rival networks.
The Street has kept raising its targets anyway. The consensus rose from $394 a year ago to $449 now, its high:
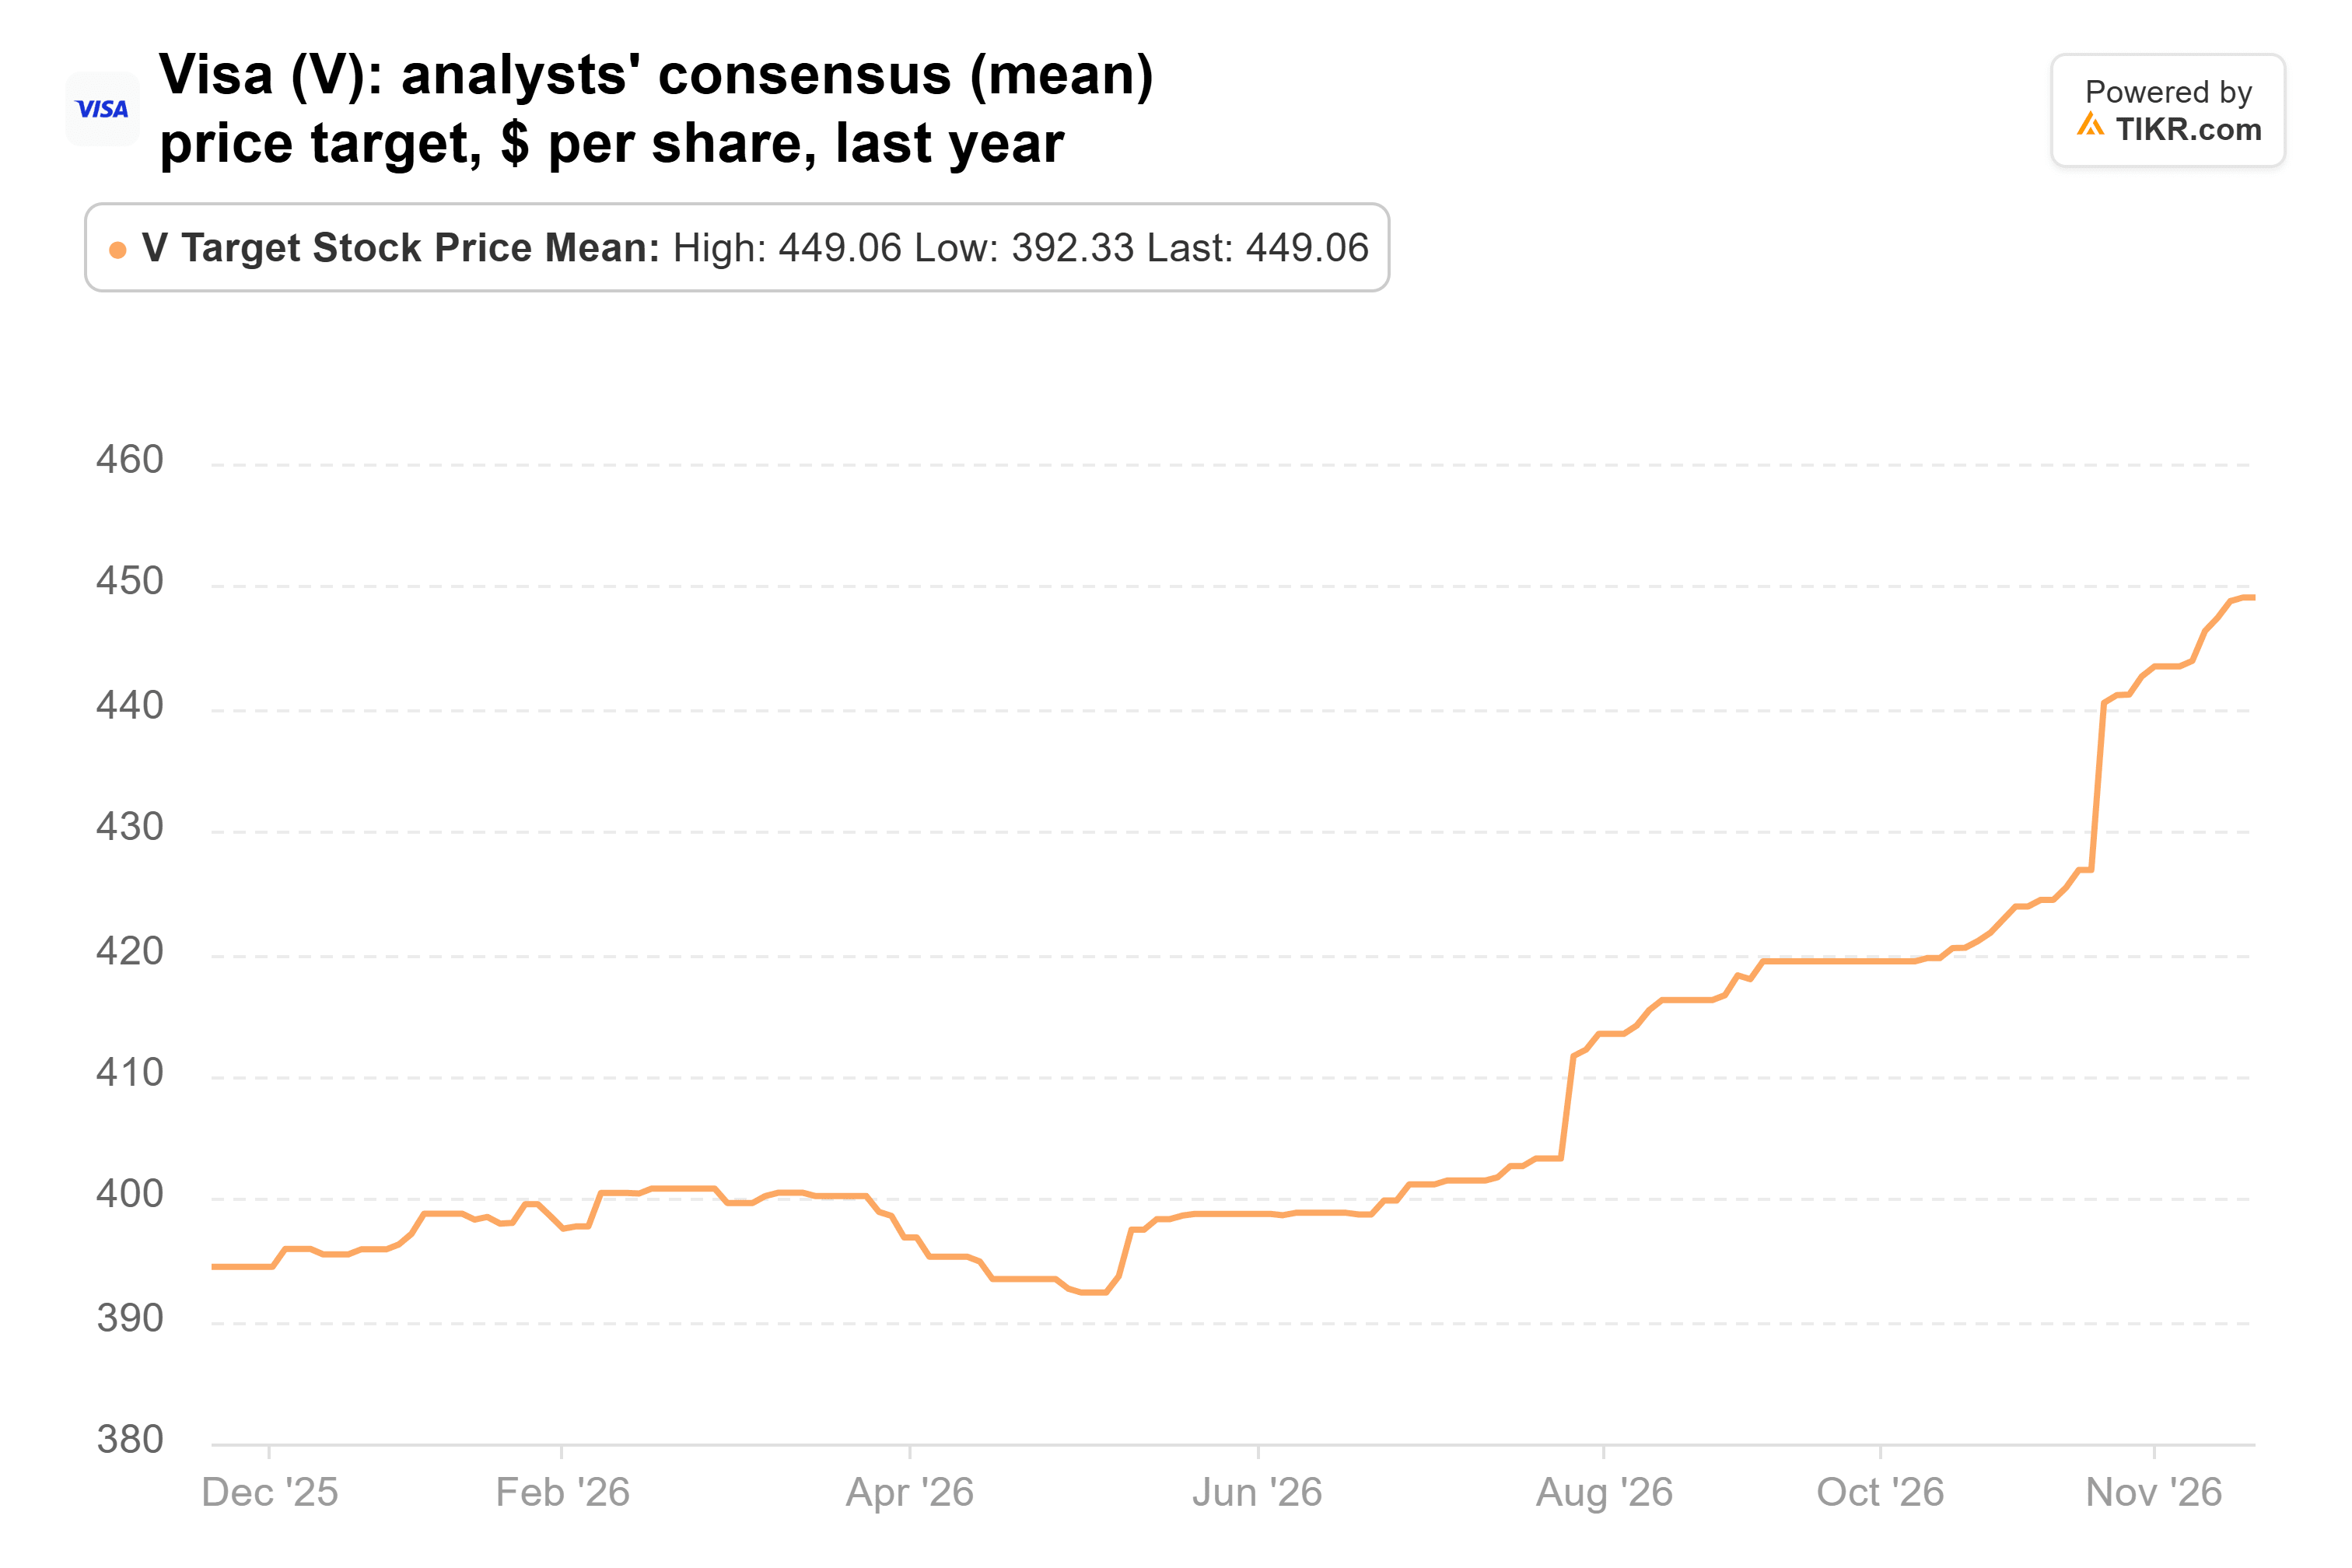
That leaves 5% upside from the $425.76 close. At about 28x forward earnings, Visa trades above the 27.6x it has averaged at quarter-ends since 2014.
Alphabet is the one the numbers back
Of the three, Alphabet is the one I’d buy today. It’s the only one that has fallen since June 30, analysts see 35% upside, and it trades at a lower multiple than Danaher or Visa. Those two are fine businesses whose rebounds have already been paid for, and Visa’s multiple leaves little room for a slower fiscal 2027.
The risk is Alphabet’s capex. It has topped operating cash flow for two straight quarters, and Alphabet plans to spend more in 2027. The payoff has to show up somewhere, and Morgan Stanley sees Alphabet’s TPU sales jumping to $84 billion.
The fund’s 13F for the quarter ended Sept. 30, due by Nov. 16, will show whether it kept adding in the third quarter. It won’t show anything after Alphabet’s October drop. Alphabet’s next report, early next year, is the bigger test: operating cash flow has to start catching up with the capex.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!