Key Takeaways
- Affirm agreed to buy Ratepay, a Berlin pay-by-invoice provider, from Nexi, with closing expected in the first half of 2027.
- Affirm’s revenue rose 35% to $1.26 billion, but international markets added only about 1 point of its 34% GMV growth.
- Provision for credit losses jumped 59%, and 30-day delinquencies rose to 2.9% from 2.5% in June.
- The fiscal second-quarter report, expected in early February, will show whether holiday lending keeps credit in check.
Affirm (AFRM) is shopping for growth abroad. On November 9, it agreed to buy Ratepay, a German pay-by-invoice provider, from Nexi (NEXI).
Nexi is selling to focus on its core payments business. Its DACH region, where Ratepay operates, brought in €330.1 million of revenue in 2025, up 7.7%.
Neither side disclosed a price. Affirm said the deal should not materially affect its results or its fiscal 2027 outlook. So for now, this is a strategy story.
That strategy points to Europe. Affirm’s U.S. engine is still humming, yet credit costs are climbing faster than revenue.
Affirm buys a German foothold
Ratepay was founded in Berlin in 2009. It serves online merchants in Germany, Austria and Switzerland, mostly through pay by invoice, where shoppers settle up after the goods arrive.
The key terms:
- Closing is expected in the first half of 2027, pending regulatory approval.
- Nexi will provide transitional support, and the two signed a memorandum to widen their DACH partnership.
- Ratepay plans to add installment loans, Affirm’s core product, under its new owner.
Affirm can easily afford it. It ended September with about $3.0 billion of liquidity and $1.9 billion of net cash. Meanwhile, the core business is still compounding fast…
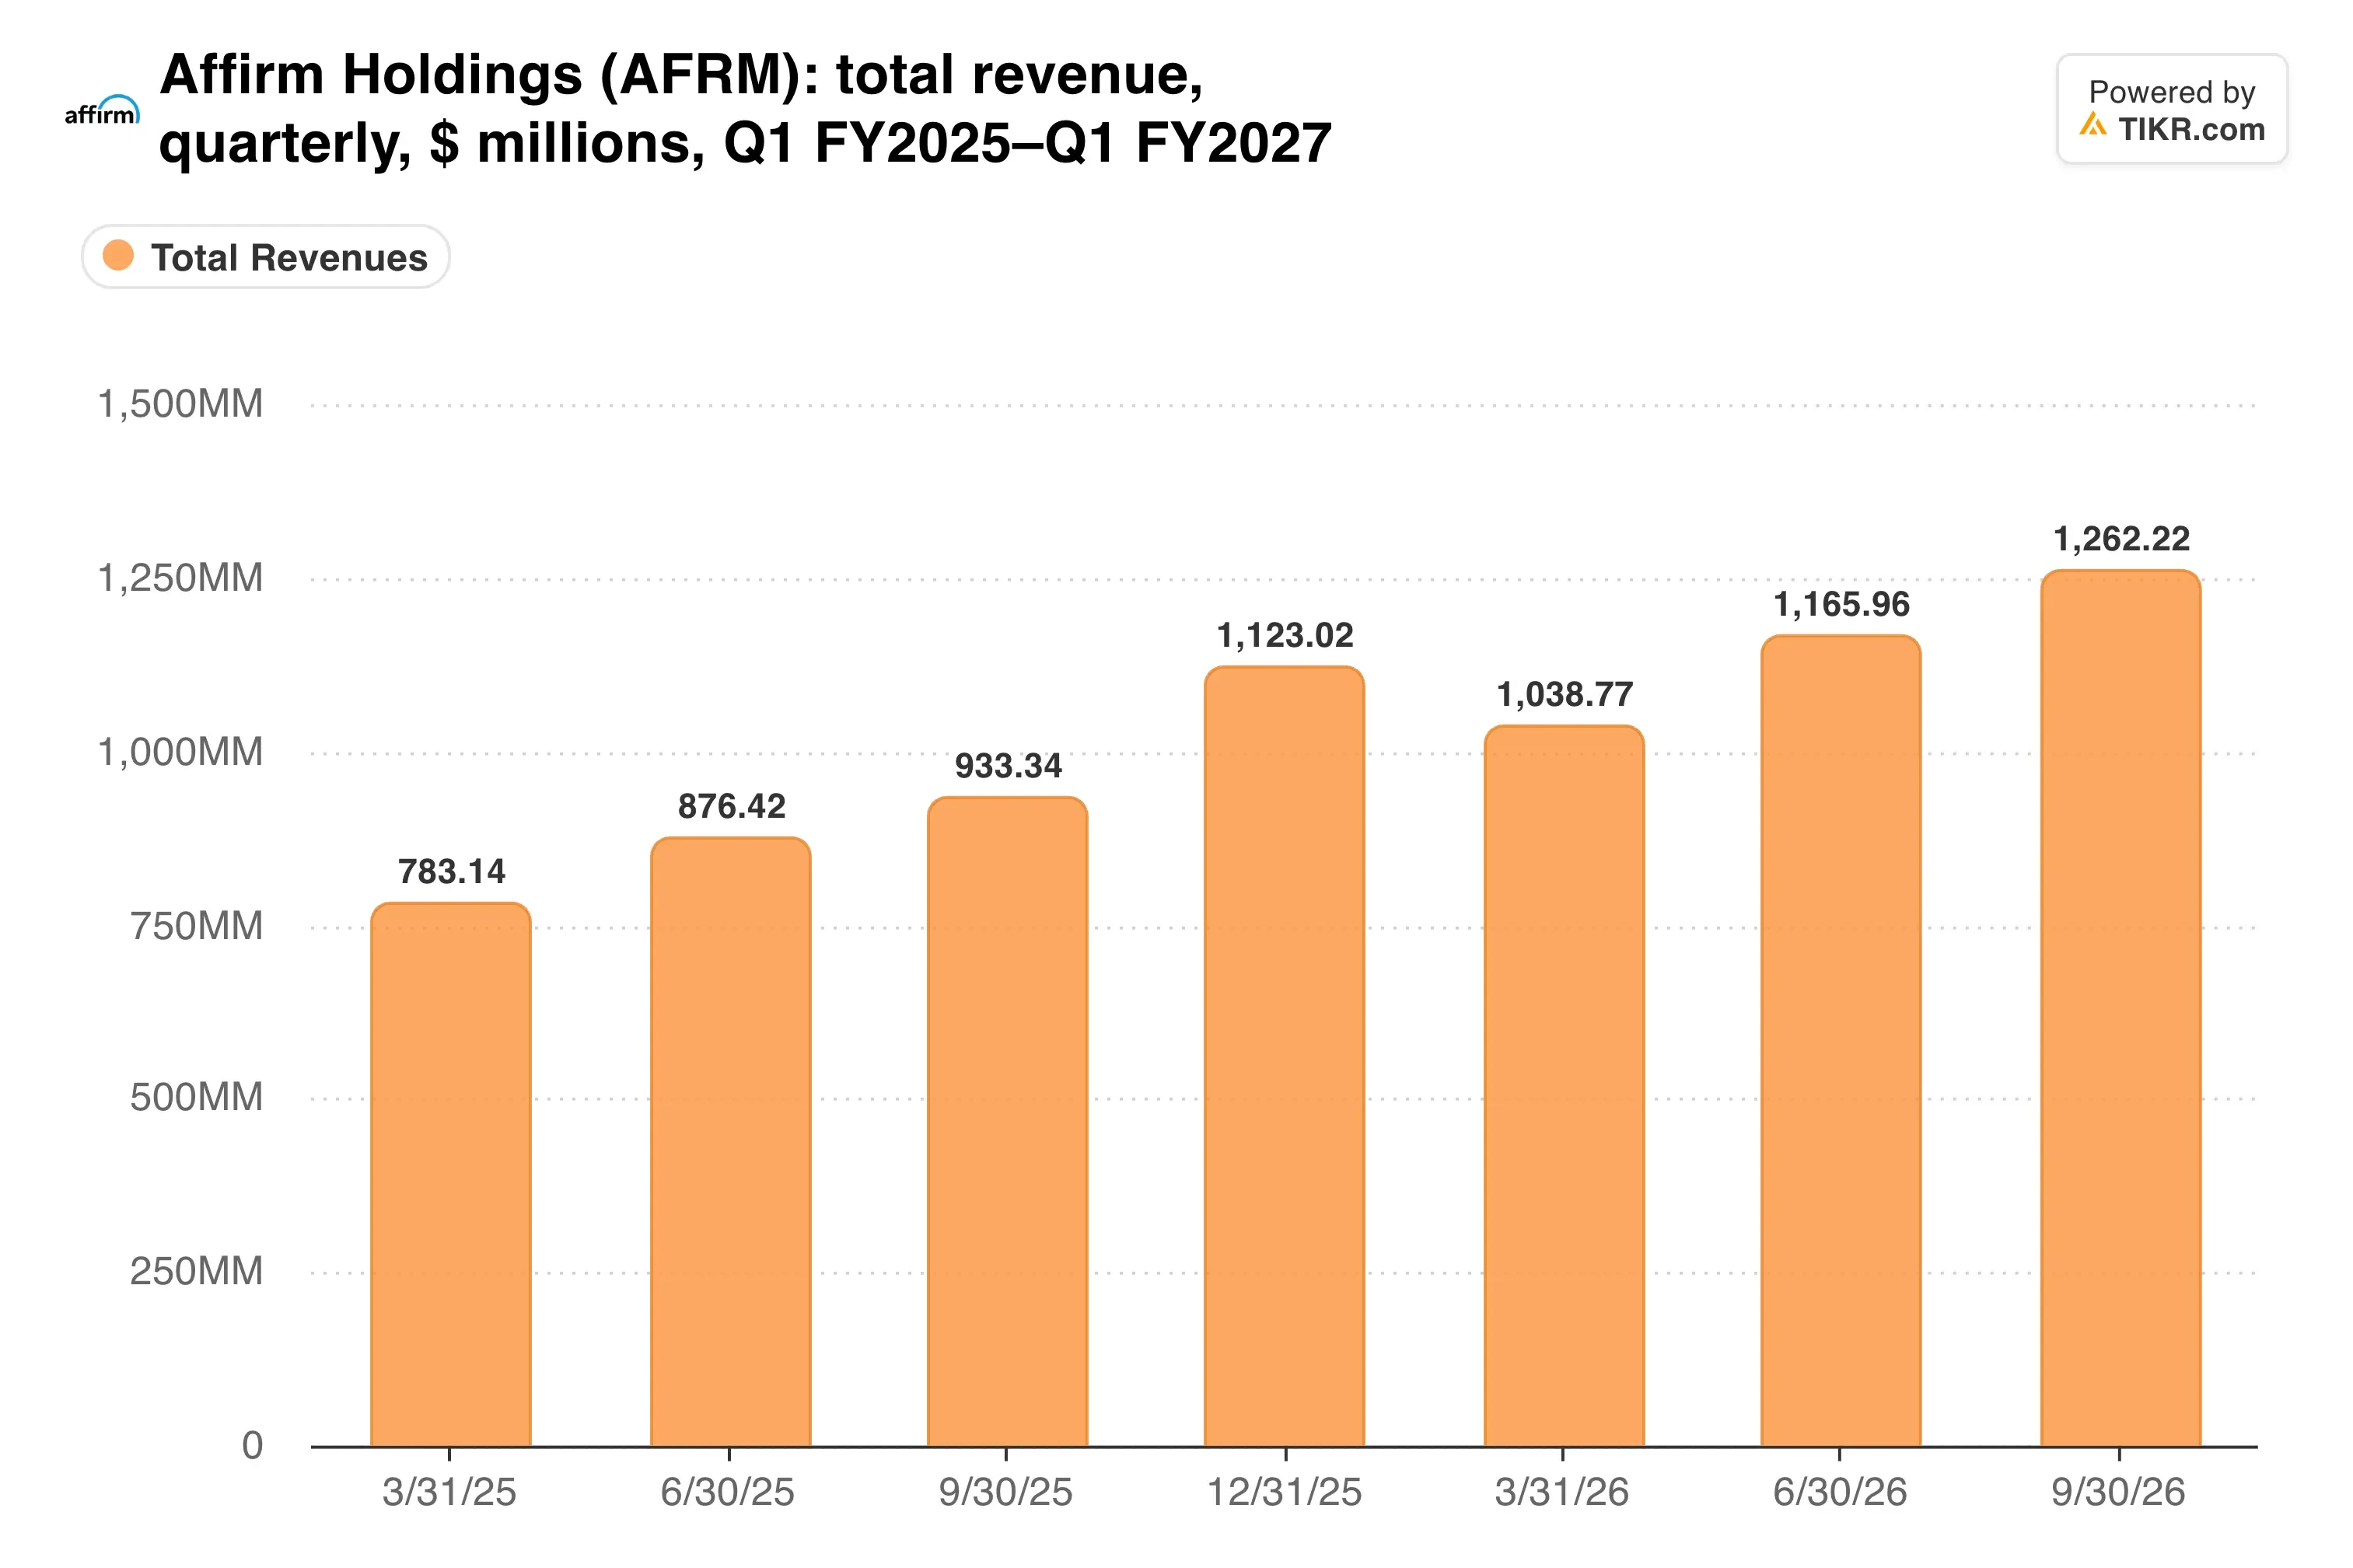
Revenue rose 35% to $1.26 billion in the September quarter, while net income doubled to $164 million, or $0.47 per share.
Europe is still a rounding error
Affirm’s growth is still overwhelmingly American. International markets added about 1 point of its 34% GMV growth in the quarter. Management also does not expect expansion outside North America to contribute materially in fiscal 2027.
The UK and Canada are already live, and Affirm launched with a large enterprise partner in the UK late in the quarter. Germany is different, though, because shoppers there have long favored paying by invoice. Buying Ratepay gives Affirm local merchants and a familiar product from day one.
Back home, the business model is shifting. Card GMV grew 117% to $3.3 billion, and those balances skew toward interest-bearing loans. So how much of the top line now comes from lending?
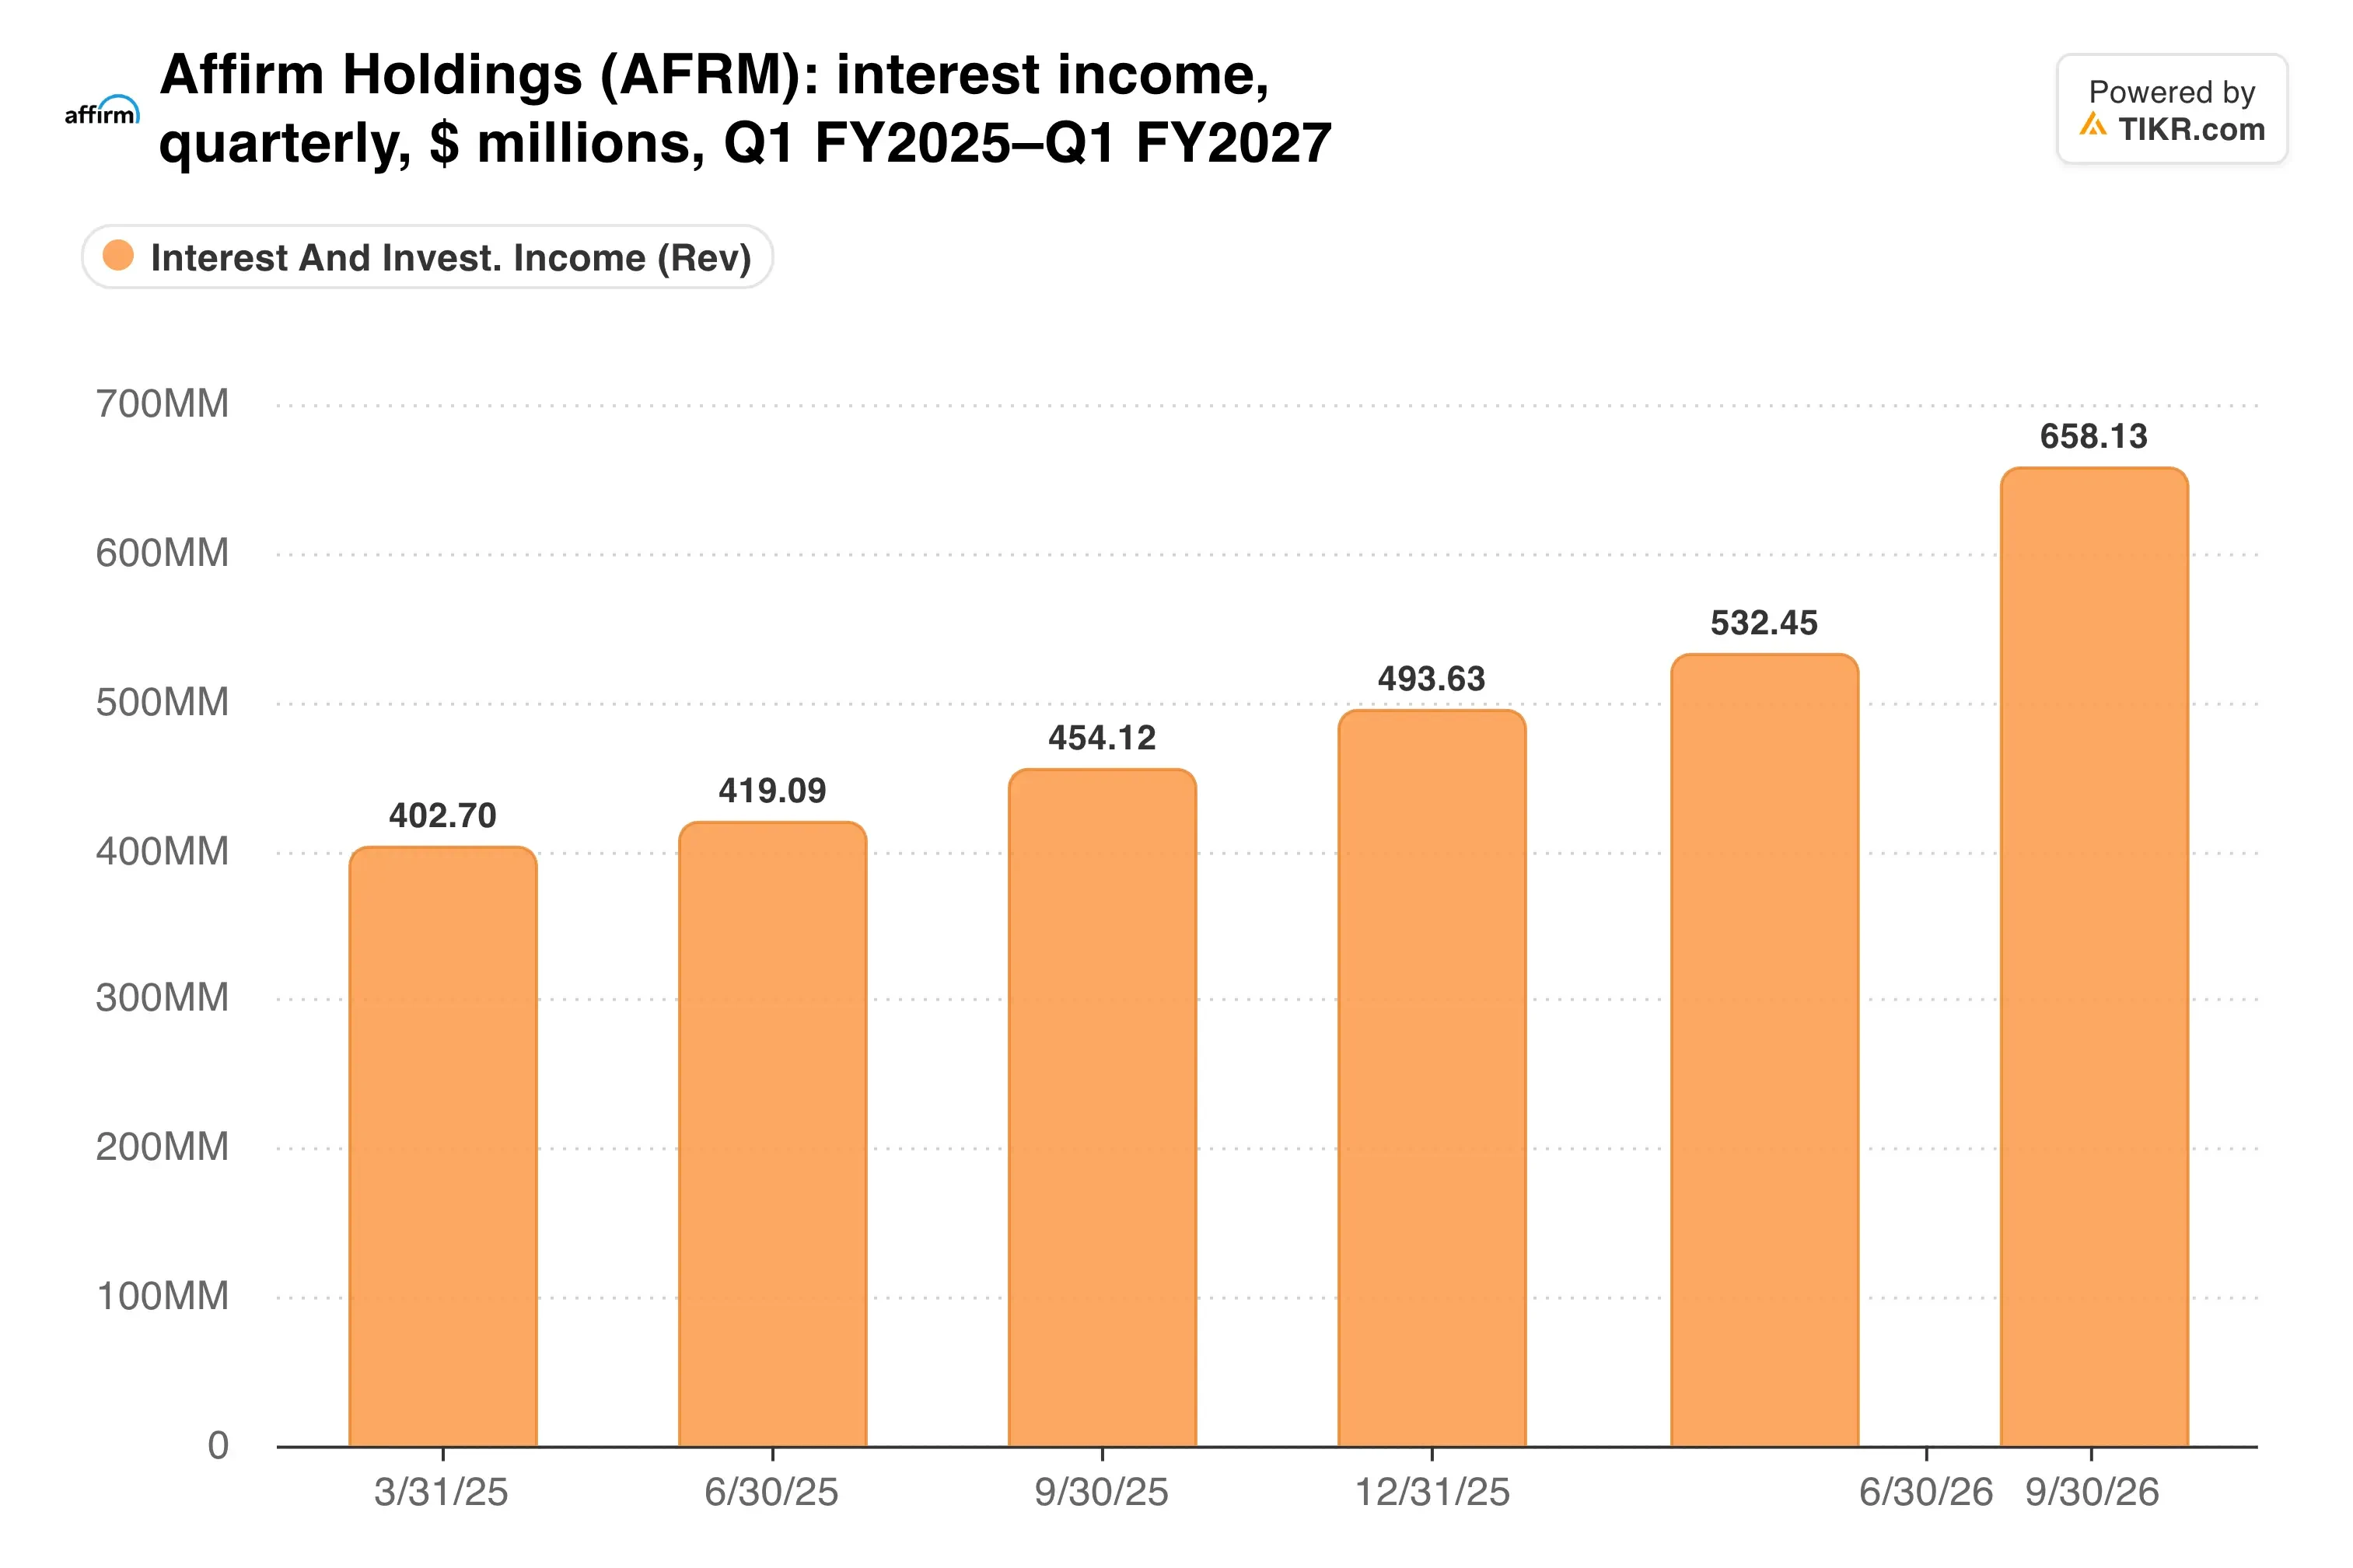
Interest income grew 45% to $658 million, more than half of total revenue. Network revenue grew just 23%. That mix ties Affirm’s results more tightly to the credit cycle.
TIKR tracks 34 analysts on Affirm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Affirm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Affirm’s Analyst Ratings
Credit is the bill coming due
The quarter’s weak spot was credit. Monthly installment loans 30 or more days past due hit 2.9%, up from 2.5% in June and 2.8% a year earlier. Provisions told the same story…
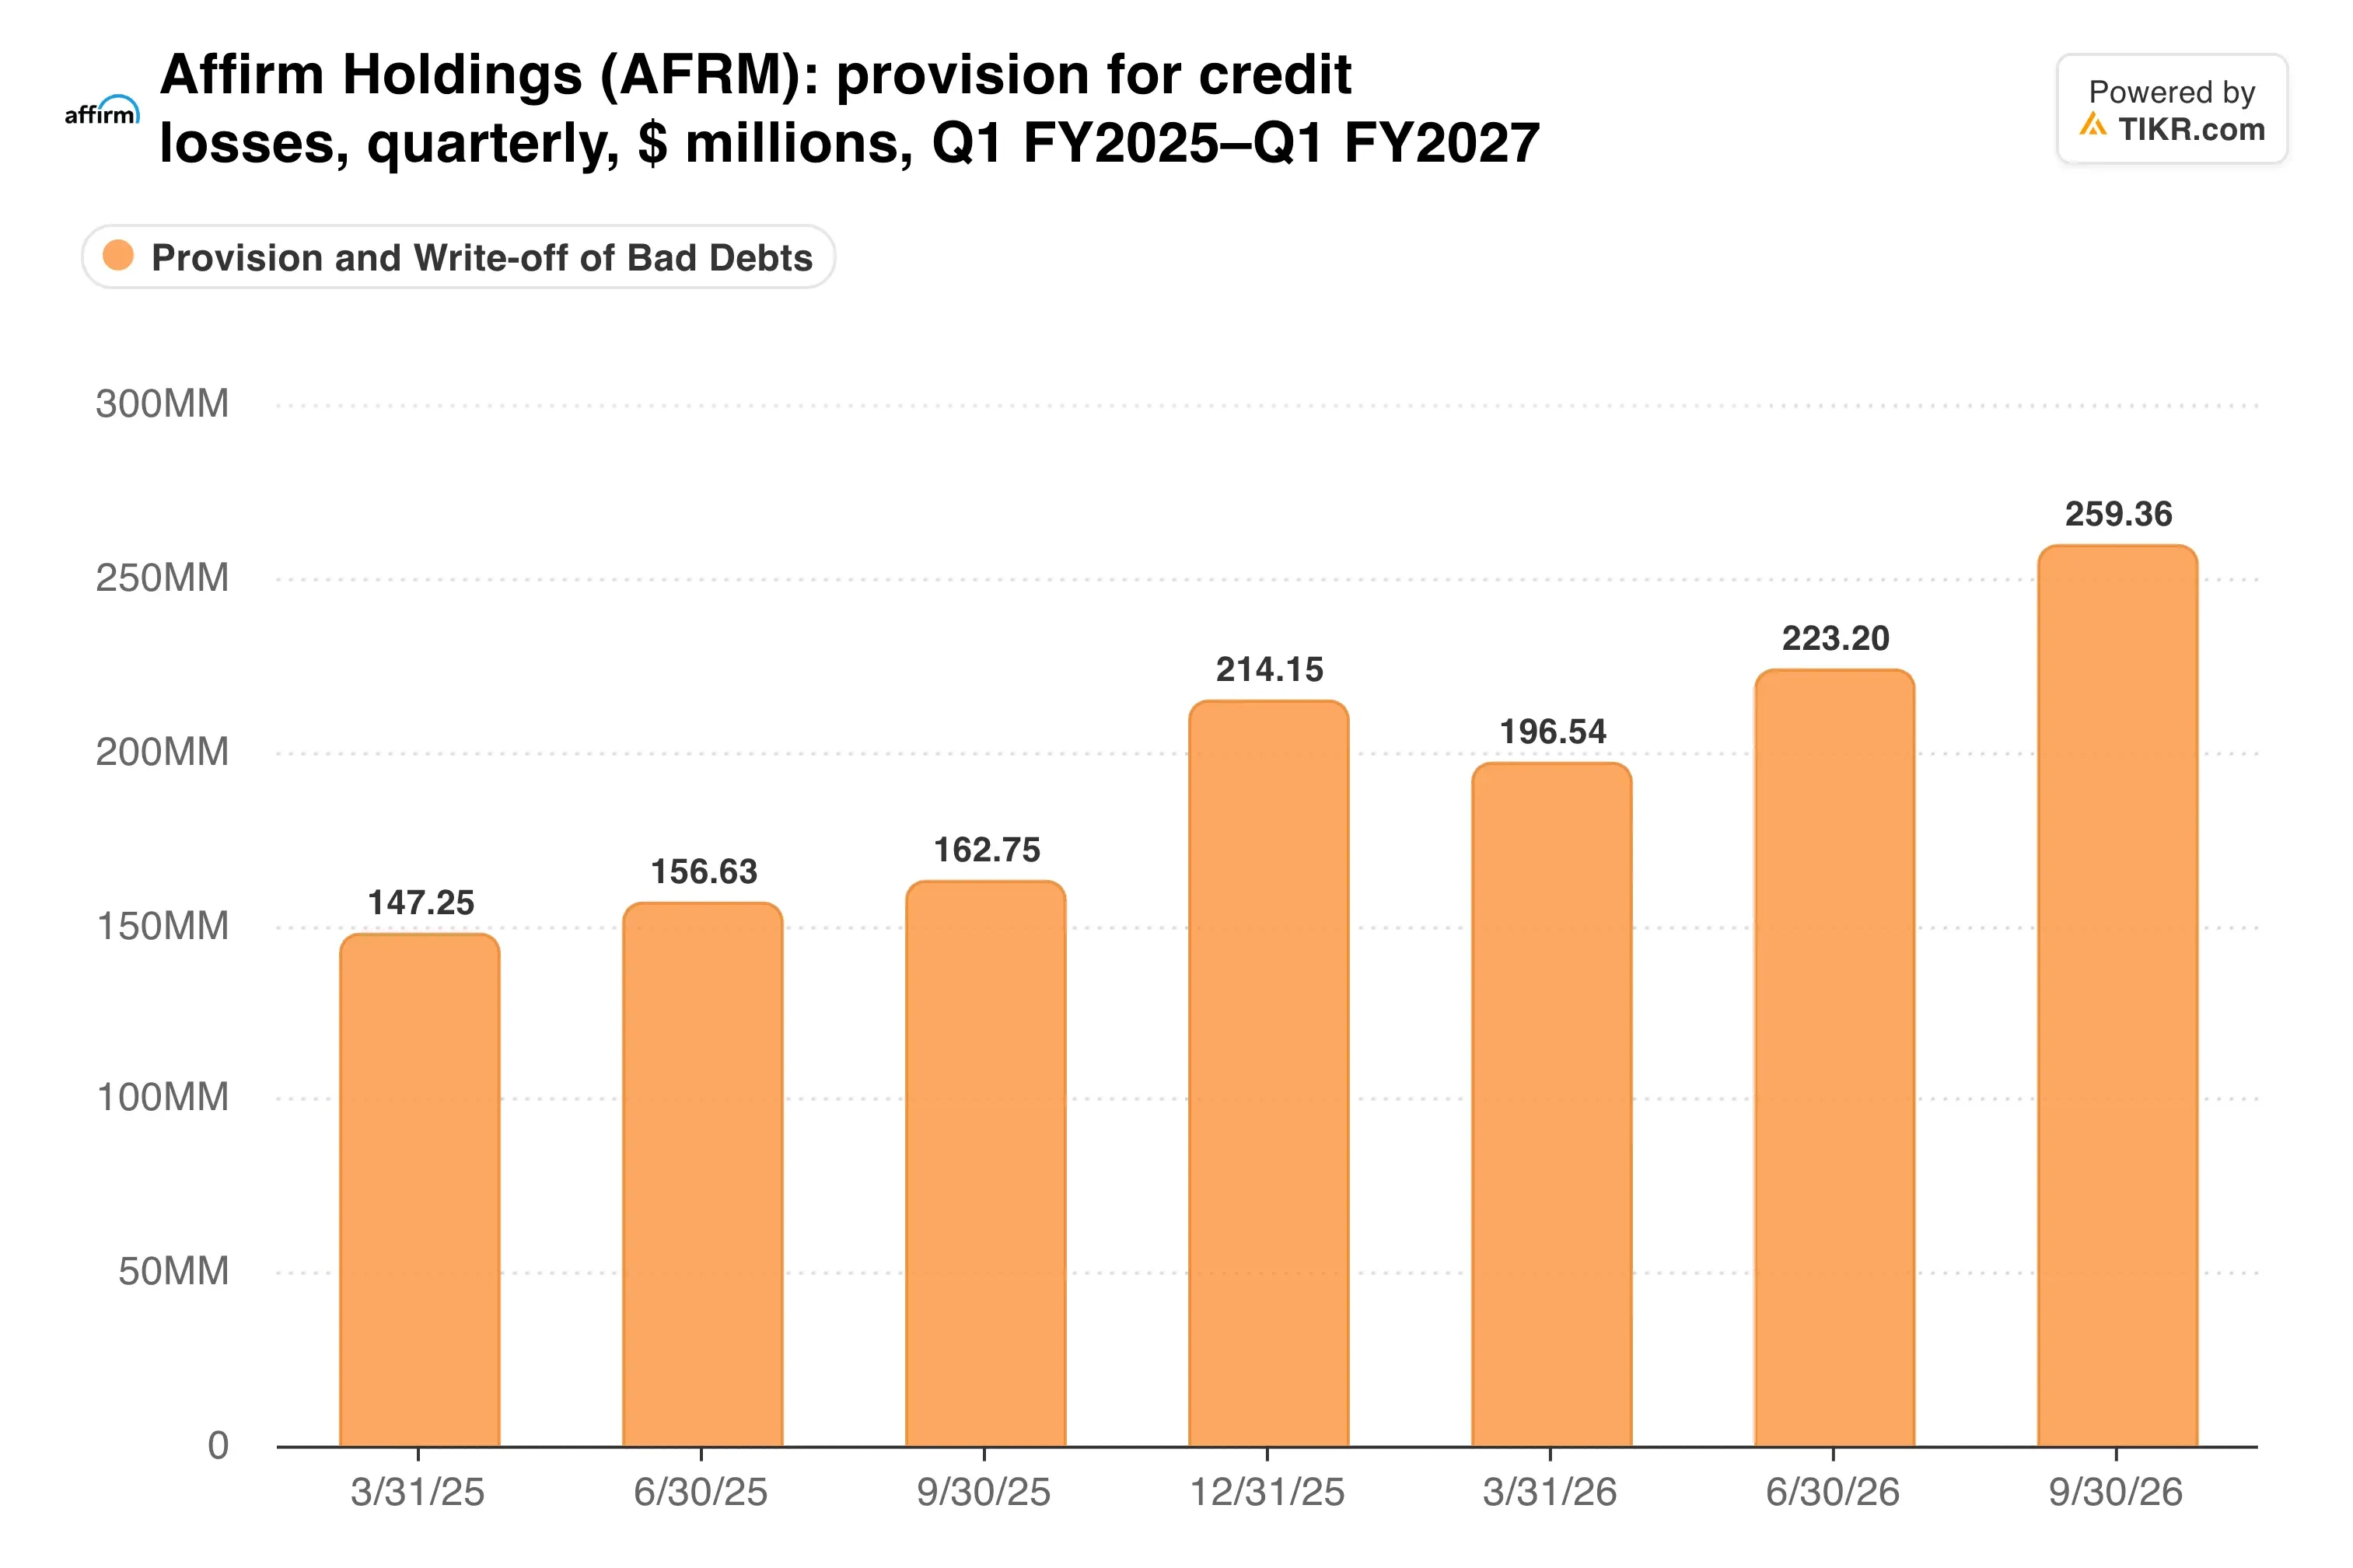
Provision for credit losses rose 59% to $259 million, well ahead of revenue growth. Funding costs also rose 27 basis points from the June quarter as benchmark rates climbed.
Guidance reflects some of that pressure. Affirm expects December quarter revenue of $1.435 billion to $1.465 billion and a GAAP operating margin of 11.5% to 13.5%, below the 14.8% it just posted. Seasonally higher warrant expense explains part of that gap.
CEO Max Levchin sounds unbothered. In his November 5 shareholder letter, he wrote that Affirm is “moving with deliberate aggression, quarter after quarter.”
My take: Ratepay is a sensible, low-risk way into German-speaking Europe, and it won’t strain the balance sheet. Still, it won’t move the numbers for at least a year. Until then, the stock will trade on credit, and I’d want delinquencies to settle before paying up for the European option.
Affirm presents at the UBS Global Technology and AI Conference on December 1. The bigger checkpoint is the fiscal second-quarter report, expected in early February, which will show whether holiday lending pushed delinquencies above 2.9%.
So what is Affirm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Affirm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!