Key Takeaways
- A fund that manages $4.7 billion added to its stakes in MercadoLibre, Mastercard and Visa in the third quarter, according to its 13F.
- MercadoLibre was the biggest of the three additions, and the stock is down 22% since Sept. 30 as its operating margin keeps shrinking.
- Mastercard and Visa are up 14% and 12% since the quarter ended, and analysts’ average targets for both are at their highs for the year.
- Mastercard is the one the numbers back best, with estimates and targets rising and a multiple below its long-run average.
Route One Investment Company’s newest 13F has one bet that’s down 22% and two that are up by double digits.
The filing, for the quarter ended Sept. 30 and filed Nov. 16, shows the fund’s three biggest additions were MercadoLibre (MELI), Mastercard (MA) and Visa (V). The firm manages $4.7 billion in all, according to its latest Form ADV, and its 13F holds $2.33 billion of US stocks across 19 positions.
The biggest add is down 22%
The fund held 81,650 MercadoLibre shares on Sept. 30, 25% more than at June 30. They were worth $141 million, 6.0% of its 13F stocks and its ninth-largest position.
The stock has fallen 22% since. MercadoLibre’s third-quarter revenue rose 45% to $10.75 billion, but its GAAP operating margin fell to 6.3% from 9.8% as it spent on free shipping, almost 20% more fulfillment space and affiliate marketing in Brazil.
Goldman Sachs cut its target to $2,100 from $2,230 on Nov. 11 and kept its Buy rating. The average target fell from about $2,850 a year ago to $2,153, its low for the year.
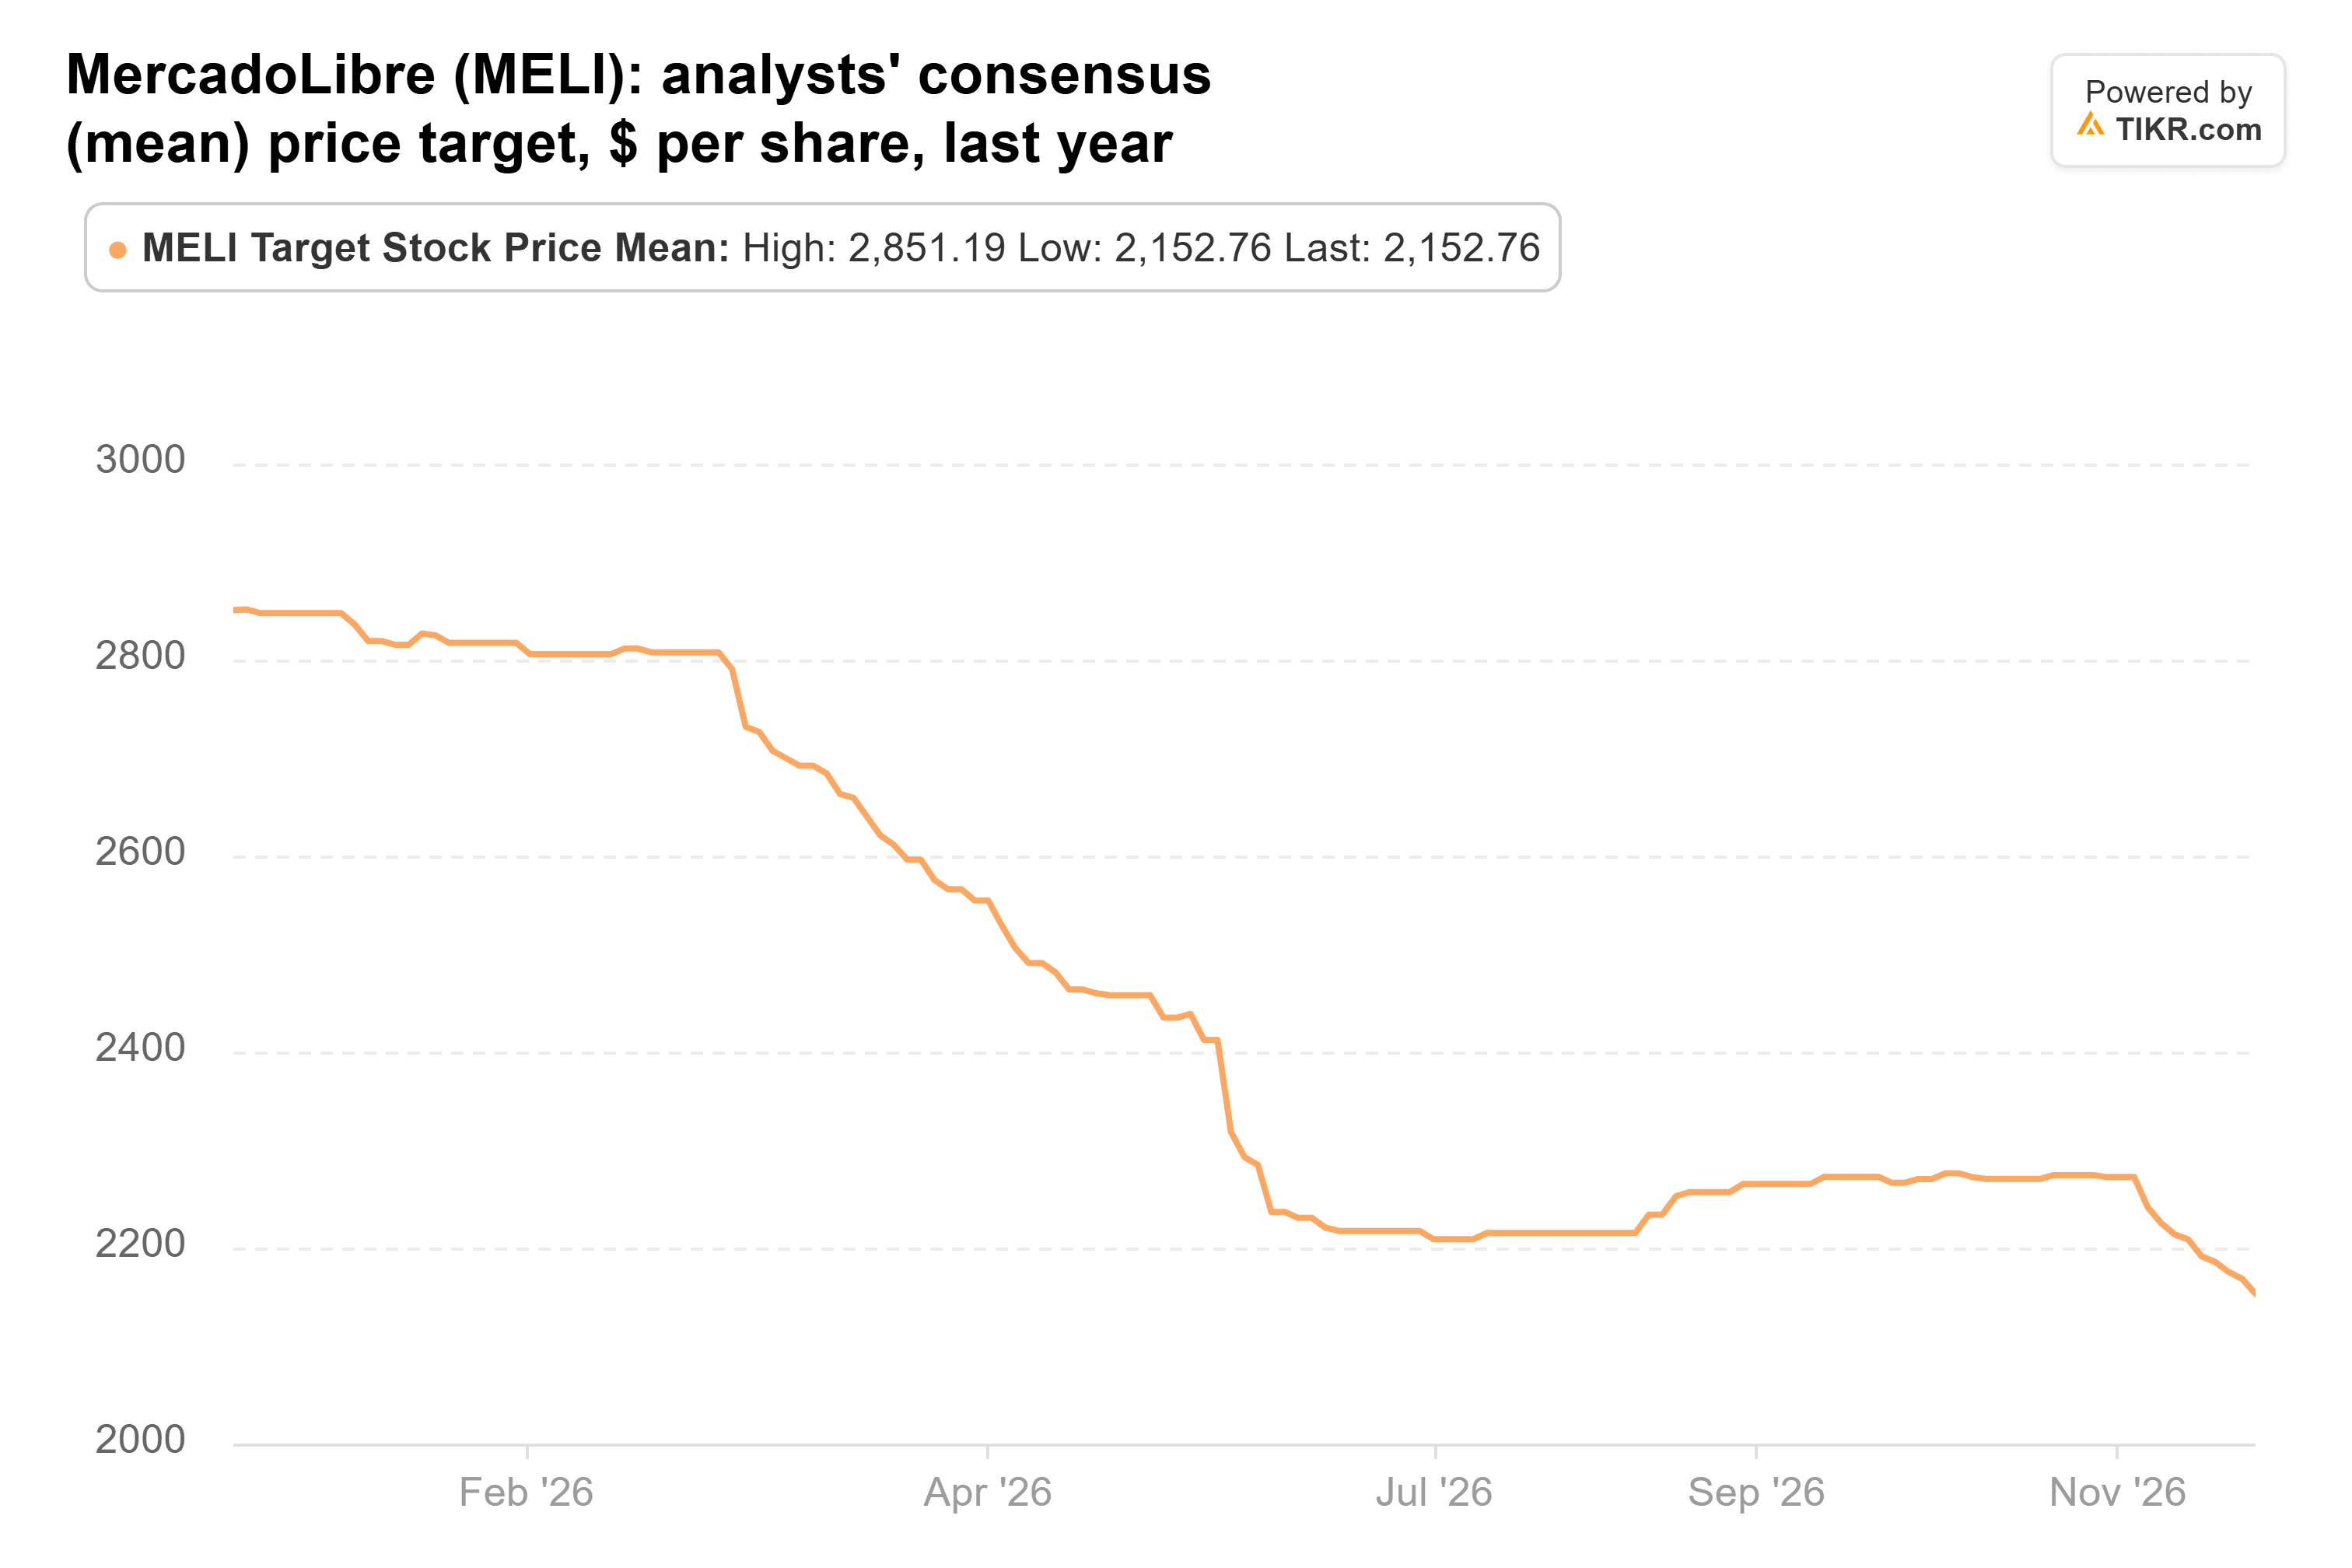
That’s still 59% above the share price, with 25 analysts’ targets running from $1,600 to $2,700.
TIKR tracks 25 analysts on MercadoLibre. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
Mastercard is already up 14%
The two payment networks have gone the other way. The fund held 84,800 Mastercard shares on Sept. 30, 20% more than at June 30. They were worth $47 million, or 2.0% of its 13F stocks, and the stock has gained 14% since.
Mastercard’s services revenue grew 19% in the third quarter, and its total revenue grew 14%. More than a dozen firms raised their targets after the report, J.P. Morgan to $755 from $720 among them. The average target has climbed from $657 a year ago to $721, its high for the year.
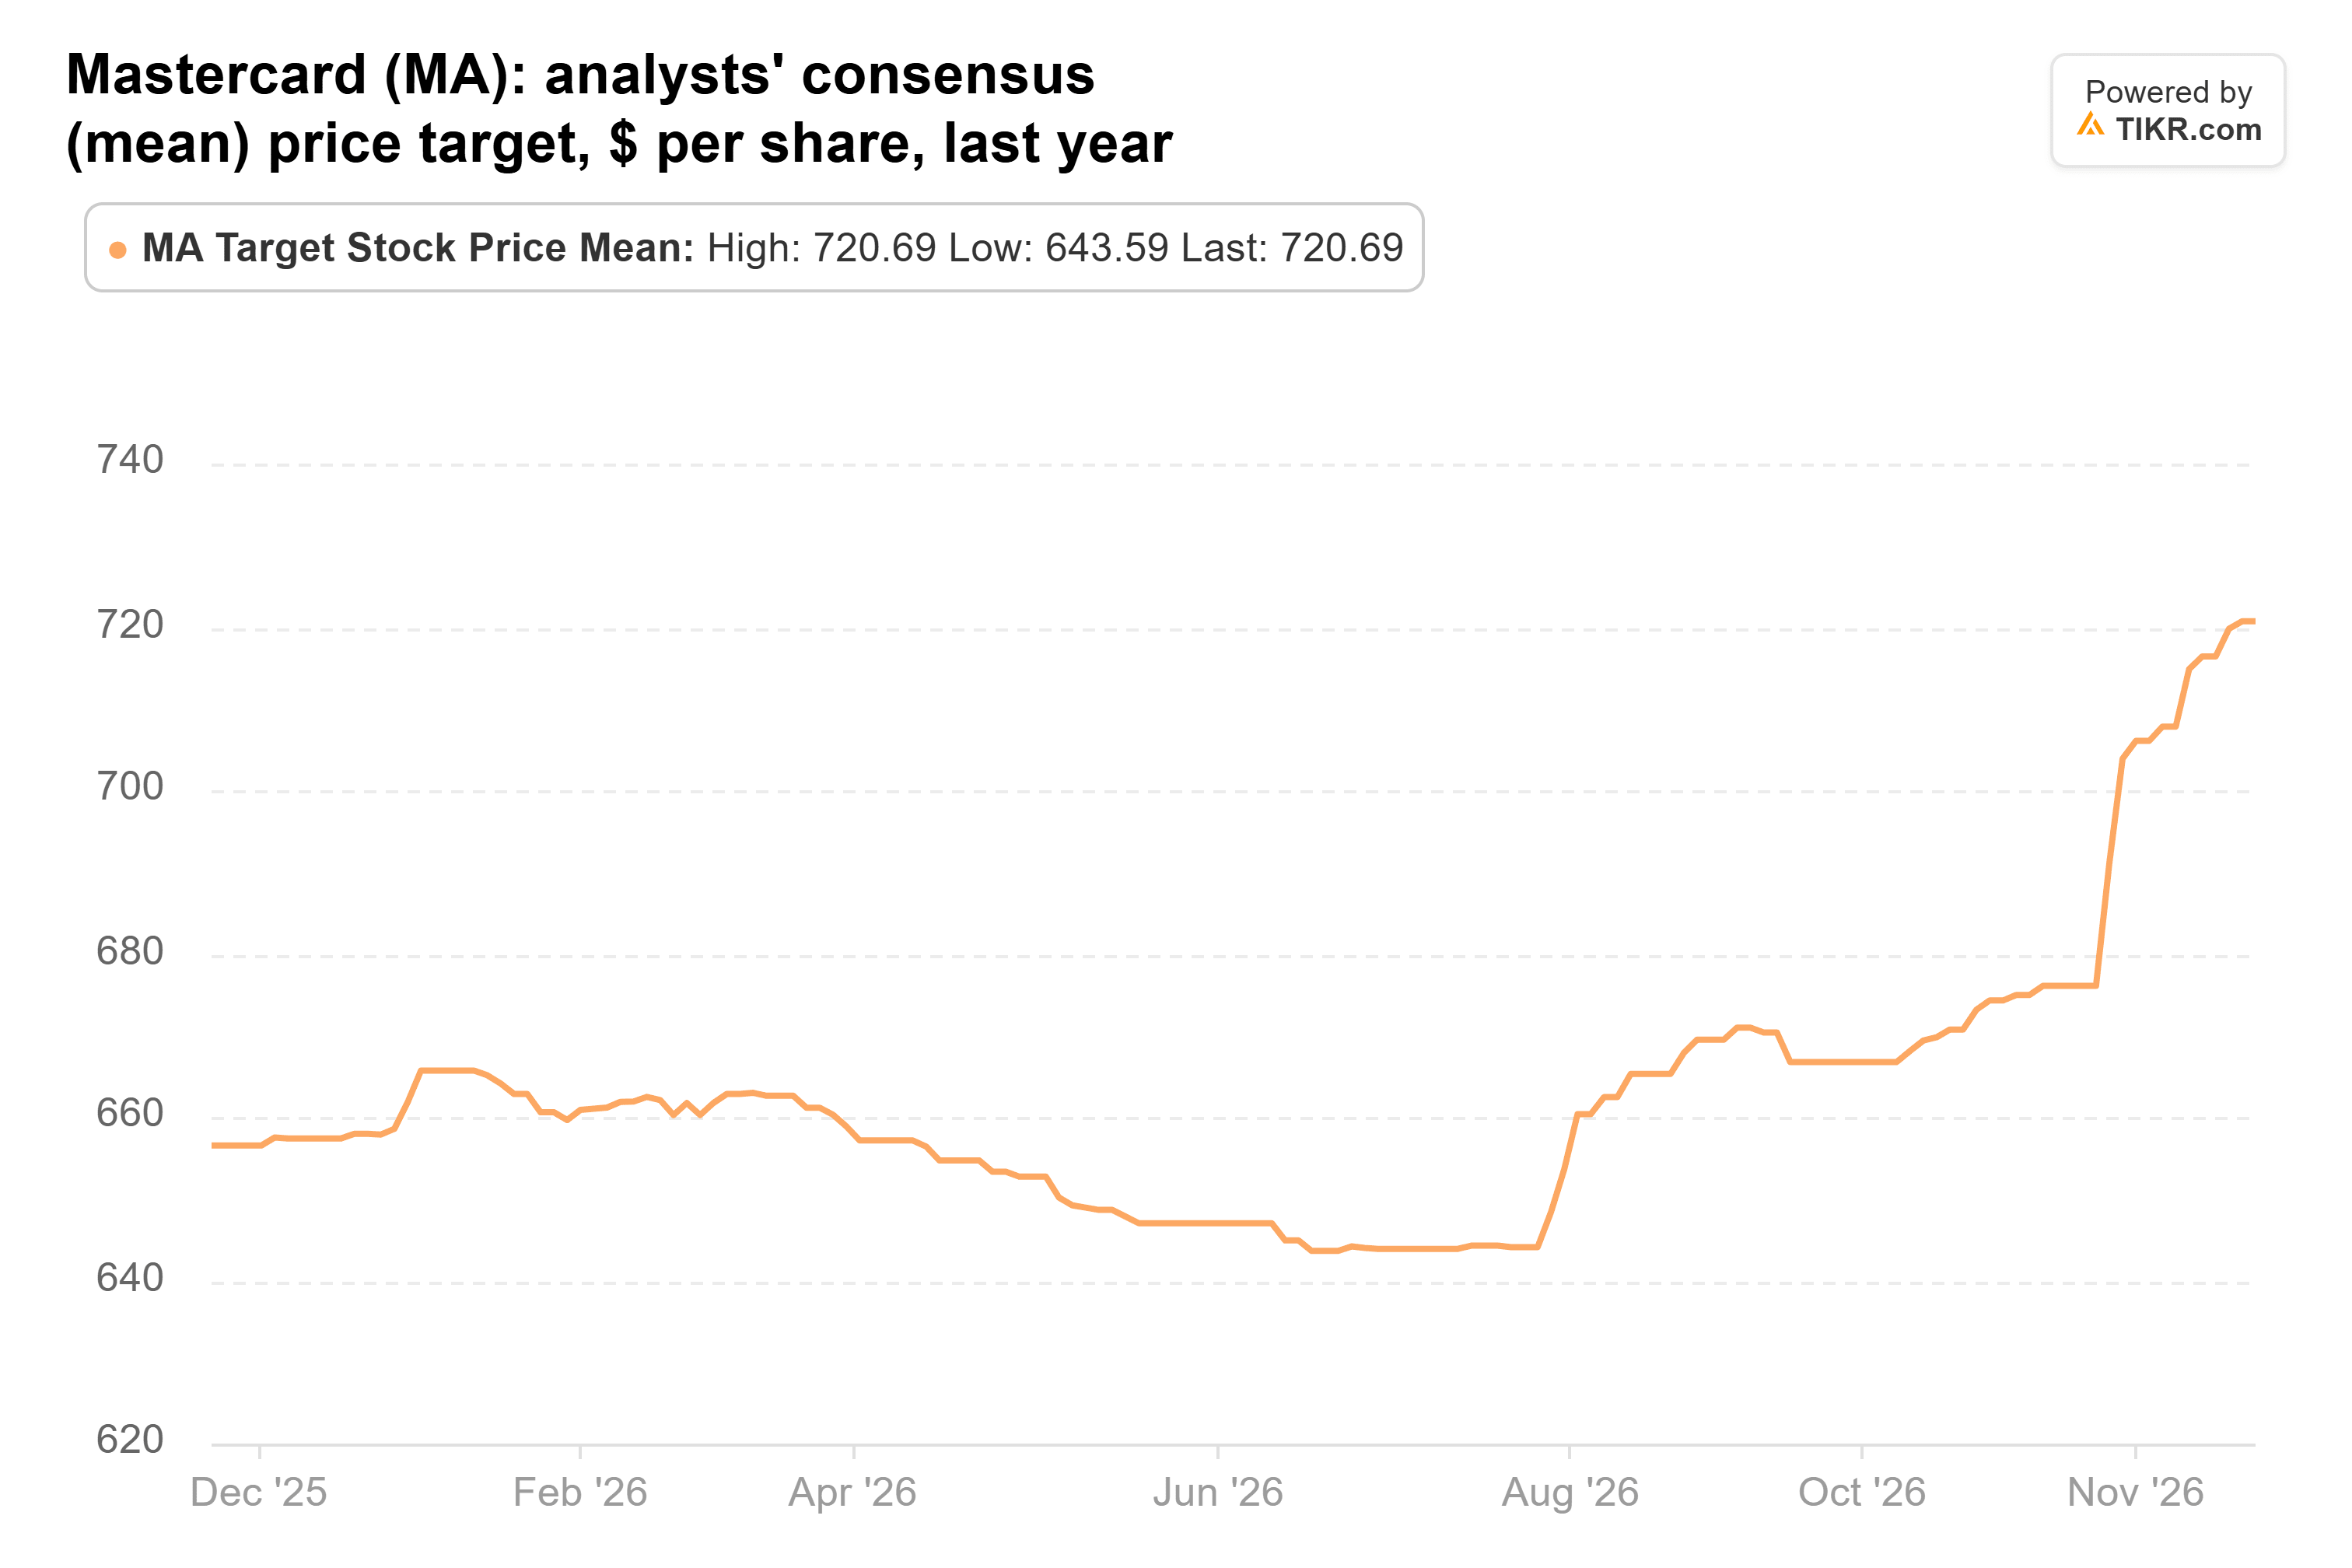
That’s 15% above the share price, from 40 analysts.
Visa is up 12%, but its banks want more
Visa’s quarter looks a lot like Mastercard’s, with one more worry. The fund held 128,700 Visa shares on Sept. 30, 21% more than at June 30. They were worth $46 million, or 2.0% of its 13F stocks, and the stock is up 12% since.
The worry is what Visa pays the banks that issue its cards. Visa guided to low-double-digit revenue growth for fiscal 2027, and its CFO flagged faster growth in client incentives. Freedom Broker cut Visa to Hold from Buy on Nov. 4, citing rising incentives and a record number of contract renewals. Cantor Fitzgerald went the other way, raising its target to $500 from $445, and the average has risen from $394 a year ago to $451, its high for the year.
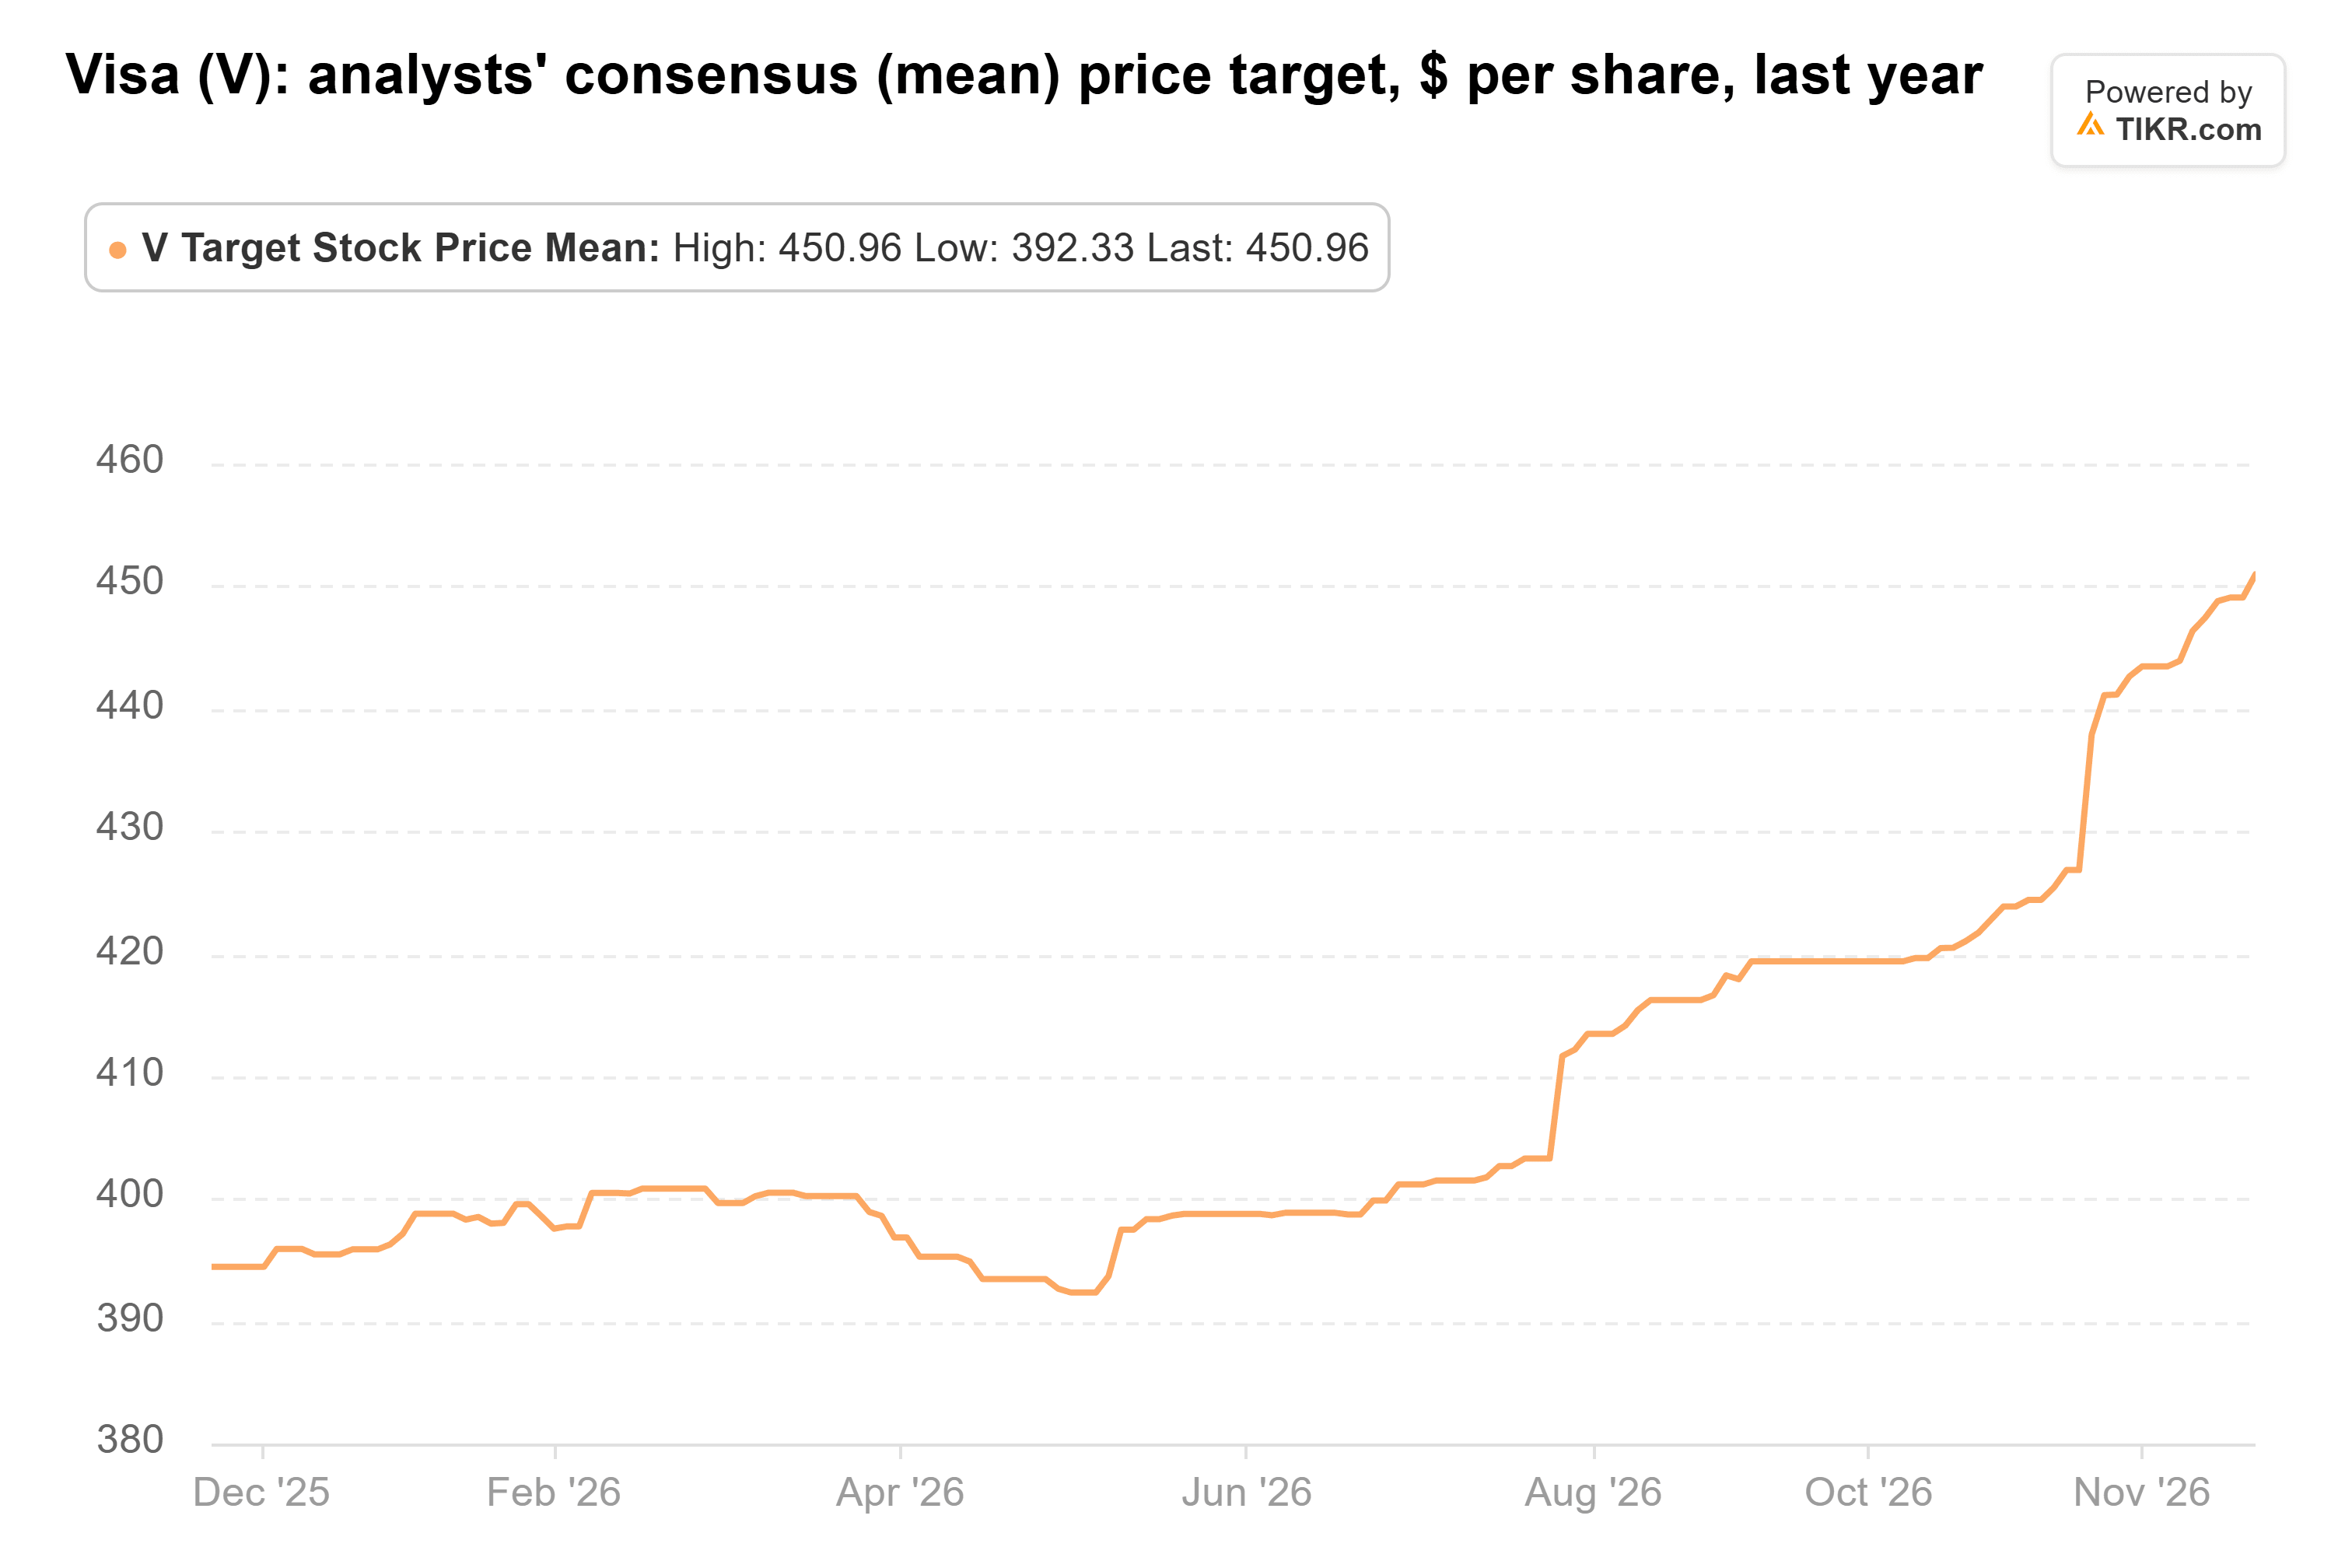
That’s 12% above the share price, from 40 analysts.
Do the numbers back the fund?
MercadoLibre looks cheapest. At about 31x forward earnings, it trades below even its 33x low at the end of March and far below its 48x average since 2023.
But the estimates behind that multiple keep shrinking. In September 2025, analysts expected $66.55 of normalized EPS for 2026, and now they expect $37.37. Their $54.44 for 2027 needs the margin to recover. On the third-quarter call, Goldman Sachs analyst Irma Sgarz asked whether a turn was in sight, and CFO Martin de los Santos gave no target: “The approach is to manage for the long term.”
Mastercard’s numbers are steadier. It trades at about 28x forward earnings, below its 31x quarter-end average since 2014. Analysts expect $23.13 of EPS for 2027, and that figure barely moved after the third-quarter beat.
Visa, at about 27x, sits right at its 28x average. The $15.02 of fiscal 2027 EPS analysts expect is at the top of Visa’s guided range and only 4% above the $14.47 they expected a year ago, so there’s little room for a miss.
Mastercard is the add to follow
The risk with Mastercard is what it costs to win business. Rebates and incentives rose 18% in the third quarter, and Mastercard expects them to take a larger share of its fees in the fourth.
Even so, if I could only follow one of these adds, it’d be Mastercard. Its estimates and targets are rising, and it still trades below its usual multiple. MercadoLibre has far more upside on paper, and a margin recovery would make it the better buy, but I’d want to see its estimates stop falling first.
The fund’s next 13F is due in mid-February and will show whether it kept adding to MercadoLibre as the stock fell. Before that, MercadoLibre’s fourth-quarter report early next year is the test. Its CFO said part of the new fulfillment costs should “come back in Q4.” An operating margin back toward the 10.1% of a year earlier would make 2027’s estimates look reachable again.
So what is MercadoLibre stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!