

Key Takeaways
- Electron Capital Partners, a firm that manages $4.2 billion, sold out of Coherent, Cognex and Keysight Technologies in the third quarter, its 13F shows.
- All three stocks have fallen since Sept. 30, and even the lowest analyst target on each sits above today’s price.
- Coherent’s cash burn is the main risk: operating cash flow was negative $93 million in its September quarter.
- At about 17x forward earnings, with estimates rising, Coherent looks like the best buy of the three.
A firm that manages $4.2 billion has gone cold on three tech hardware stocks. Electron Capital Partners’ 13F for the quarter ended Sept. 30, filed Nov. 16, shows it held no Coherent (COHR), Cognex (CGNX) or Keysight Technologies (KEYS) at quarter-end, after owning all three at the end of June.
They were three of nine sizable positions the fund sold out of, and all three have dropped since Sept. 30: Coherent by 48%, Cognex by 33% and Keysight by 18%. Meanwhile, the fund added to Constellation Energy and nearly tripled its Eversource Energy stake.
Coherent burns cash, and trades at a discount
The fund held 277,072 Coherent shares worth $109 million at June 30, 4.4% of its 13F stocks at the time. The stock now sits 54% below its 52-week high.
The worry is cash. Coherent is spending heavily to make more of its own lasers for AI data centers, and it isn’t turning that into cash yet: operating cash flow was negative $93 million in the September quarter, and inventory climbed to $3.3 billion.
But the orders keep coming. Coherent signed a roughly $20 billion, five-year PhotonLink deal, and analysts now expect $10.41 of EPS for the year ending June 2027, up from $9.42 at Sept. 30. Their average target has more than doubled over the past year, to $372:

Even the lowest of the 26 analysts’ targets, $228, is above today’s $203 price. And Coherent’s CEO and chairman bought $1.2 million of stock between them this month.
TIKR tracks 26 analysts on Coherent. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coherent, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coherent’s Analyst Ratings
Cognex is down despite a record quarter
The fund’s 967,843 Cognex shares were worth $70 million at June 30, 2.8% of its 13F stocks. Since then, Cognex has reported a record quarter: revenue grew 13% to $313 million in the three months ended Oct. 4, and adjusted EPS rose 61% to $0.53. Yet the stock sits 34% below its 52-week high.
Analysts haven’t backed off much. Their average target is $70, 45% above today’s price and up from $49 a year ago, though it’s come down from $80 in August:
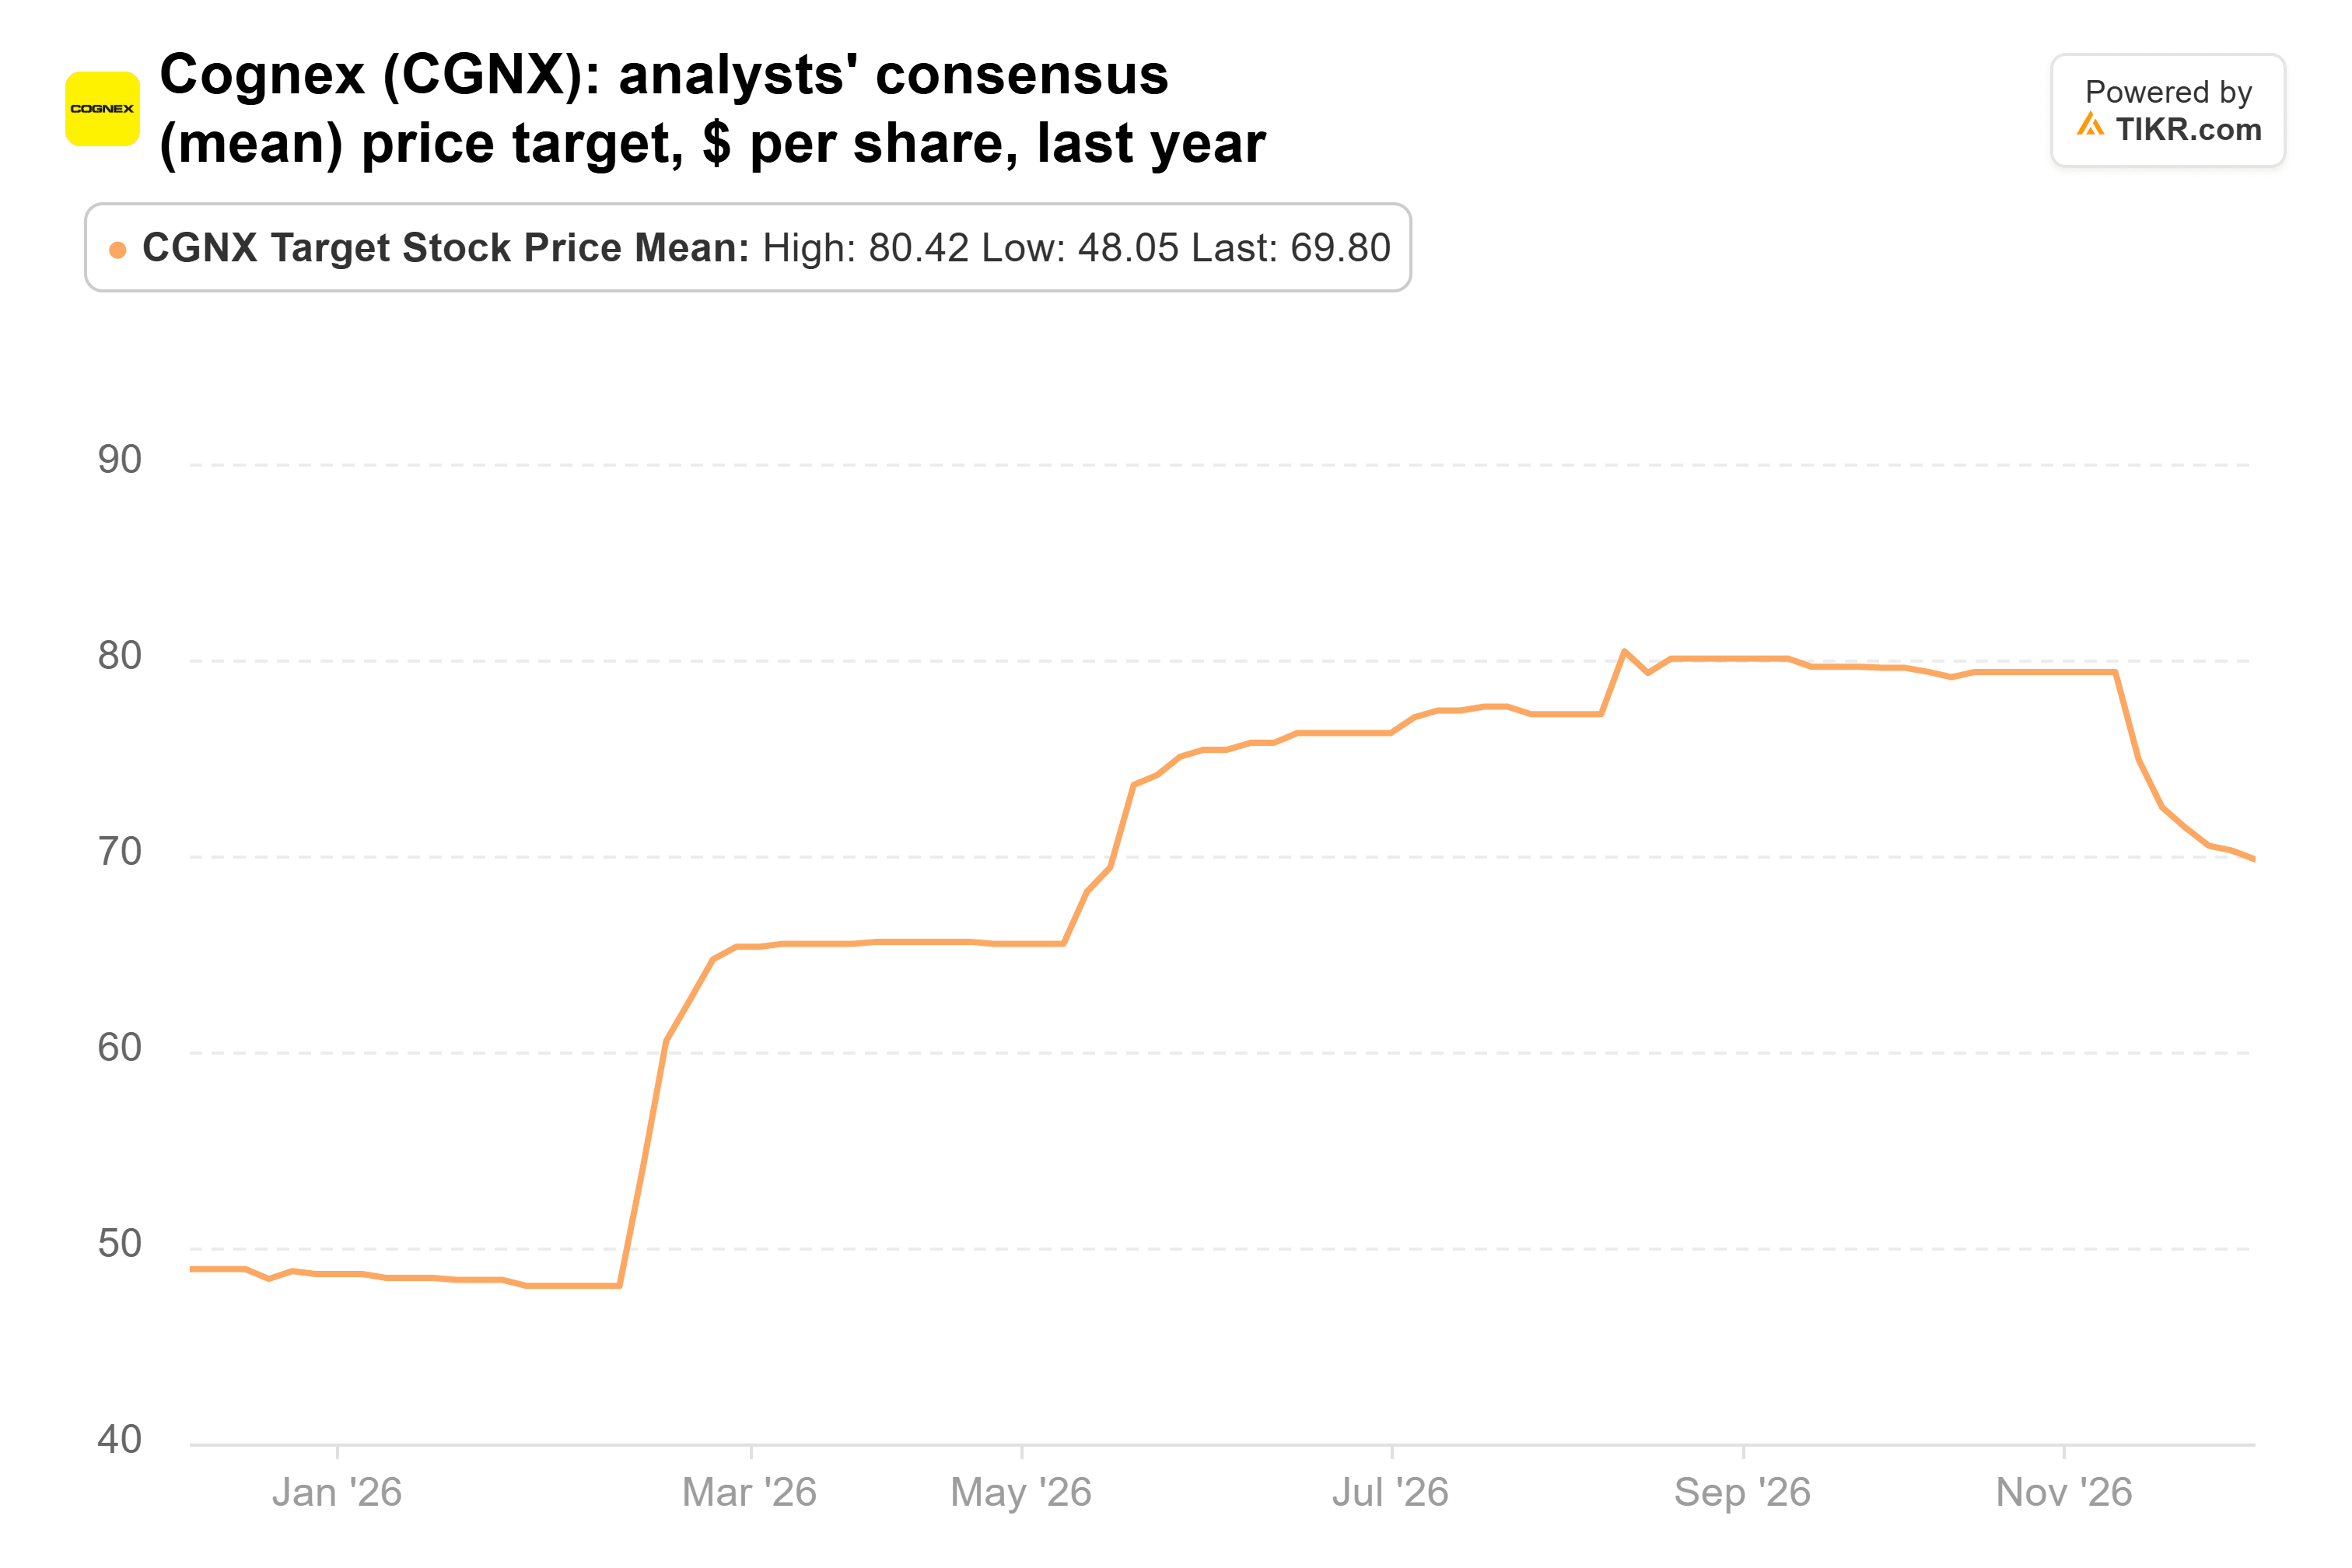
Its lowest target, $55, is still above the price. But at about 26x forward earnings, Cognex is far from cheap, even after the drop.
Keysight’s growth keeps speeding up
Keysight was a position of the same size: 199,931 shares worth $70 million, also 2.8% of the fund’s 13F stocks at June 30. Its revenue grew 36% to $1.85 billion in the quarter ended July 31, led by 56% growth in commercial communications, and management guided to about 37% growth for the quarter ended Oct. 31. Analysts have more than doubled their average target over the year, to $420:
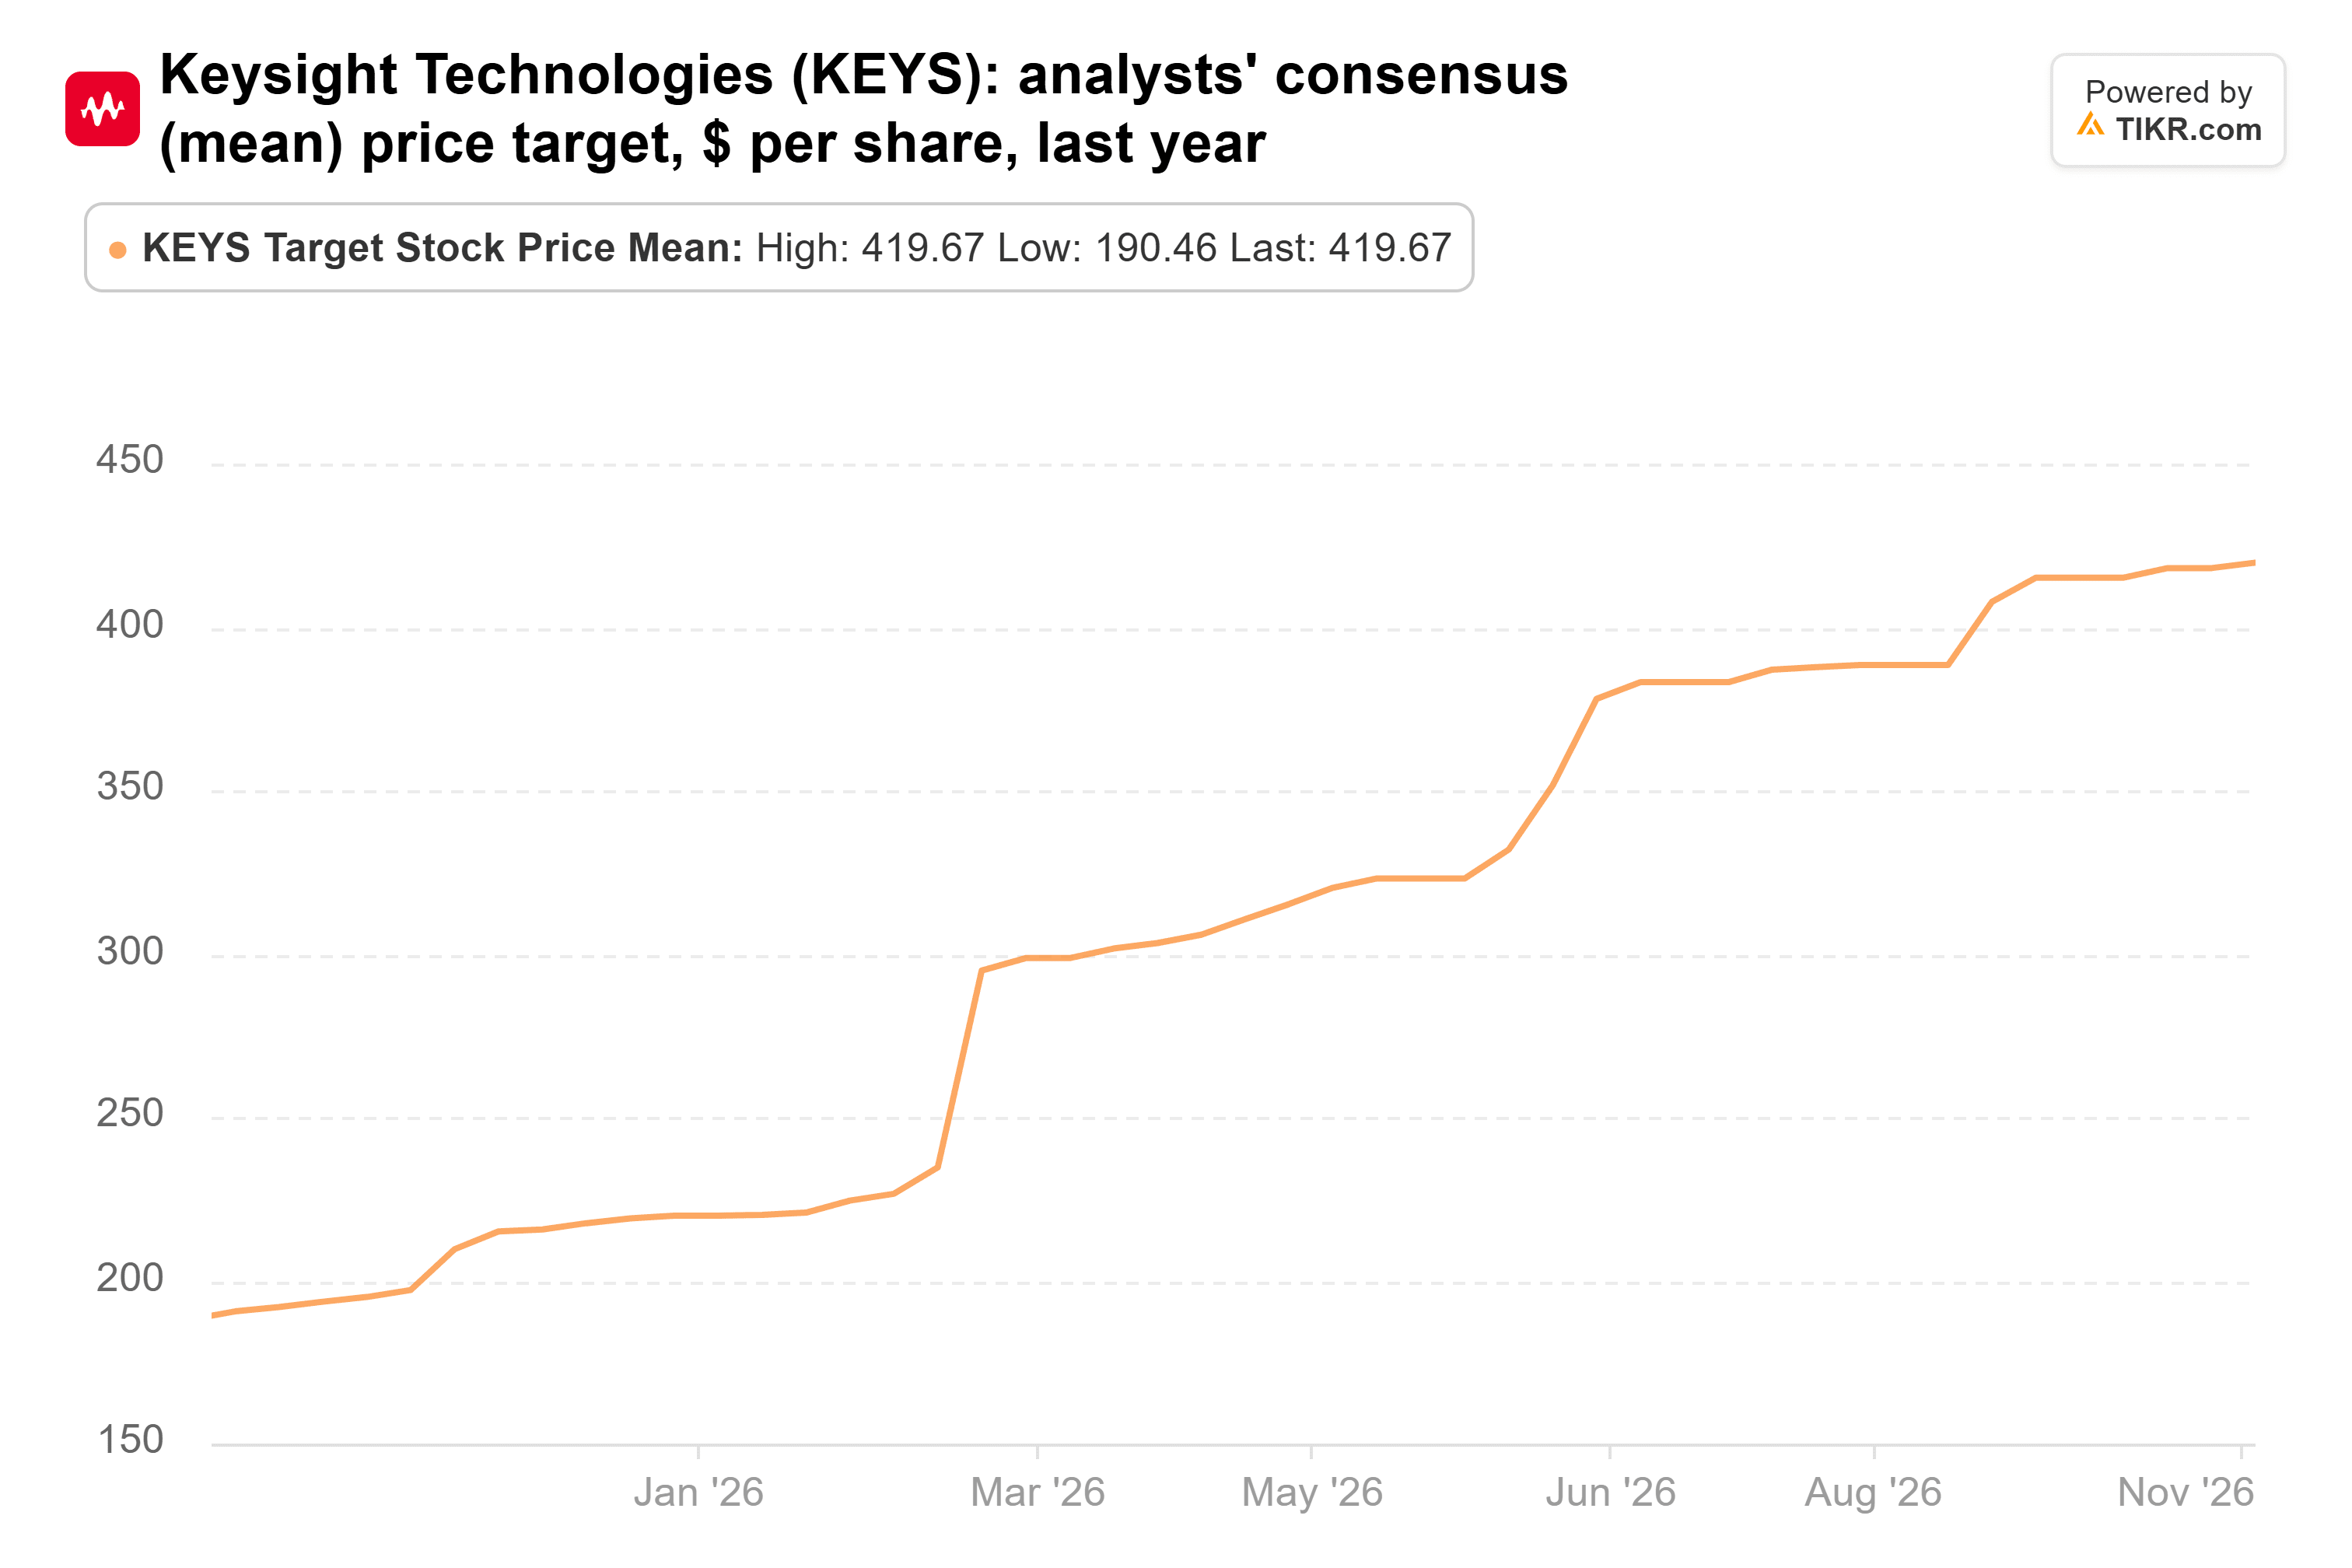
That’s 47% above today’s price, with the stock at about 21x forward earnings, and the lowest target, $350, clears the price too. Keysight reports that October quarter later this week.
Coherent is the one I’d buy
None of the three was in the fund’s 13F at Sept. 30, before the drops. For anyone buying today, though, the question is the price, and all three are cheaper than they were at quarter-end.
If I could only buy one right now, it’d be Coherent. At about 17x forward earnings, it trades below the roughly 21x it has averaged at quarter-ends over the past 12 years, while analysts keep raising its earnings estimates.
Keysight is the cleaner story, with growth speeding up and positive free cash flow, and a strong report this week would make its case too. Cognex’s record quarter is real, but at about 26x forward earnings, it leaves less room for error.
The risk with Coherent is cash: if operating cash flow stays negative and inventory keeps climbing, the discount is deserved. Its Feb. 3 report is the next check on that, and the fund’s next 13F, due by mid-February, will show whether it has come back to any of these.
So what is Coherent stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coherent could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





