Key Takeaways
- A $3.1 billion fund added to Microsoft, Amazon and MSCI in the third quarter, its three biggest new or added positions, per its 13F filed Nov. 16.
- Microsoft is now the fund’s second-largest holding at 14.1% of its US stocks, with Amazon third at 10.7%.
- Analysts’ average targets sit 31% above the last close for Microsoft and 32% for Amazon, but only 13% for MSCI after its gain since Sept. 30.
- Of the three, Microsoft has the strongest case: it’s the cheapest on forward earnings, and its free cash flow stays positive.
Consulta Ltd holds $3.09 billion of US stocks in just 14 positions, per its 13F for the quarter ended Sept. 30, filed Nov. 16. In a portfolio that concentrated, every add is a real bet. Its three biggest went to Microsoft (MSFT), Amazon (AMZN) and MSCI (MSCI).
Analysts see upside in all three. The numbers back one more than the others.
Microsoft is now a 14% position
The fund raised its Microsoft stake 21% in the third quarter, to 850,000 shares worth $436 million at Sept. 30. That’s 14% of the fund and its second-largest holding. The stock is down 6% from its Sept. 30 close, even though the quarter Microsoft reported on Oct. 28 was a strong one. Azure grew 48%, ahead of the 44% to 45% Microsoft had guided.
Amazon’s cloud is speeding up too
Amazon got a similar boost. The fund added 20% to its stake and ended the quarter with 1.32 million shares worth $330 million. That’s 10.7% of the fund and its No. 3 holding. The stock has barely moved since, down 0.9% from its Sept. 30 close. AWS sales grew 39% to $46.0 billion in the third quarter, its fastest growth in nearly five years, and Amazon’s 13.9% operating margin was its highest ever.
TIKR tracks 58 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
MSCI’s stake grew the most
MSCI is a much smaller position, but the fund grew it the fastest. Its stake rose 62% to 325,000 shares worth $175 million, 5.7% of the fund and its eighth-largest holding. The stock is up 13% from its Sept. 30 close. In the third quarter, operating revenue grew 12.4% to $892.0 million and adjusted EPS rose 14.3% to $5.11. Its index business led the way: run rate rose 16.5% to $2.1 billion on record assets in ETFs linked to MSCI indexes. And clients are staying, with retention at 95.0%.
Do the numbers back the bets?
Start with Microsoft. The 58 analysts who rate it on TIKR have raised their average target from a low of $556 in late July to $636, which is 31% above the last close:

The stock trades at about 23x forward earnings, well below its five-year average of about 29x. The worry is cash. Analysts have cut their fiscal 2027 free cash flow estimate three times, to $32.0 billion. Microsoft generated $67.0 billion in fiscal 2026, and it keeps pouring money into data centers.
Amazon’s targets have moved up even more. The 62 analysts who rate it on TIKR now average $327, up from $294 a year ago and 32% above the last close:

At about 25x forward earnings, Amazon trades at roughly half its five-year average of 49x. But Amazon is spending even harder than Microsoft: consensus now has its 2026 free cash flow as a $41.2 billion outflow. And Anthropic began trading on Nov. 19, so Amazon’s 14.7% stake now gets a market price every quarter, which will swing its GAAP earnings. With nearly 40% of the IPO’s shares free to trade from day one, that price could move a lot.
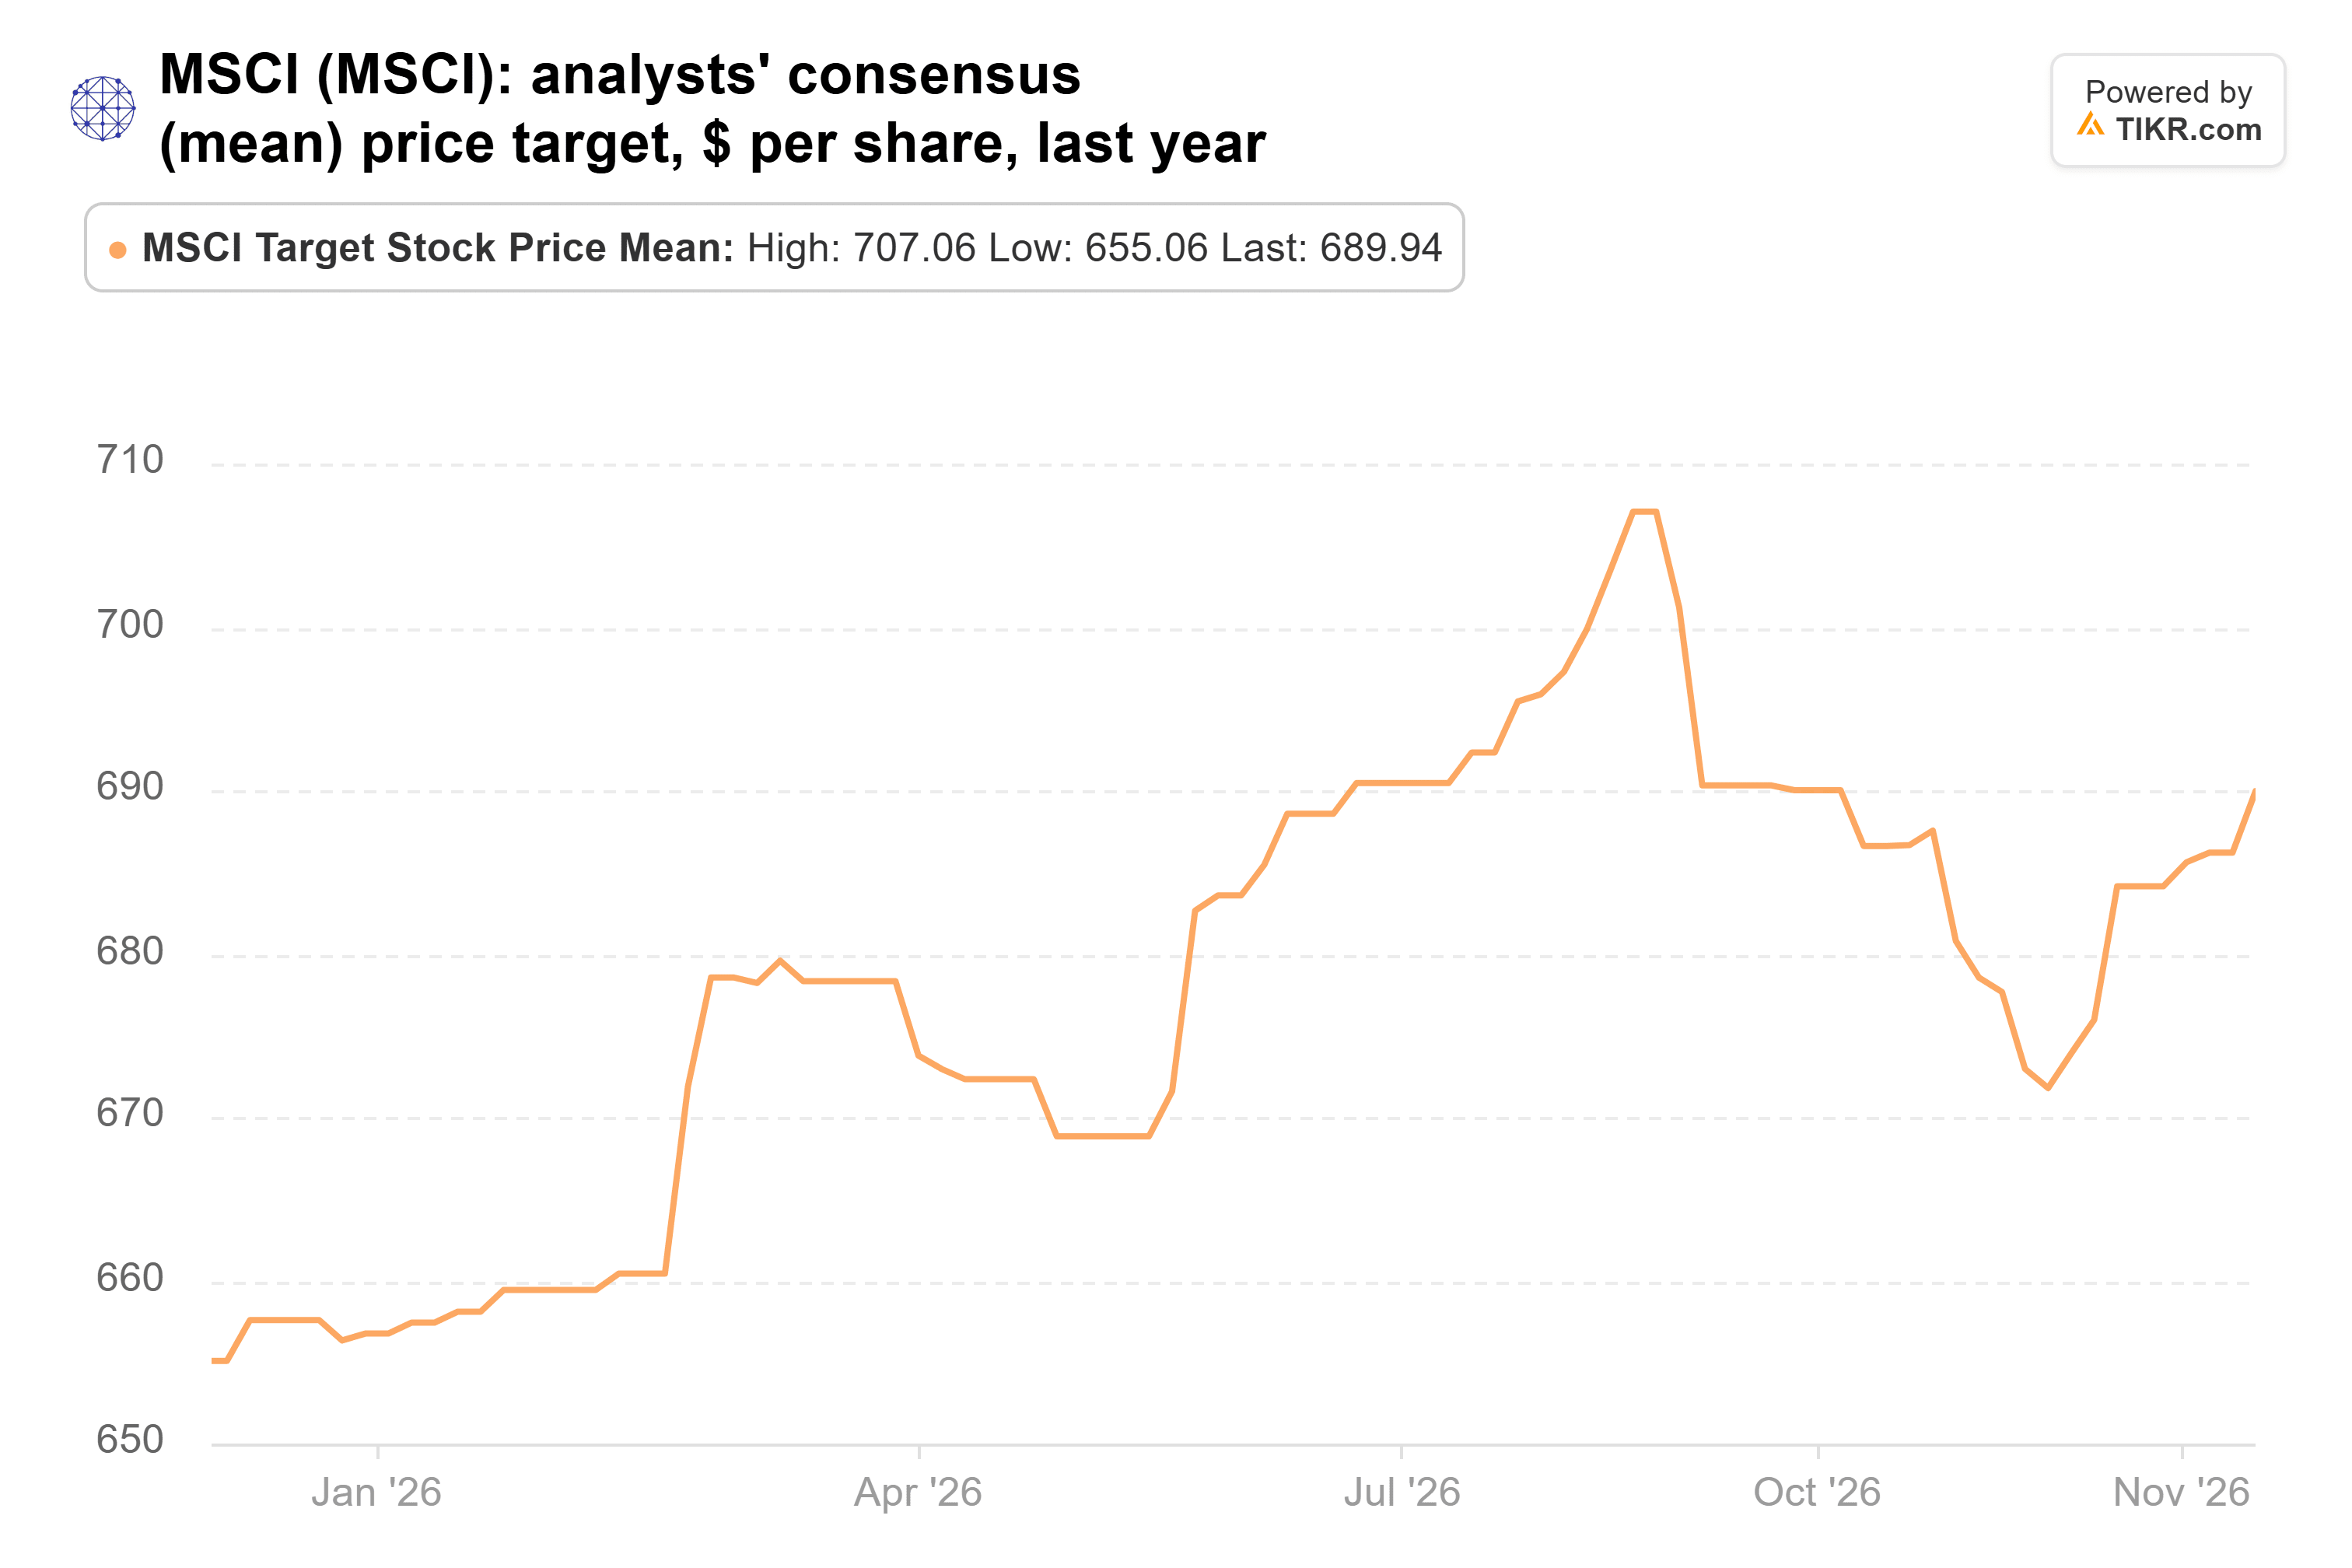
MSCI has the least room left. Its average target rose from $655 a year ago to $690, only 13% above the last close:
At about 28x forward earnings, it’s also the priciest of the three.
Microsoft is the one I’d buy
If I could only buy one of the three right now, it’d be Microsoft. It’s the cheapest of the three on forward earnings, and its free cash flow stays positive while Amazon’s goes negative.
Amazon is a close second. I just want to see how much Anthropic’s stock swings its earnings first. MSCI’s quarter was excellent too, but after its gain since Sept. 30, I’d want a better price.
Microsoft’s next report, in late January, is the test. After $18.6 billion of free cash flow in the September quarter, it needs only about $13.4 billion over the next three quarters combined to reach the $32.0 billion consensus. Another quarter near September’s pace would make that estimate look too low. The fund’s next 13F, due in mid-February, will show whether it kept adding.
So what is Microsoft stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Microsoft could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!