Key Takeaways
- Discovery Capital Management’s latest 13F shows its three biggest new or added positions in the third quarter were Amazon, Take-Two Interactive and First Solar.
- Analysts’ average targets sit 32% to 82% above the last close for all three.
- Amazon’s faster cloud growth and rising targets back the fund’s biggest add, while First Solar’s guidance cut makes its gap harder to trust.
- Of the three, Amazon has the strongest case on the numbers.
A $2.2 billion fund just put fresh money into three very different stocks: Amazon (AMZN), Take-Two Interactive (TTWO) and First Solar (FSLR). Discovery Capital Management’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows them as its three biggest new or added positions. (That $2.2 billion is what its 13F holds in US stocks: $2.18 billion across 102 positions.)
Amazon is now a top-three holding
Discovery held 456,739 Amazon shares at Sept. 30, 159% more than the quarter before. They were worth $114 million, or 5.2% of its 13F, its No. 3 position, and the stock is down 0.9% since the quarter’s end.
Amazon gave the bet plenty of support in its third-quarter report on Oct. 29. AWS sales grew 39% to $46.0 billion, up from 37% growth in the second quarter, and GAAP operating income of $28.1 billion made for a 13.9% operating margin, Amazon’s highest ever.
The catch is the cash. CEO Andy Jassy said on CNBC on Nov. 17 that Amazon will spend about $220 billion this year and “meaningfully more” in 2027. Consensus has free cash flow at a $41.2 billion outflow in 2026 before a $35.7 billion inflow in 2028.
Analysts have kept raising their targets anyway. The consensus target rose to $327 from $294 a year ago, 32% above the last close:
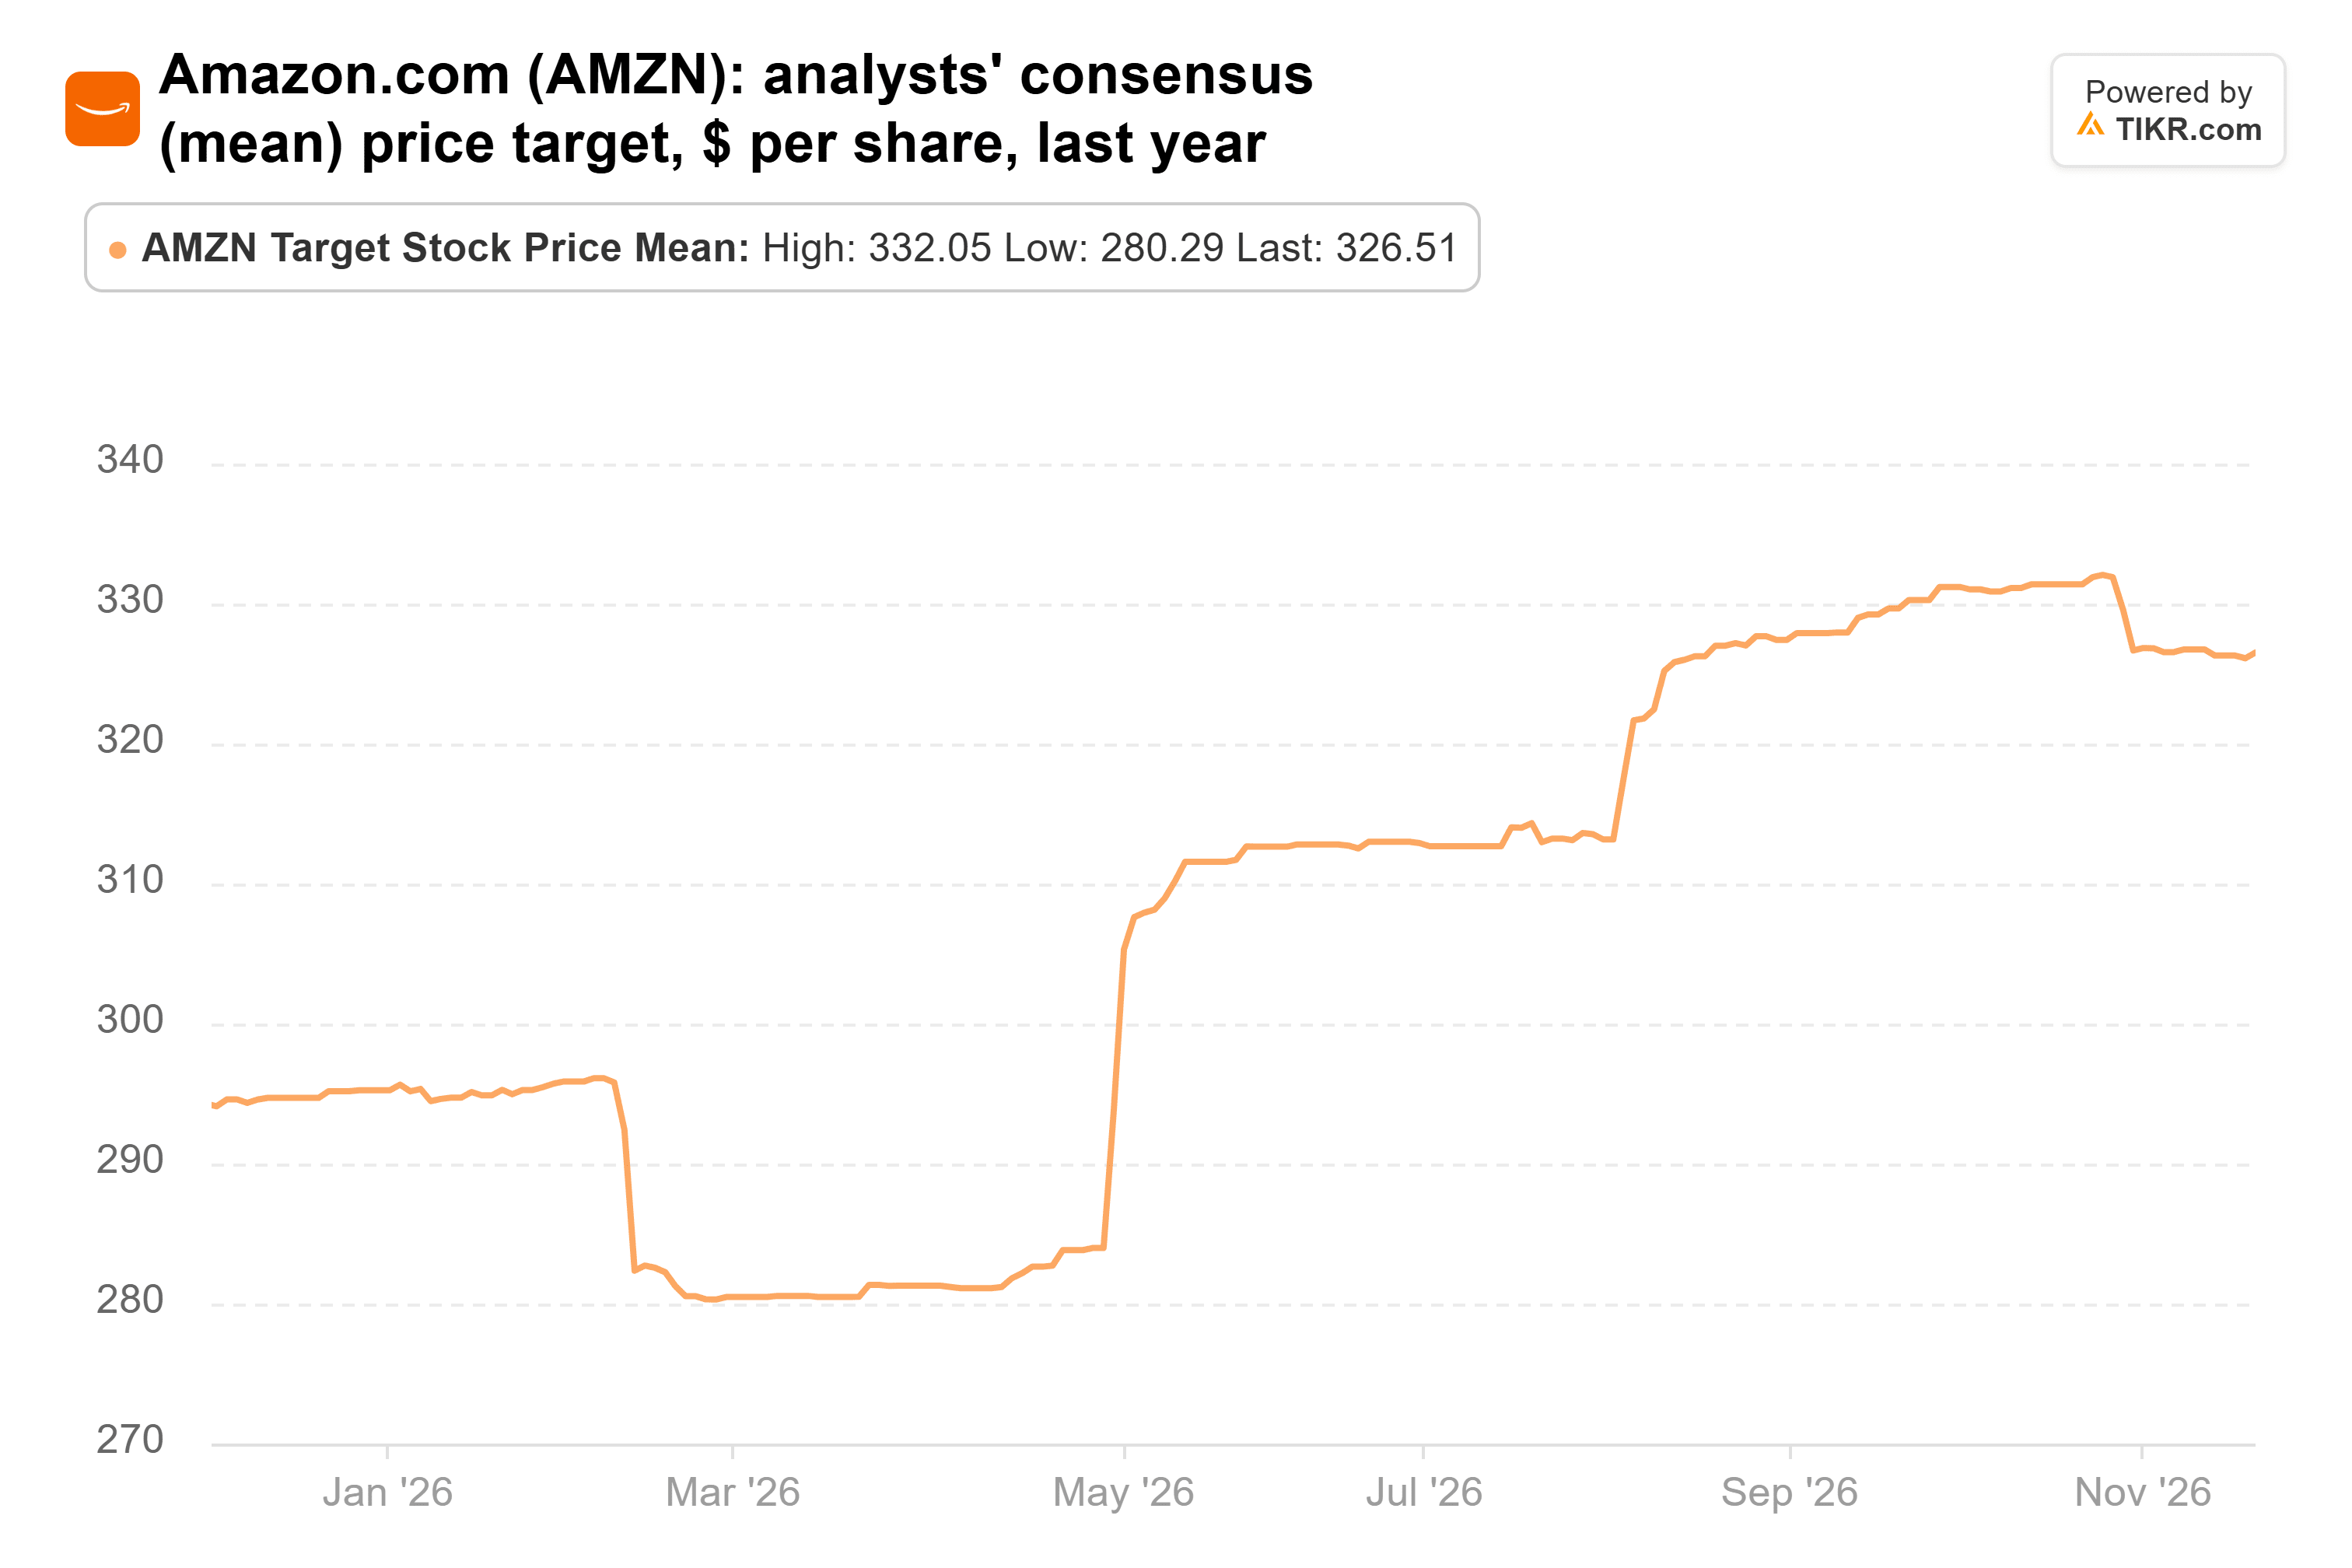
And at about 25x forward earnings, Amazon trades below its one-year average of about 30x on TIKR, even though analysts raised their 2028 earnings estimates 24% over the year to Oct. 23.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Take-Two finally has its blockbuster
Take-Two is a smaller bet. Discovery added 91% to its stake, ending the quarter with 219,100 shares worth $45 million, 2.1% of its 13F and its No. 11 holding. The stock is up 1% since Sept. 30.
The case is Grand Theft Auto VI, which launched Nov. 19. Take-Two said the game brought in an estimated $3.79 billion of retail sales on its first day, the biggest entertainment launch ever by its count. (That’s what shoppers spent, and Take-Two keeps only part of it.)
The launch came after a soft quarter: net bookings fell 18% to $1.60 billion in the September quarter. Management held its guidance of $8.0 billion to $8.2 billion of net bookings for the fiscal year ending in March, with $3.35 billion to $3.5 billion in the December quarter alone. Wells Fargo raised its own forecast for the year 19%, to $9.76 billion.
Analysts’ consensus target barely moved over the year, edging up to $284 from $276, while the stock slid to $210 from $235:
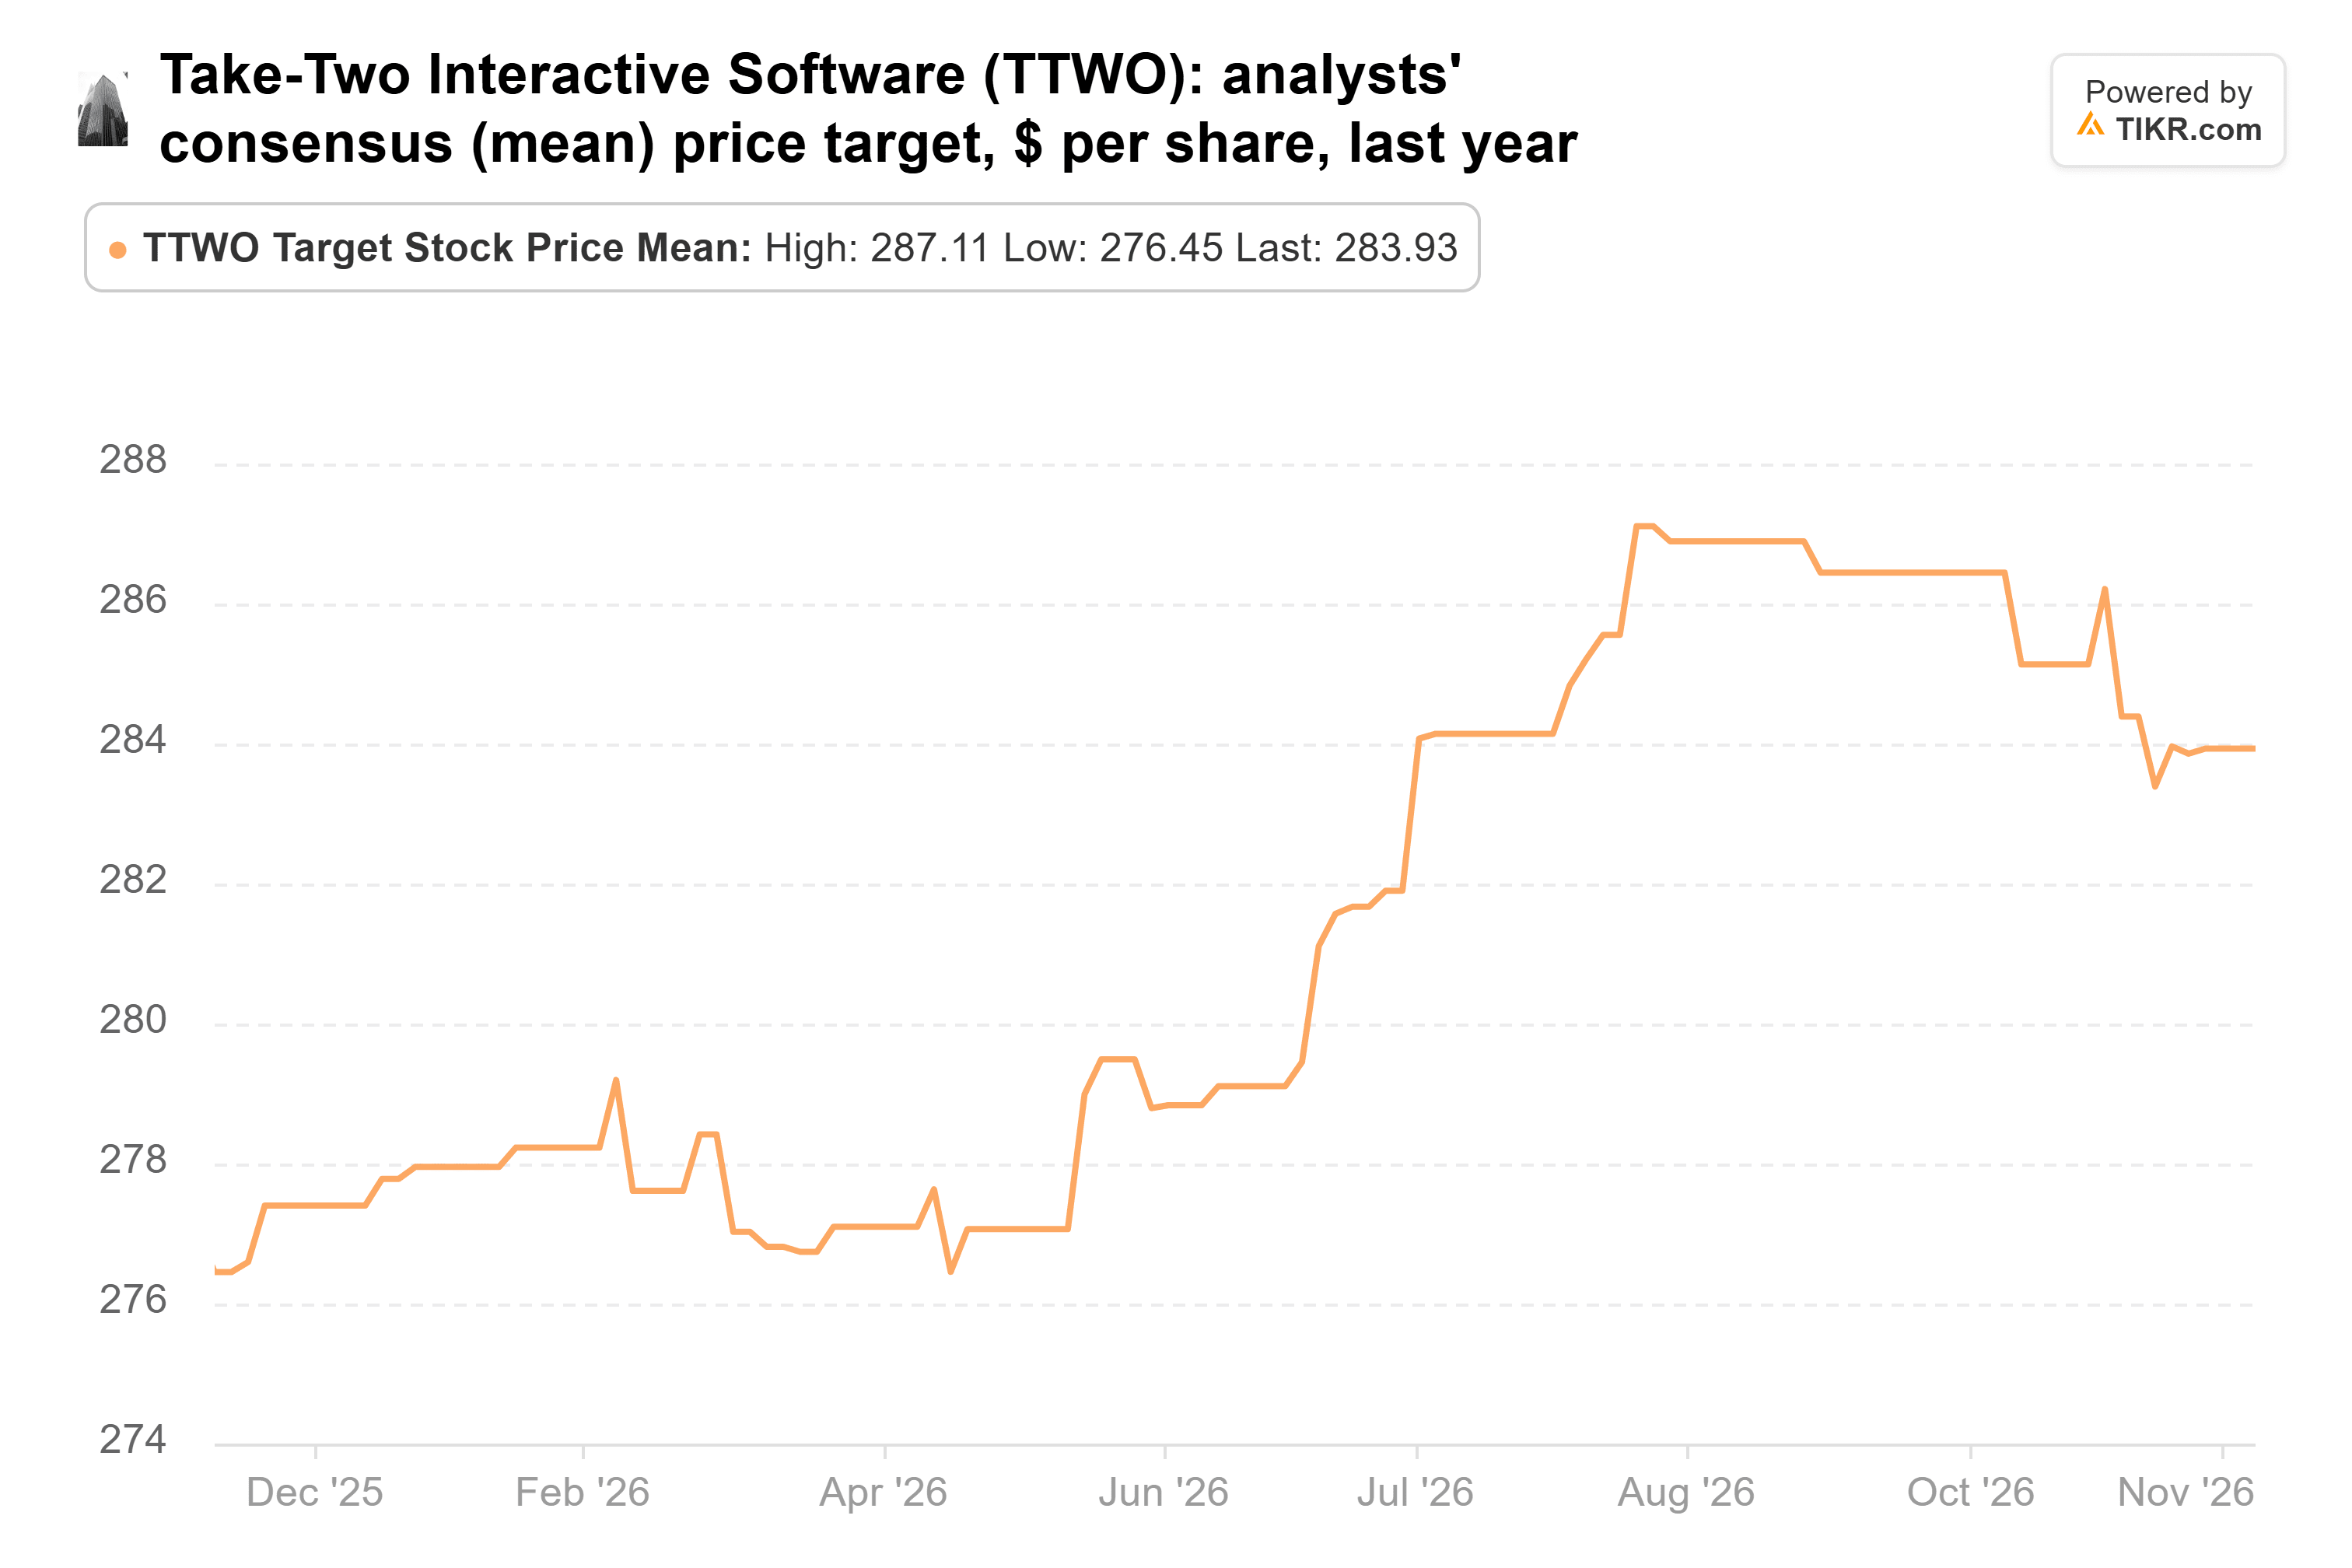
Those targets came before launch day, so analysts may well raise them after a start this strong. At about 22x forward earnings, the stock needs GTA VI to keep selling well past its first week.
First Solar is cheap for a reason
Discovery lifted its First Solar stake 473% to 238,452 shares, worth $42 million and 1.9% of its 13F at Sept. 30. The stock has fallen 21% since then and sits 57% below its 52-week high.
On Oct. 29, First Solar reported that sales fell 23% to $1.23 billion as it sold fewer modules to third parties. It also cut its 2026 sales guidance to $4.6 billion-$4.9 billion from $4.9 billion-$5.2 billion. Its operations used $43 million of cash in the quarter, after bringing in $1.27 billion a year earlier.
Analysts have trimmed their targets over the year, to $251 from $272, but the stock has fallen much faster:
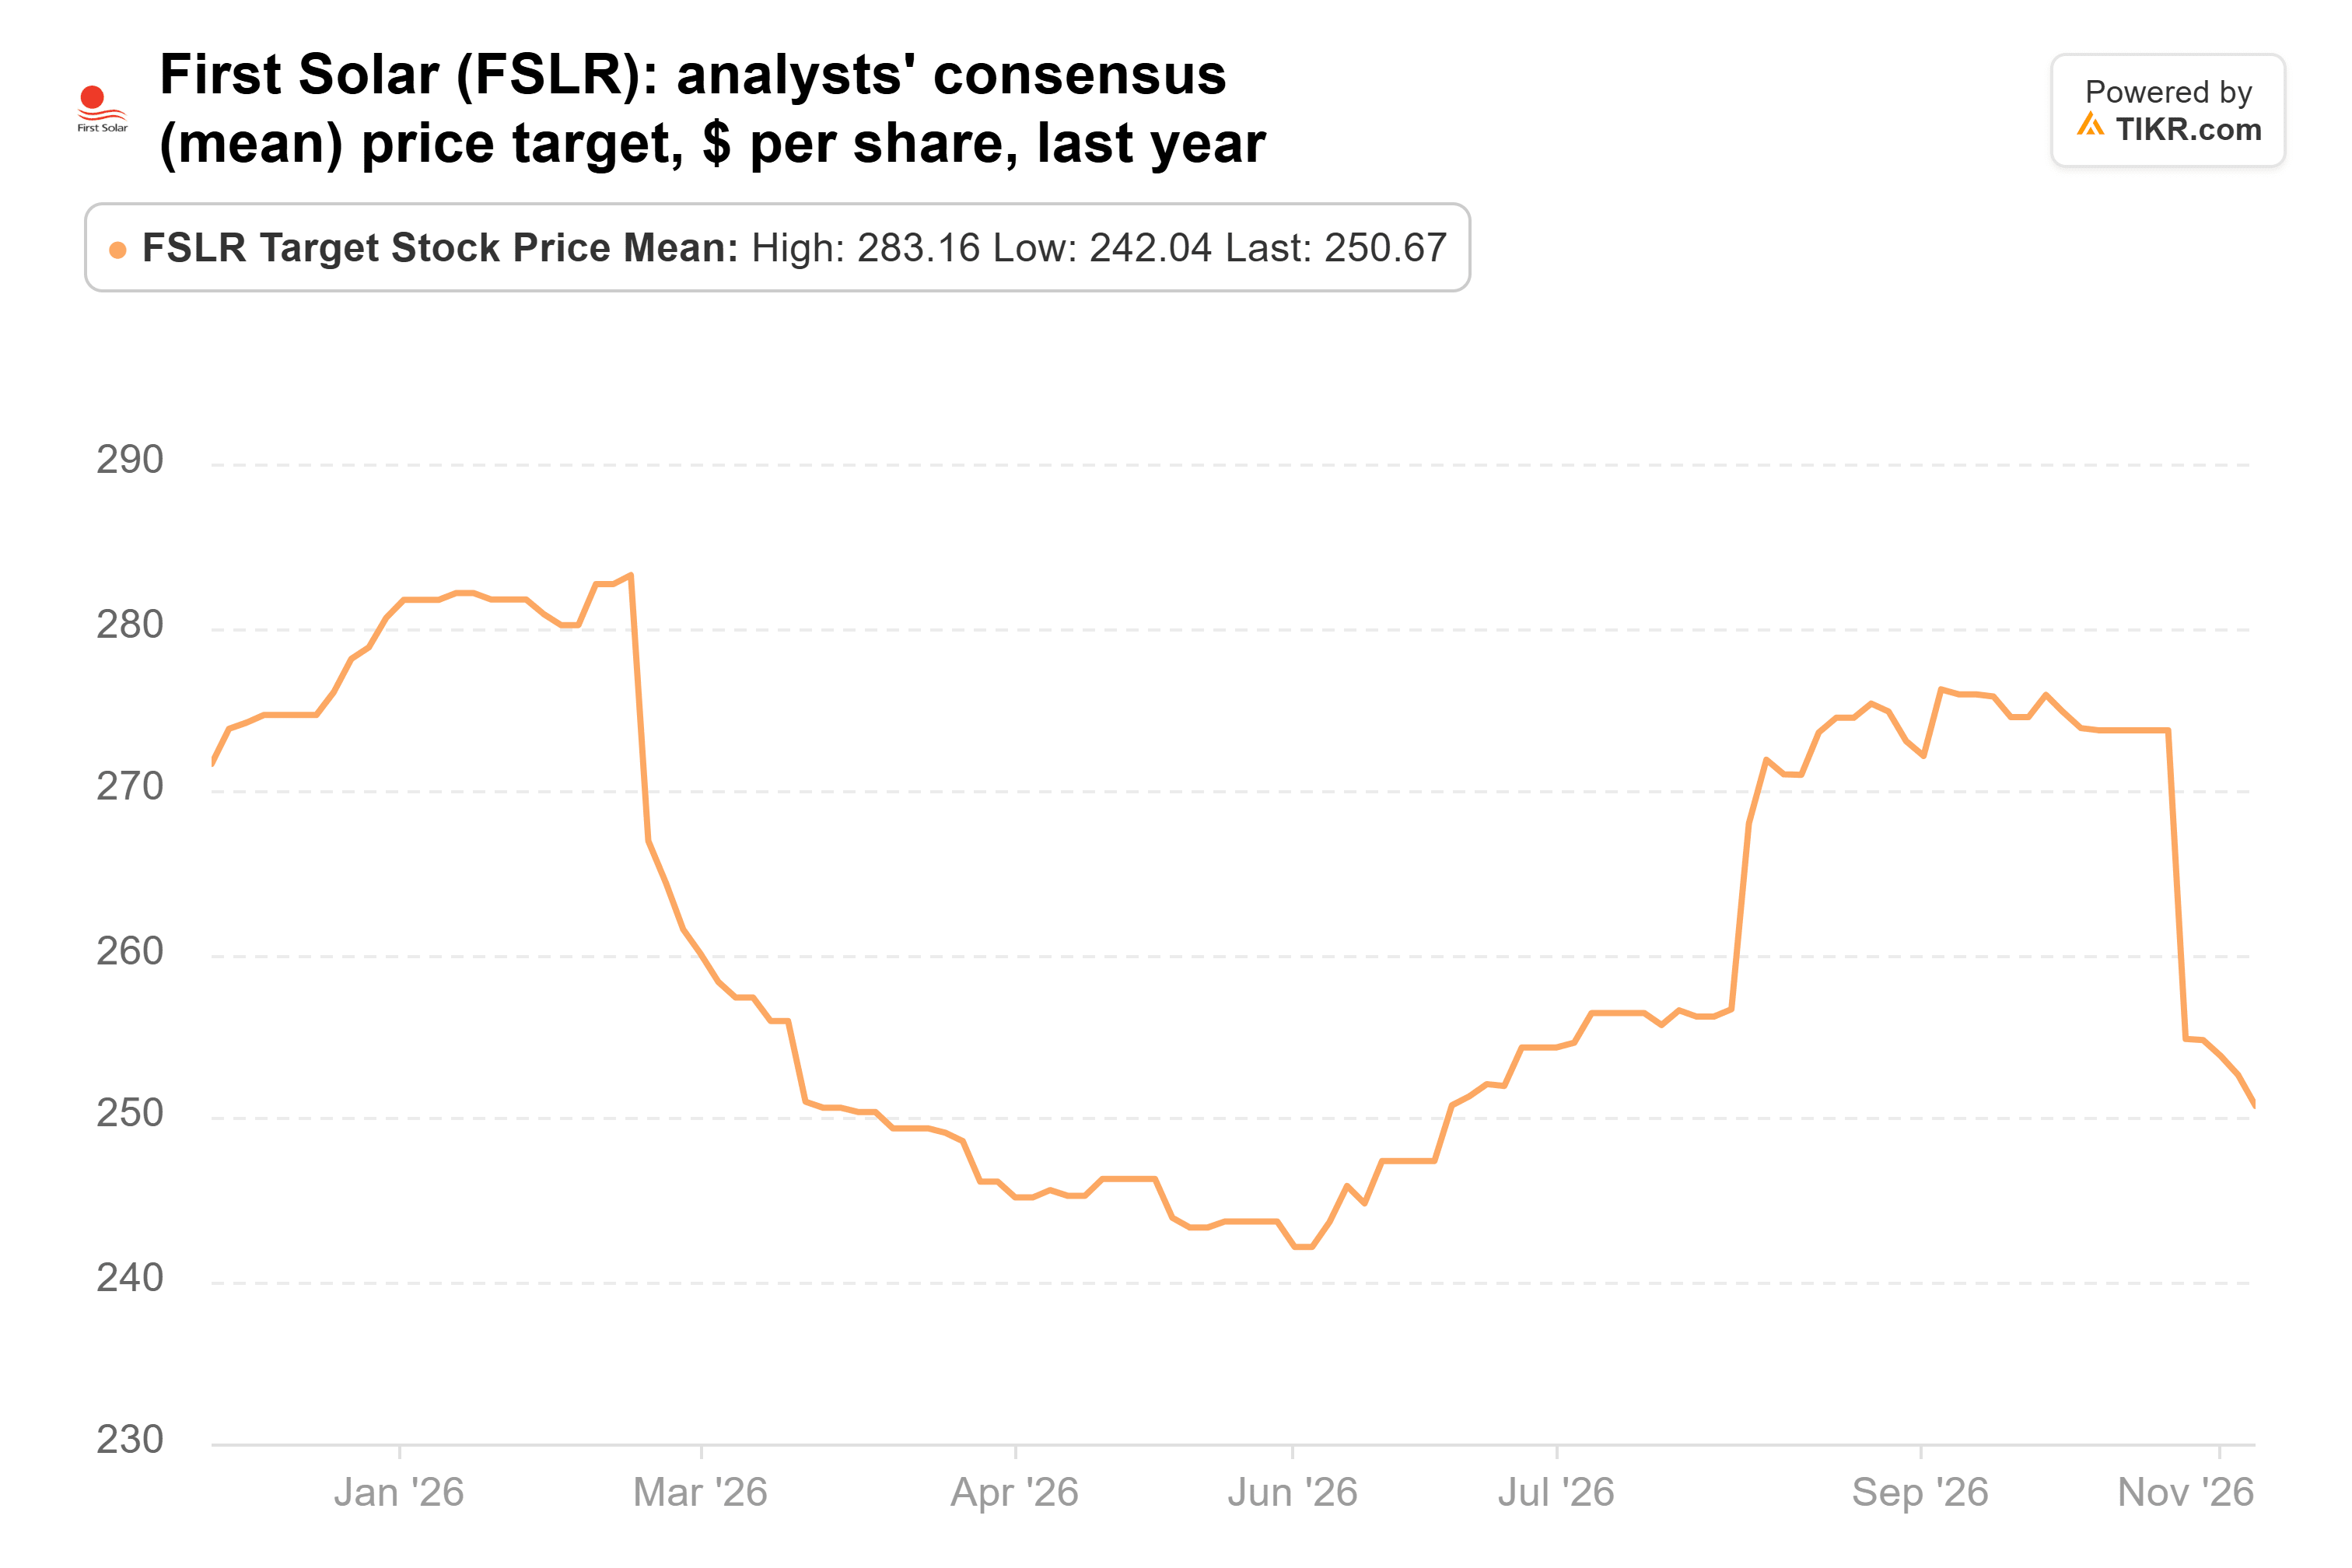
Even the lowest target, $169, sits well above the last close of $138. Discovery isn’t alone, either: a $14 billion fund also bought First Solar last quarter. At about 6x forward earnings it looks like a bargain, but a company that just cut its sales outlook has to show those earnings estimates can hold.
If I could only buy one
Amazon’s risk is the bill. On consensus, free cash flow stays negative until 2028. And once Anthropic trades, Amazon’s stake in it will be marked to market every quarter, so Amazon’s earnings will swing with Anthropic’s stock.
Even so, if I could only buy one right now, it’d be Amazon. Its targets are rising, AWS is growing faster than it has in nearly five years, and the stock trades below its own recent average. Take-Two’s case rests on GTA VI selling well beyond launch week, and First Solar’s on a quarter that shows sales have stopped shrinking.
Of course, Amazon gives its 2027 capex outlook with its fourth-quarter report in early February. If it guides well above the $278.2 billion analysts expect, investors will wait longer for the cash to come back. Discovery’s next 13F, due in mid-February, will show whether it kept adding.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!