Key Takeaways
- Microsoft CEO Satya Nadella said selling to one or two customers “is not a business,” and that Microsoft builds its own capacity first and rents last.
- That’s a warning for CoreWeave, whose three biggest customers made up 72% of second-quarter revenue, and for Nebius and IREN, which count Microsoft as an anchor customer.
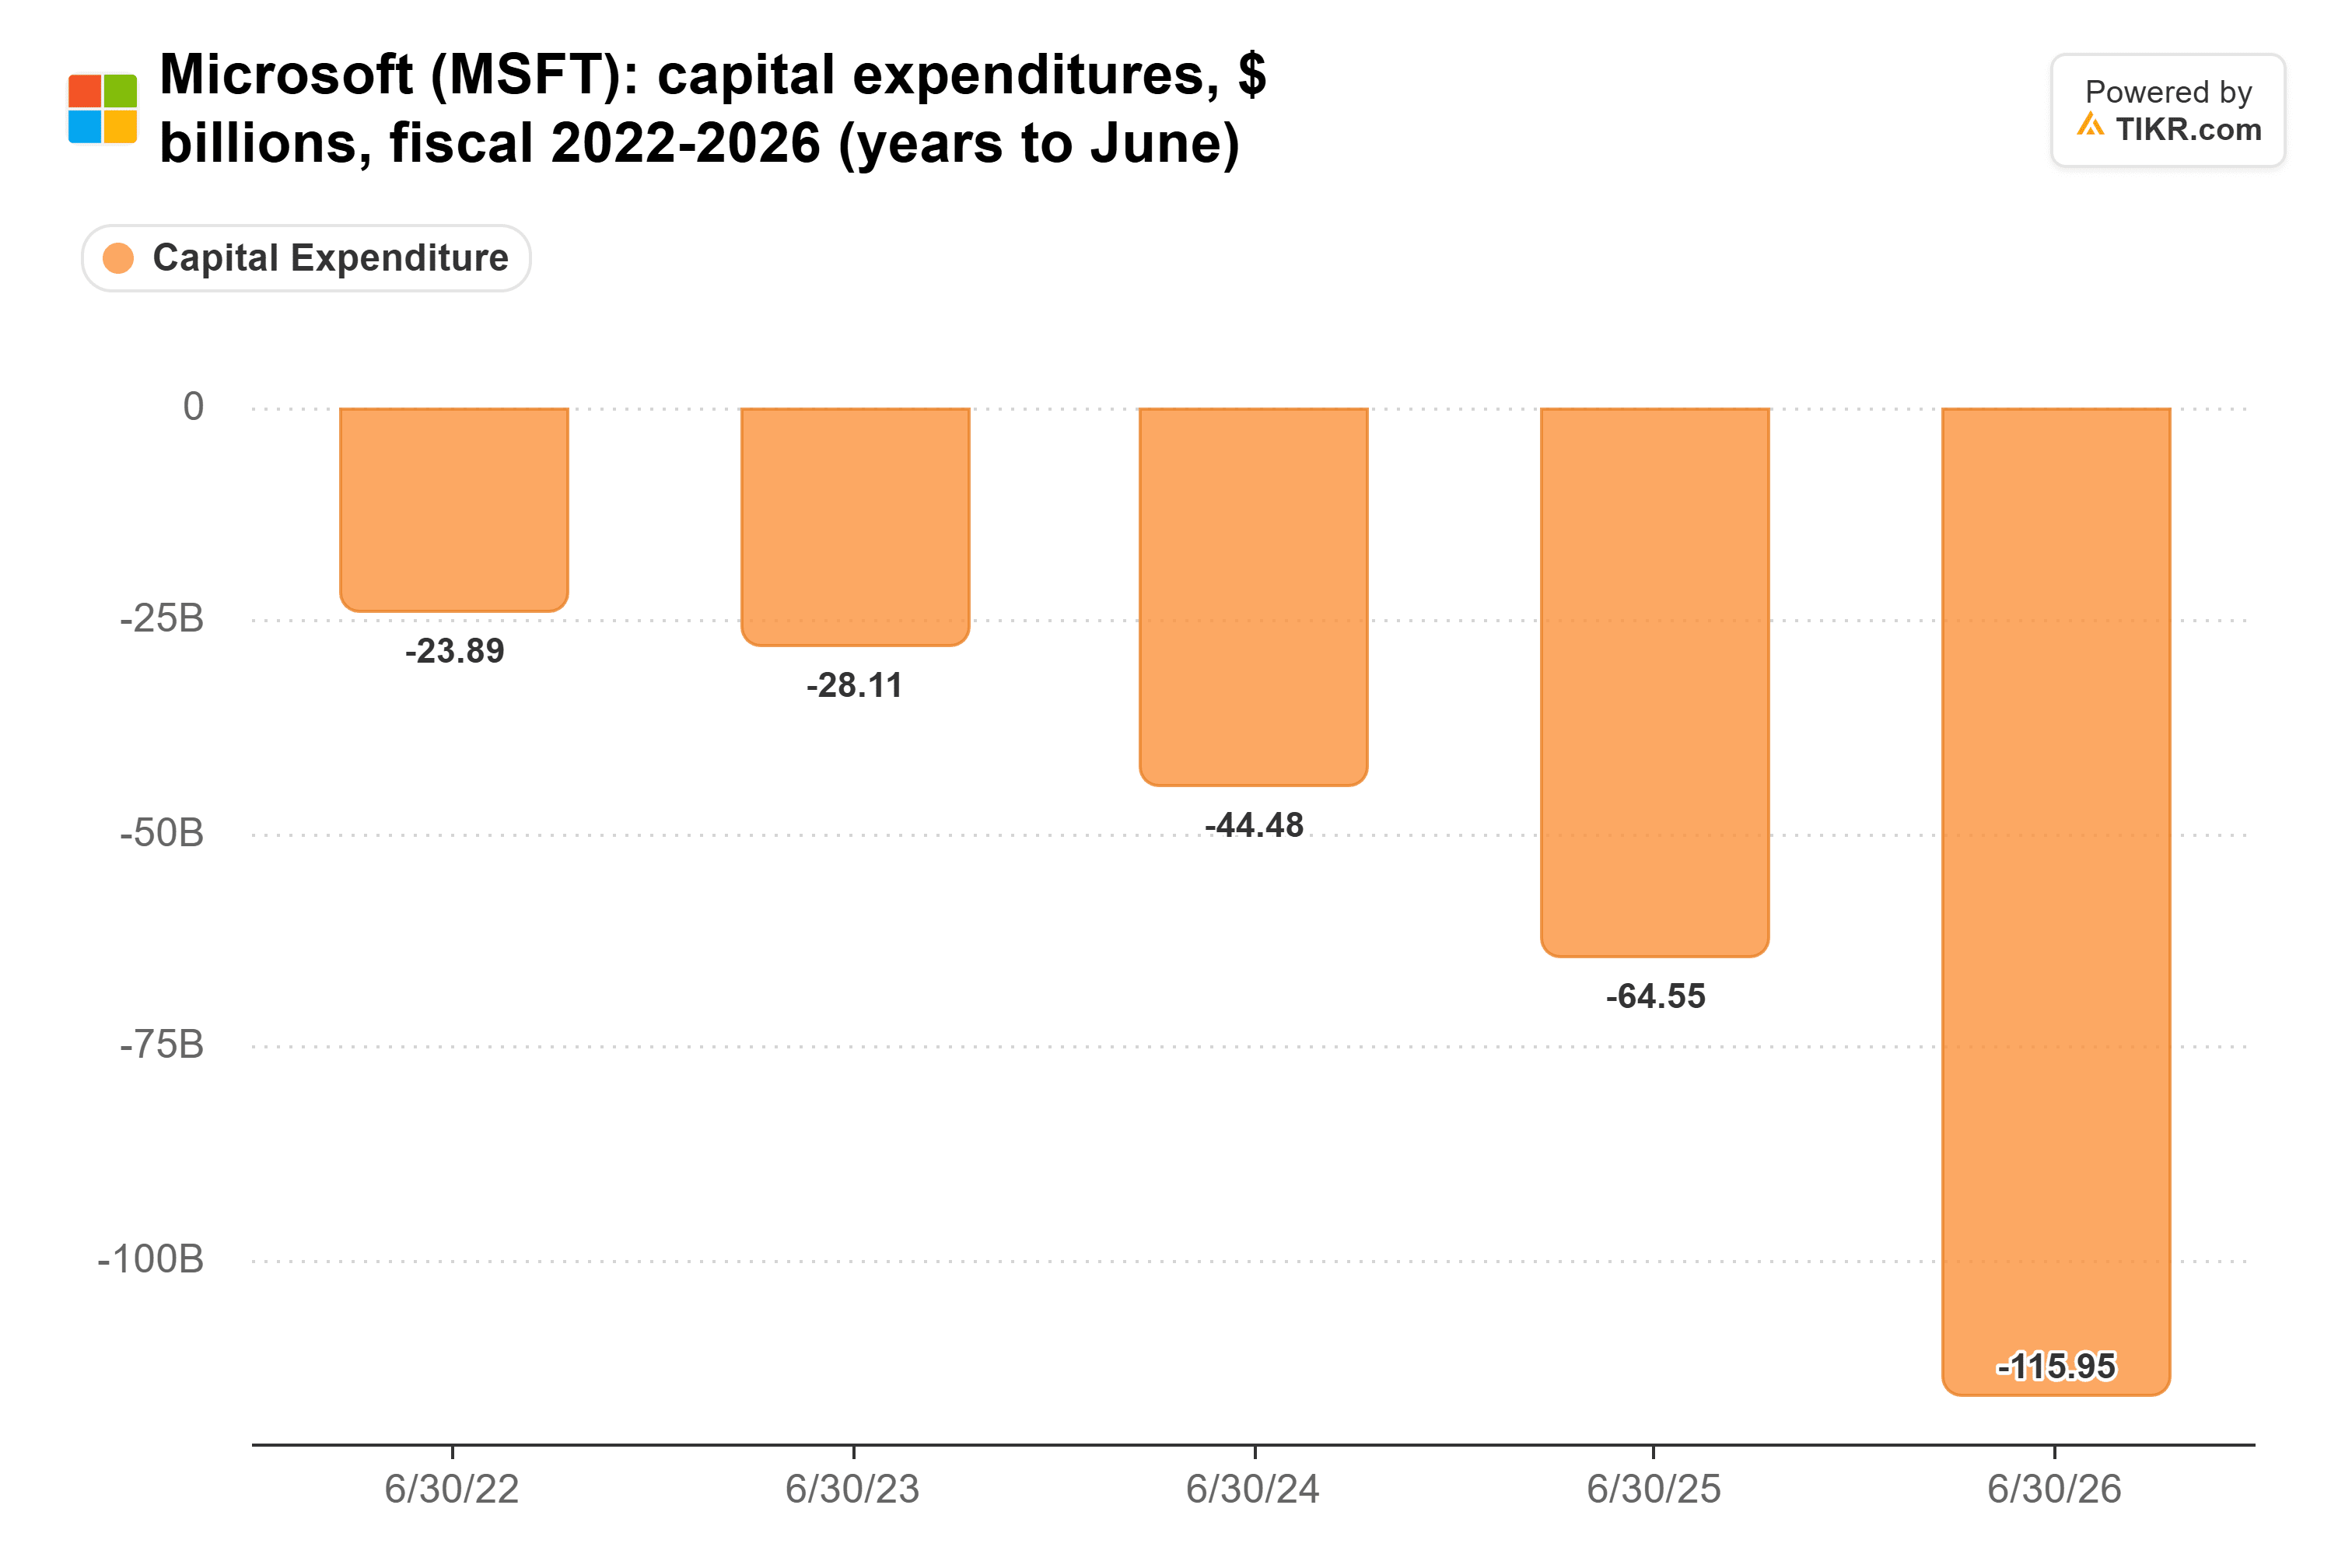
- CoreWeave’s free cash flow was negative $7.25 billion in 2025, while Microsoft spent $116 billion on capex in its latest fiscal year.
- CoreWeave’s customer base is broadening, but it still rests on a few big buyers, and its landlord Applied Digital carries the same risk.
Microsoft (MSFT) CEO Satya Nadella has a blunt view of companies that live off a couple of big customers.
“Just selling to one or two customers is not a business in my opinion,” he said on the Nov. 18 episode of Mad Money, while explaining how Microsoft matches its spending to demand.
He didn’t name anyone. But Jim Cramer’s next question was about the neoclouds, and that’s a problem for CoreWeave (CRWV), which leans on a few huge buyers, and for Nebius (NBIS) and IREN (IREN), which count Microsoft as an anchor customer. Even Applied Digital (APLD), which leases its only running campus to CoreWeave, is exposed.
Cramer asked whether that’s why Microsoft uses neoclouds for “a minority of your business, but still a great deal,” adding: “They charge 30% more than if you build your own.”
Nadella said Microsoft rented because it was short of supply. “We build, we lease, we rent. All three will always be options,” he said, but “we build for the long term, we lease and then we rent.”
So renting comes last. That’s not great news if renting out compute is your whole business.
TIKR tracks 41 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
Three customers, most of the money
Analysts expect CoreWeave’s revenue to go from $5.13 billion in 2025 to $13.1 billion this year and $45.1 billion by 2028:

But three customers made up 72% of CoreWeave’s second-quarter revenue.
Building for those customers also costs far more than the business brings in. Free cash flow went from negative $70 million in 2022 to negative $7.25 billion in 2025:

Analysts expect free cash flow to stay negative every year through 2030, so CoreWeave needs lenders to keep funding the build. And they’re charging for the risk: its 9.75% notes due 2031 last traded at 79.75 cents on the dollar on Nov. 2, a 15.83% yield.
Microsoft would rather build
You can see Nadella’s order in Microsoft’s own spending. Capex rose from $23.9 billion in fiscal 2022 to $116 billion in fiscal 2026, the year ended June 2026:
Every data center Microsoft builds is one it doesn’t have to rent at Cramer’s 30% premium.
That’s the risk for Nebius and IREN. Nebius’s Microsoft contract alone is worth up to $19.4 billion. IREN put its Horizon 1 data center into service for Microsoft in the quarter to Sept. 30. Both contracts run for years, so the question is the next one, once Microsoft’s own buildings catch up.
Applied Digital’s other four leased campuses go to investment-grade hyperscalers, which is Nadella’s advice in practice, but until they come online, its AI rent comes from CoreWeave.
Intrator’s 50% is a head count
CoreWeave CEO Mike Intrator sees it differently. “50% of our clients in the first three quarters of this year are not AI labs,” he said in an interview Semafor posted on X.
And the mix is getting better. CoreWeave’s largest customer went from 71% of revenue in the second quarter of 2025 to 36% a year later, and 30% in the third quarter.
But Intrator counted clients, and a small client counts the same as the biggest one. The buyers replacing the labs look a lot like the biggest names in tech, and Nadella just told us Microsoft rents last.
The way I see it, that makes Nadella’s line a fair warning for CoreWeave. Of course, if AI demand keeps outrunning what Microsoft can build, it may keep renting longer than Nadella suggests. CoreWeave’s fourth-quarter report, due early next year, will show whether its top customer’s share keeps falling.
So what is CoreWeave stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CoreWeave could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!