Key Takeaways
- Truist raised its Walmart price target to $134 from $114 after the third-quarter report and kept its Buy rating. That’s 6% above today’s price.
- Walmart raised its fiscal 2027 adjusted EPS outlook to $2.84-$2.89 as Walmart U.S. advertising grew 37% and Walmart U.S. eCommerce grew 23%.
- Walmart trades at 42x forward earnings. That’s well above its five-year average of 30x and more than twice Target’s 17x. Costco trades at 48x.
- Truist’s target needs investors to still pay about 37x earnings a year from now, so the stock’s run has already priced in most of the good news.
Truist raised its price target on Walmart (WMT) to $134 from $114 on Nov. 19 and kept its Buy rating after Walmart beat estimates and raised its outlook. The new target is 6% above where the stock trades after a 24% gain over the past year.
Costco (COST) trades at 48x forward earnings, and Target (TGT) at 17x after a quarter in which its traffic grew faster than Walmart’s.
Ads and membership carried the quarter
In the quarter ended Oct. 31, Walmart U.S. advertising rose 37%, Walmart U.S. eCommerce grew 23% and global membership fee revenue grew 17%. Walmart raised its fiscal 2027 adjusted EPS outlook to $2.84-$2.89 from $2.80-$2.87.
Walmart U.S. comparable sales grew a slower 2.9%, on 1.5% more transactions, while Target’s rose 5.6% on 5.0% more traffic. Walmart’s $120 bundle of Walmart+ and Sam’s Club Plus, launched Oct. 20, goes after Costco, whose Dec. 10 report will be the first sign of whether it’s costing Costco members.
TIKR tracks 44 analysts on Walmart. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Walmart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Walmart’s Analyst Ratings
Truist wants a premium for it
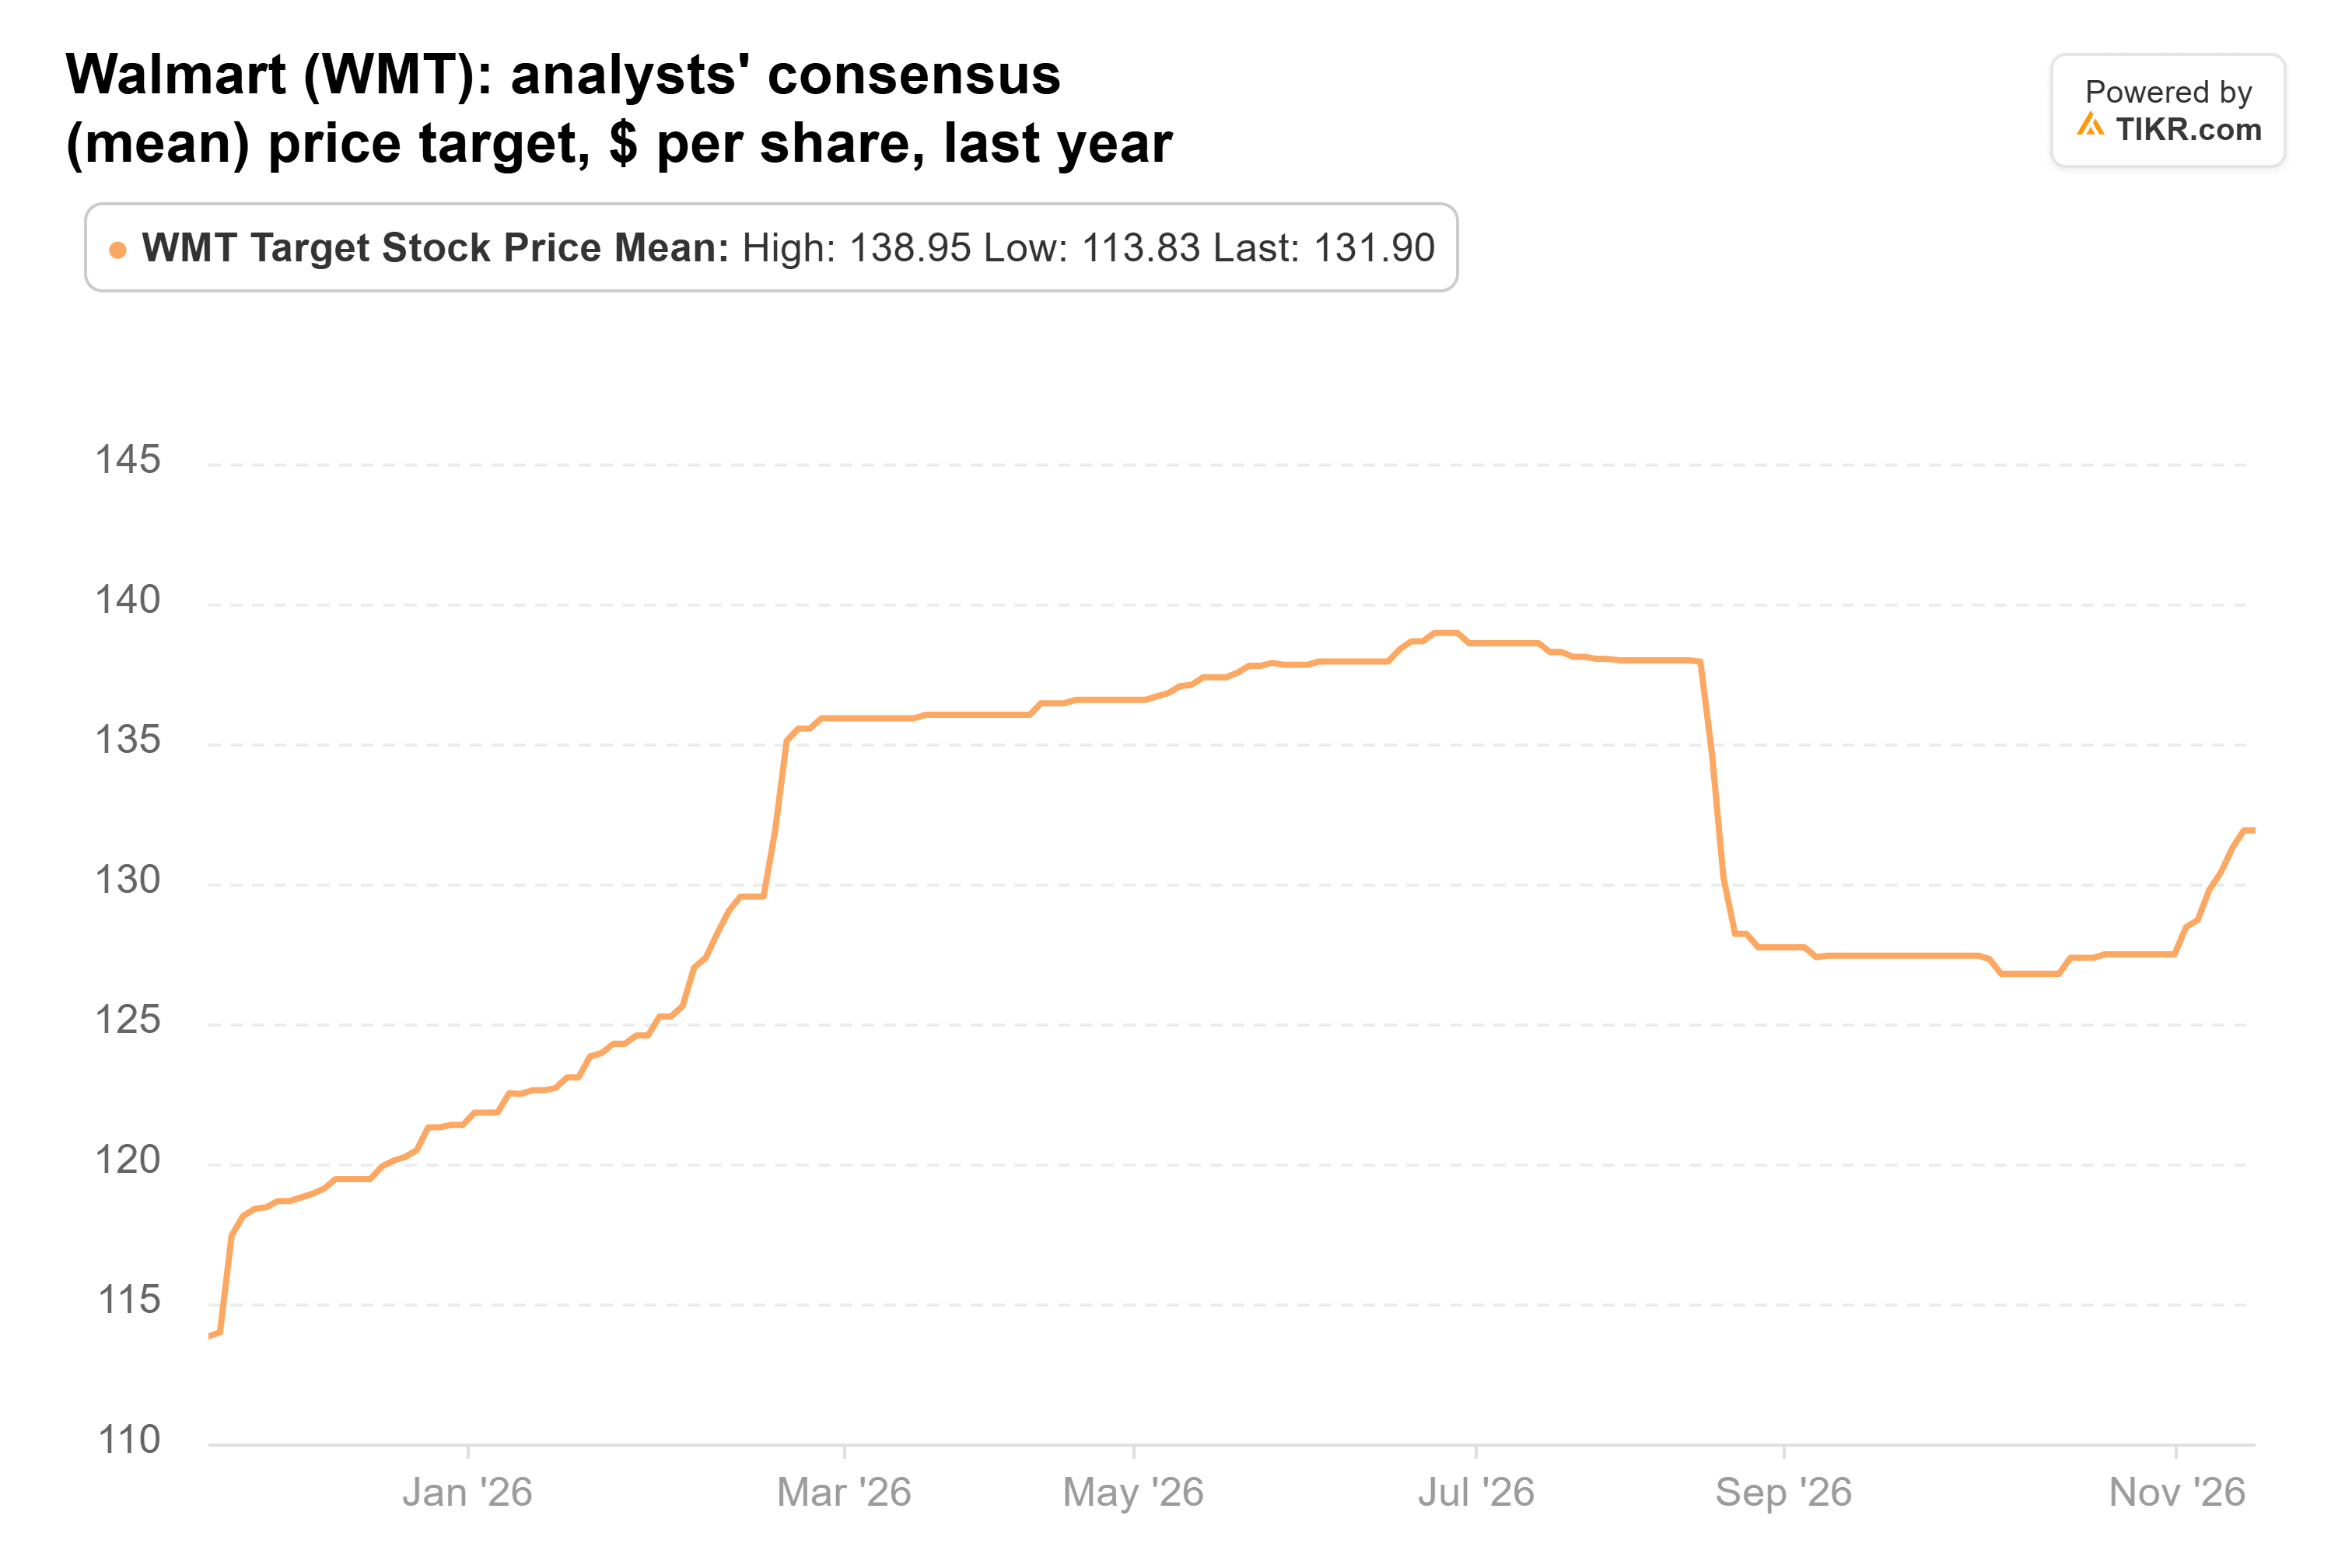
Truist expects low prices and faster delivery to keep winning market share while ads, marketplace and membership widen the margin, and says the stock deserves a premium valuation. Its $134 is a little above the $132 consensus target from 45 analysts, which was set before the report. That average has slipped since its $139 peak in late June:
Does $134 add up?
Analysts expect normalized EPS of $3.23 in fiscal 2028 and $3.63 in fiscal 2029, the year ending January 2029:
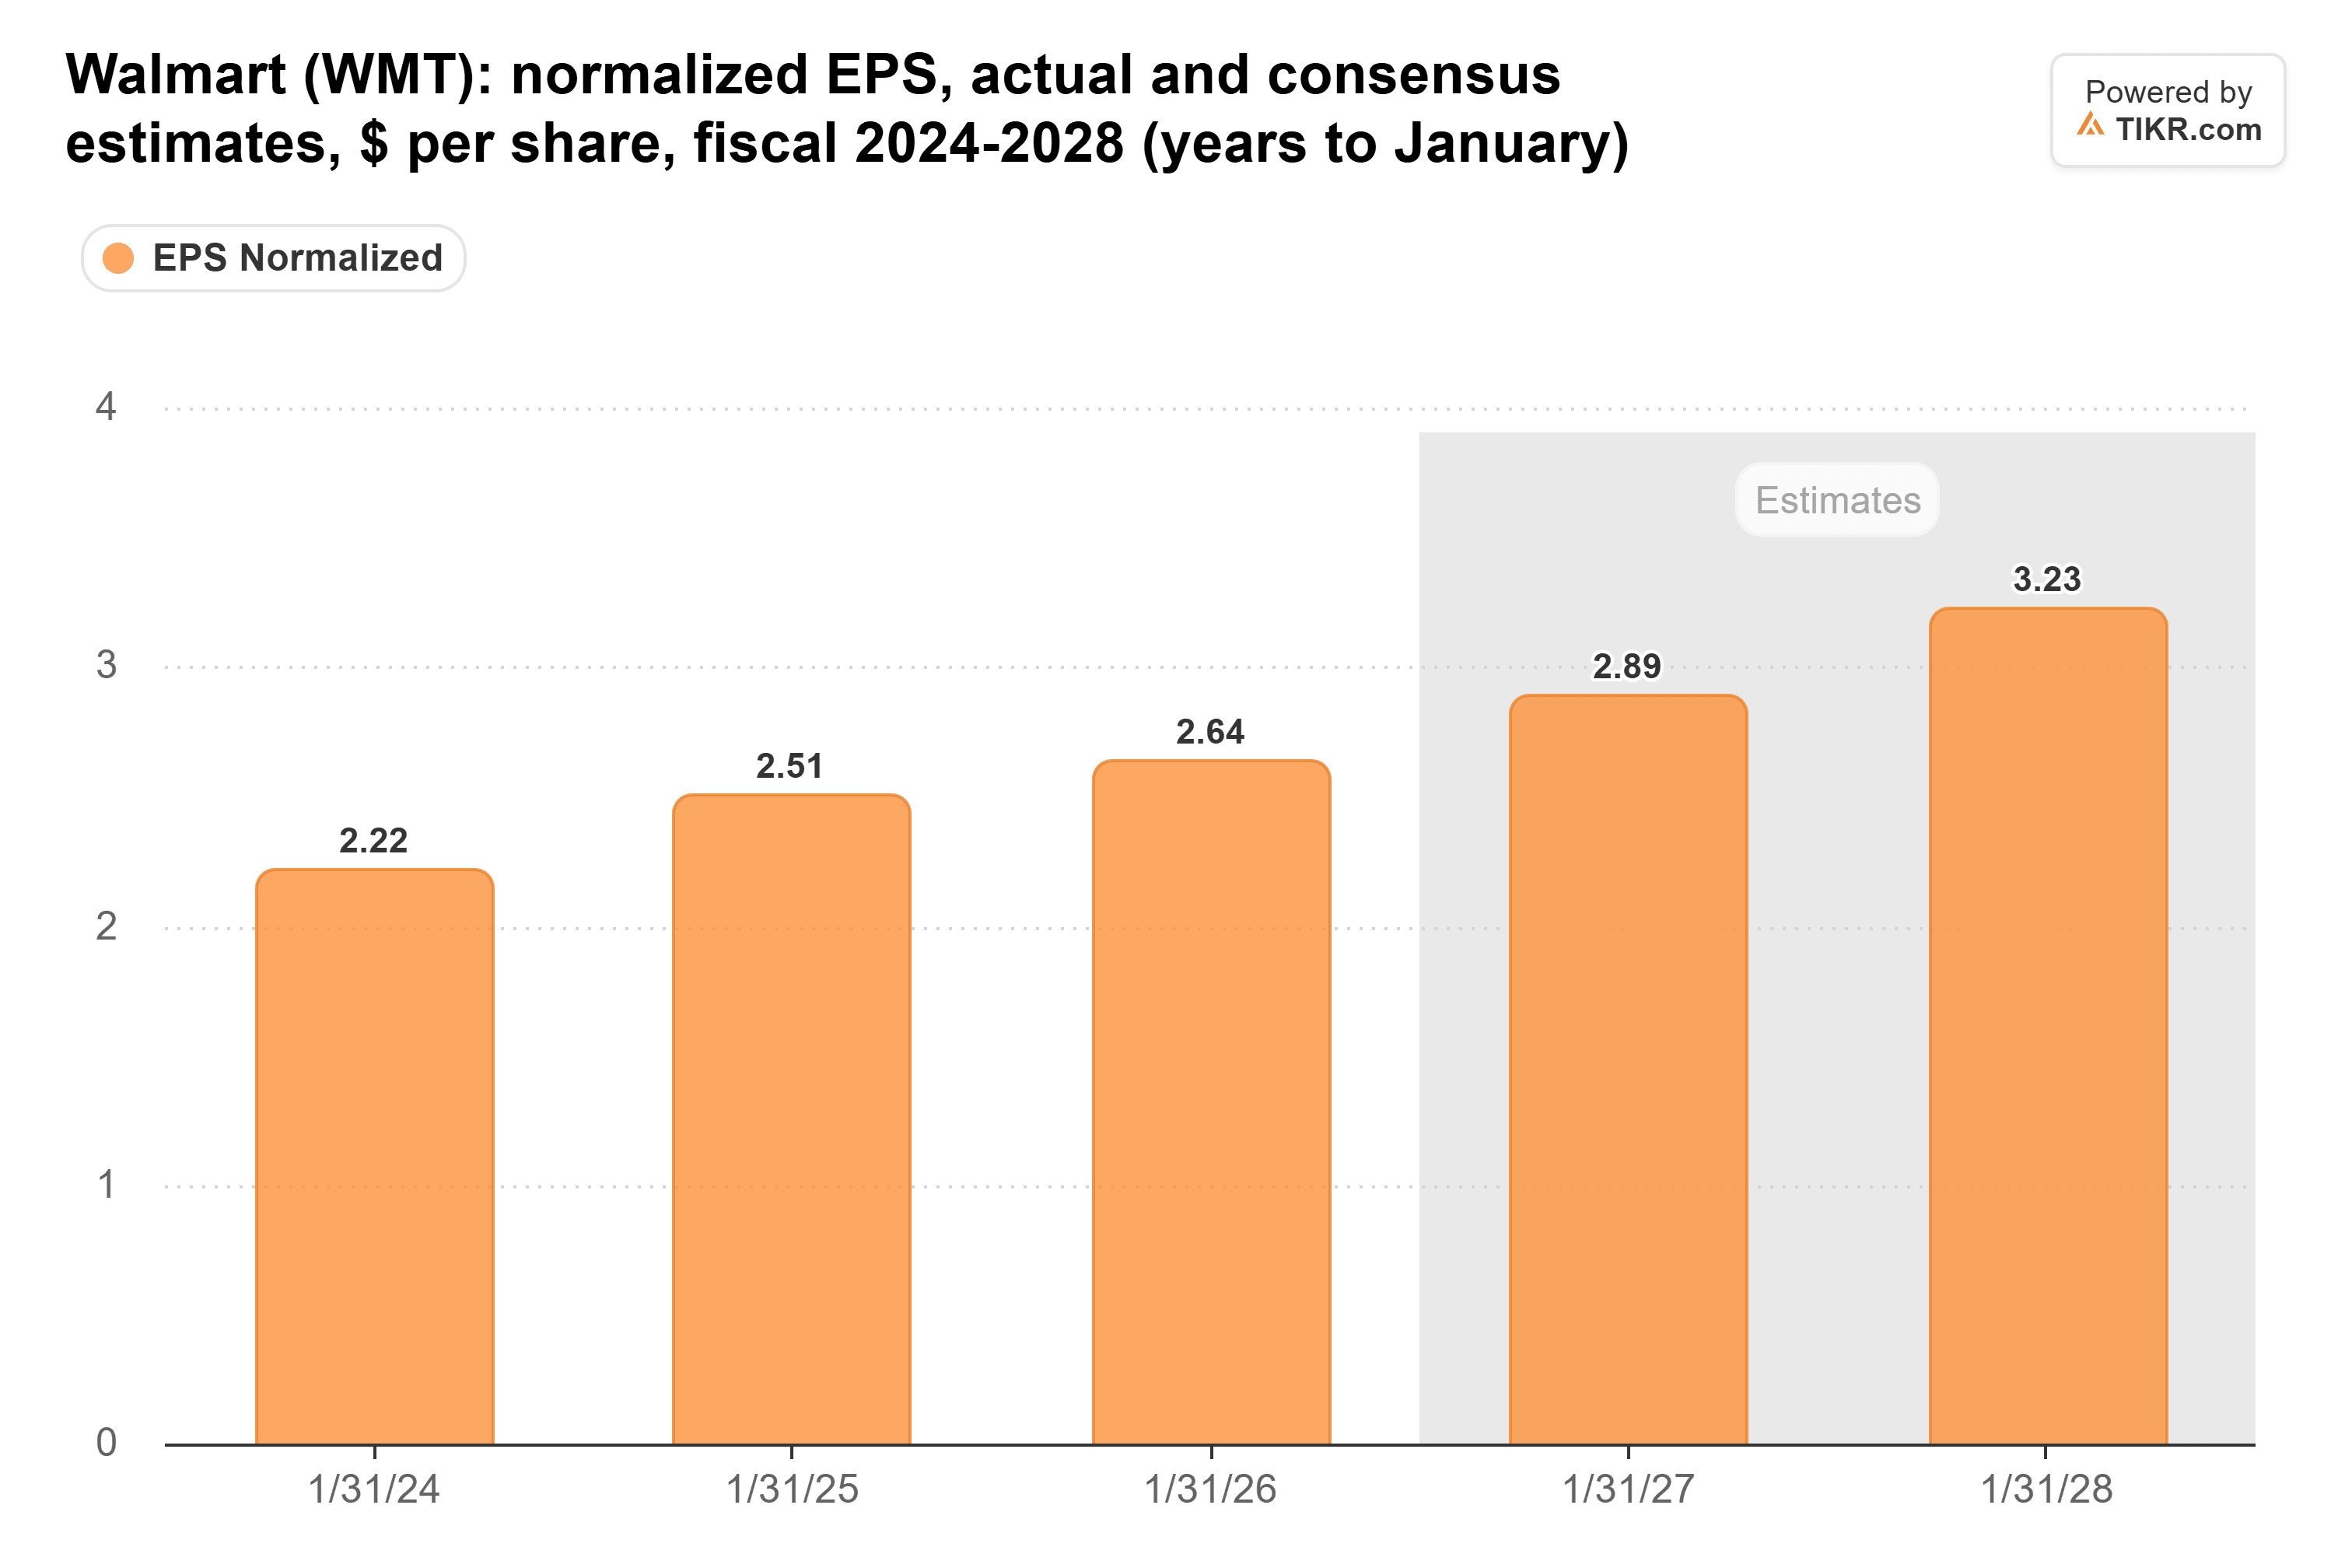
With the raise, Walmart only caught up to the $2.89 analysts already expected for fiscal 2027.
Walmart’s forward P/E is near the top of its five-year range:
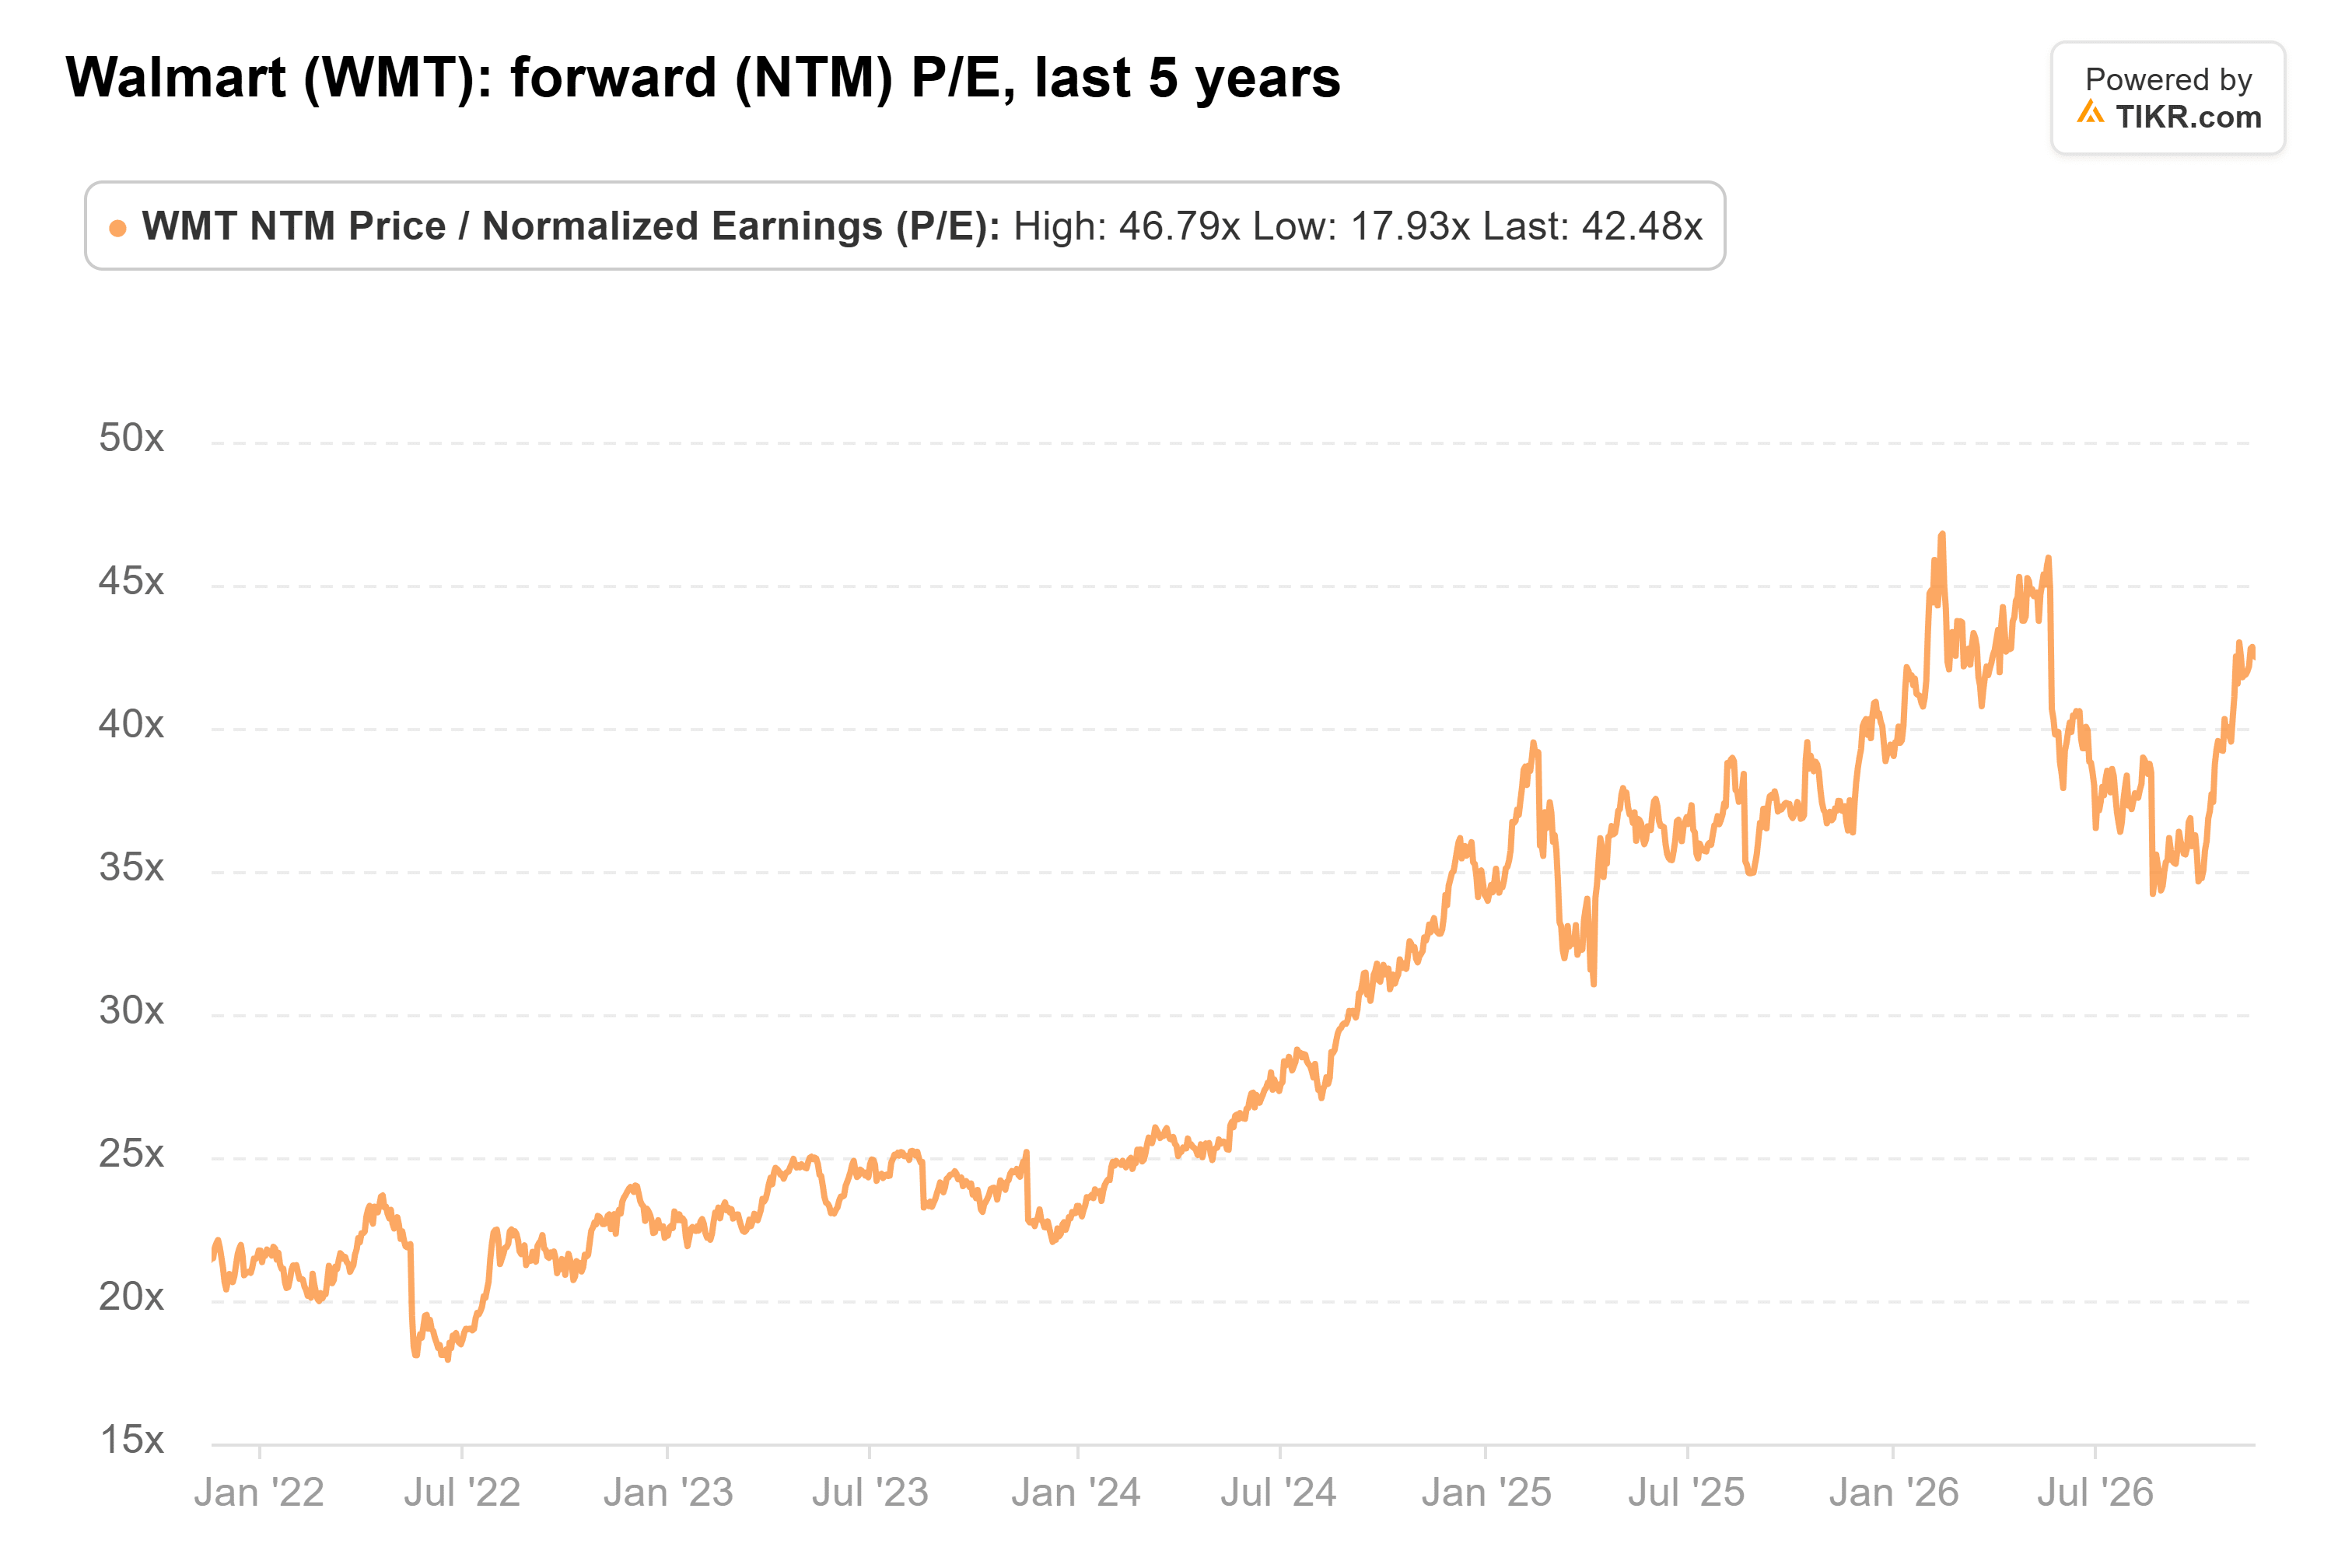
At 42x, the multiple is close to February’s high of 47x and well above its five-year average of 30x. On fiscal 2029 estimates, Truist’s $134 is about 37x earnings. To get there, earnings grow 21% while the multiple falls 13%. At the five-year average multiple, that same $3.63 is worth about $107 a share.
Priced for the good news
The risk is cost: free cash flow fell $2.0 billion to $6.8 billion in the first nine months.
The way I see it, Truist has the business right, and the stock already reflects it. An upside of [6%] is a thin reward for paying more than twice Target’s multiple. The next test is the fiscal 2028 outlook, due in February. If Walmart guides EPS at or above the $3.23 analysts expect, $134 is within reach. If it doesn’t, there’s little cushion at 42x.
So what is Walmart stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Walmart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!