Key Takeaways
- A fund that manages $4.5 billion opened a stake in ServiceNow and added to Valvoline and ESCO Technologies in the third quarter, its new 13F shows.
- ServiceNow, the biggest of the three, is down 34% since Sept. 30 after a softer growth outlook.
- Valvoline is up 22% since Sept. 30, and ESCO is down 16% even as its earnings keep climbing.
- ServiceNow looks like the best buy of the three, at about 20x forward earnings against a five-year average of 53x.
One $4.5 billion fund went into October with a new top-10 stake in ServiceNow (NOW), and the stock has lost a third of its value since. Its two other big adds, Valvoline (VVV) and ESCO Technologies (ESE), have gone opposite ways.
The fund is Hawk Ridge Capital Management, which filed its 13F for the quarter ended Sept. 30 on Nov. 16. It shows $2.52 billion of US stocks across 38 positions.
The biggest bet is down 34%
Hawk Ridge held 945,381 ServiceNow shares worth $127 million on Sept. 30, 5.0% of its 13F stocks and its seventh-largest position. It held none three months earlier.
Most of the drop since then came after ServiceNow’s third-quarter report on Oct. 28. Contracted revenue due over the next 12 months grew 21%, helped by renewals pulled forward by a July 1 price change, and management guided it to 18.5% growth in the fourth quarter. The stock fell hard on that guide, and analysts cut their 2027 EPS estimate to $4.80 from $5.01.
The Street’s average target has come down with the estimates:
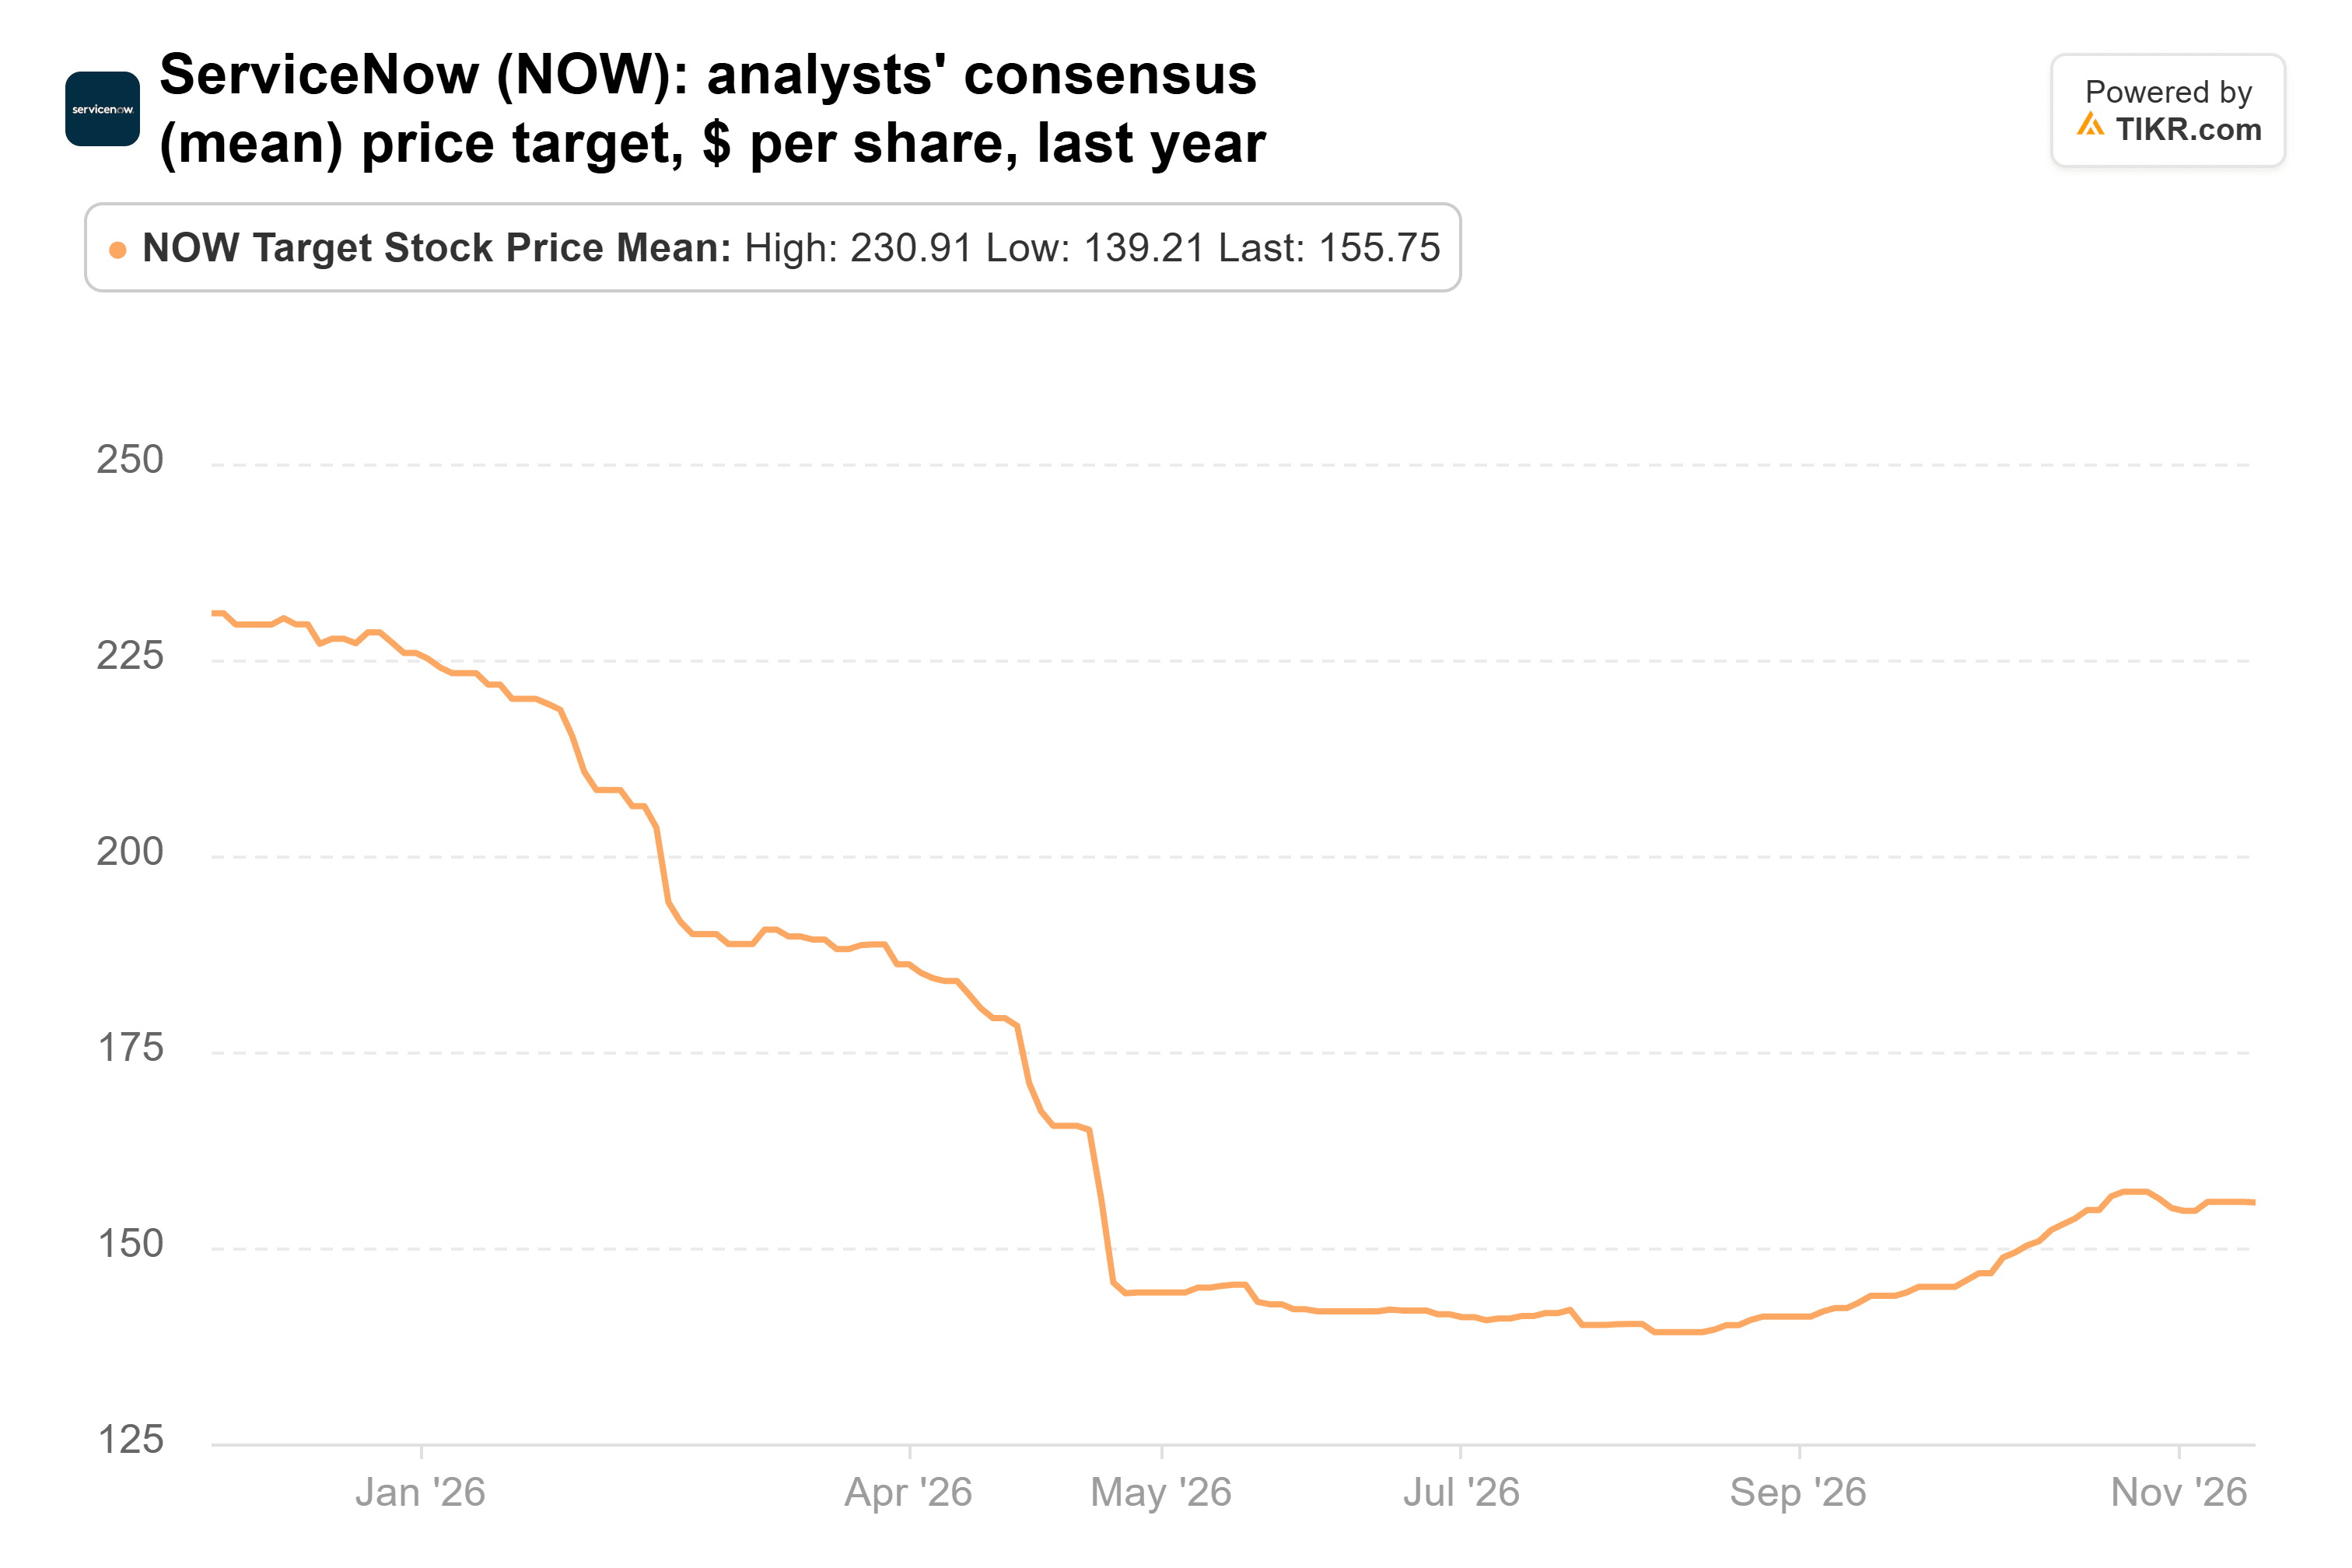
It’s $156 now, down from $231 a year ago. That’s still 75% above the last close.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
Valvoline already paid off
Hawk Ridge grew its Valvoline stake 35% to 3.98 million shares, worth $120 million on Sept. 30, or 4.8% of its 13F stocks. That one has worked out so far: the stock is up 22% since the quarter’s end.
Valvoline’s fiscal year ended Sept. 30, and it reported on Nov. 19. System-wide same-store sales rose 9.4% in the fourth quarter, extending its streak to 20 straight years of growth, and full-year adjusted EPS of $1.76 beat the top of its guidance. Free cash flow jumped to $204 million from $48 million in fiscal 2025. The catch is costs: gross margin fell 3 points in the quarter as lubricant prices climbed. Management guides fiscal 2027 adjusted EPS to $1.85-$2.05, and the stock trades at about 19x forward earnings.
The average target has barely moved in a year:
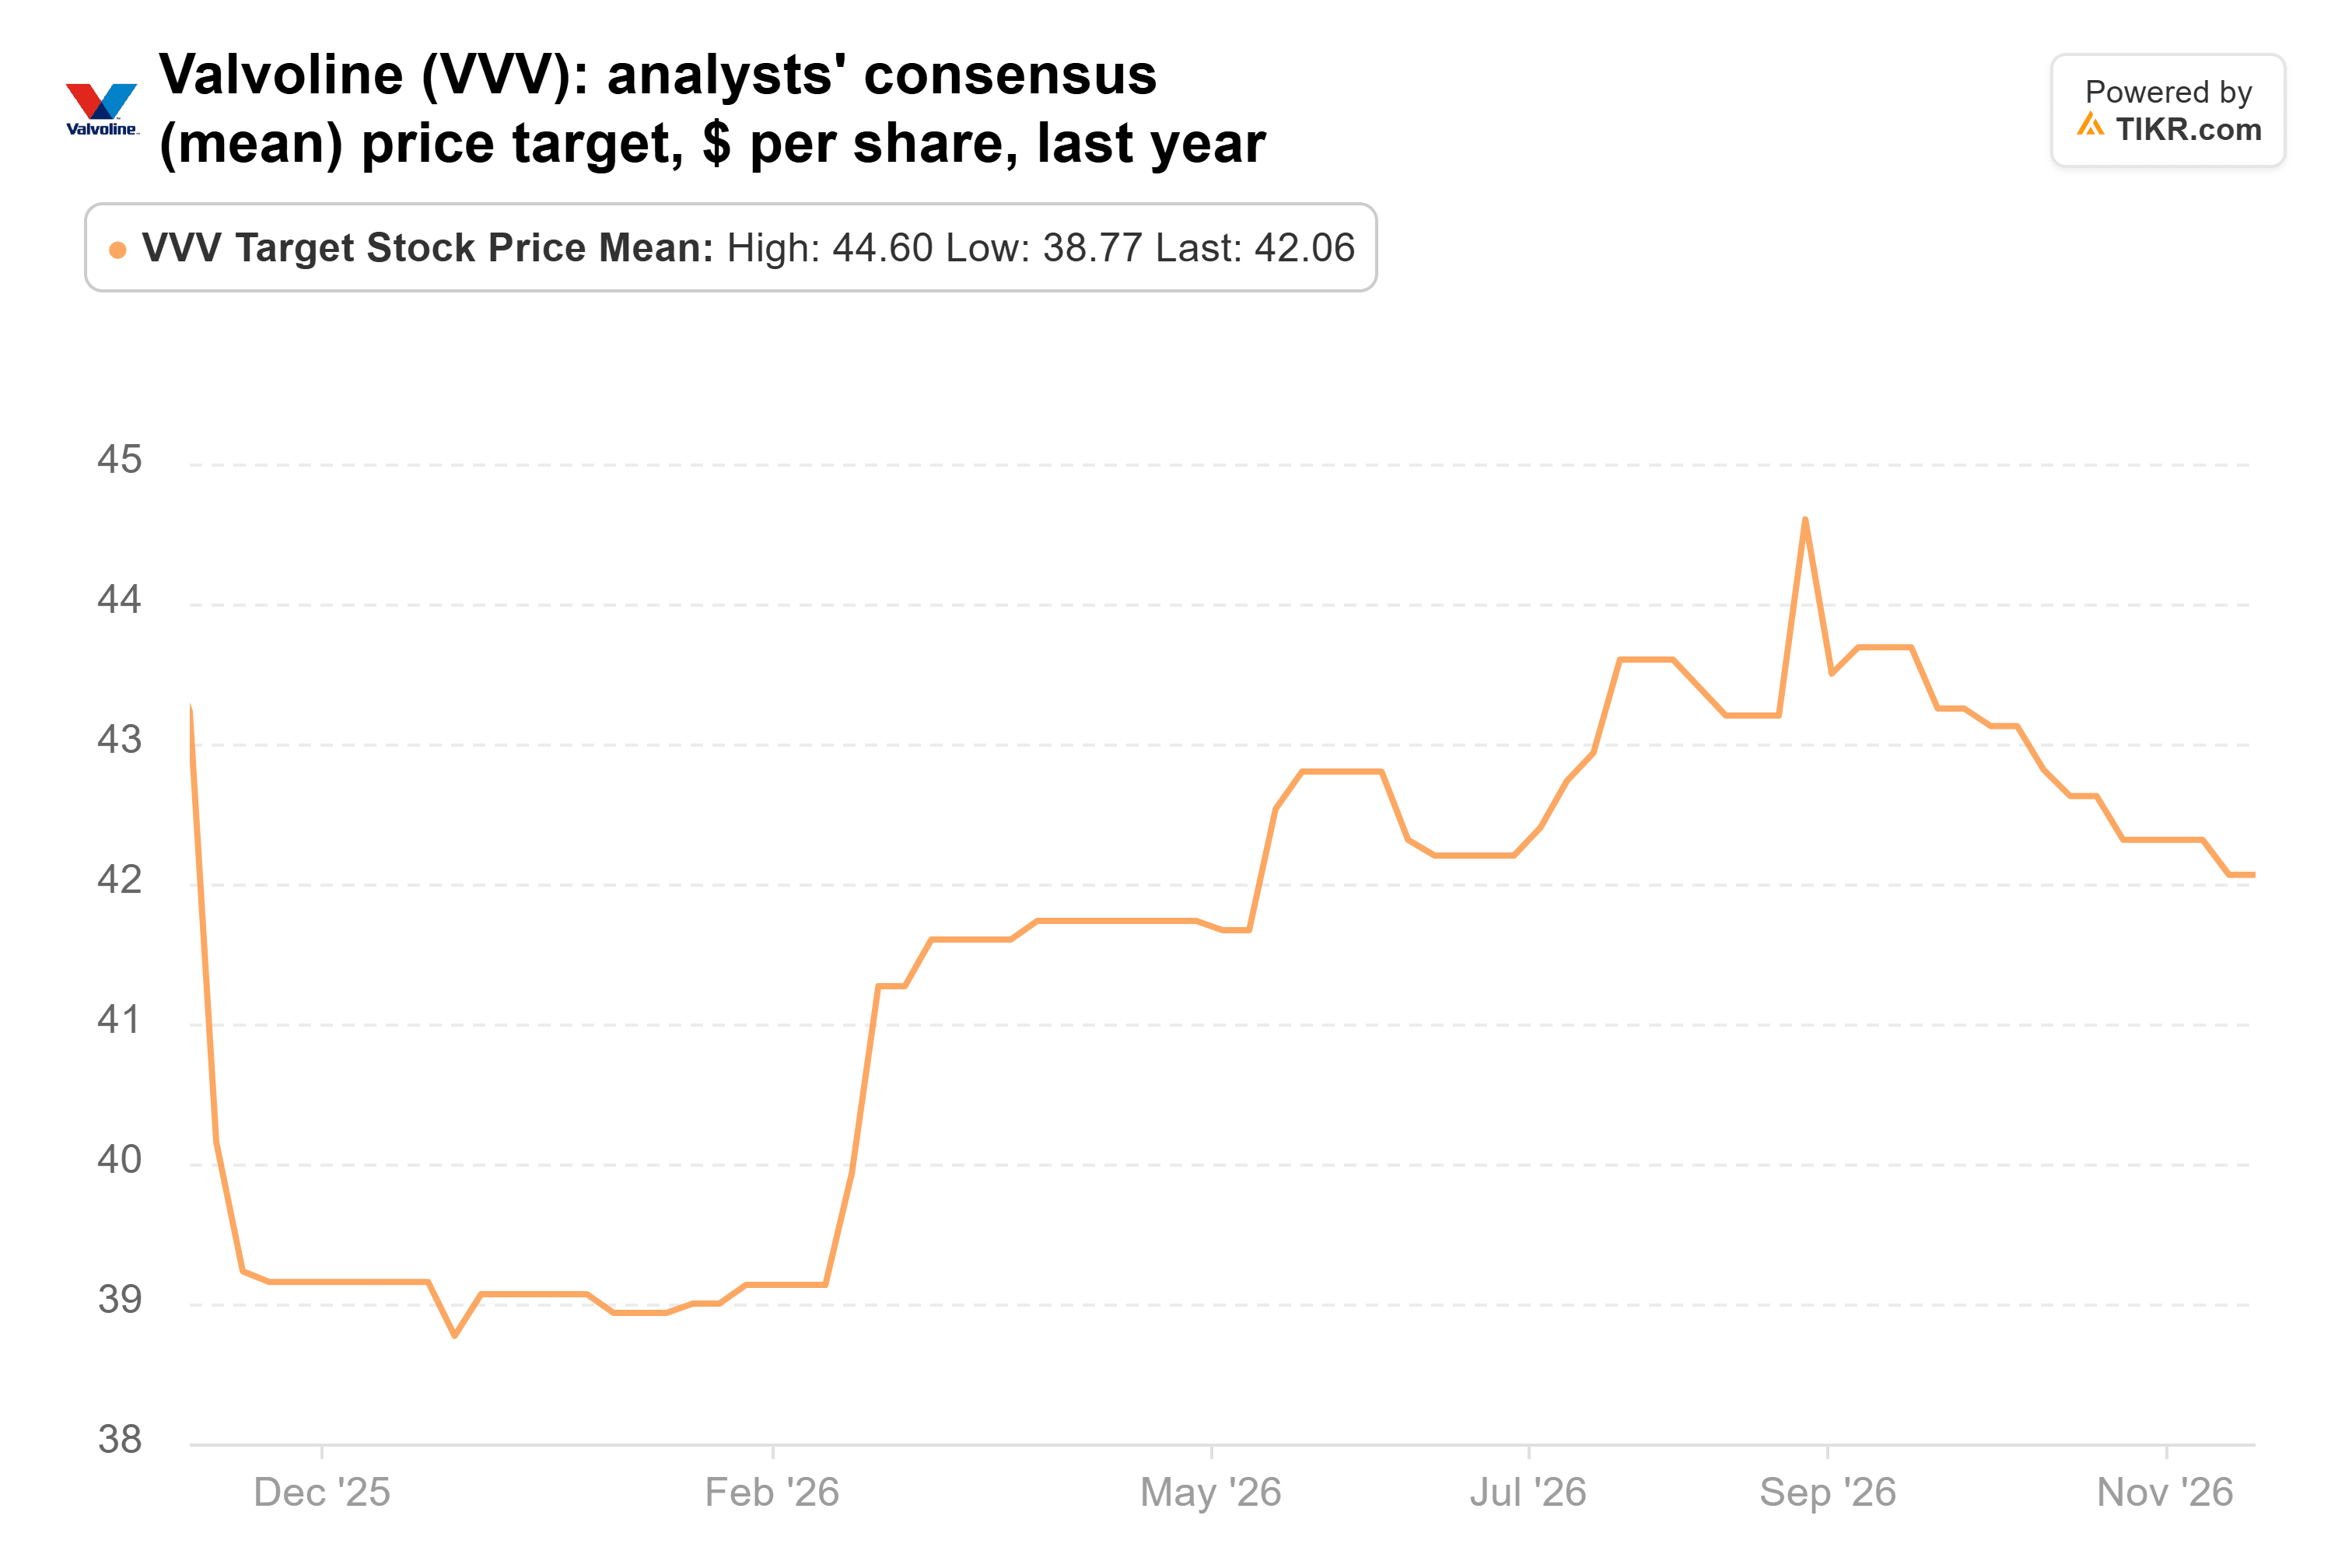
At $42, it sits 15% above the last close. Those targets came before the report, so they may rise, but much of the easy gain is already behind the stock.
ESCO’s earnings keep climbing
Hawk Ridge added 41% to its ESCO stake, ending the quarter with 425,380 shares worth $113 million, 4.5% of its 13F stocks. The stock has fallen 16% since then and sits 38% below its 52-week high.
ESCO reported after the close on Nov. 19, and the quarter was strong: sales rose 9% to $384 million, all of it organic, and adjusted EPS rose 15% to $2.67. For fiscal 2026, adjusted EPS climbed 40% to $8.42, and orders left it with a record $1.5 billion backlog. It has also closed its $2.35 billion purchase of Megger Group, and the quarter’s GAAP EPS of $1.97 carried financing and deal costs tied to it.
Only four analysts cover ESCO, and their average target rose over the year:
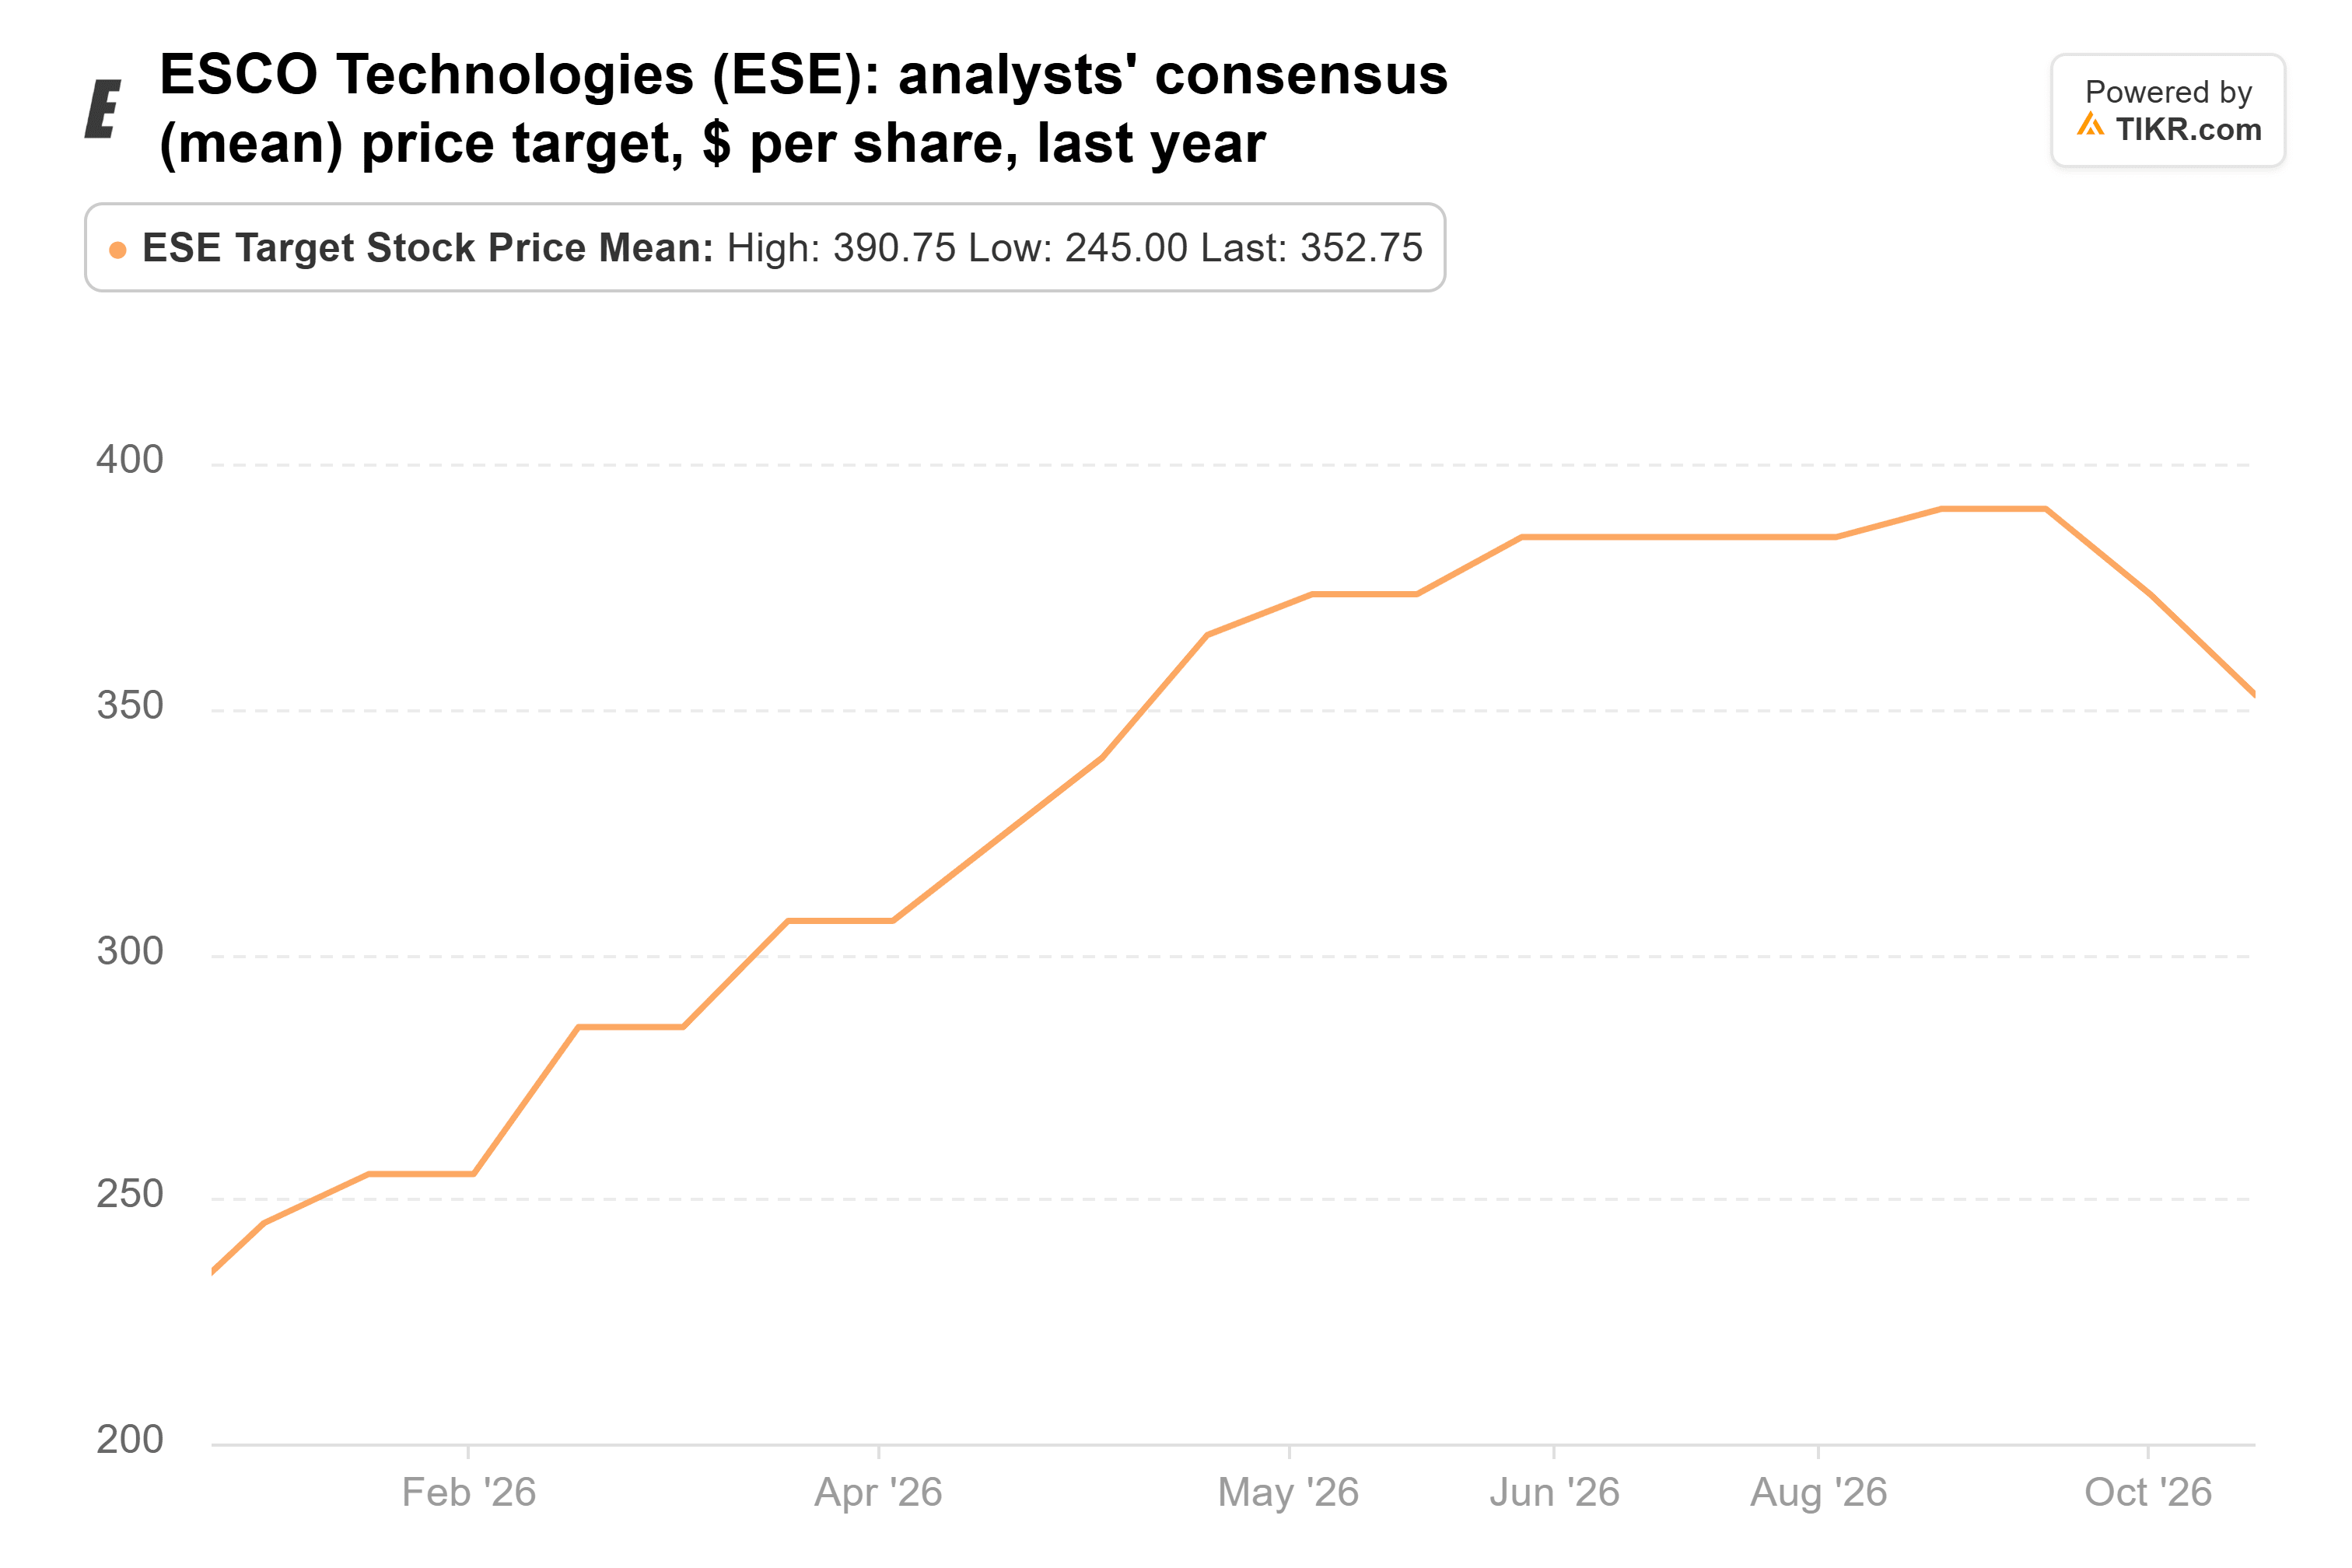
At $353, it’s 58% above the last close. It’s down from August’s $391, though, and was set before the report.
ServiceNow is the one to own
At about 20x forward earnings, ServiceNow trades below the 23x it hit on June 30 and far under its five-year average of 53x. Analysts expect revenue to grow from $13.3 billion in 2025 to $22.8 billion in 2028, about 20% a year. ESCO, at about 25x, costs more for a smaller company that grows partly through acquisitions.
Hawk Ridge has company, too: of the big funds that have filed, 25 bought ServiceNow last quarter and 13 sold.
The risk is the one behind the selloff: AI agents could shrink ServiceNow’s per-seat fees faster than its AI products make up for them. Interest expense also rose to $81 million in the third quarter from $6 million after it borrowed to buy Armis.
If I could only buy one of the three right now, it’d be ServiceNow, since its multiple already assumes a lot goes wrong. Its fourth-quarter report in late January will show whether AI contract value reached management’s raised $1.7 billion target. Hawk Ridge’s next 13F, due in mid-February, will show whether the fund held on through the drop.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!