Key Takeaways
- Nvidia trades at about 15x forward earnings after a 9% drop on Nov. 5, half its three-year average.
- Consensus sees $1.1 trillion in revenue by the year ending January 2030, a target Bob Elliott says is easy to miss.
- Only 8 analysts forecast that far out.
- The Nov. 17 report is the next test of whether 15x is cheap or a peak-cycle multiple.
Nvidia (NVDA) sank 9% on Nov. 5 in the chip selloff that followed the midterms, leaving it at its cheapest forward multiple in at least three years.
Bob Elliott, co-founder, CEO and CIO of Unlimited Funds, thinks the price still assumes too much. He told CNBC’s Closing Bell Overtime on Nov. 6 that “we have by no means unwound the mania in its entirety.”
Then he got specific: “the expectations are that Nvidia is going to sell a trillion dollars of chips on an annual basis in 29. And, you know, it doesn’t take much in terms of stalling of the AI trade to disappoint relative to those relatively extraordinary expectations.”
Wall Street Really Does Expect a Trillion
Elliott’s number checks out. Revenue estimates climb every year, and the one for the year ending January 2028 is up about 25% since June:
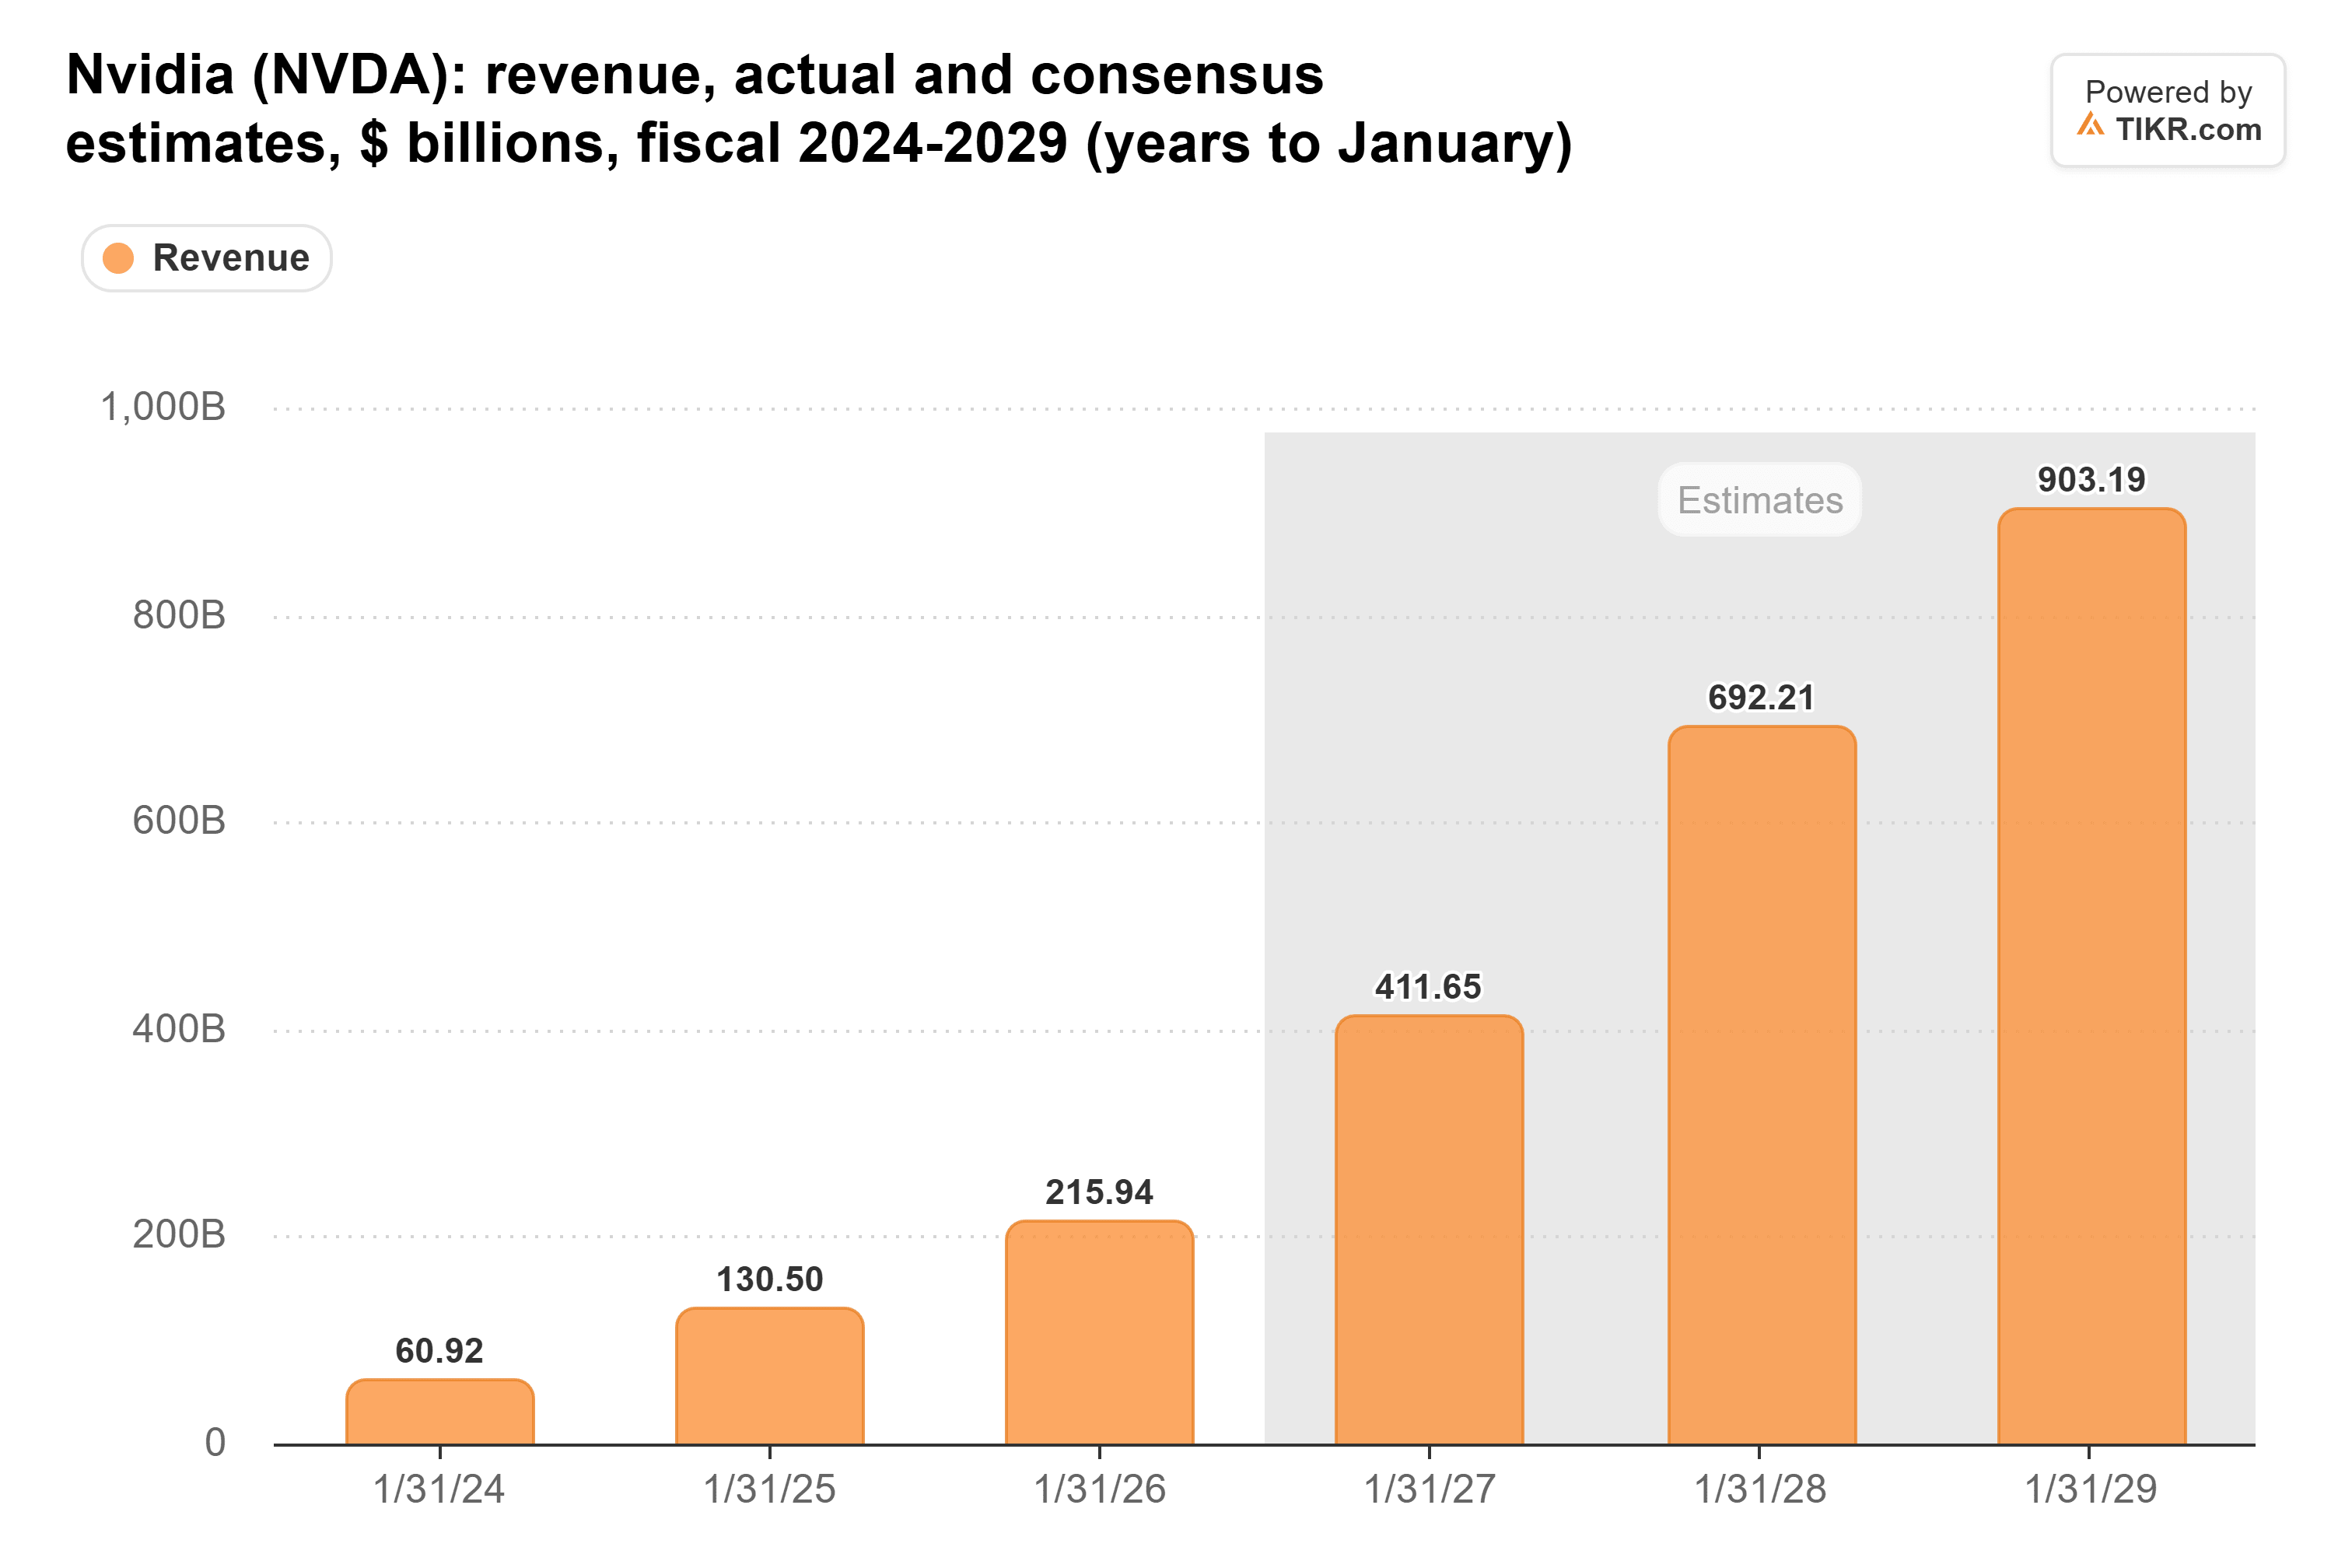
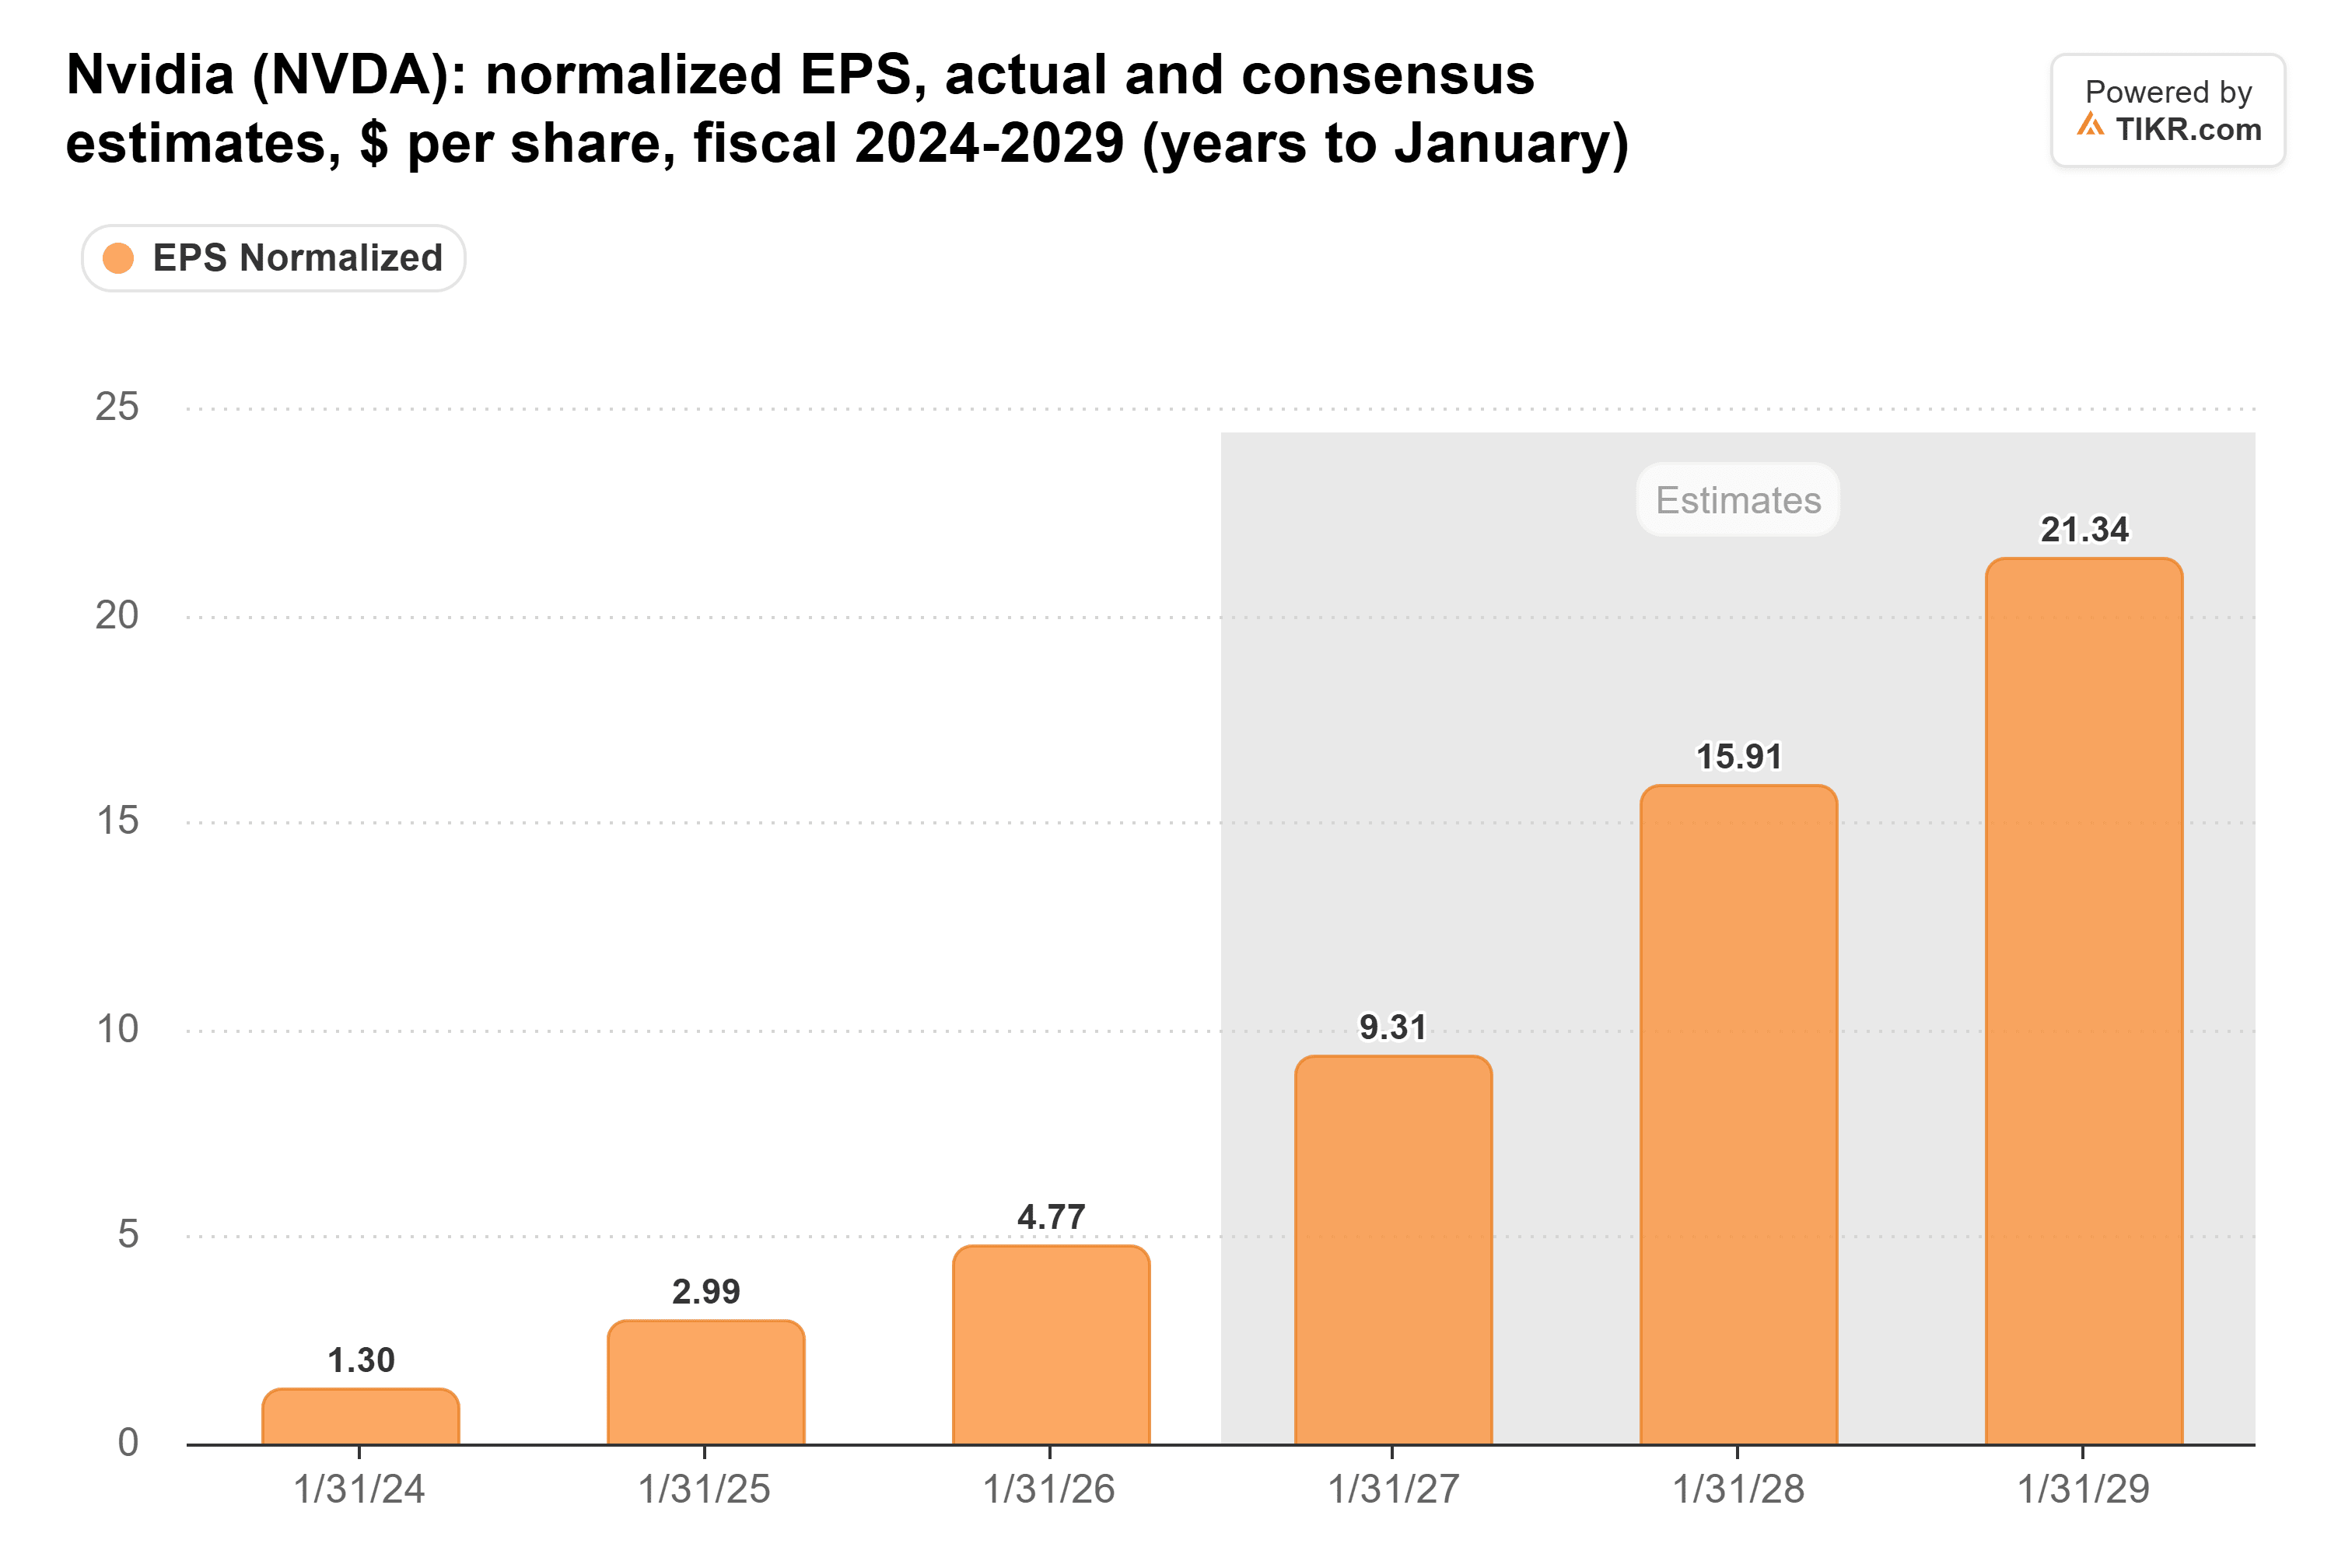
The last bar comes to $1.1 trillion, about five times the $215.9 billion Nvidia sold in the year ended January 2026. Only 8 analysts forecast it, against 57 for the year ending January 2028. Normalized EPS climbs from $4.77 to $25.98 over the same span, a forecast just 4 analysts make.
TIKR Tracks 62 Analysts on Nvidia. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
The Lowest Multiples Come at the Top
Nvidia’s forward P/E fell to 15.4x on Nov. 6, about half its three-year average of 30.1x.
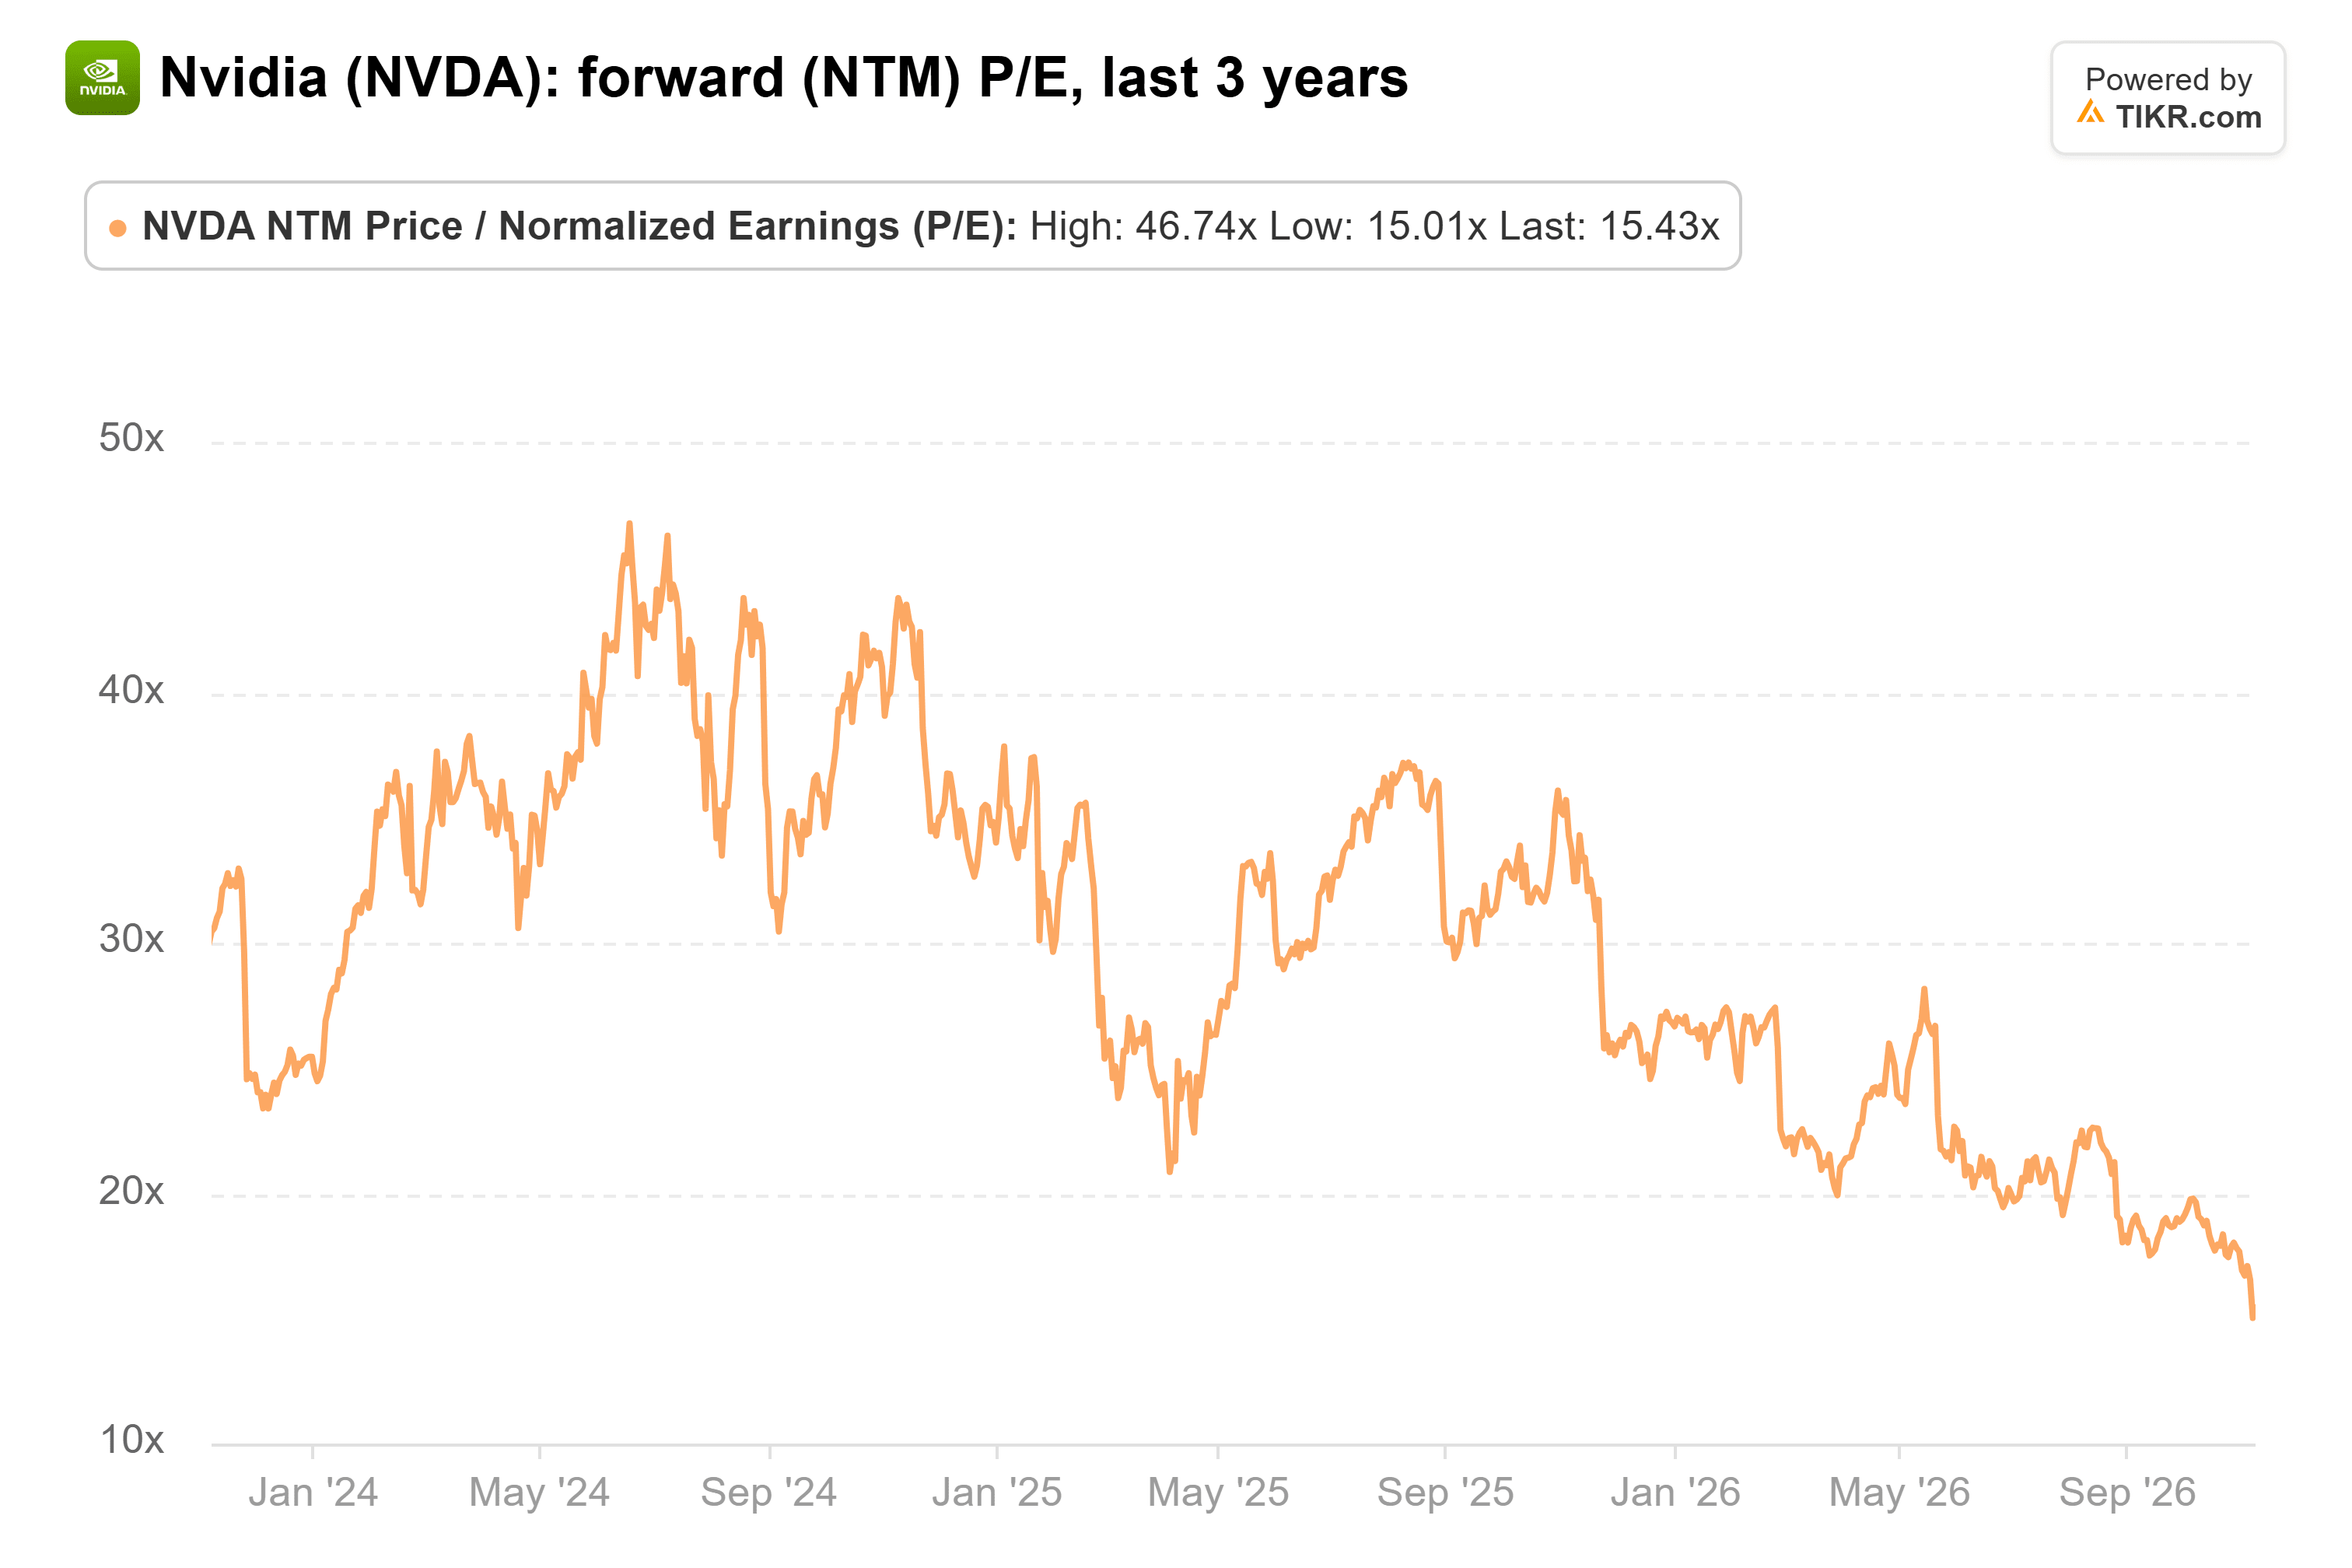
Ed Yardeni of Yardeni Research said of chip stocks on CNBC’s Closing Bell that “the fact that the P.E. has gone down with earnings soaring creates a buying opportunity.” Jim Lebenthal of Cerity Partners told the Halftime Report that “these are multiples that are now expressing sentiment that is simply, in my opinion, far too negative.”
But Yardeni also explained why chip stocks trade this low: “They’re selling as cyclicals.” In his words, “whenever you had very high earnings, that’s when you had your lowest PE.”
Nvidia has been there before. In the year ended January 2023, revenue was flat at $27.0 billion, and operating margin, before the write-off of its abandoned Arm deal, fell to 20.7% from 37.3%. If this cycle peaks within two years, 15x is a multiple on the best earnings Nvidia will report for a while.
Nvidia’s Customers Are Still Spending
On the Aug. 26 call, CFO Colette Kress said top-five hyperscaler capex is expected to reach $1.3 trillion in 2027, with cloud backlog above $2 trillion. She guided revenue for the year ending January 2028 up about 70%, calling it supply-constrained. That year makes up about nine of the next twelve months behind the 15x, so near-term earnings look covered.
The trillion is two years further out, and consensus has growth slowing to 30.5% in the year ending January 2029 and 21.3% the year after. Nvidia has also locked in $279 billion of supply and capacity commitments, with $87 billion due in the year ending January 2028 and $88 billion the year after. That’s a lot of supply to pay for if the build-out slows.
Nvidia’s Nov. 17 Report Is the First Test
Elliott has the better of this argument for now. The next year looks solid, but 15x only stays cheap if earnings keep climbing after it, and I’d want proof the build-out lasts past 2027 before calling Nvidia a bargain.
That proof starts on Nov. 17 with third-quarter results. Revenue guidance is $108.0 billion, plus or minus 2%, and management expects gross margin to bottom at 71% to 72% in the January quarter. Another quarter above the top of its revenue guidance range would make the bears’ case much harder to argue.
So What Is NVIDIA Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!