Key Takeaways
- Upbound jumped 13% on a third-quarter beat as free cash flow more than doubled to about $121 million.
- Acima’s revenue fell 6.5%, but charge-offs and margins improved, and FirstCash’s lease-to-own unit shows the same pattern.
- A soft fourth-quarter guide, a cash target that leaves room for an outflow, and Brigit’s rising losses are the risks.
- Affirm’s and Dave’s reports in early November will show whether the same strain is spreading.
Upbound Group (UPBD) stock jumped 13% today after its third-quarter results beat Wall Street’s estimates. CEO Fahmi Karam said free cash flow “more than doubled year over year, enabling us to further reduce leverage as we build for the future.”
Acima, Upbound’s lease-to-own arm, is getting pickier, and it isn’t alone. FirstCash Holdings (FCFS) is doing the same at its lease-to-own unit. Affirm Holdings (AFRM) says it would rather slow growth than risk credit. Rising losses at Upbound’s Brigit put Dave (DAVE), a cash-advance rival, on watch.
Acima Is Shrinking Into Better Credit
Acima’s revenue fell about 6.5% to $585 million, and its merchandise volume dropped about 11%. But its lease charge-off rate improved 104 basis points to 8.7%, which Upbound credits to “disciplined underwriting,” and its adjusted EBITDA margin widened about 270 basis points to 14.7%.
FirstCash’s American First Finance unit shows the same trade. Its lease and loan volume fell 15% in the third quarter, which it blamed on weak furniture demand and a focus on merchant quality, while net charge-offs improved to 5.6% from 5.8%. So the volume drop isn’t all Upbound’s choice: weak furniture demand is hitting both lenders.
Affirm says it would make the same call. “You would see us slow down growth before you would see us have a real credit disturbance,” CEO Max Levchin said on the company’s Aug. 27 earnings call. With $50.2 billion of gross merchandise volume in the fiscal year to June 30, it hasn’t had to yet. Its Nov. 5 report will tell.
TIKR Tracks 6 Analysts on Upbound Group. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Upbound Group, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Upbound Group’s Analyst Ratings
Cash Is Doing the Work
Upbound’s free cash flow swings from quarter to quarter, but the first half of 2026 ran well ahead of the first half of 2025:
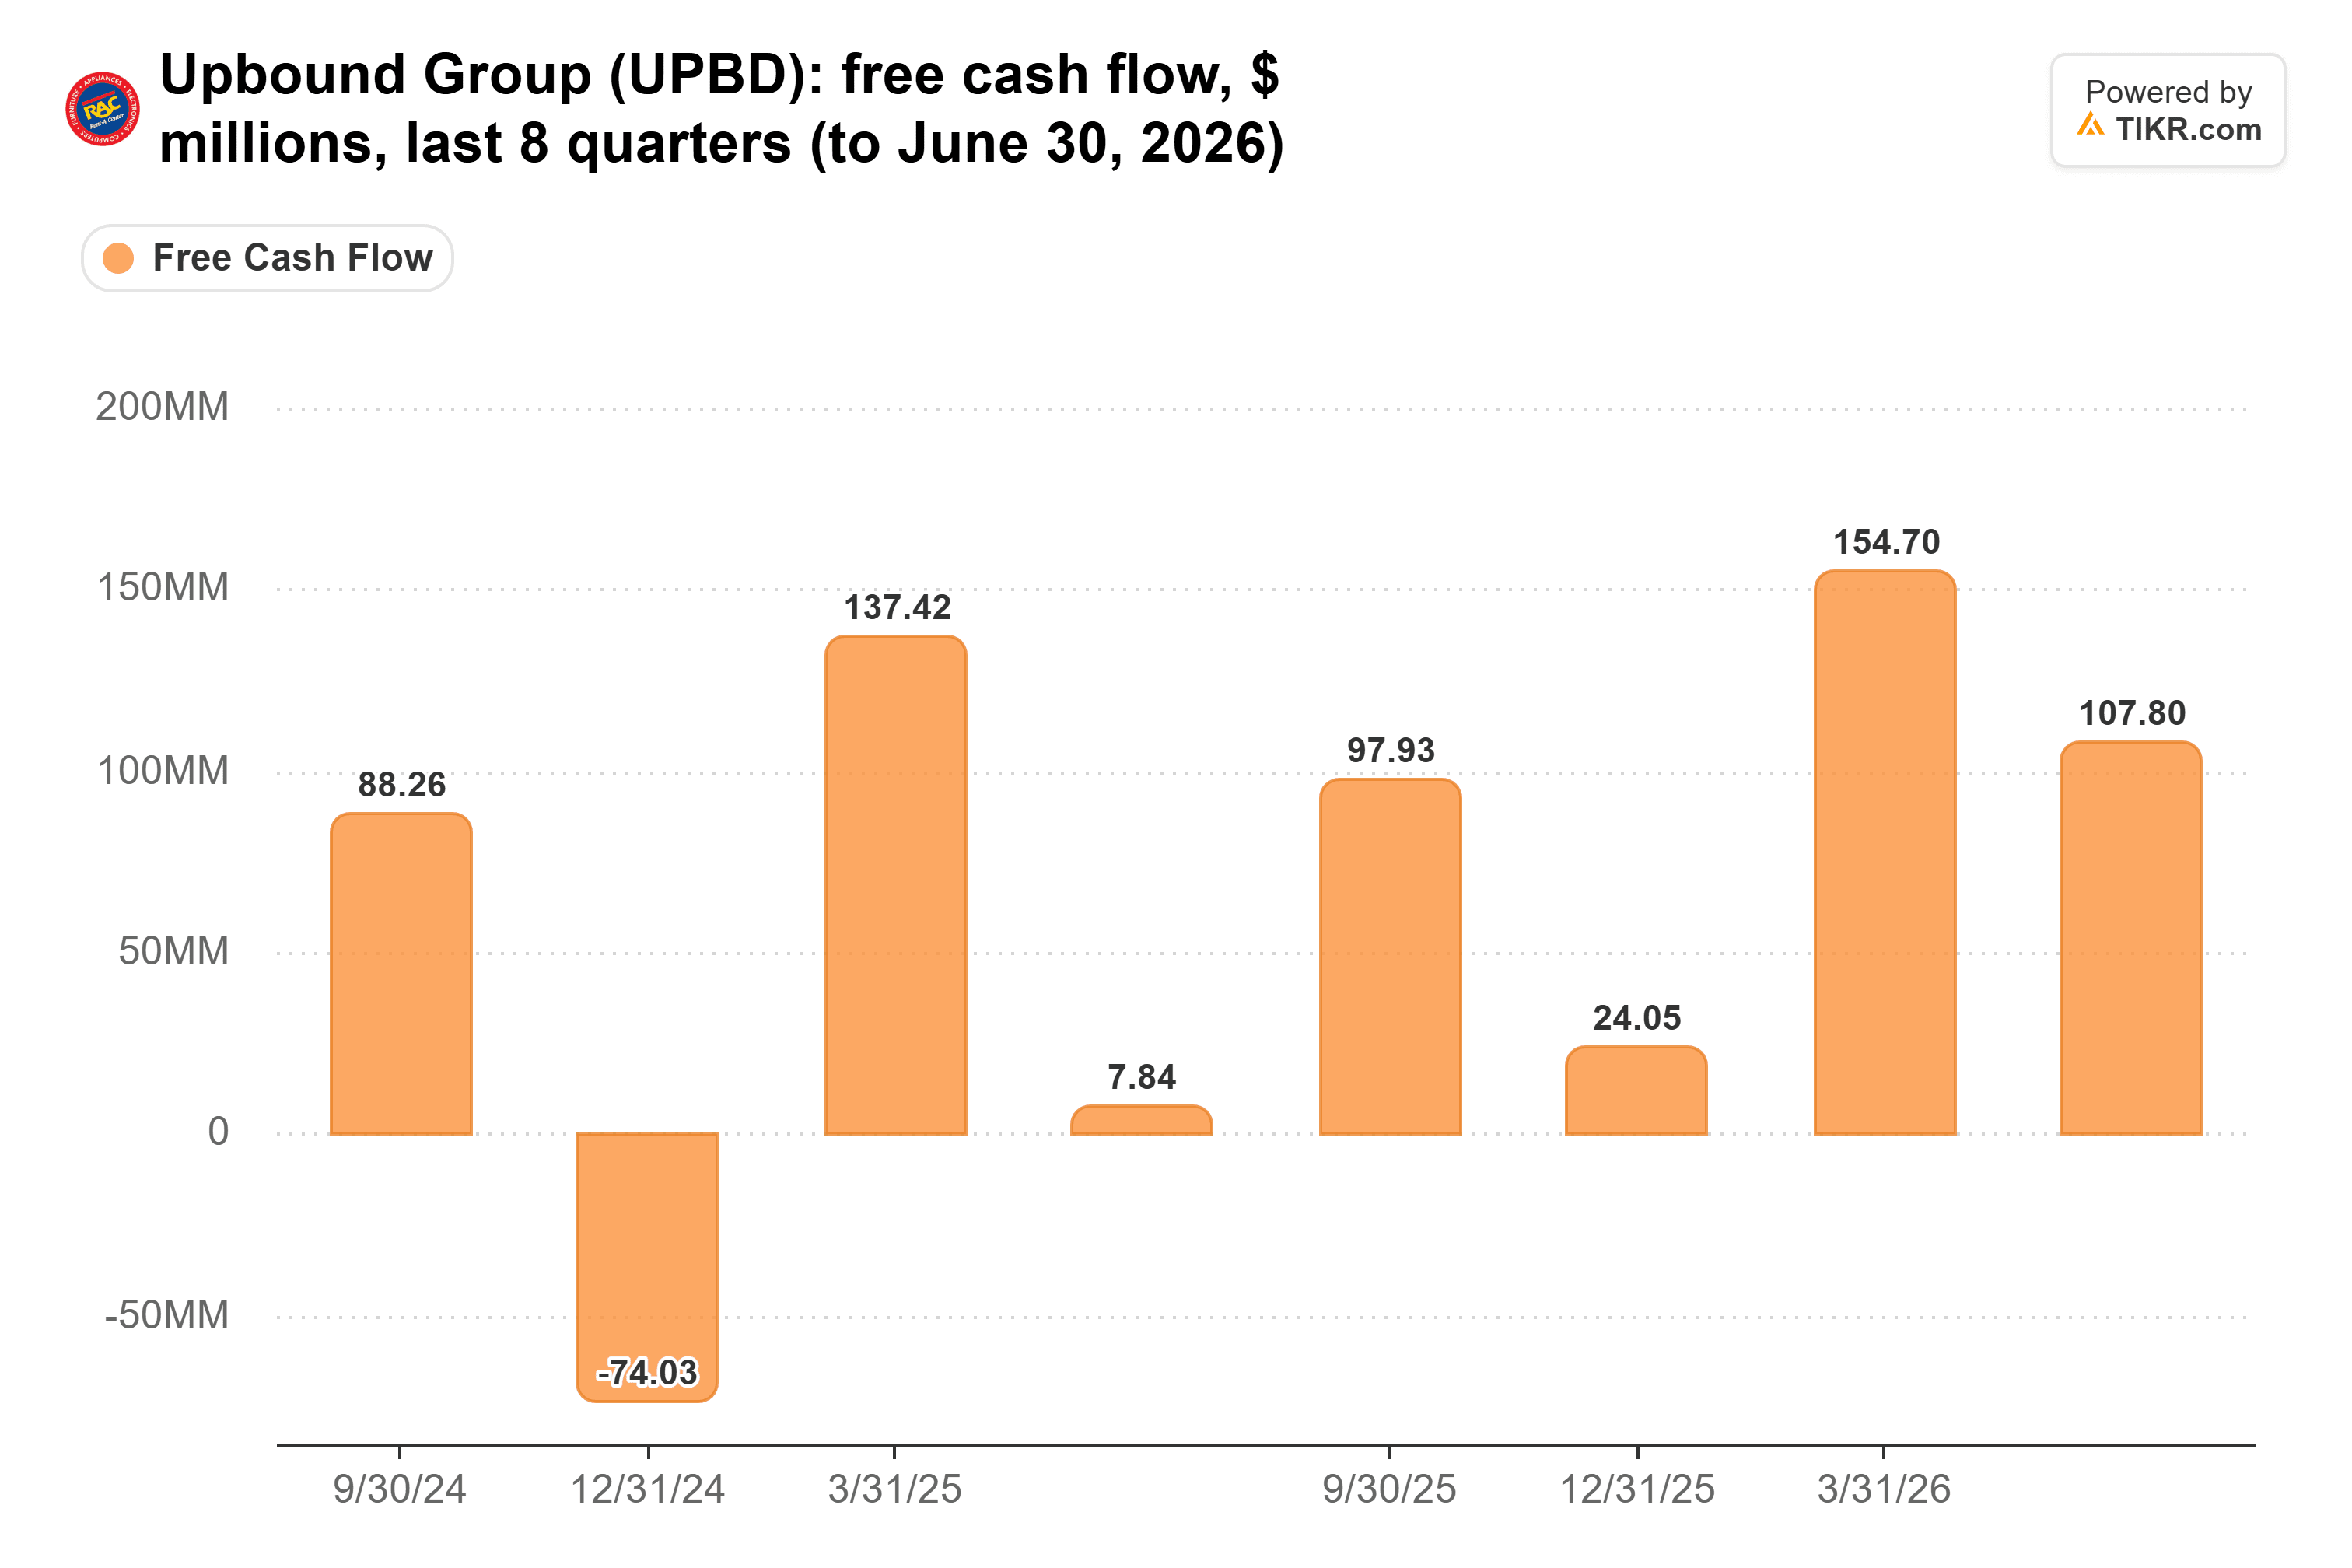
The third quarter added about $121 million by Upbound’s count, bringing the year to about $340 million. It repaid about $77 million of debt, cutting net leverage to 2.4x from 2.6x, and plans to buy back up to $50 million of stock.
But Upbound kept its full-year target at “at least $250 million,” including legal payments. With $340 million already in hand, that leaves room for cash to flow out in the fourth quarter.
Where Upbound Could Still Slip
Fourth-quarter adjusted EPS guidance of $1.00-$1.10 sits below the $1.10 analysts expected. And Brigit’s net advance loss rate rose 111 basis points in a year to 4.4%, which Upbound tied to “strong portfolio growth” in “a challenging macroeconomic environment.”
Dave’s own 28-day past-due rate improved 14 basis points in a year to 2.12% in its second quarter, and its CFO expected losses to hold “in a similar range to Q2.” Its Nov. 4 report will be another check on how cash-advance borrowers are holding up, though the two companies measure losses differently.
Giving up volume for cleaner credit has paid off: Acima is earning more on less, and the debt is coming down. But FirstCash’s numbers show weak demand is doing some of the shrinking. Acima’s new deal to be the preferred lease-to-own option in about 5,000 Boost Mobile stores is the first real test of whether volume can come back without the losses.
So What is Upbound Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Upbound could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!