Key Takeaways
- Uber Technologies (UBER) has fallen approximately 26% over the past year, but Citi analyst Ronald Josey’s $105 price target implies nearly 52% upside from its November 12 closing price of $69.12.
- Amazon (AMZN) recently partnered with Uber Eats to offer qualifying U.S. Prime members $0 delivery fees, potentially expanding Uber’s delivery reach.
- Analysts expect Uber’s normalized EPS to increase from $2.45 in 2025 to $5.50 in 2028, although driver shortages, rising debt, and autonomous-vehicle competition remain risks.
- Uber traded near 17x forward earnings on November 10, below its three-year average of approximately 25x, suggesting potential undervaluation if projected earnings growth materializes.
What Happened?
Uber Technologies (UBER) has declined approximately 26% over the past year, but Citi sees significant recovery potential.
Citi analyst Ronald Josey resumed coverage on November 6 with a Buy rating and a $105 price target, implying approximately 52% upside from Uber’s November 12 closing price of $69.12.
Citi’s bullish outlook reflects Uber’s autonomous-vehicle strategy, 55 million Uber One members, improving driver availability, and expanding delivery opportunities.
However, Uber’s third-quarter earnings highlighted several challenges.
Mobility revenue declined 2% year over year to $7.5 billion, despite an 18% increase in Mobility gross bookings. Business model changes weighed on reported revenue growth, while driver shortages constrained performance in several international markets.
Meanwhile, long-term debt increased from $10.5 billion at the end of 2025 to $15.7 billion by September 2026.
Uber also announced a $14.8 billion cash takeover offer for Delivery Hero in July, raising questions about financing requirements and integration risks. The proposed transaction is expected to close in the second half of 2027, subject to conditions.
Autonomous-vehicle competition remains another concern, particularly as robotaxi operators expand their fleets and develop direct relationships with riders.
Despite these challenges, CEO Dara Khosrowshahi highlighted Uber’s “fifth consecutive quarter of 20%+ Gross Bookings growth” in its third-quarter earnings announcement.
Analysts also project normalized EPS will more than double from $2.45 in 2025 to $5.50 in 2028, according to TIKR estimates.
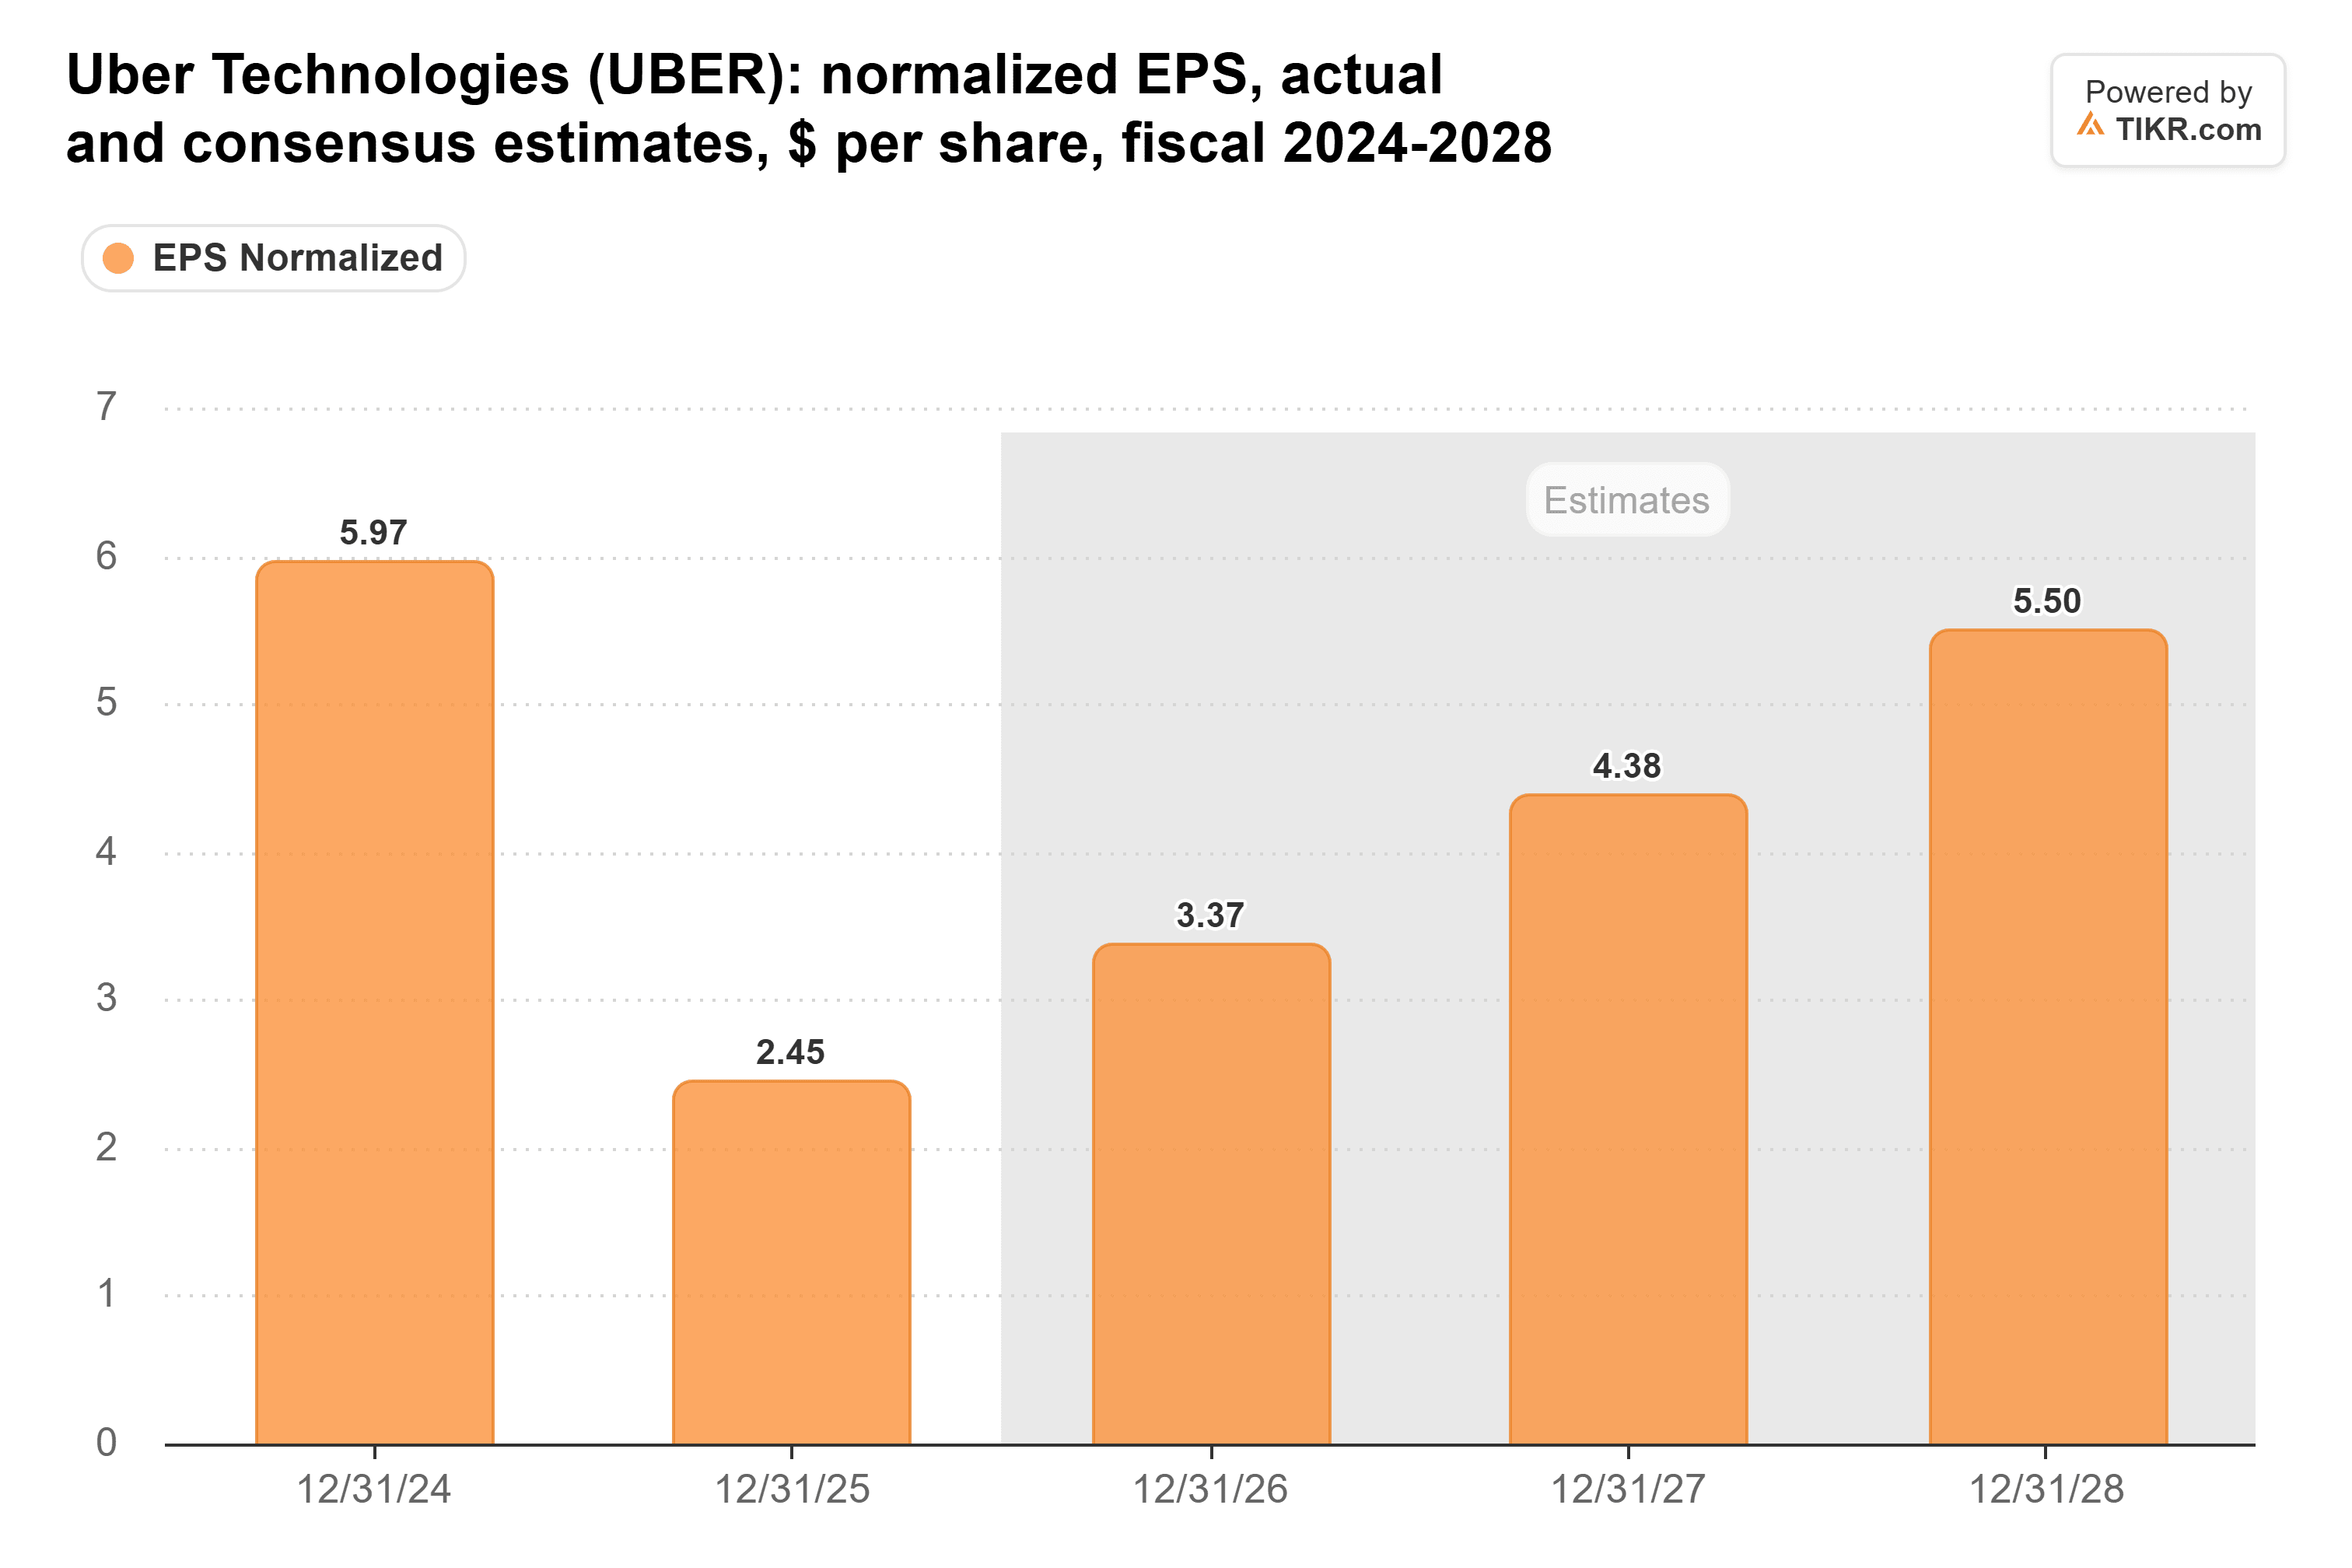
However, the fiscal 2027 consensus estimate has edged lower to $4.38, suggesting some moderation in near-term earnings expectations.
Is Uber Stock Undervalued or Overvalued?
Uber traded at approximately 17x forward earnings on November 10, compared with three-year and one-year averages of roughly 25x and 21x, respectively, based on earlier TIKR valuation data.
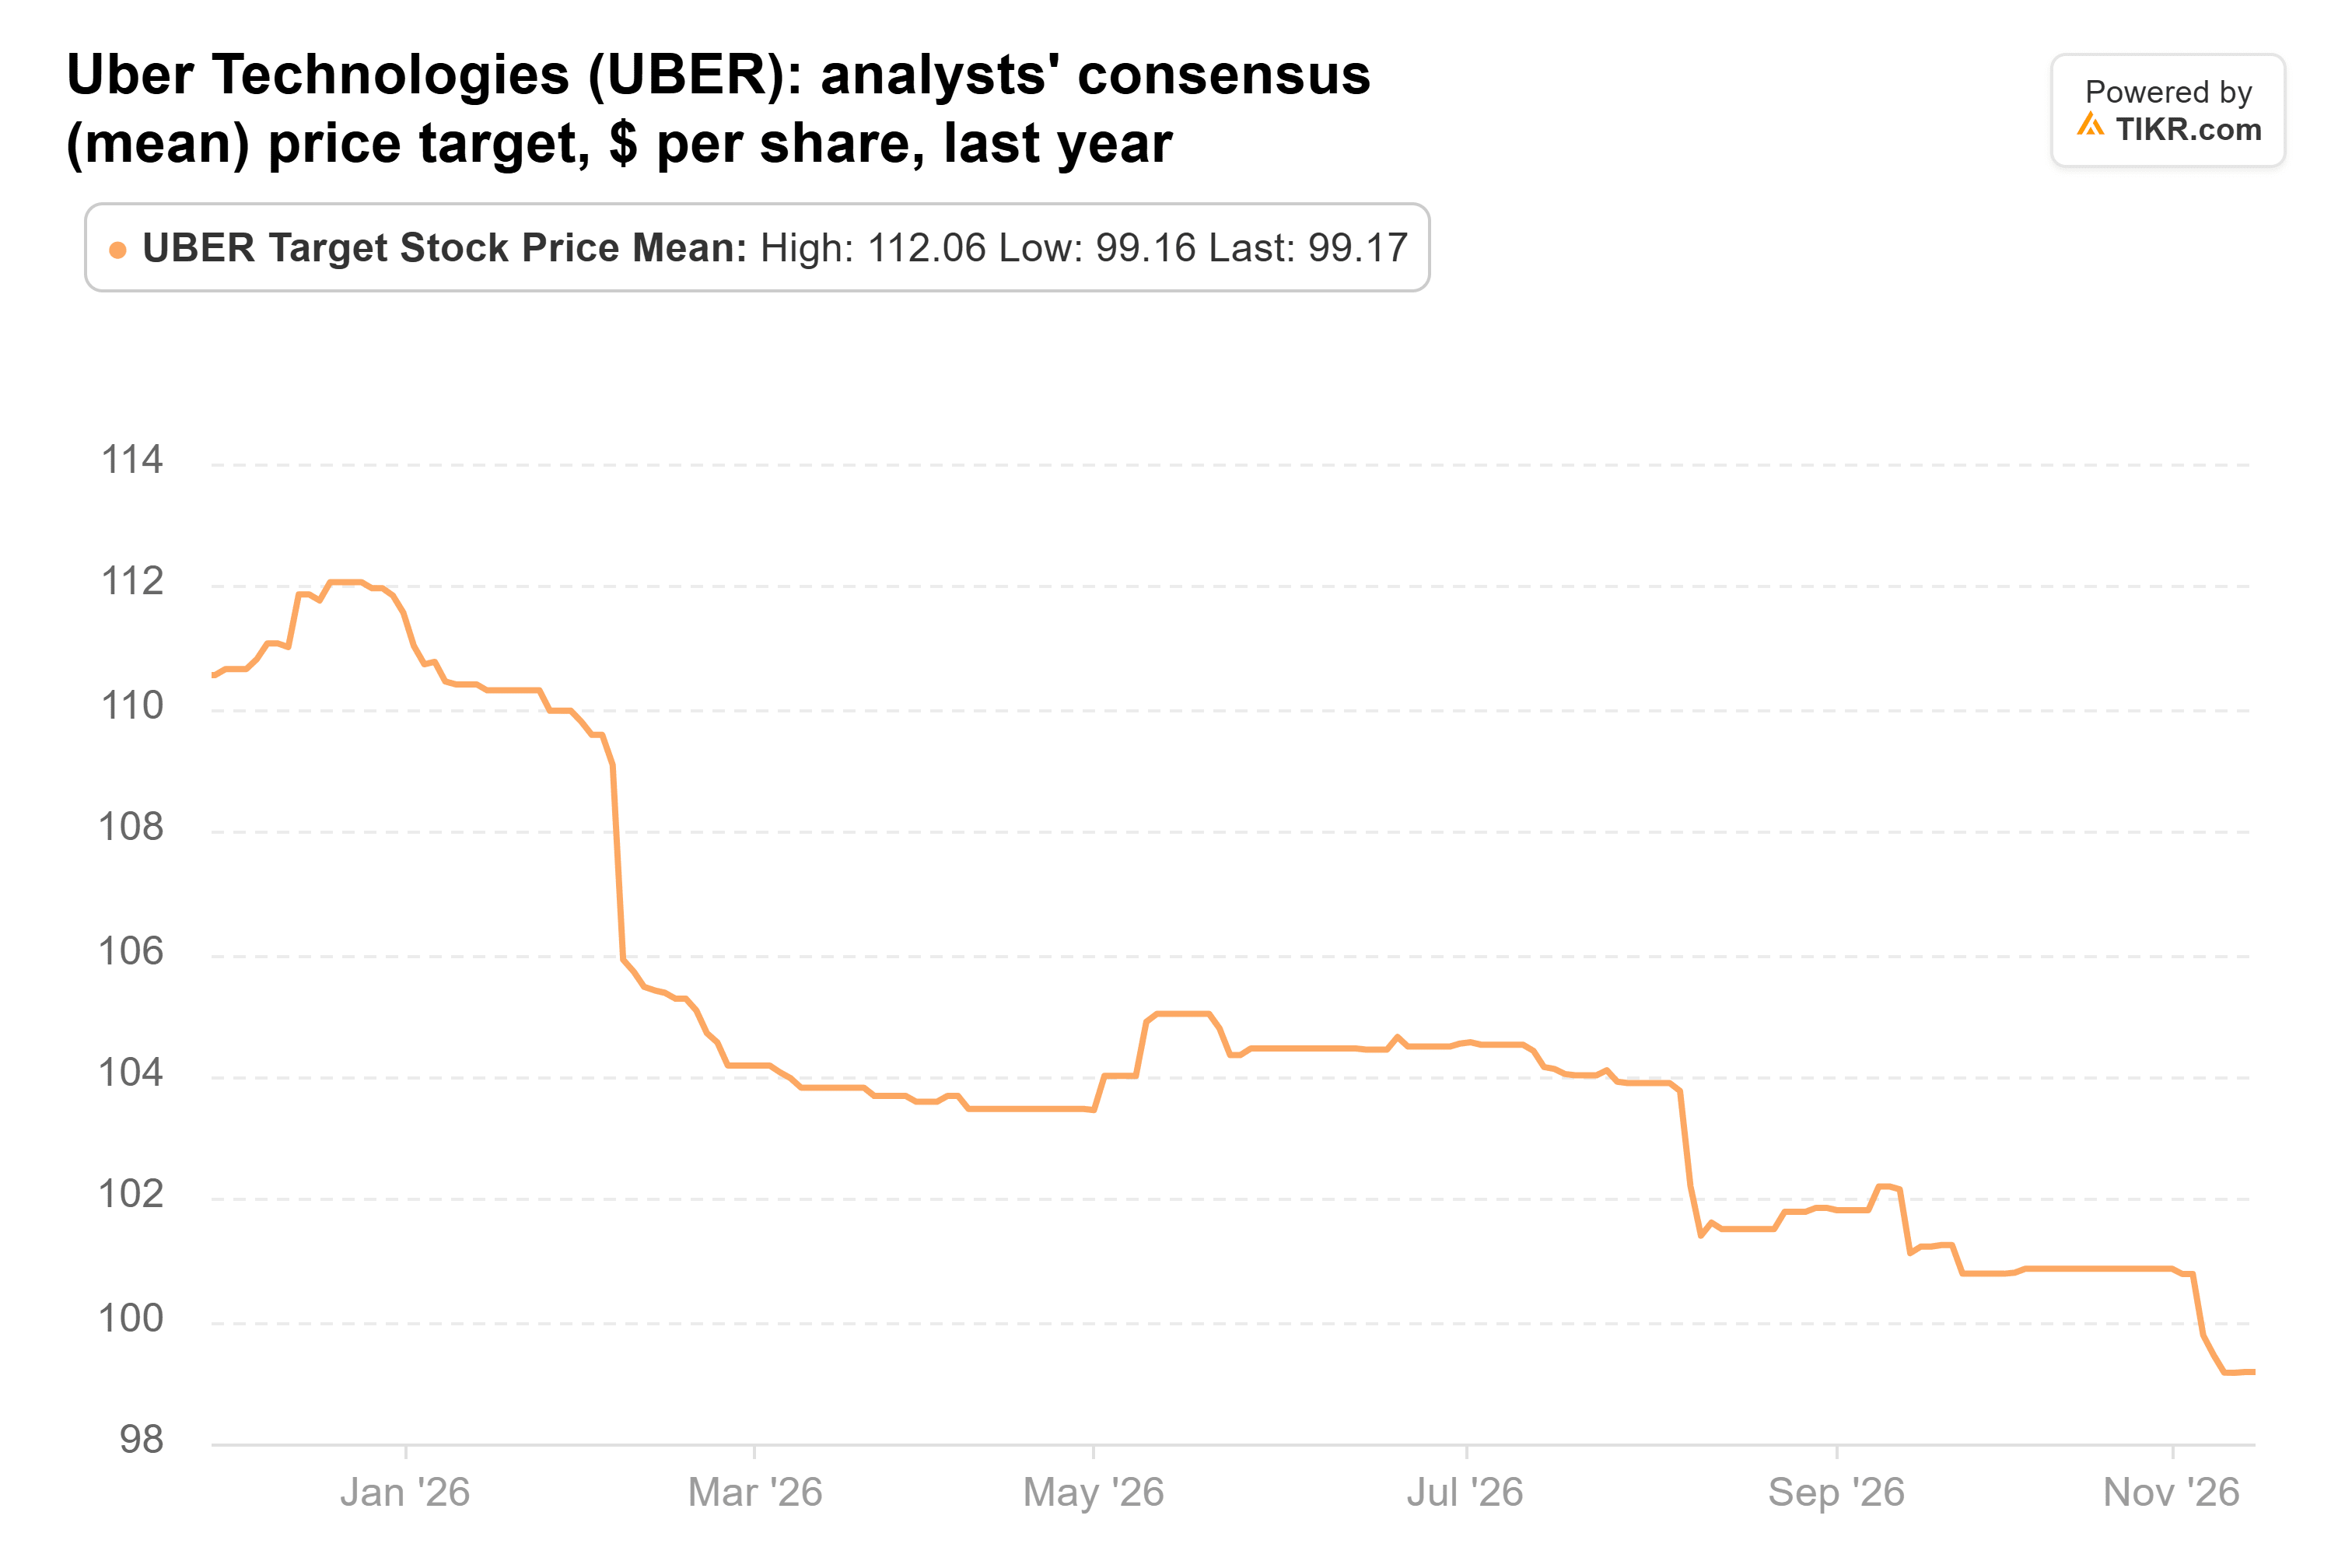
Wall Street’s average price target of approximately $99, according to November 10 TIKR data, implies roughly 43% upside from Uber’s November 12 closing price. The consensus target has declined from approximately $111 over the preceding year.
Citi’s $105 target implies approximately 26x next-twelve-month earnings using TIKR’s $4.08 EPS estimate. Reaching that target would therefore require meaningful valuation expansion alongside earnings growth.
Uber’s growth drivers include 55 million Uber One members and a new partnership with Amazon (AMZN) offering qualifying U.S. Prime members $0 delivery fees on restaurant orders of $25 or more placed through Amazon.
The partnership announced November 5 enables Prime members to order through Amazon’s website and shopping app, potentially supporting additional delivery demand.
Uber also expects approximately 700 fully driverless vehicles on its network by year-end, while fourth-quarter non-GAAP EPS guidance of $0.95 to $0.99 represents projected annual growth of 34% to 39%.
Over the next 12 months, continued bookings growth, improving driver supply, delivery profitability, and successful autonomous deployment could strengthen Uber’s earnings outlook.
Uber appears potentially undervalued at its current earnings multiple, but Citi’s 52% upside forecast looks optimistic over the next 12 months. Stronger earnings and improving investor confidence could support a recovery, while robotaxi competition, rising costs, and execution risks could limit gains.
So what is Uber stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Uber could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!