Key Takeaways
- NVIDIA stock is 47% below its October high, even after a beat-and-raise quarter and higher earnings estimates.
- Gene Munster compares NVIDIA to Apple in 2012, and he’s right that better fundamentals alone won’t end the selloff.
- At 8.7x forward earnings, NVIDIA trades below Apple’s 2013 bottom, but a reported US accounting probe gives buyers a reason to wait.
- Broadcom’s custom AI chips and NVIDIA’s lower margin outlook are the other overhangs, starting with Broadcom’s Dec. 9 report.
NVIDIA (NVDA) beat expectations and raised its outlook on Nov. 17. Then it had its worst week in nearly 20 years.
Gene Munster, managing partner at Deepwater Asset Management, has seen a selloff like this before. He covered Apple (AAPL) at Piper Jaffray back then, and on Friday he wrote in a post on X:
“I had a flashback to 2012 when $AAPL was down big and am reminded that the selloff does not end when fundamentals improve, rather when the buyers return.”
One investor on X laid out the parallel. In 2013, he wrote, the fear was that cheap Android phones would wreck Apple’s margins. Today the fear is that custom chips, like the ones Broadcom (AVGO) designs for the biggest AI buyers, will do the same to NVIDIA’s.
Analysts keep raising the numbers
TIKR’s data shows the first half of Munster’s point plainly. Analysts expect NVIDIA to earn more every year through January 2030:
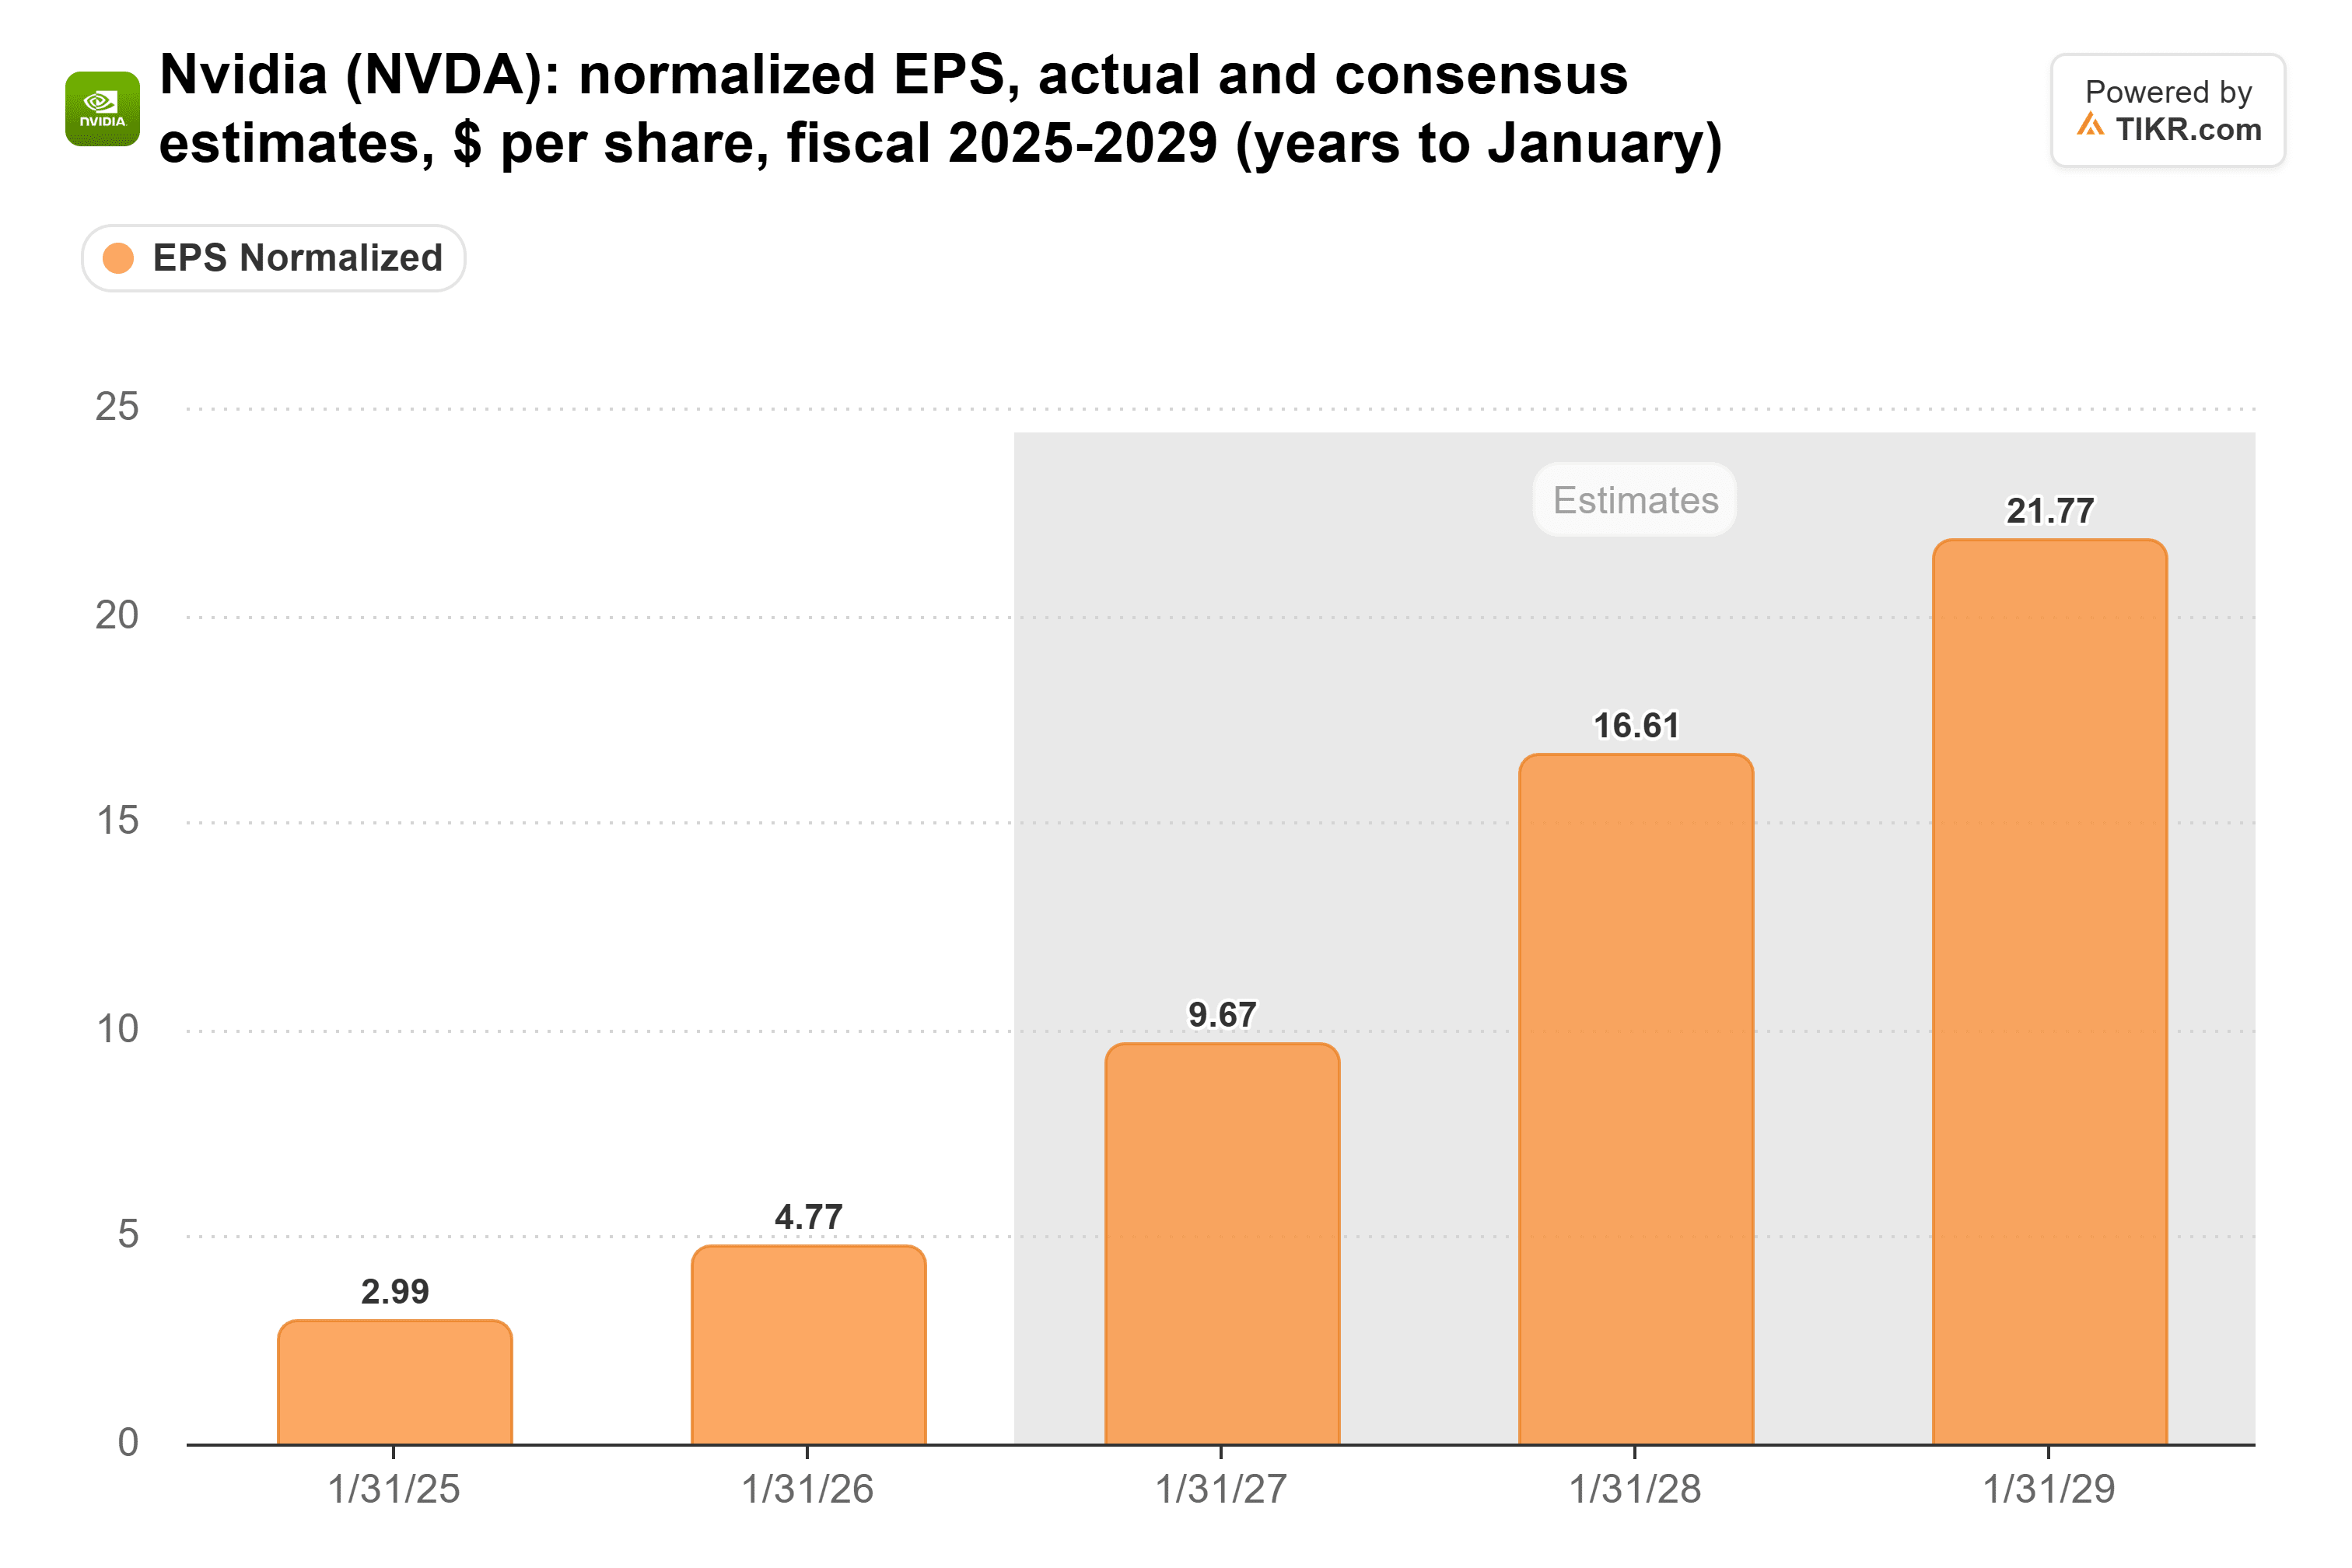
The consensus for normalized EPS in the year ending January 2028 is now $16.61 a share, up from $15.92 in late October.
One investor in r/ValueInvesting found that from Sept. 9 to Nov. 18, consensus EPS for the year to January 2028 rose 2.6%. Over the same stretch, the stock fell 33%.
TIKR tracks 63 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Already cheaper than Apple’s bottom
Rising estimates and a falling price have crushed NVIDIA’s forward P/E:
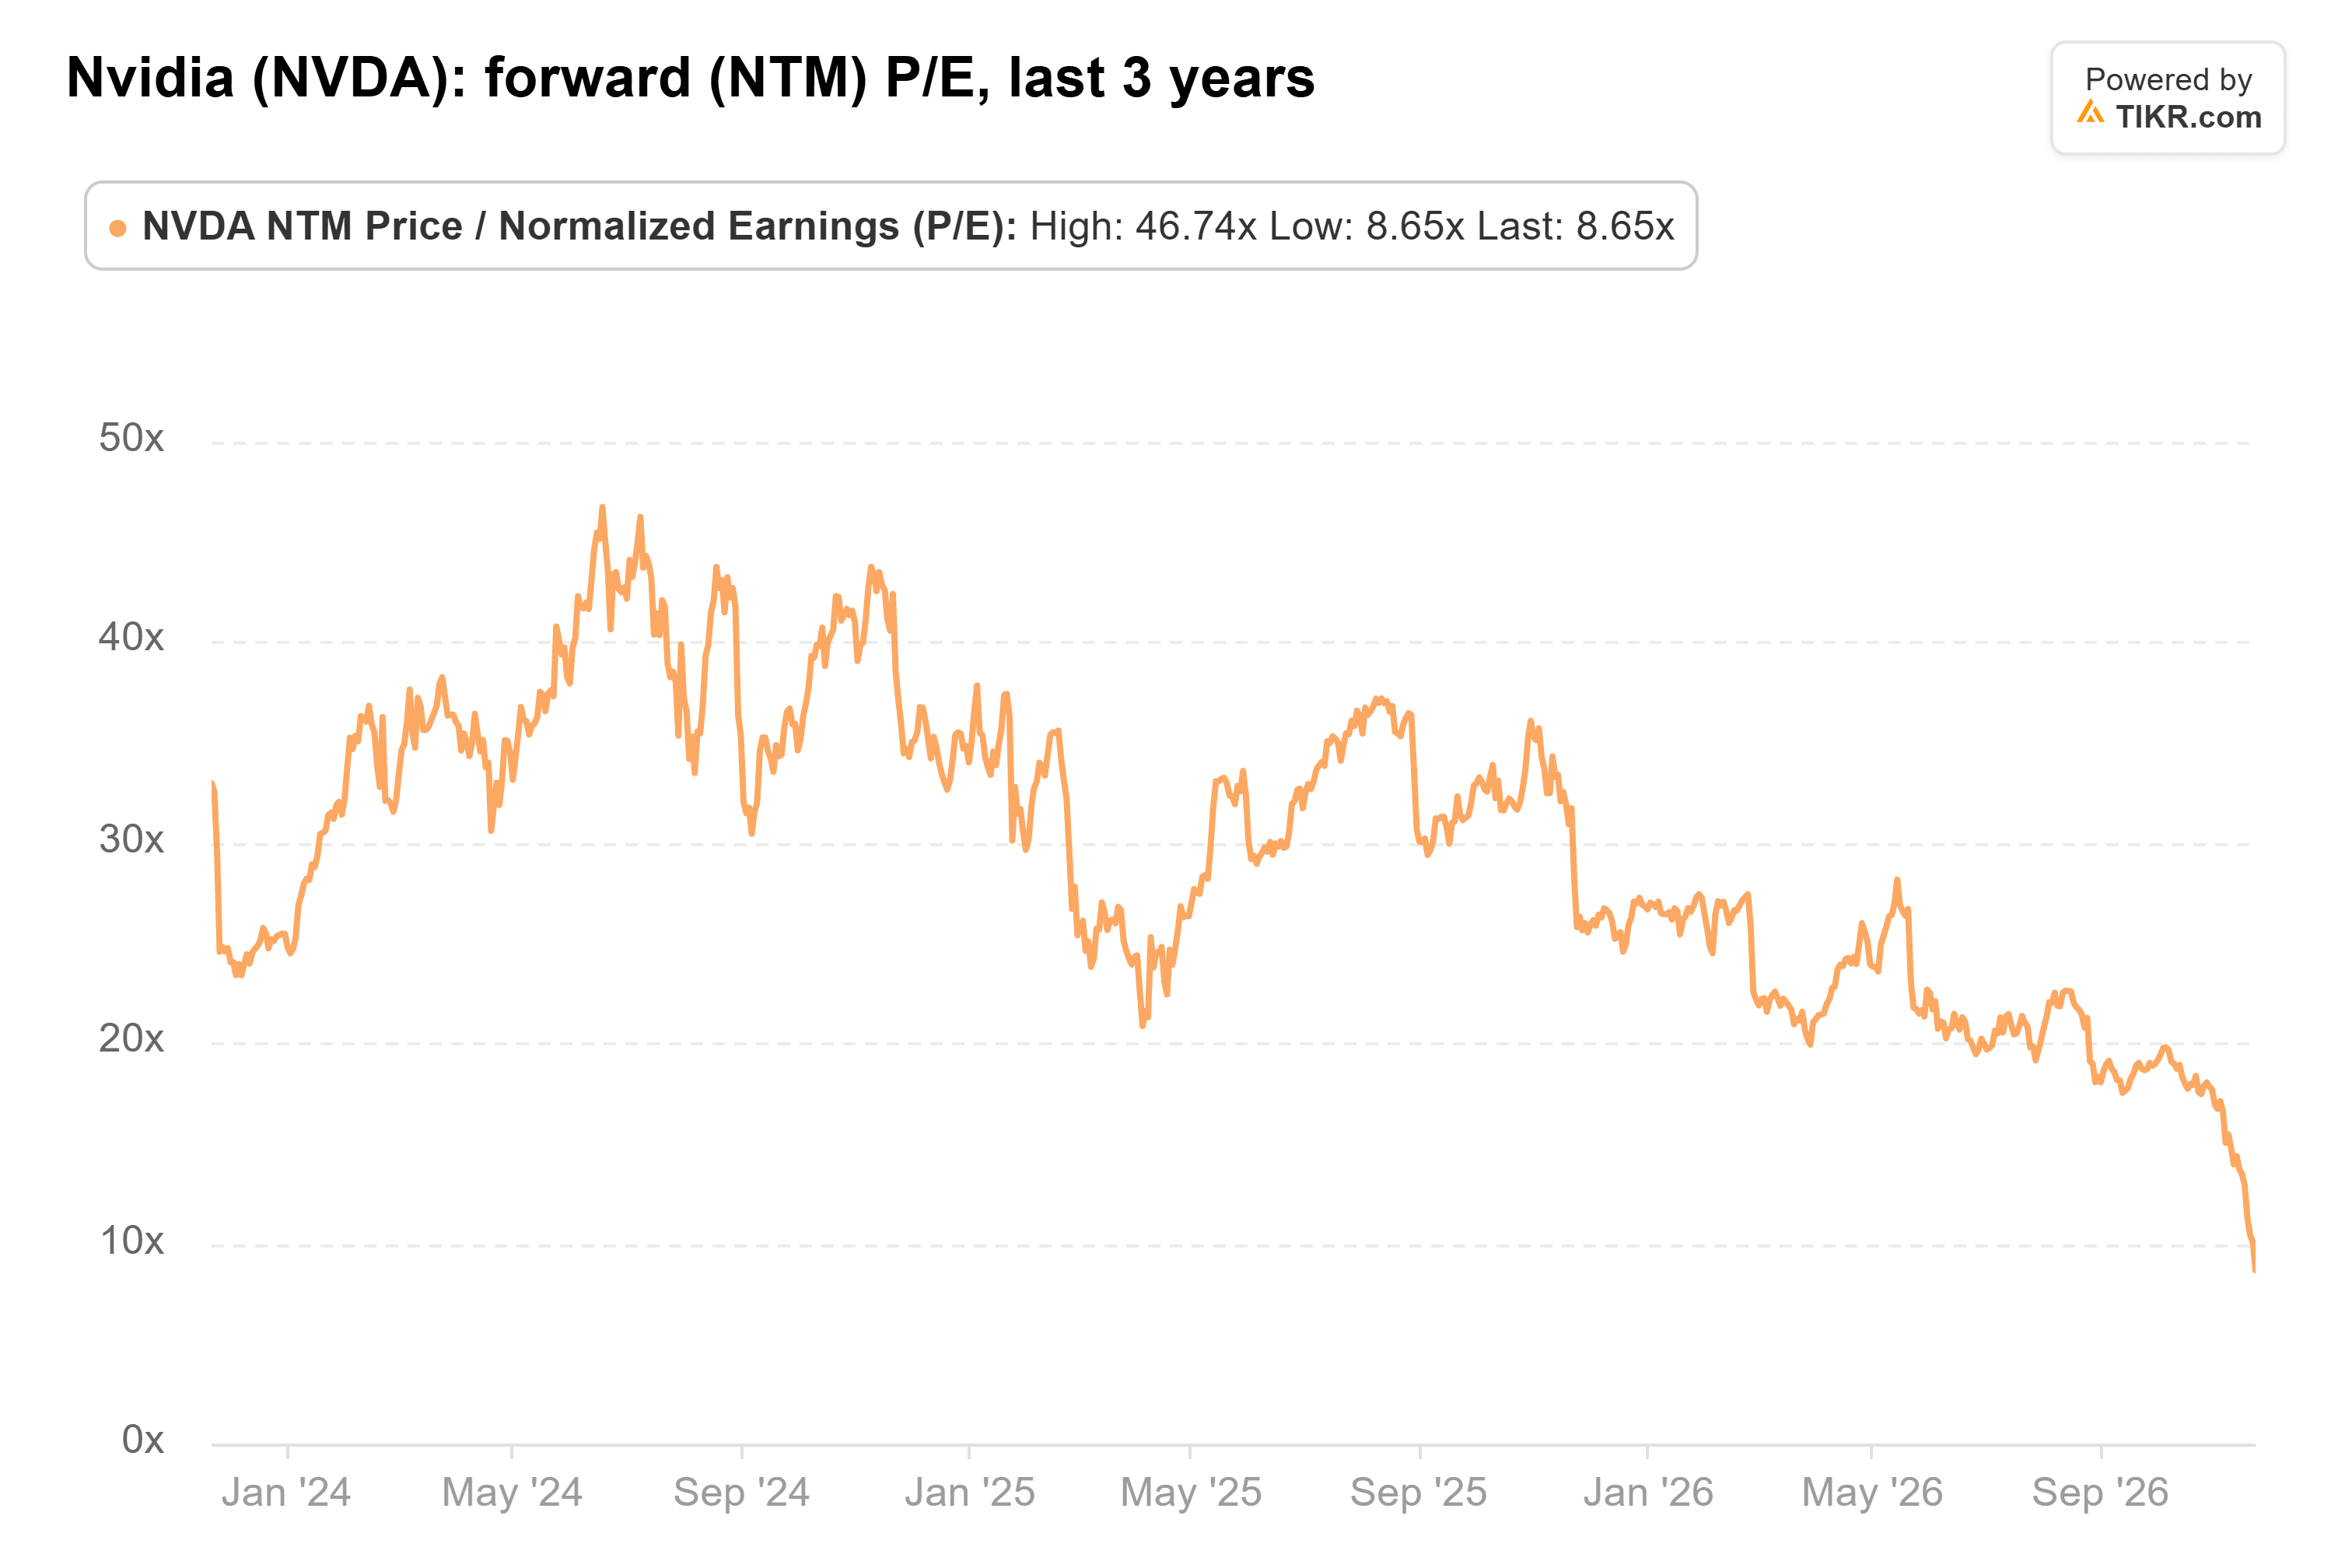
At 8.7x, NVIDIA trades at its lowest forward P/E of the past three years. Its three-year average is 30x. The investor on X puts Apple’s 2013 bottom at 9.4x earnings. So on valuation, NVIDIA has already fallen further than Apple did.
Analysts’ price targets haven’t pointed the way back, though. The average target has been cut sharply:

The average target is now $244.18, down 26% from $328.95 on Oct. 23, even though estimates rose over the same period. The r/ValueInvesting poster thinks analysts are “just chasing the price.” That’s Munster’s point from another angle: analysts move their targets after the buyers move the stock.
NVIDIA’s overhang goes beyond margins
Apple’s worry in 2013 was margins, and NVIDIA has its own version of that. Broadcom’s AI chip revenue grew 221% to $16.7 billion in its quarter ended Aug. 2. NVIDIA’s data center revenue grew 117% to $89.0 billion in its quarter ended July 26. NVIDIA also said in August that it expects its gross margin to bottom at 71%-72% in the January quarter as memory prices climb, down from 75.0% in the July quarter.
NVIDIA’s biggest new problem is a reported US probe into its accounting. The quarterly filing that would detail its receivables and guarantees has reportedly been held up by the probe. Those receivables had already climbed to $63.1 billion by July 26, from $38.5 billion in January.
Buyers can’t put a number on an open probe, so they have every reason to wait, however low the multiple goes.
What brings the buyers back
I think NVIDIA is already priced the way Apple was at its low. What’s missing is the buyers, and I don’t expect them back in force until the accounting probe has an answer.
The next tests come quickly. Broadcom reports on Dec. 9, against its $21.7 billion AI guide. Then there’s the filing that’s reportedly delayed. NVIDIA reports again in late February, and a gross margin at or above 71% would show it has memory costs under control.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!