Key Takeaways
- TD Cowen raised its Walmart price target to $147 from $125 and kept its Buy rating after a beat-and-raise quarter.
- The firm expects fast e-commerce growth to lift margins, and at least eight other firms raised targets the same day.
- Walmart trades at about 43x forward earnings, against 17x for Target and 48x for Costco, and $147 needs that premium to hold for another year.
- $147 looks like Walmart’s bull case, and the new mid-$130s targets look like the likelier landing.
Walmart (WMT) rose 1.5% to $127.95 on Friday, Nov. 20, while the Nasdaq fell 5.3%, a day after it beat its own guidance and raised its outlook again. TD Cowen lifted its price target to $147 from $125, 15% above Friday’s close, and kept a Buy rating.
Target (TGT) posted 5.6% comparable sales growth in its own third quarter, and Walmart’s new $120 bundle of Walmart+ and Sam’s Club Plus goes after the warehouse shopper Costco (COST) counts on.
A Beat, a Raise and a New Bundle
In the quarter to Oct. 31, adjusted EPS came in at $0.65, above Walmart’s $0.62 to $0.64 guide, and adjusted operating income grew 5.5% in constant currency against a 2% to 4% guide. Full-year adjusted EPS guidance went to $2.84-$2.89 from $2.80-$2.87, its second raise this year.
Walmart U.S. comparable sales rose 2.9% excluding fuel, and Sam’s Club’s rose 4.9%. CEO John Furner said Sam’s has seen “a couple million new members come in and shop” since the bundle launched.
TD Cowen Is Betting on Walmart’s E-Commerce Margins
TD Cowen’s Max Rakhlenko said Walmart’s e-commerce kept accelerating with stronger incremental margins, and he expects more “outsized” growth to lift margins. CFO John David Rainey put U.S. e-commerce incremental margins at over 12% in the quarter.
The new target takes TD Cowen most of the way back to the $150 it had before it cut to $125 after the stock fell on Walmart’s August report. At least eight other firms, including Morgan Stanley, BofA and Jefferies, also raised targets on Friday, to between $135 and $145. The $132 consensus target, 3% above the price and set before the report, is still below its June peak of $139.

Does $147 Add Up?
Analysts expect normalized EPS to climb from $2.64 last year to $3.62 in the year ending January 2029.

By my math, $147 is about 41x those earnings, a touch below today’s 43x forward multiple. So the target doesn’t need a higher multiple. At today’s multiple, it needs next-12-month EPS of about $3.44 a year from now, up 15% from today’s $3.00.
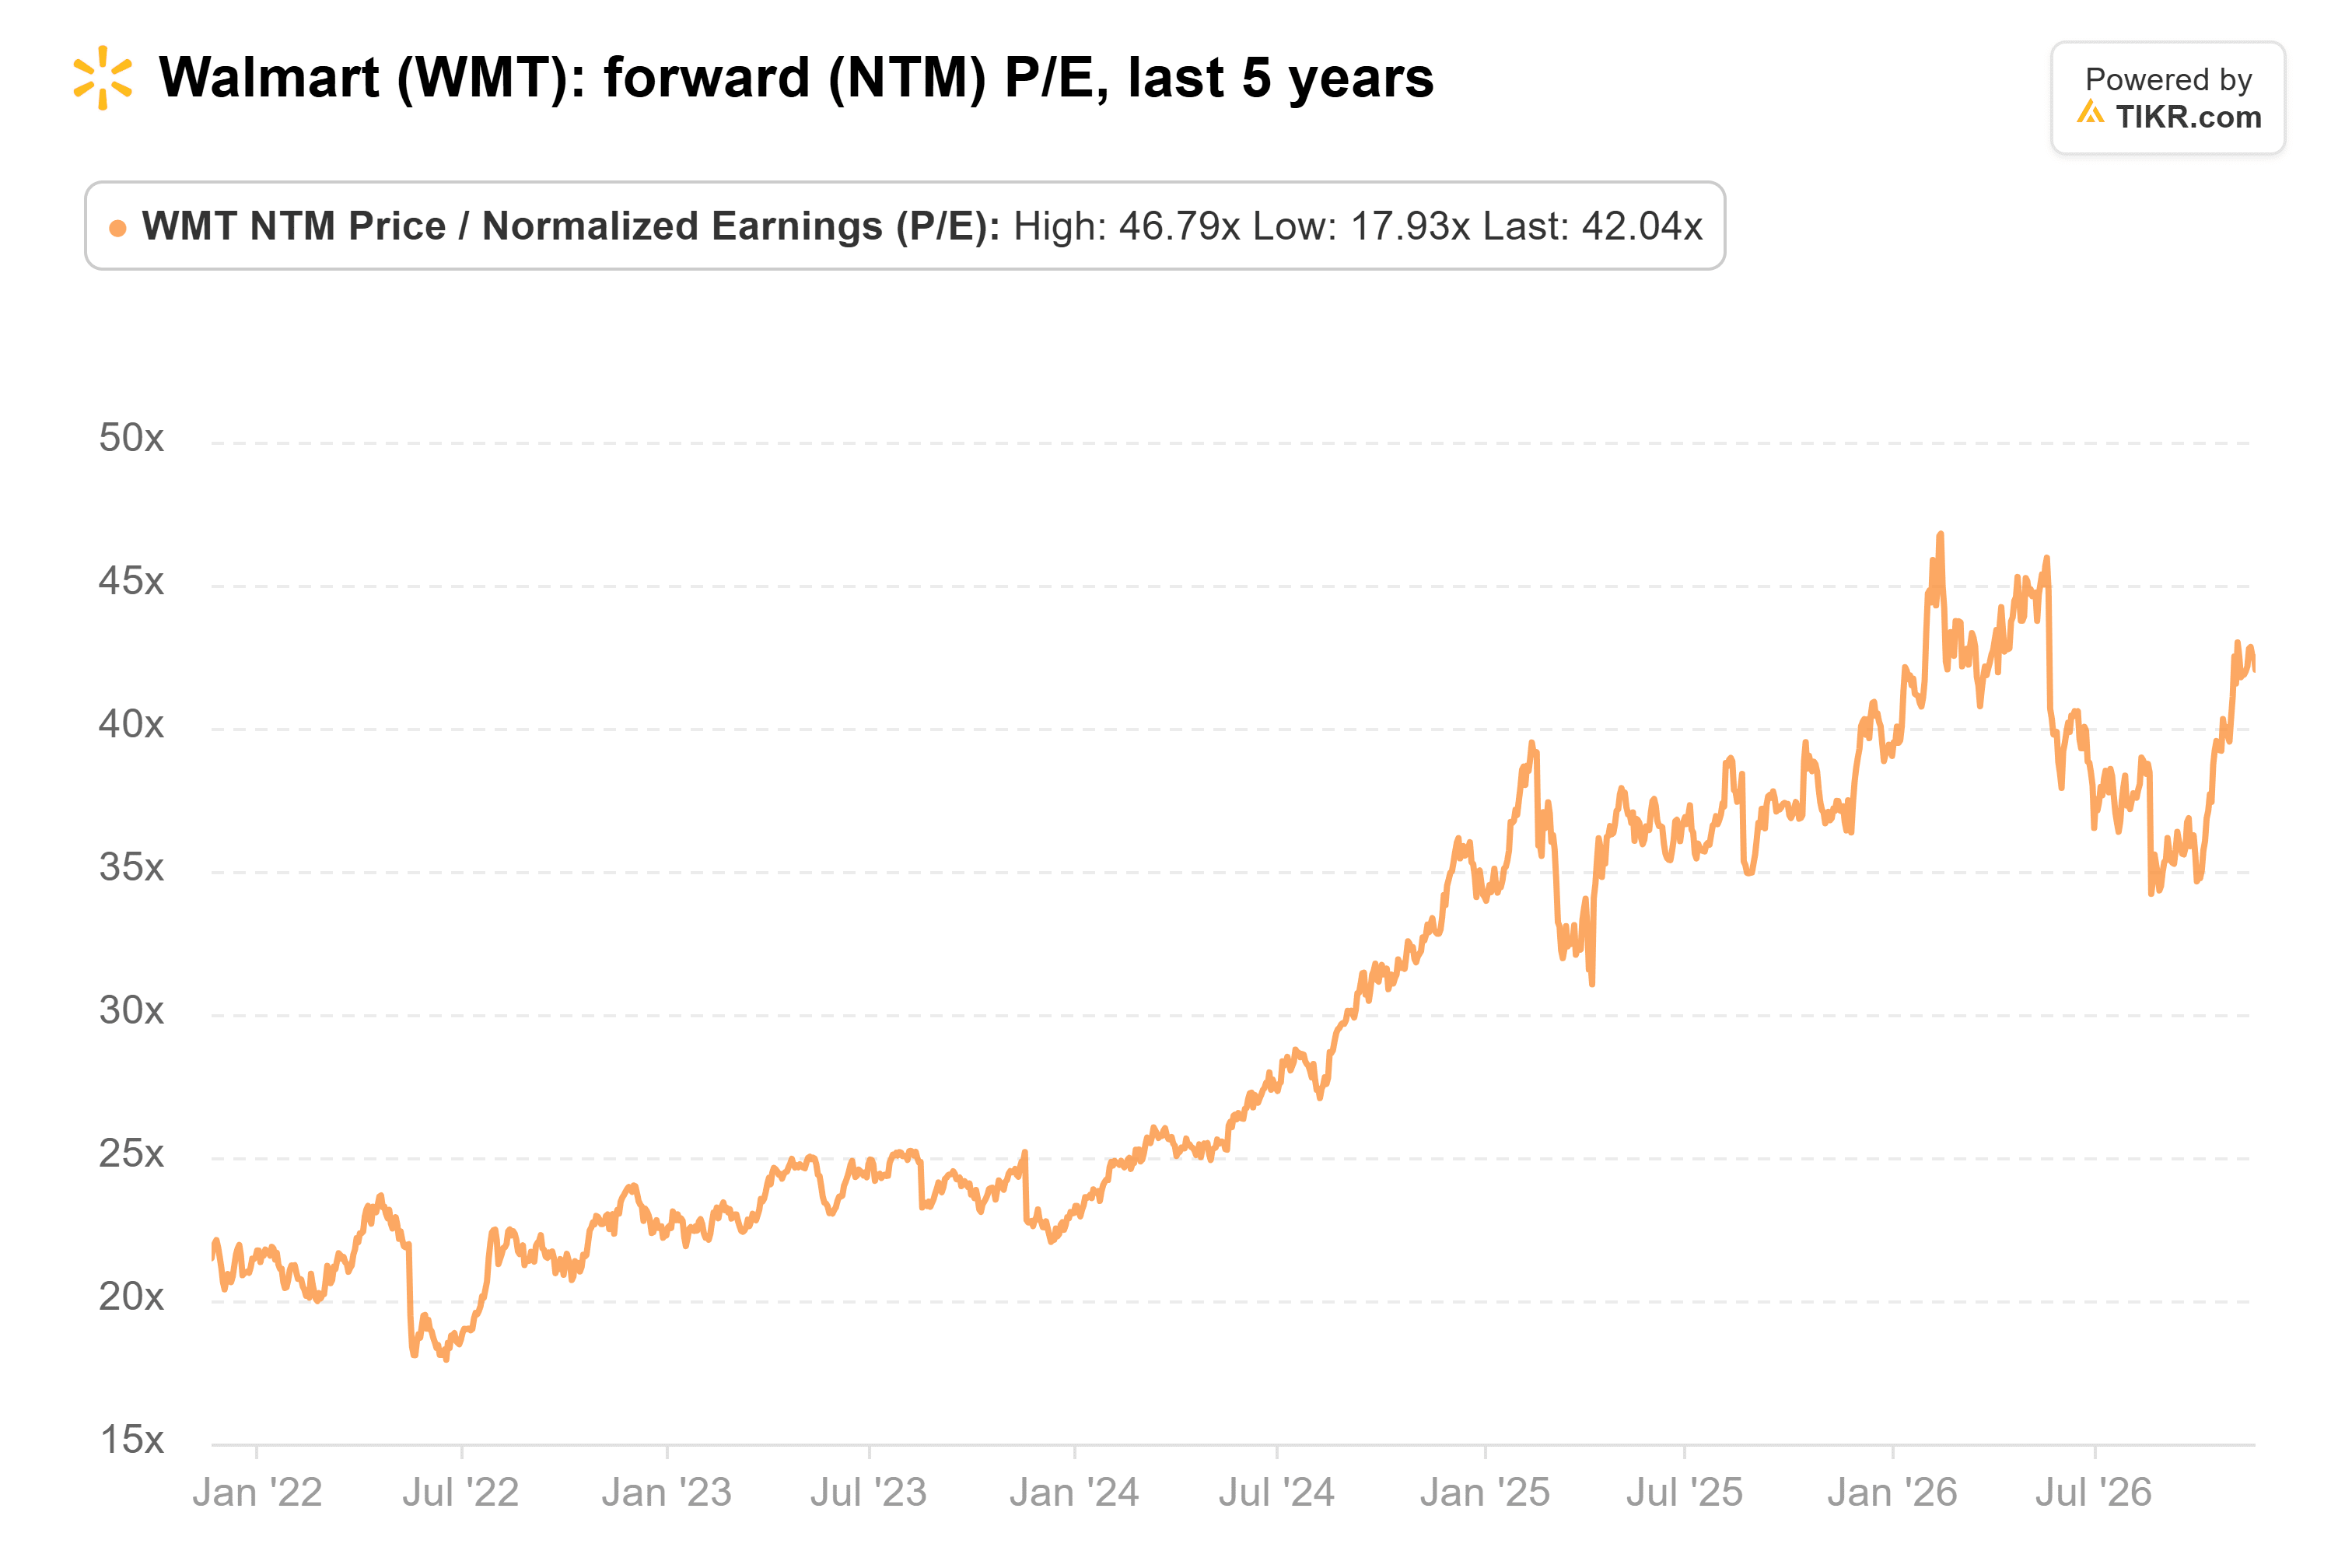
At its five-year average of 29.7x, $3.62 is worth about $107 a share. Walmart already costs more than twice Target’s 17x forward earnings and sits near Costco’s 48x (both as of Nov. 19).
TIKR Tracks 44 Analysts on Walmart. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Walmart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Walmart’s Analyst Ratings
To Me, $147 Is Walmart’s Bull Case
Fourth-quarter profit is only guided to keep pace with sales: adjusted operating income up 4% to 6% in constant currency, against sales up 4.5% to 5.5%. So $147 isn’t too low. It needs investors to keep paying near the top of Walmart’s five-year range for another year, before the margin gains that would justify it arrive. The new targets in the mid-$130s, about 37x the same earnings, look like the likelier landing.
Walmart’s outlook for the year ending January 2028, due in February, is the next test. An operating income guide well ahead of sales, with EPS at or above the $3.24 analysts expect, would make $147 look reasonable.
So What Is Walmart Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Walmart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!