Key Takeaways
- A $750,000 portfolio split evenly across Kimberly-Clark, Agree Realty and Molson Coors pays about $35,300 a year in dividends, or about $2,950 a month.
- Agree Realty’s dividend looks safe and growing, with about 70% of AFFO going to it and a raise in October.
- Molson Coors pays out just 31% of its free cash flow, but it cut its 2026 outlook as beer volumes fall.
- Kimberly-Clark’s dividend is the least covered, at 87% of free cash flow, and halving it would cut the income to about $29,400 a year.
Three well-known dividend payers can give a retiree a real monthly income. But each dividend check is only as reliable as the business behind it.
Take a hypothetical 67-year-old who splits $750,000 evenly across Kimberly-Clark (KMB), Agree Realty (ADC) and Molson Coors (TAP). At today’s prices, that buys about 2,300 shares of Kimberly-Clark, about 3,600 of Agree Realty and about 6,100 of Molson Coors.
Together, the three checks pay about $35,300 a year, or about $2,950 a month. That’s a 4.7% yield on this part of the portfolio. (Of course, no one should ever own just three stocks.)
What covers each check is another story:
| Stock | Shares | Cost | Income a year | Share of income | Coverage |
|---|---|---|---|---|---|
| Kimberly-Clark (KMB) | 2,311 | $249,935 | $11,832 | 33% | Cash dividend payout ratio: 87% (TTM) |
| Agree Realty (ADC) | 3,625 | $249,944 | $11,781 | 33% | AFFO payout ratio: 71% (fiscal 2025), 70% (fiscal 2026 est.) |
| Molson Coors (TAP) | 6,110 | $249,960 | $11,731 | 33% | Cash dividend payout ratio: 31% (TTM), 36% (fiscal 2026 est.) |
| Total | $35,345 | 100% |
Source: TIKR. Today’s prices; dividends at each company’s current annual rate. TTM is the twelve months to Sept. 30, 2026.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Kimberly-Clark just got a lot bigger
Kimberly-Clark closed its purchase of Kenvue on Nov. 2. To help pay for it, Kimberly-Clark sold $4.9 billion of notes on Oct. 29, and Kenvue’s $7.0 billion of bonds became its debt too. Its own business was soft going in. Third-quarter organic sales fell 1.3% from a year before, hurt by social media allegations about its diapers in China and club distribution changes in North America.
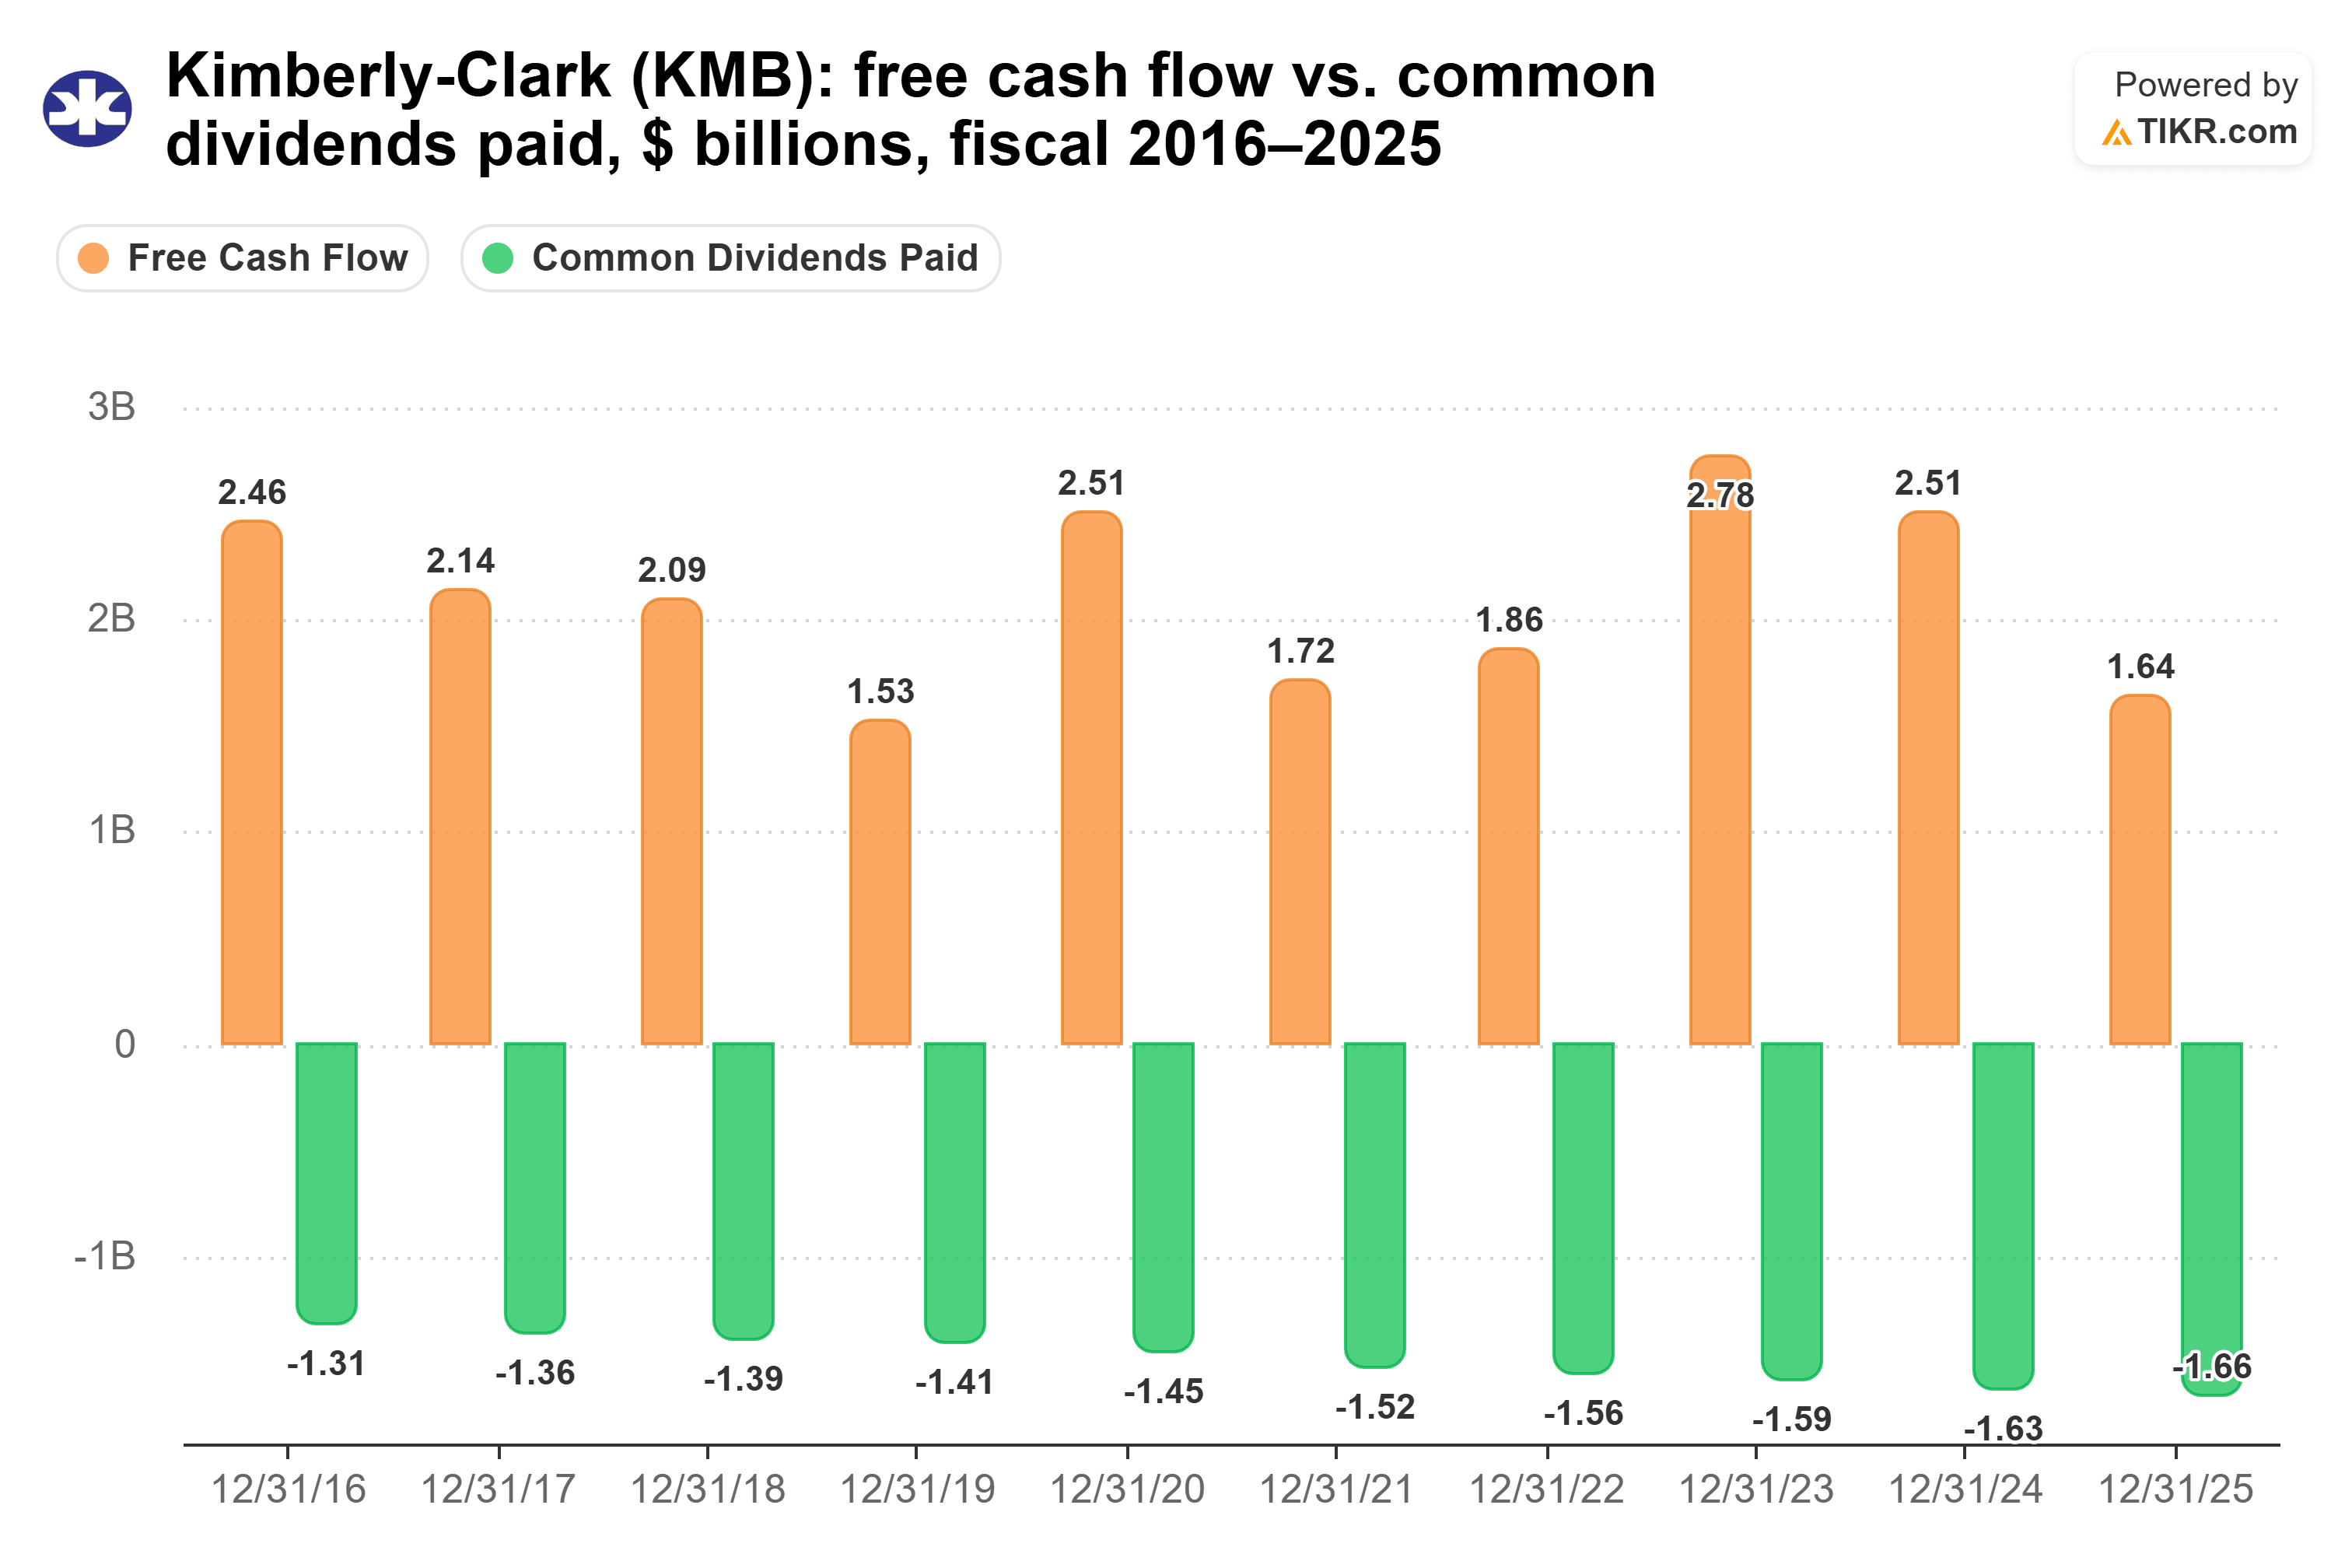
Its dividend took 87% of free cash flow over the twelve months to Sept. 30. Free cash flow covered dividends in every fiscal year of the past decade but fiscal 2025, when $1.66 billion of dividends edged past $1.64 billion of free cash flow:
Kimberly-Clark says it has raised its dividend in each of the past 54 years. On Nov. 11, its board made its first declarations since the deal closed: the regular $1.28 a quarter, a one-time special dividend of $30 a share payable Dec. 4, and up to $4 billion of buybacks through November 2030. The special isn’t counted in the income here.
Agree Realty’s check keeps growing
Agree Realty’s check comes with a lot less drama. In October, the REIT raised its monthly dividend to $0.271 a share, up 3.4% from a year before. Third-quarter AFFO per share rose 4.9% to $1.15, and management raised its 2026 AFFO guidance to $4.58-$4.59 a share from $4.57-$4.59.
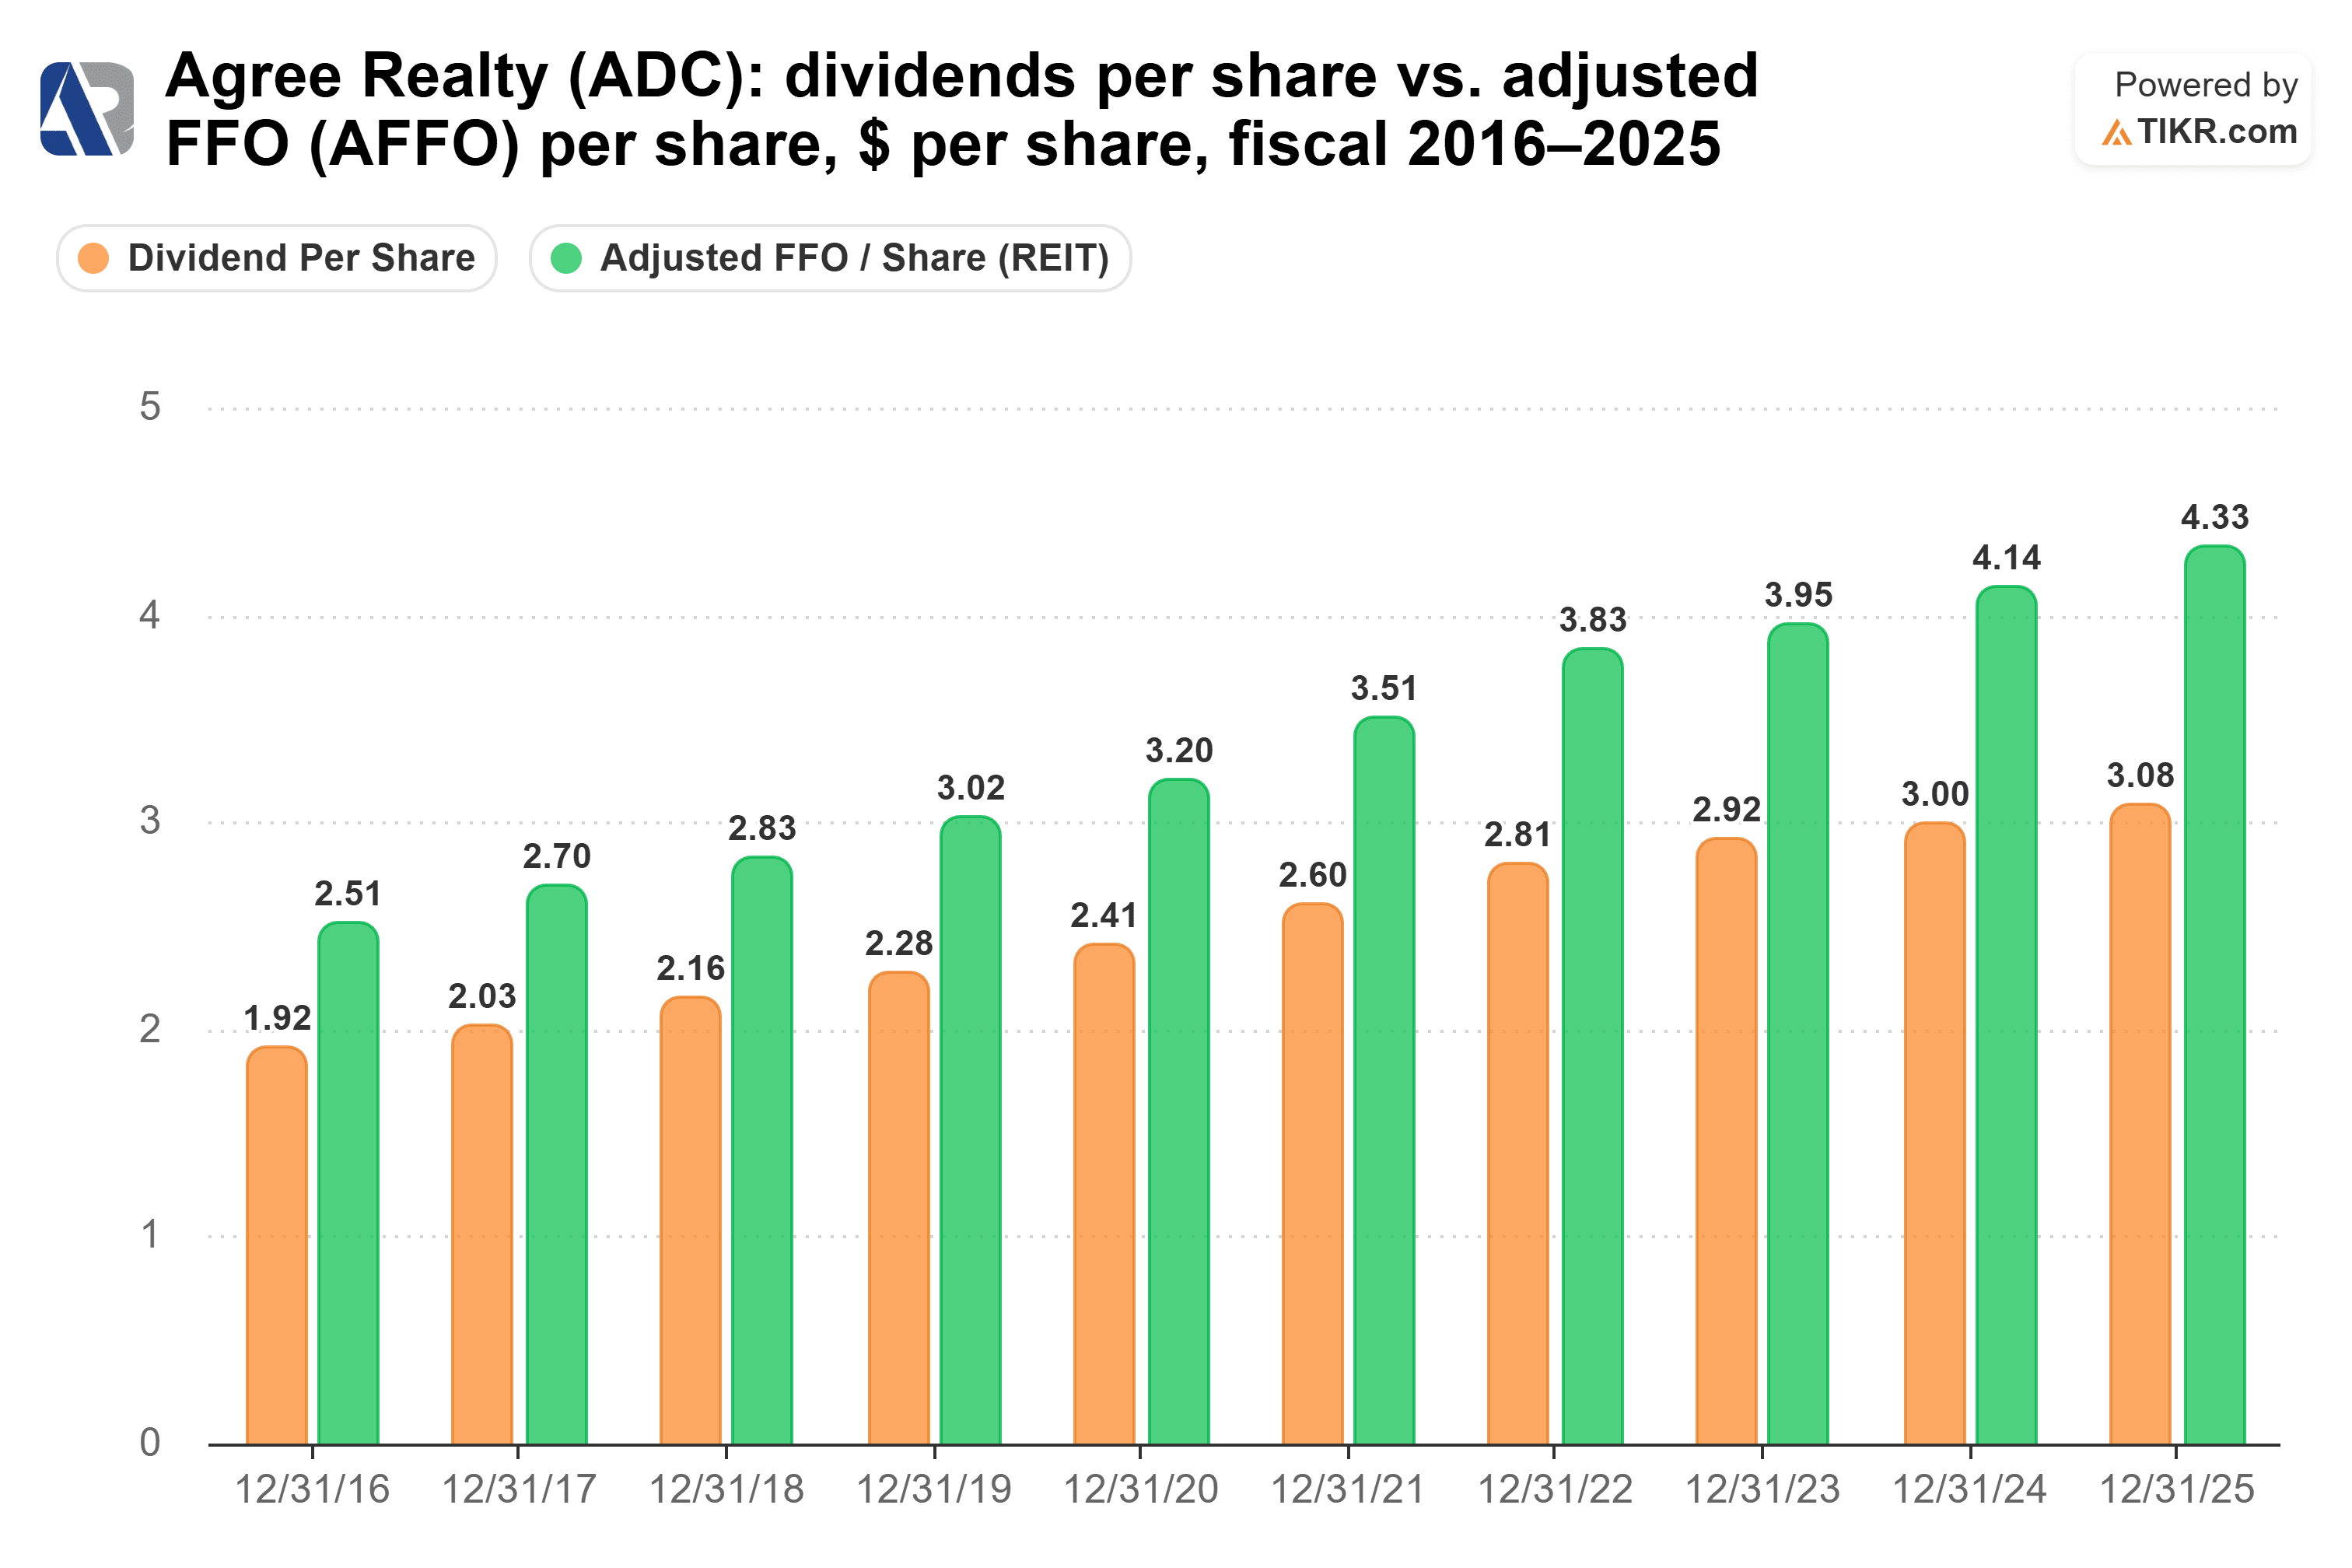
The dividend took a comfortable 71% of AFFO in fiscal 2025, and analysts expect 70% for fiscal 2026. That’s better than fiscal 2016’s 76.5%, even as the dividend grew from $1.92 a share to $3.08 by fiscal 2025:
The main risk is a higher cost of capital. It led Agree Realty to cut its 2026 investment guidance to about $1.6 billion from $1.6-$1.8 billion. CEO Joey Agree says the company will keep “focusing on value over volume.” It has no material debt maturities until 2028, and it expects mid-single-digit AFFO per share growth in 2027.
Molson Coors has room to spare and a shrinking business
Where Kimberly-Clark’s cushion is thin, Molson Coors’ is thick. Its dividend took just 31% of free cash flow over the twelve months to Sept. 30, and analysts expect 36% for fiscal 2026. Free cash flow has covered dividends easily in every year of the past decade. Dividends paid did drop to $130 million in fiscal 2020 from $420 million in fiscal 2019:
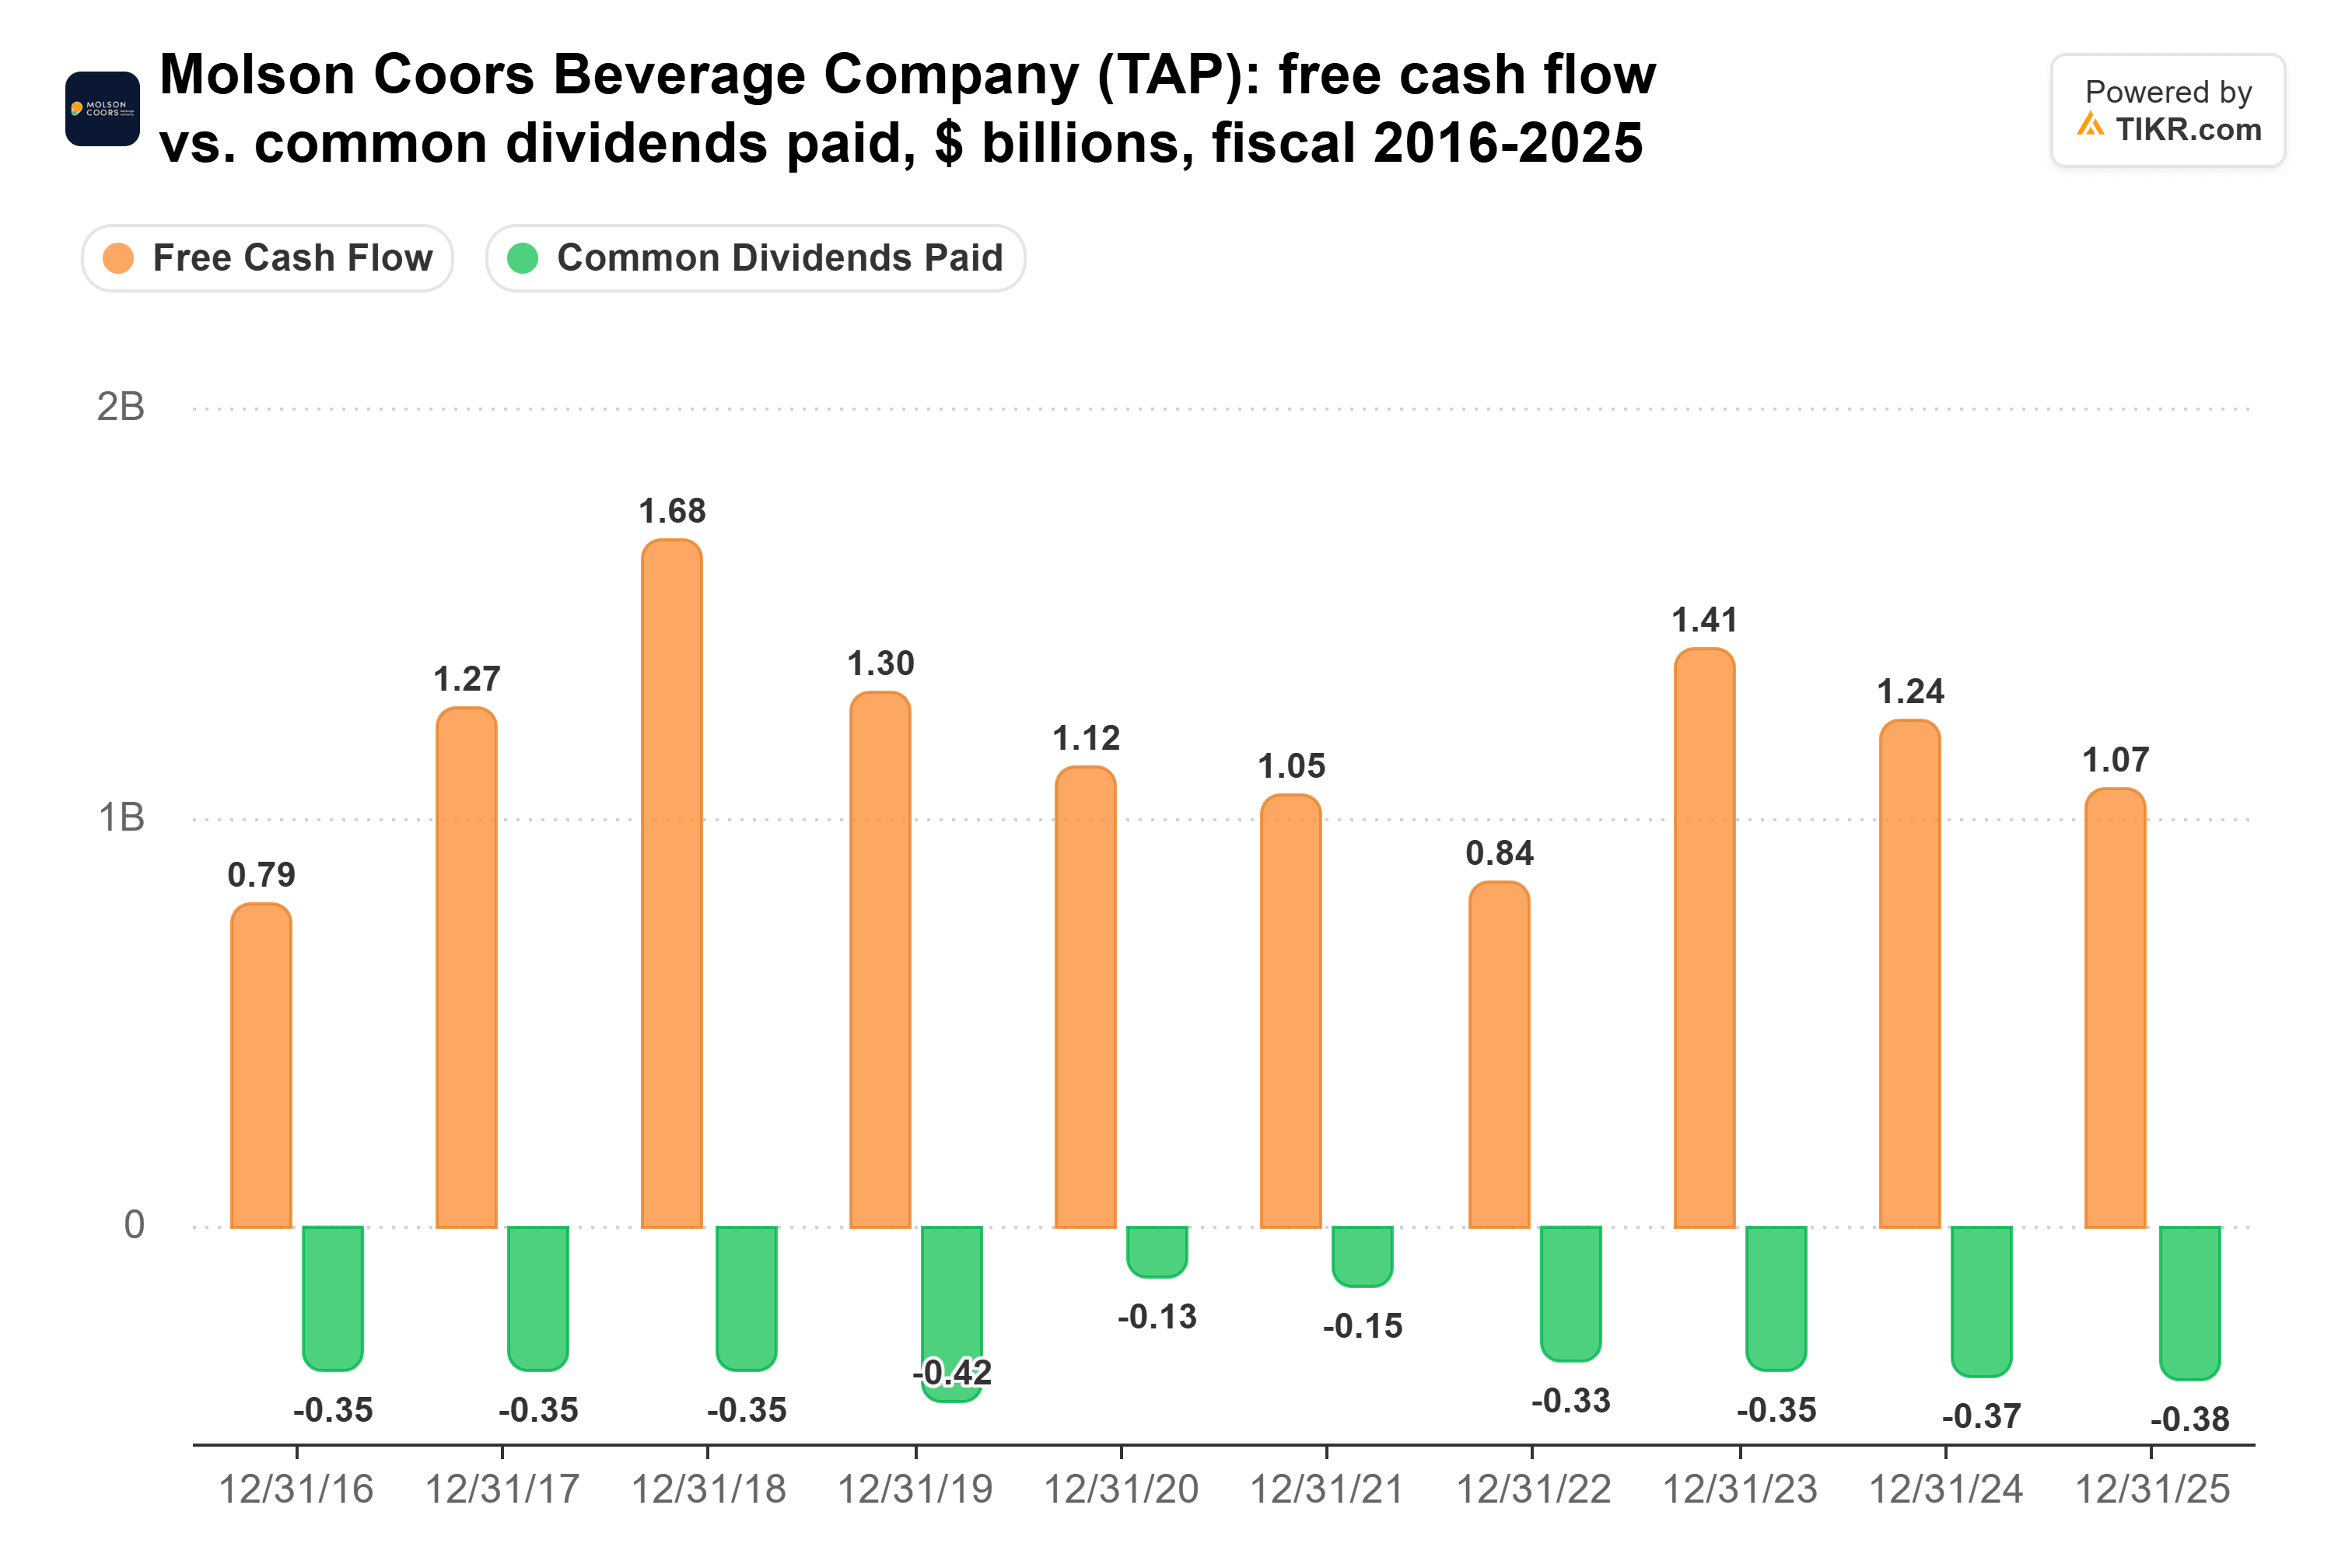
That cushion is handy, since the business is shrinking. On Nov. 5, Molson Coors cut its 2026 outlook. It now expects underlying EPS to fall 16% to 19%, down from a forecast of 11% to 15% before, and underlying free cash flow of about $1.0 billion, down from $1.1 billion. Management cited three causes:
- U.S. beer industry volume down more than 4% by the company’s estimate
- Heavier discounting in the U.K.
- About $130 million more in Midwest Premium aluminum costs than last year
Even at $1.0 billion, the dividend would take well under half of free cash flow. The stock is another matter. Wells Fargo and JPMorgan both downgraded it to Underweight on Nov. 6, and JPMorgan cut its target to $37 from $41.
Two solid checks and one to watch
Agree Realty’s check looks safe and growing. Molson Coors’ looks safe but slow. I’d worry about the stock long before the dividend. Still, at $1.88 a share in fiscal 2025 against $1.64 in fiscal 2015, the dividend has barely grown in a decade.
Kimberly-Clark is the least covered, at 87% of free cash flow, so it’s the one to test. If it halved its dividend, this retiree’s income would fall to about $29,400 a year. If it stopped paying, the income would fall to about $23,500. It’s the most at risk of the three, but I wouldn’t call it risky. A 54-year streak is a lot to give up. And in the first nine months of 2026, Kimberly-Clark generated $2.4 billion of operating cash flow, which covered $1.0 billion of capital spending plus $1.3 billion of dividends. Still, all that new debt leaves less room for a slip.
If I had to lean on one of these checks, it’d be Agree Realty’s. The next test is Kimberly-Clark’s first report with Kenvue in it, early next year. I want to see free cash flow back above the dividend.
Forget Agree Realty: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Agree Realty isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!