Key Takeaways
- Suze Orman told a married couple in their mid-70s to pay cash for their next home instead of taking a mortgage at today’s rates.
- If $400,000 of that cash came from a traditional IRA, on top of $50,000 of other income, the couple’s joint income for the year would be $450,000. That’s above Medicare’s $410,000 surcharge line for 2026.
- At 2026’s rates, that adds $446.30 a month to each spouse’s Part B premium two years later. That’s $10,711.20 for the year, before the income tax on the withdrawal.
- Using the money from selling their current home avoids the problem, because a married couple can exclude up to $500,000 of gain on a main home from income.
If you’re in your 70s and thinking about one last move, Suze Orman has a clear answer on whether to take a mortgage: don’t. But check which account the cash comes from before you write the check, because the wrong one can cost a couple more than $10,000 in Medicare surcharges.
Orman wants this house paid for
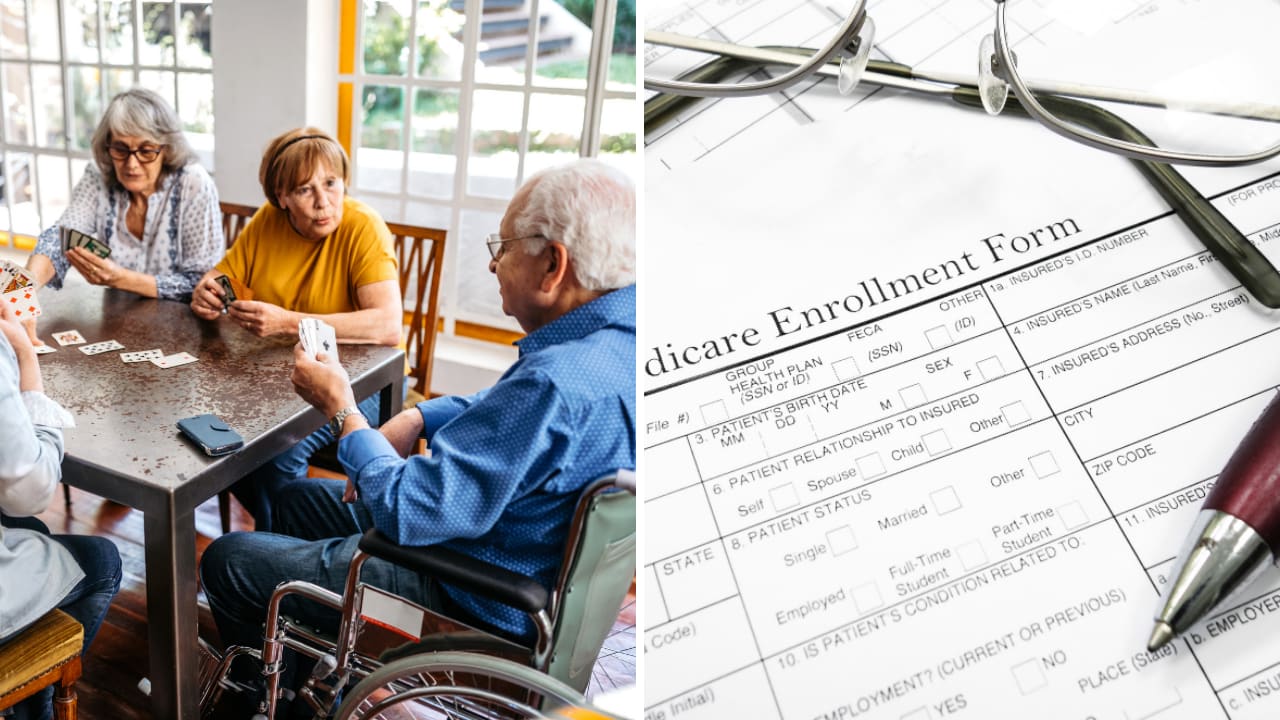
On the Nov. 15 episode of Suze Orman’s Women & Money podcast, Orman answered a letter from a husband who said he and his wife are both in their mid-70s. They plan to sell their current home and move somewhere more urban where they can walk everywhere. He’d rather take a mortgage on the new place and keep the money from the sale invested so they have cash on hand. His wife disagrees.
Orman sided with paying cash. She put mortgage rates at about 7.5%, said she wouldn’t be surprised to see 8%, and asked, “Do you think that you can guarantee yourself an 8% return in the stock market?” She also pointed out that when one of them dies, the survivor loses one of their two Social Security checks and still has to afford the house. If they want cash on hand later, she said, they can open a home equity line of credit after they buy. Her verdict: “No, you are to absolutely own this home outright.”
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
The IRA is the expensive place to find that cash
The couple’s letter suggests the sale of their current home would pay for the next one. But say the new place costs more than the old one sells for, or they have to close before their sale does, and they take $400,000 out of a traditional IRA to cover it. Add an assumed $50,000 of other income on their tax return, and their joint income for the year comes to $450,000.
Medicare sets each person’s Part B premium from their tax return two years earlier. In 2026, a married couple filing jointly with income above $410,000 and below $750,000 pays a surcharge of $446.30 a month each, on top of the standard premium. If both of them are on Part B, both owe it.
So a withdrawal taken this year shows up in their 2028 premiums. At 2026’s rates, that’s $446.30 a month times 12 months times two spouses: $10,711.20 for the year in surcharges, on top of the income tax on the $400,000 itself. That’s real money for a couple whose other income is $50,000 a year.
Selling the old house first is the cheap way to pay
Money from selling their current home is treated differently. A married couple filing jointly who has owned the home and lived in it as their main home for at least two of the last five years can exclude up to $500,000 of the gain from income. That gain never shows up on the tax return Medicare uses, so it can’t push them into a surcharge band. Any gain above $500,000 is taxable, though, and it does count.
So the cheapest way to follow Orman’s advice is the sale the couple already planned: sell first, and put the proceeds into the new home. If an IRA has to fill a gap, timing helps. Split the same $400,000 into $200,000 in December and $200,000 in January. With the same $50,000 of other income, each year’s joint income is $250,000. That puts them in 2026’s lowest surcharge band, $81.20 a month each. That’s $1,948.80 a year for the two of them, and $3,897.60 over the two years. That’s about $6,800 less than taking it all in one year, and it keeps more of the withdrawal in lower income-tax brackets too.
Own it outright, from the right account
I’m with Orman on this one. Borrowing at 7.5% to keep money invested is a bet that the market beats that rate year after year. In your mid-70s, I’d rather the surviving spouse never have to pay a mortgage on one Social Security check. Just pay with the old home’s proceeds wherever you can, since a big IRA withdrawal for the house can cost five figures in surcharges two years later. The surcharge bands rise with inflation each year, so 2028’s income lines will likely be a bit higher than 2026’s $410,000. A $450,000 year would still likely be over it, so if you’re planning a big withdrawal, check that year’s bands before you take it.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!