Key Takeaways
- BMO Capital Markets upgraded Bloom Energy to Outperform on Nov. 19 and cut its price target to $230 from $260, 37% above the stock.
- The stock is 51% below its June high after a cash-burning quarter and post-midterm fears of a data-center slowdown.
- $230 works at Bloom’s lowest forward P/E since 2023 if forward EPS reaches $7.93 a year out.
- The next tests are Oracle’s mid-December report and Bloom’s fourth-quarter revenue and cash.
Bloom Energy (BE) is 51% below its June high, and BMO Capital Markets turned bullish. On Nov. 19, analyst Ameet Thakkar upgraded the stock to Outperform from Market Perform and cut his target to $230 from $260, 37% above Thursday’s $168.11 close.
That upside rides on customers’ data-center spending, starting with Oracle (ORCL). Oracle plans to buy up to 2.8 gigawatts of Bloom’s fuel cells, and its wider data-center build left it with negative free cash flow of $5 billion in its quarter ended Aug. 31.
Record Quarters, Thin Cash, Then the Midterms
Bloom’s Oct. 22 report set records: third-quarter revenue rose 138% to $1.24 billion, and management raised 2026 revenue guidance a third time, to $4.4 billion-$4.6 billion. But free cash flow was negative $181 million, as contract assets jumped $430 million on systems delivered but not yet billed. CFO Simon Edwards said the quarter’s $27 million operating cash outflow was “not the beginning of a trend.”
In the midterms, Democrats won Congress, Texas’s incoming governor promised a moratorium on new data-center approvals, and UBS estimated that pauses could put about 30% of the U.S. data-center capacity additions expected in 2028 at risk. With 97% of its third-quarter revenue from the U.S., Bloom sold off even on the day NTT DATA agreed to deploy 900 megawatts of its fuel cells. (Texas regulators have since resumed data-center permitting.)
TIKR Tracks 29 Analysts on Bloom Energy. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
BMO Got the Proof It Wanted
BMO had doubted Bloom’s large-scale track record, its staying power once grid power gets easier to find, and its reliance on U.S. data centers. Those debates remain, Thakkar says, but projects like Nebius’s now give BMO the execution evidence it wanted. The target cut, he wrote, reflects “recent multiple compression across power infrastructure.”
Does Bloom Energy’s $230 Add Up?
Targets run from $102 to $380, and the $284 average has barely moved from its October peak as the stock fell.
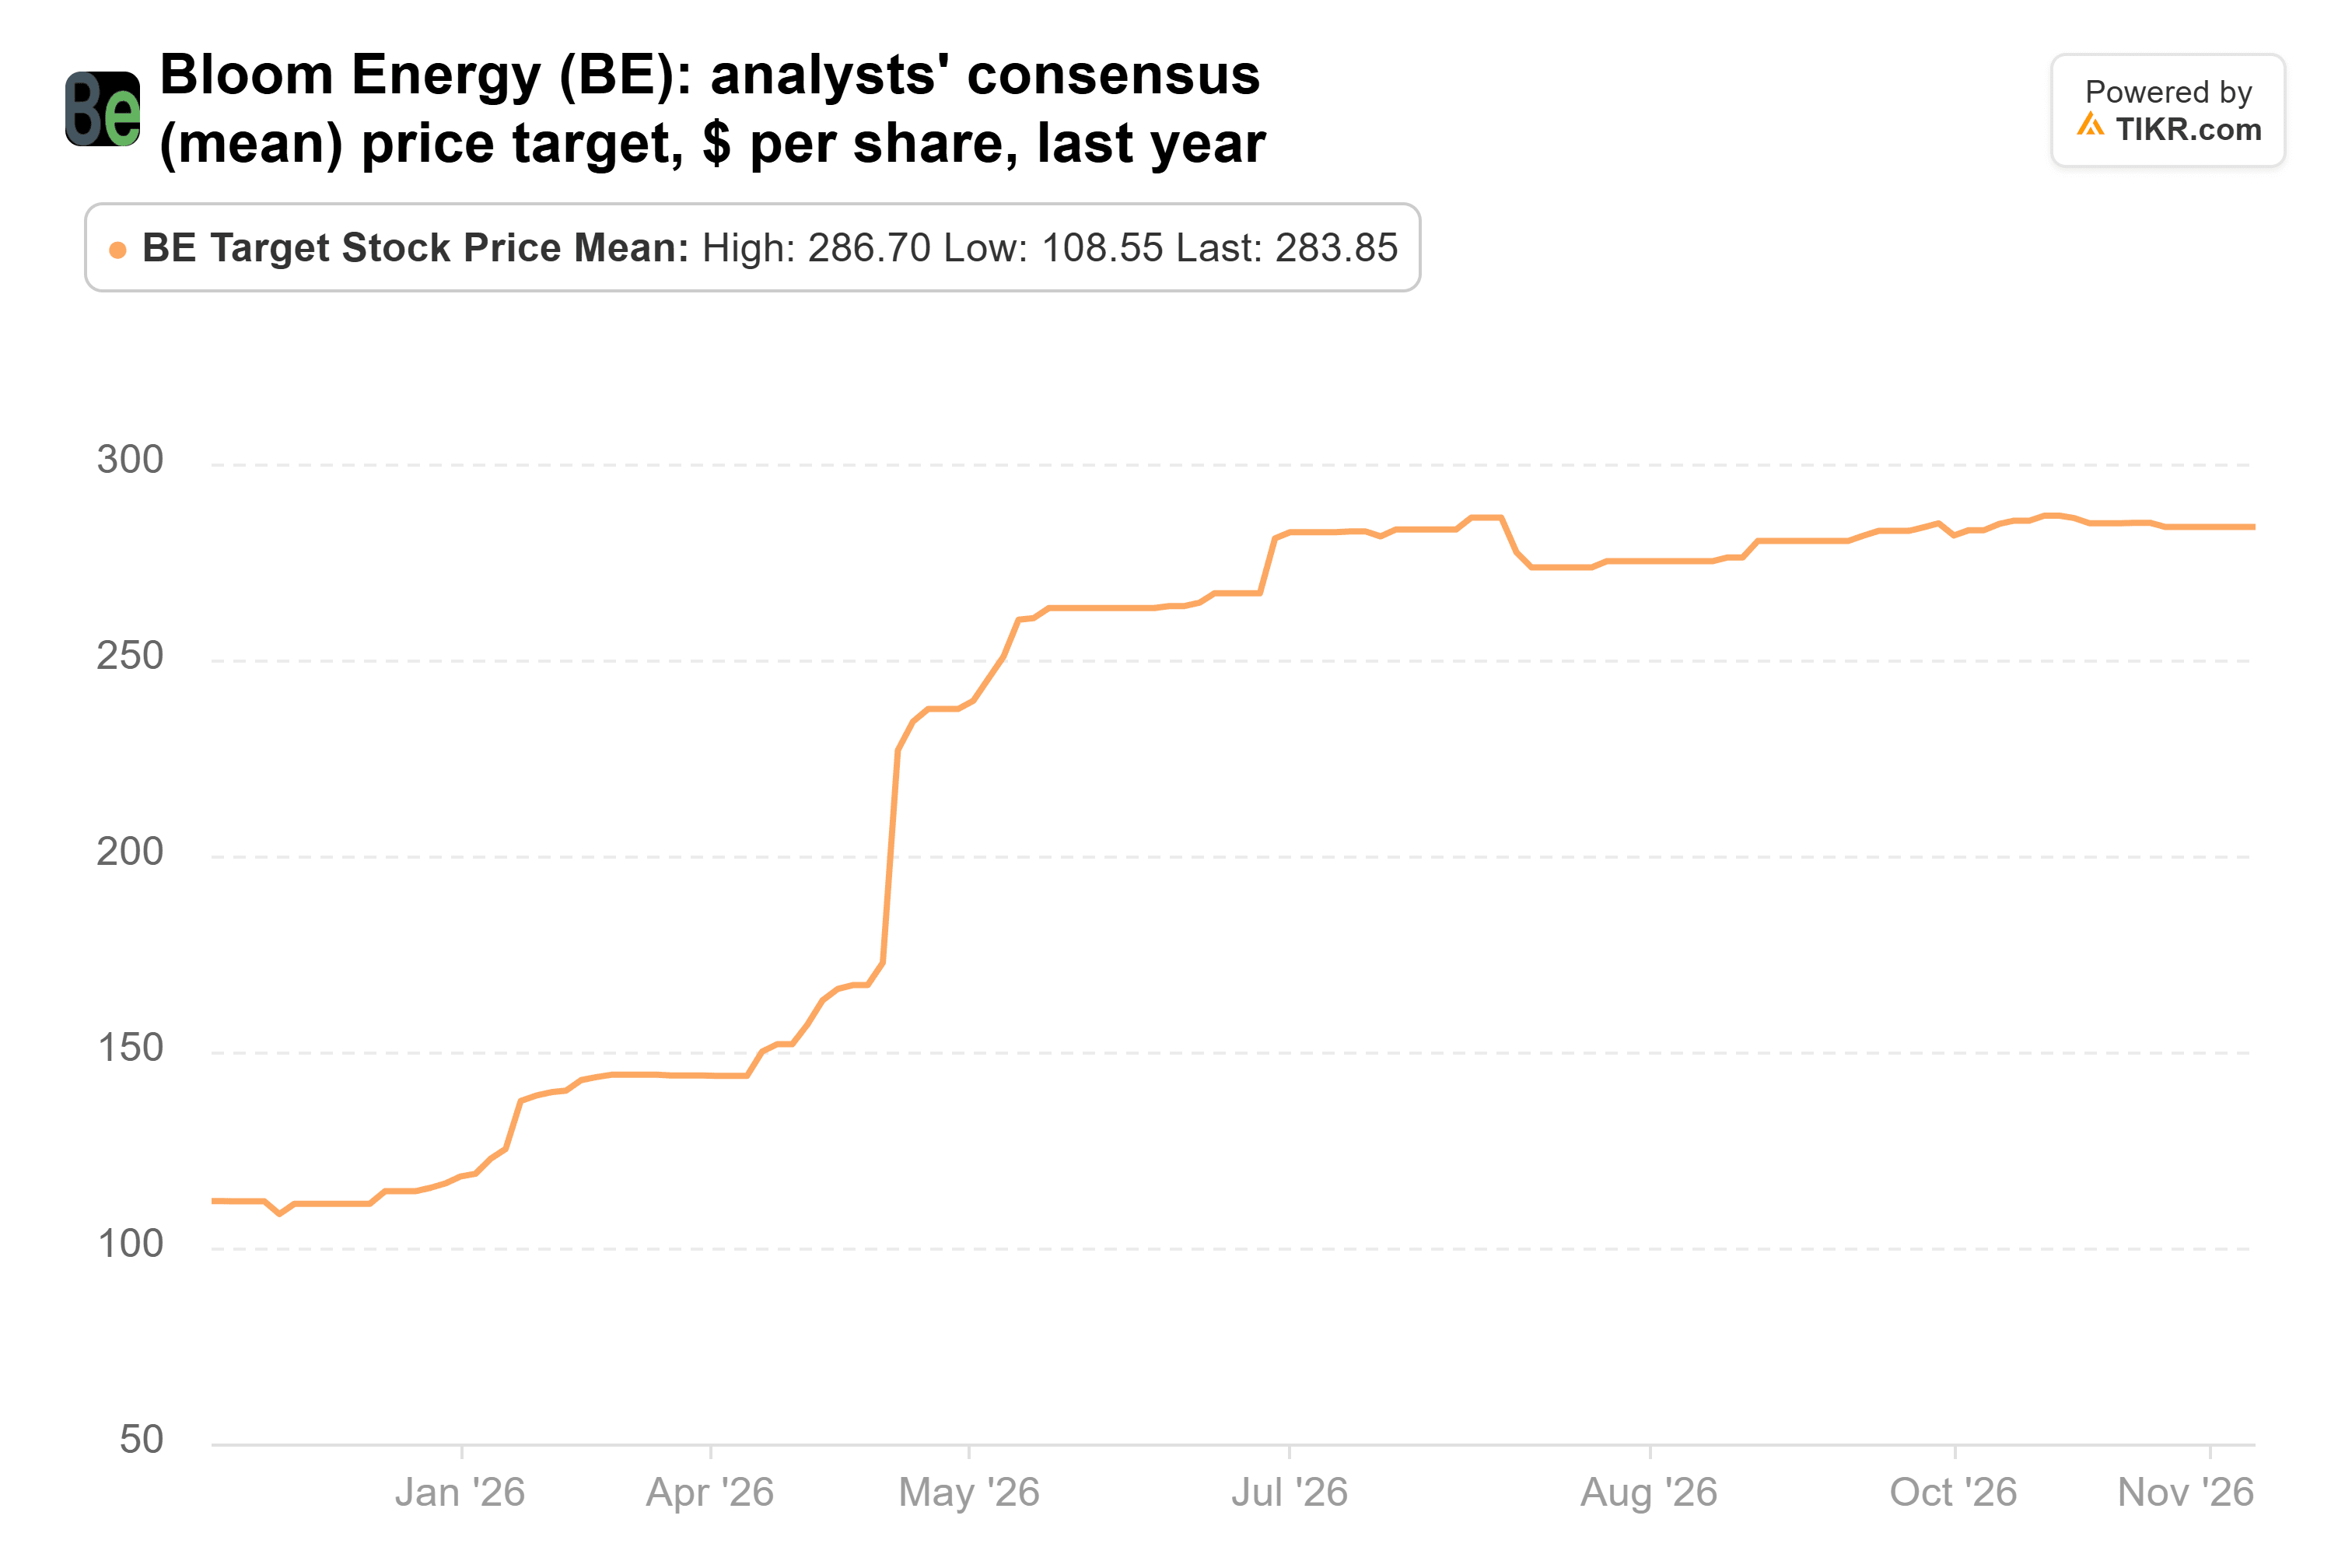
The estimates under those targets rose after the report and held through the midterm scare. Normalized EPS is expected to go from $0.76 in 2025 to $8.24 in 2028.
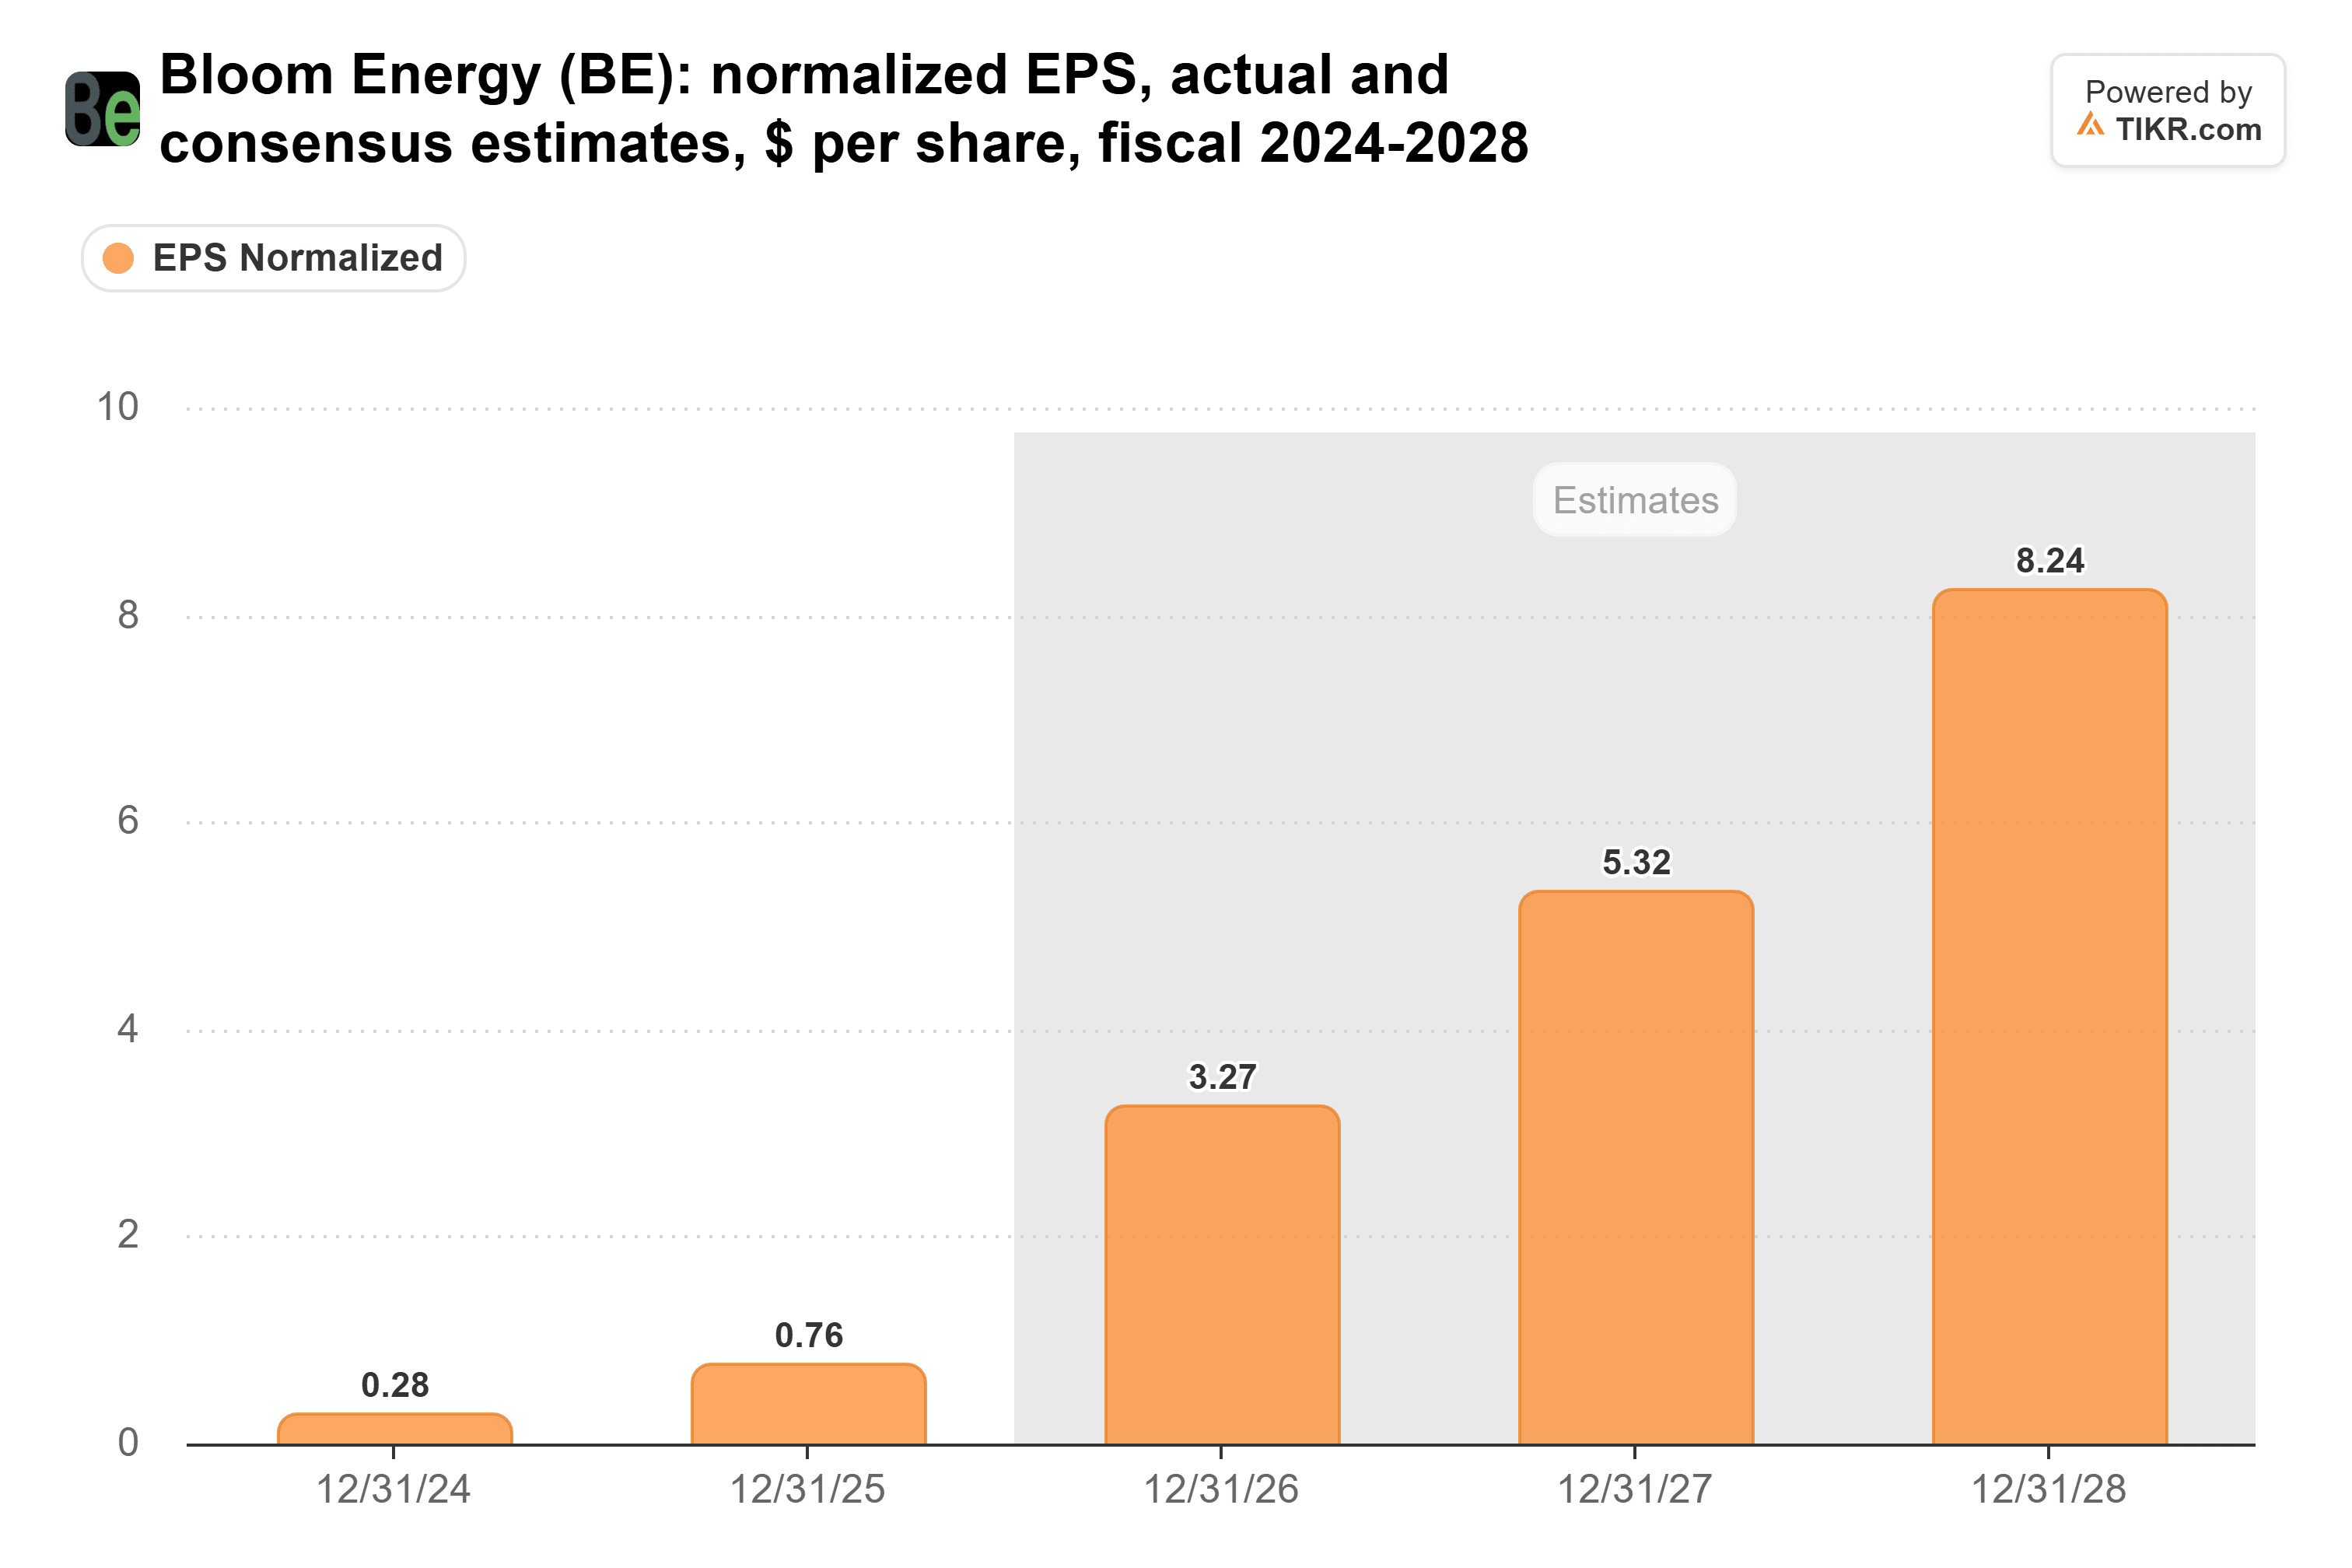
Bloom’s forward P/E has run between 29x and 145x at quarter-ends since September 2023, and it’s 34x now. At that 29x low, $230 needs about $7.93 of forward EPS a year from now. Analysts expect $8.24 for 2028, so no re-rating is needed if forward EPS hits $7.93 by November 2027.
A Low Bar for Bloom Energy, If the Build Holds
The risk is the estimates, which take revenue from $2.02 billion in 2025 to $10.30 billion in 2028 and need the data-center build to hold. Bloom also faces a securities class action over a short seller’s July claims about its scandium supply.
BMO isn’t asking for much: $230 works at Bloom’s lowest multiple since 2023 if forward EPS reaches $7.93. Oracle reports first, in mid-December. Bloom needs about $1.35 billion of fourth-quarter revenue to reach its guidance floor. For cash, watch whether contract assets keep rising from $858.6 million.
So What Is Bloom Energy Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!