Key Takeaways
- Starbucks grew global comparable sales 7.9% in fiscal Q3, led by a 4.2% gain in transactions.
- Management raised fiscal 2026 non-GAAP EPS guidance to $2.55 to $2.65 and lifted the quarterly dividend to $0.63.
- At 34.3x NTM earnings, Starbucks trades at nearly double McDonald’s multiple, with a 141.8% payout ratio.
- The October 29 Q4 report will show whether traffic gains hold up through $300 million of restructuring charges.
Two weeks ago, Starbucks (SBUX) had to tell the market it was not buying Chipotle (CMG). That says a lot about how confident investors have become in Brian Niccol’s turnaround.
The speculation is gone, but the momentum is real. Shares closed at $101 on October 23, down 1.1% on the day yet up 22.2% year to date, within reach of the 52-week high of $111.
Now comes the test. Starbucks reports fiscal Q4 and full-year results on October 29, with analysts modeling Q4 EPS of $0.73.
The question for that report is simple. Can a recovery built on more customers visiting more often survive store closures and a 34x multiple?
Traffic is doing the heavy lifting
Fiscal Q3 was the cleanest quarter of the turnaround so far. Global comparable sales rose 7.9%, driven by a 4.2% gain in transactions and a 3.5% rise in average ticket.
A few numbers stand out:
- North America comps rose 8.1%, with transactions up 4.5%.
- GAAP EPS jumped 86% to $0.91, and non-GAAP EPS of $0.85 crushed the $0.66 consensus.
- Revenue slipped 1% to $9.3 billion because China moved to a licensed joint venture with Boyu Capital.
That last point is mostly accounting. Starbucks kept a 40% stake in the China business, so company-operated revenue shrinks while the model gets lighter on capital.
Did the comp recovery actually reach the bottom line?

It did, and that Q3 jump in EPS is what gave management the confidence to raise guidance.
Guidance now leans on margins
The raised outlook calls for global comps near 6%, consolidated operating margins above 11% and non-GAAP EPS of $2.55 to $2.65 for fiscal 2026. Starbucks also expects 600 to 650 net new coffeehouses and raised the quarterly dividend 1.6% to $0.63.
Margins are the part to watch. Comps can come from promotions, but margin expansion requires the labor and store investments to start paying back.
So far, that is happening. Starbucks has two straight quarters of margin expansion, and it plans at least 1,500 store uplifts by the end of fiscal 2026. Those uplifts are the bet behind the margin target.
Here is the margin rebuild in one view…
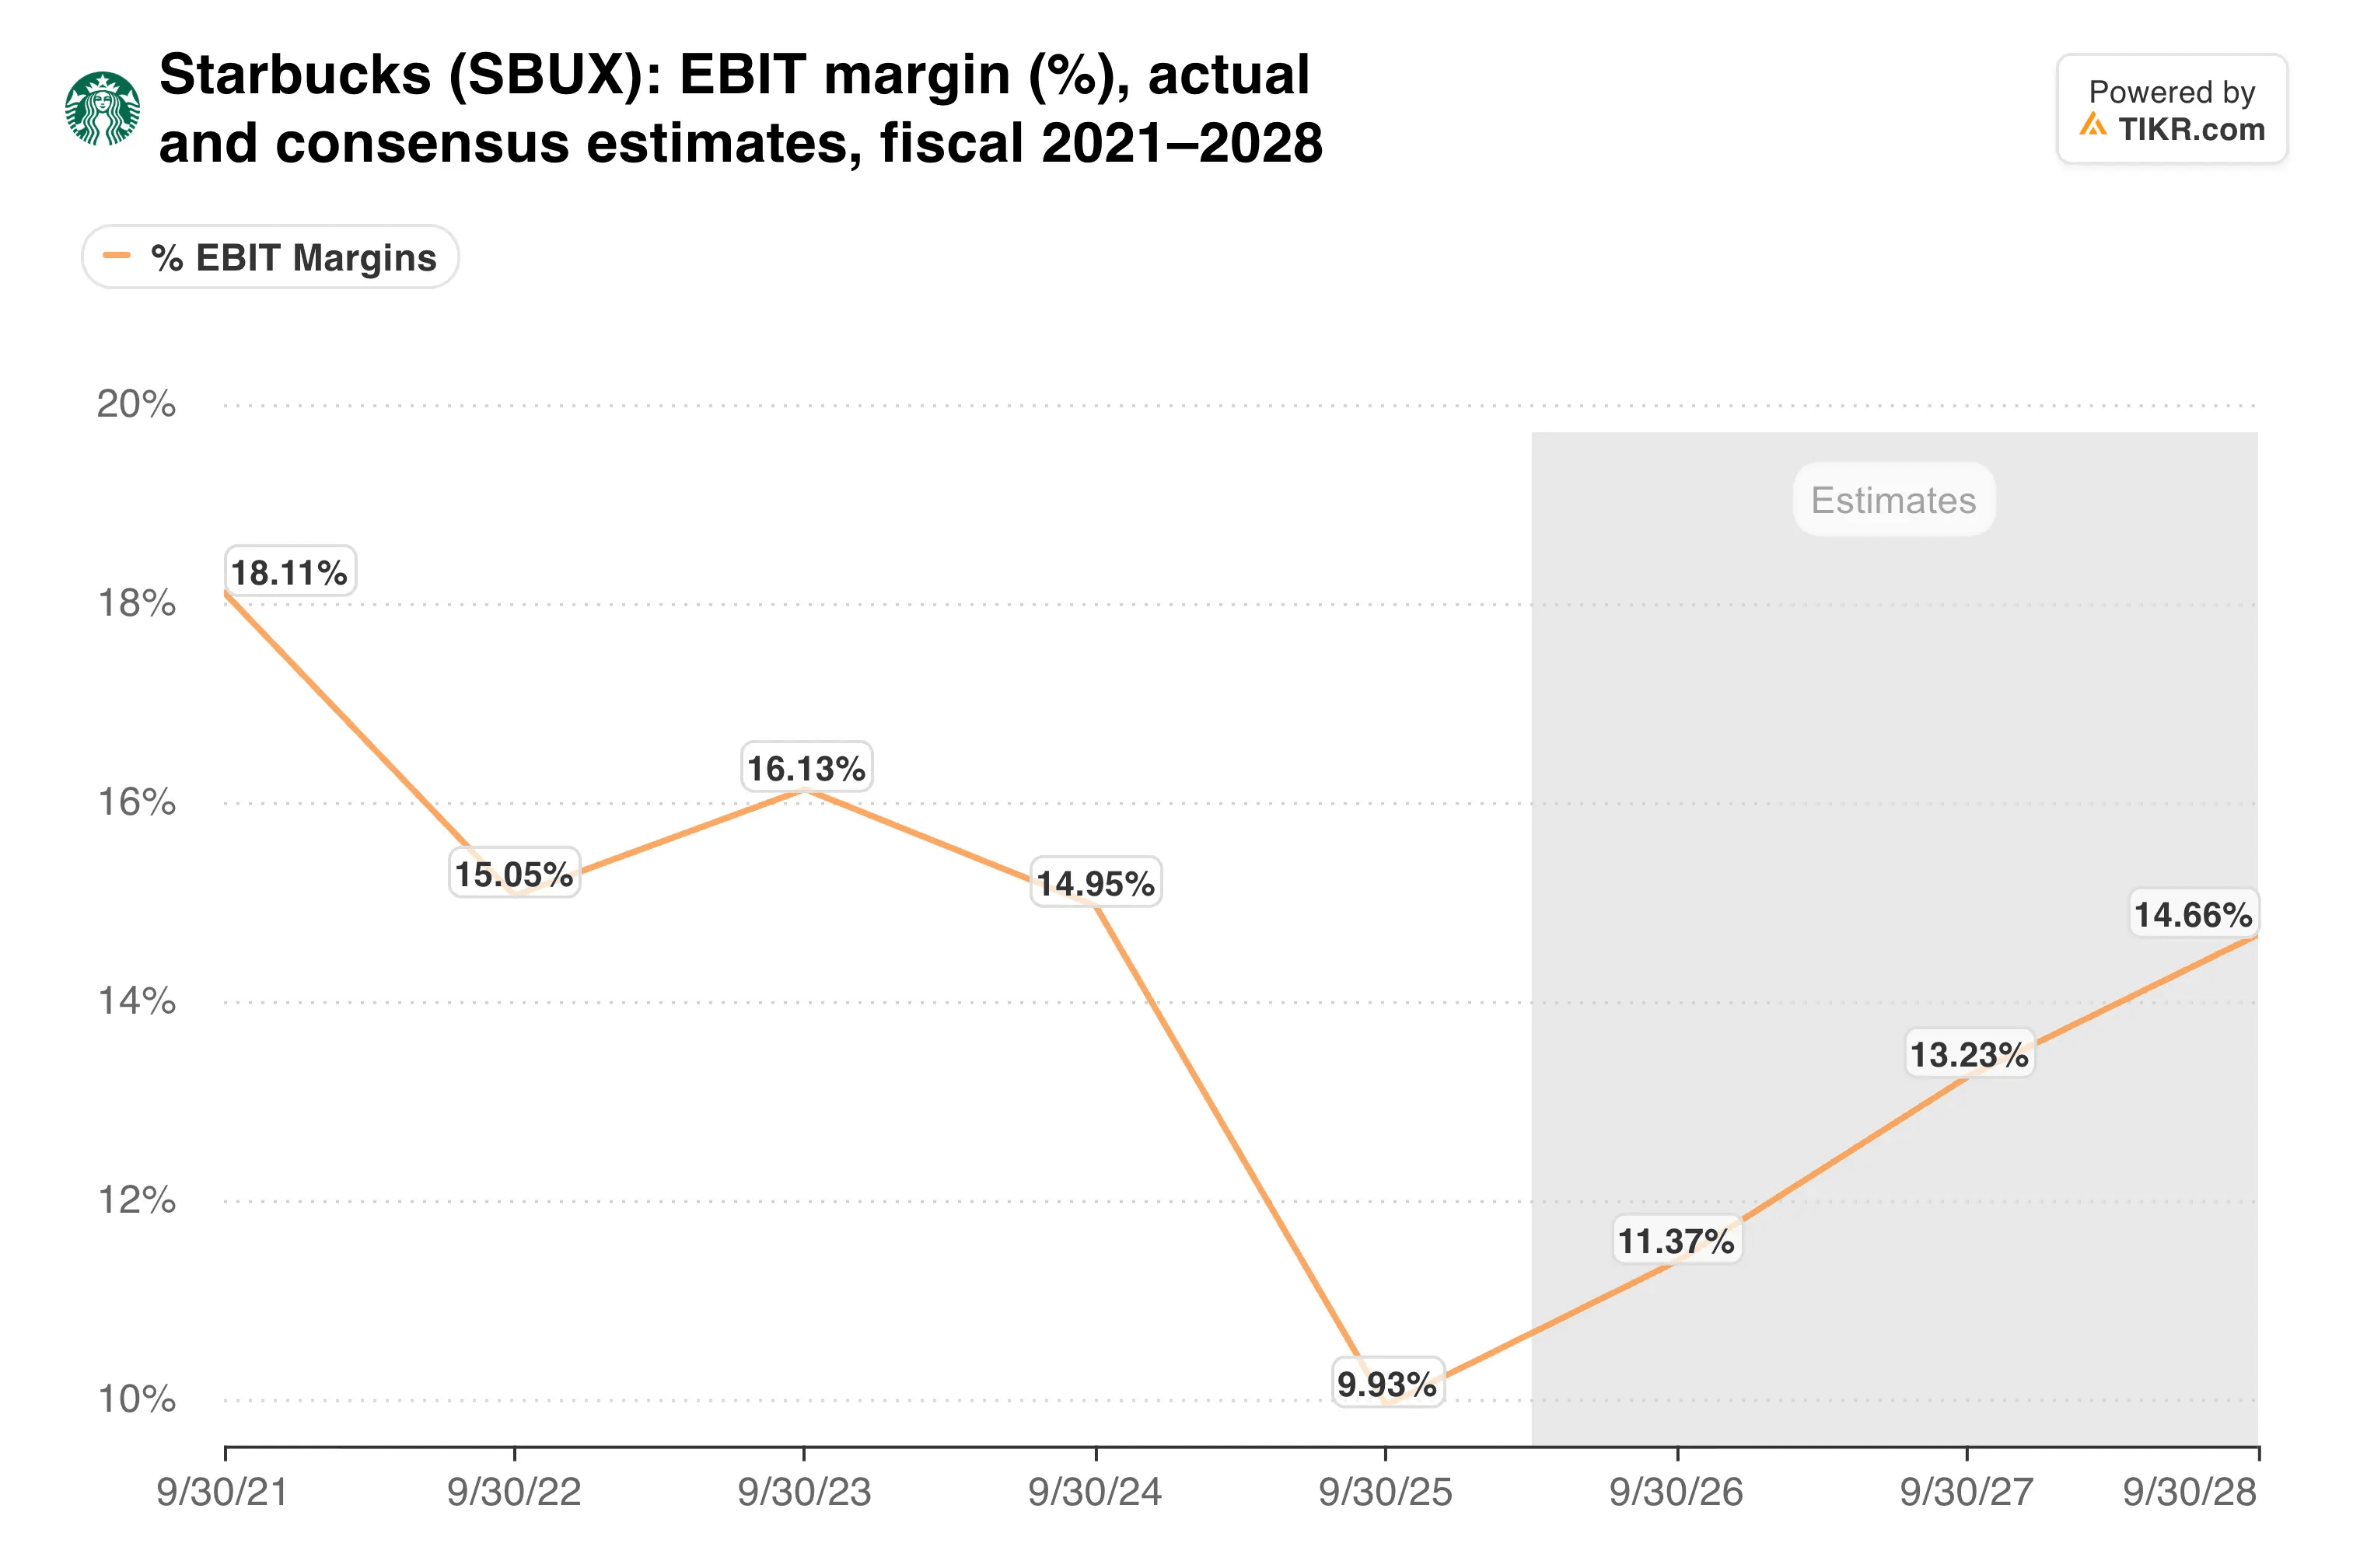
Even above 11%, margins would still sit well below where they were before the slump, so there is room to run if traffic holds.
TIKR tracks 35 analysts on Starbucks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Starbucks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Starbucks’ Analyst Ratings
Paying 34x for a comeback
The market has already priced the turnaround generously. Starbucks trades at 34.3x NTM earnings and 21.2x NTM EV/EBITDA. McDonald’s (MCD) trades at 18.9x and 14.4x, while posting just 1.3% global comps last quarter.
That premium assumes Starbucks keeps compounding. Analysts expect EPS to grow about 21% a year over the next two years, which helps explain why the gap persists.
And the gap has grown this year:

Because the premium widened as comps accelerated, any slowdown would likely hit the multiple first.
Costs are also coming due. Starbucks expects about $300 million of restructuring charges tied to closing roughly 1% of North American coffeehouses, and labor relations remain tense. The payout ratio sits at 141.8%, which leaves the dividend leaning on future earnings growth.
My take: This is the most convincing Starbucks recovery in years, because transactions are driving it. Yet at 34x, the stock needs both a beat and a confident fiscal 2027 outlook, and I would want to see both before adding.
On October 29, the number that matters is U.S. comps against management’s target of 6.5% or better for Q4. Hitting it would support the $111 Street target.
So what is Starbucks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Starbucks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!