Key Takeaways
- Elon Musk said SpaceX is assuming “zero sales to OpenAI,” replying to Sam Altman’s warning about chipmakers counting on OpenAI’s demand.
- That puts the risk of double-counted demand on suppliers like AMD, whose OpenAI deal covers up to 6 gigawatts of GPUs.
- OpenAI’s adjusted operating loss reached $10.9 billion in the third quarter, the Wall Street Journal reported, and Oracle’s free cash flow was negative $23.7 billion in its latest fiscal year.
- SpaceX leans on one big customer too, reportedly Anthropic, whose finances look far healthier than OpenAI’s.
Elon Musk took a shot at OpenAI on X: SpaceX (SPCX), he says, isn’t counting on OpenAI as a customer at all. Advanced Micro Devices (AMD) and Oracle (ORCL) are, and they’re the ones on the hook if OpenAI’s demand has been counted twice.
Musk was replying to OpenAI CEO Sam Altman, who put it this way at a Semafor event on Monday:
“There are now many people making chips. And many of those people think they’re going to sell most of the volume to us and Anthropic and others. And we have some limited amount of demand and data centers and everything else.”
Musk’s response? “SpaceX is assuming zero sales to OpenAI. If OpenAI is not seeing demand rising super fast, then something is wrong with their products.”
Ouch.
SpaceX’s demand is coming from elsewhere
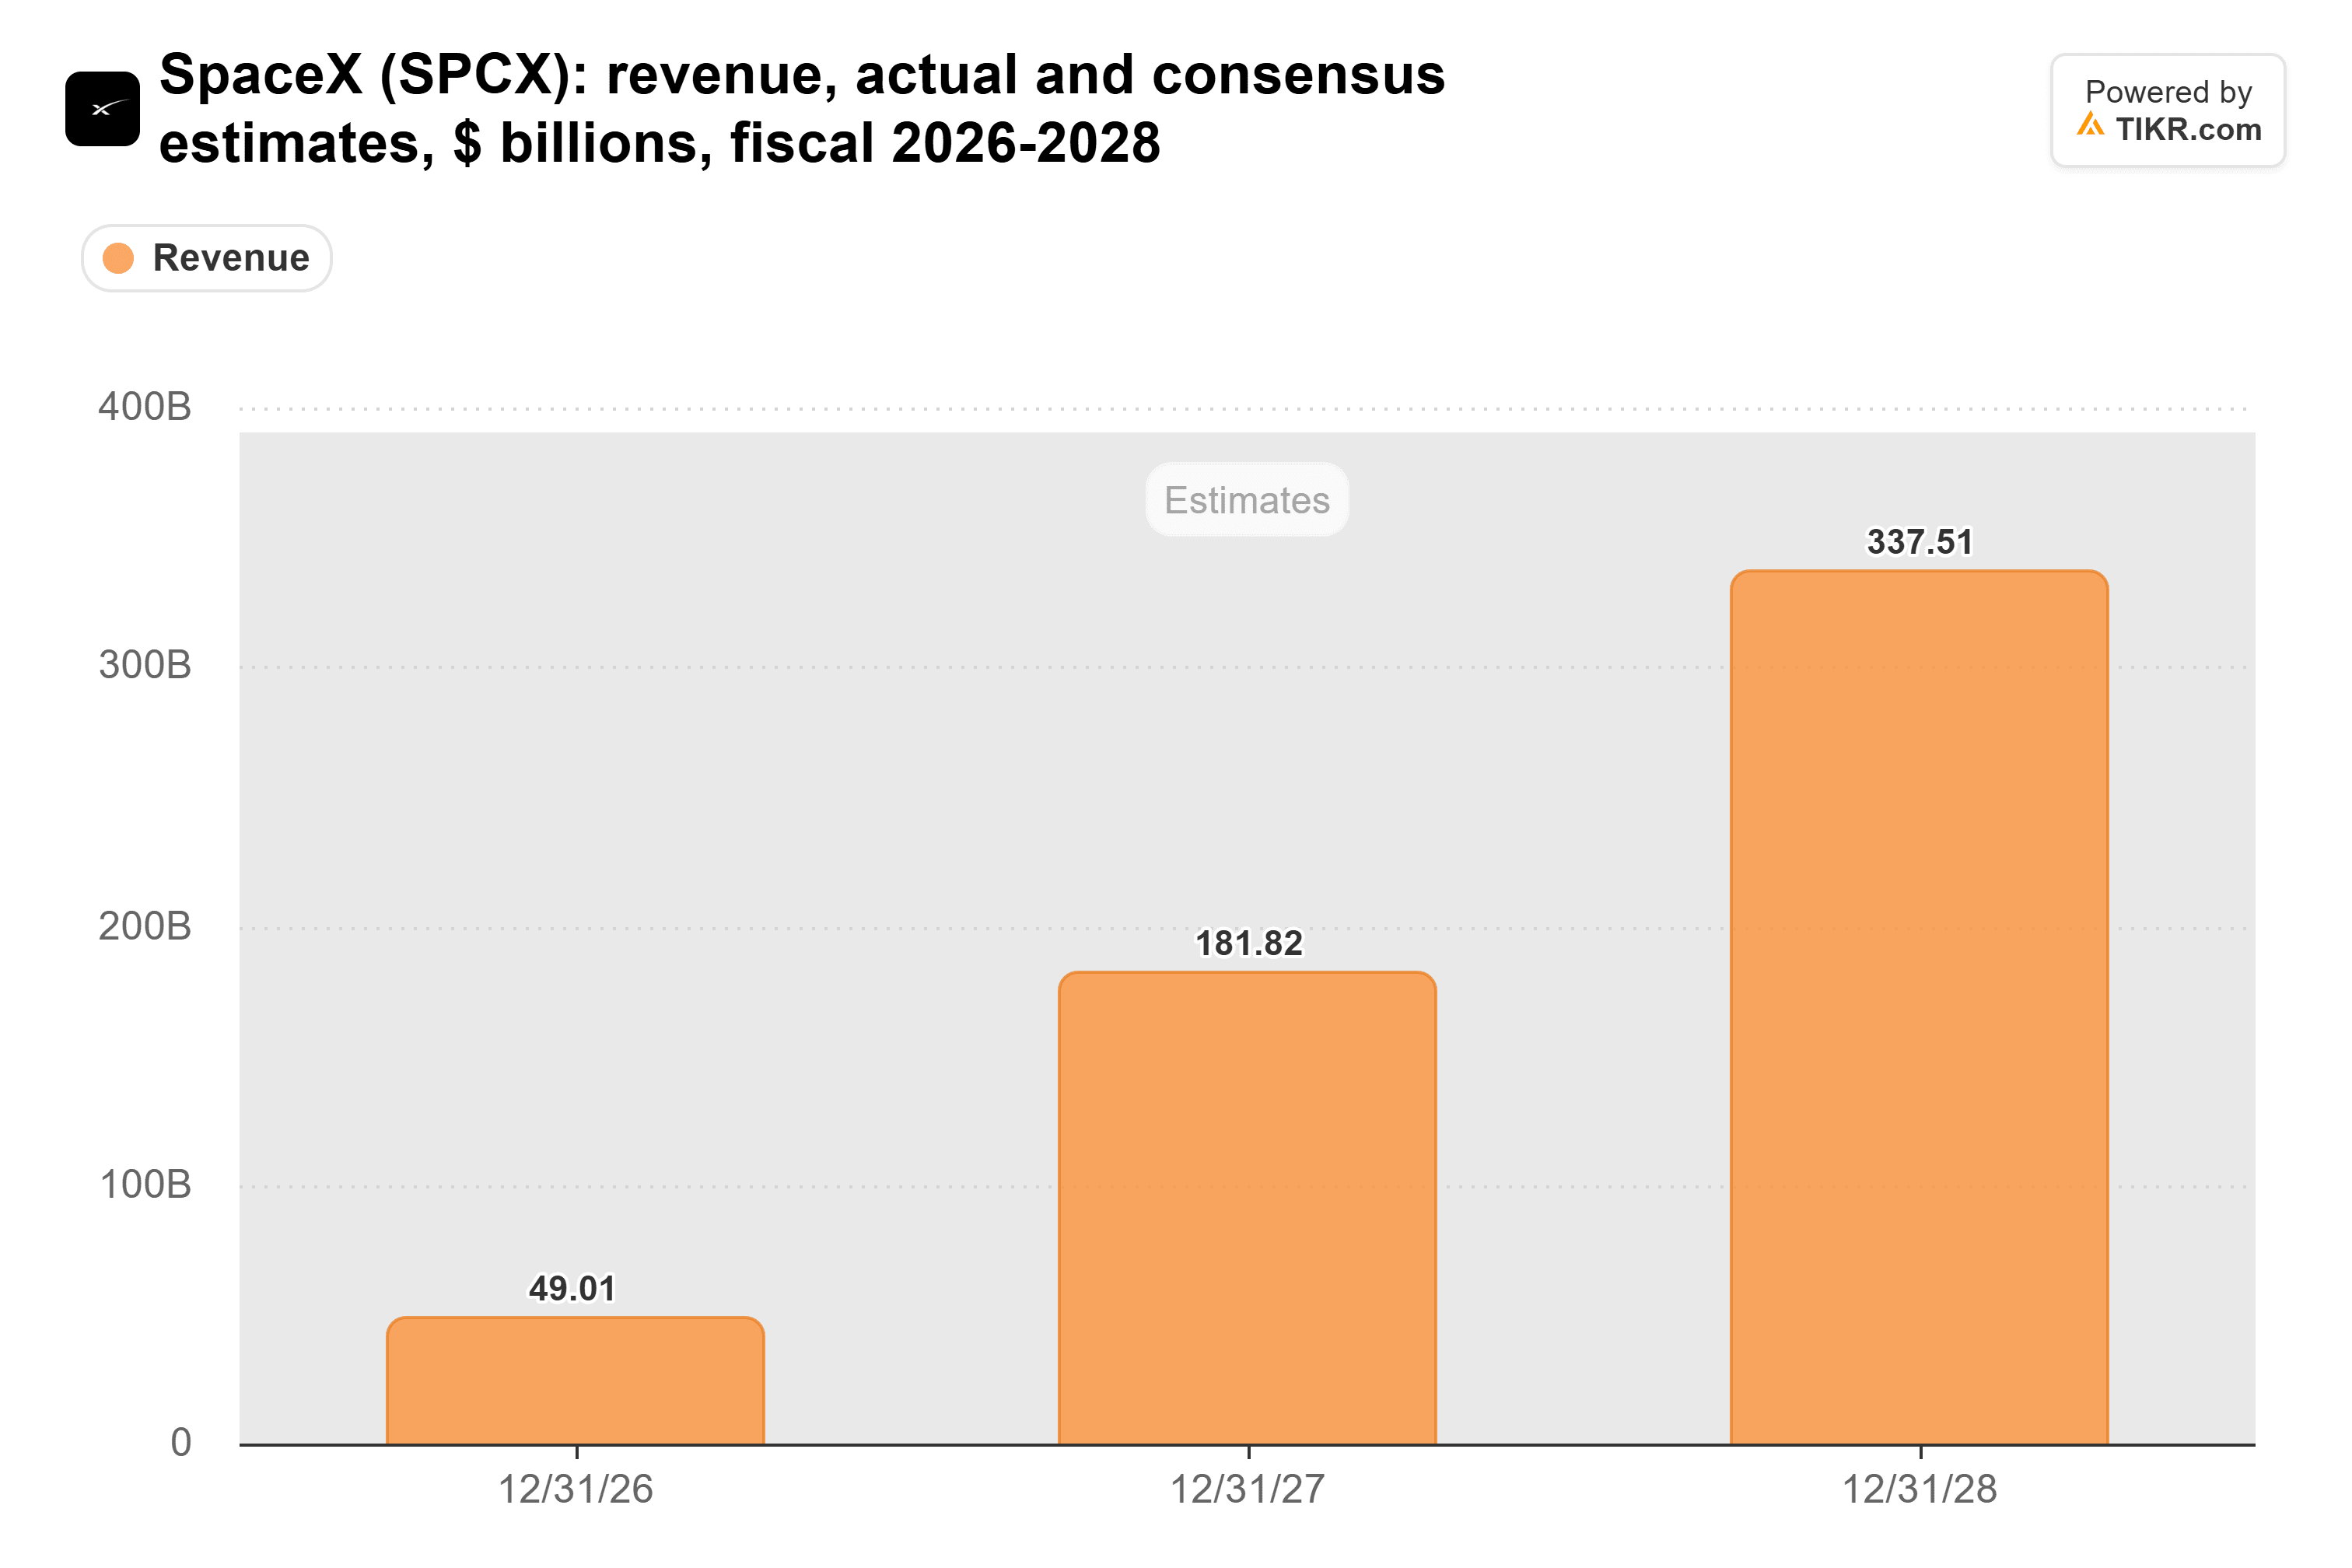
Musk can say that because SpaceX’s compute business is already selling plenty without OpenAI: its Super Intelligence segment brought in $7.56 billion of revenue in the third quarter, up from $2.56 billion in the second. And analysts expect SpaceX’s revenue to grow nearly 4x from this year to next:
AMD’s ramp has OpenAI’s name on it
AMD is in a very different spot. OpenAI and AMD have announced a buildout of up to 6 gigawatts of AMD GPUs.
Analysts expect AMD’s revenue to nearly triple from 2025 to 2027:
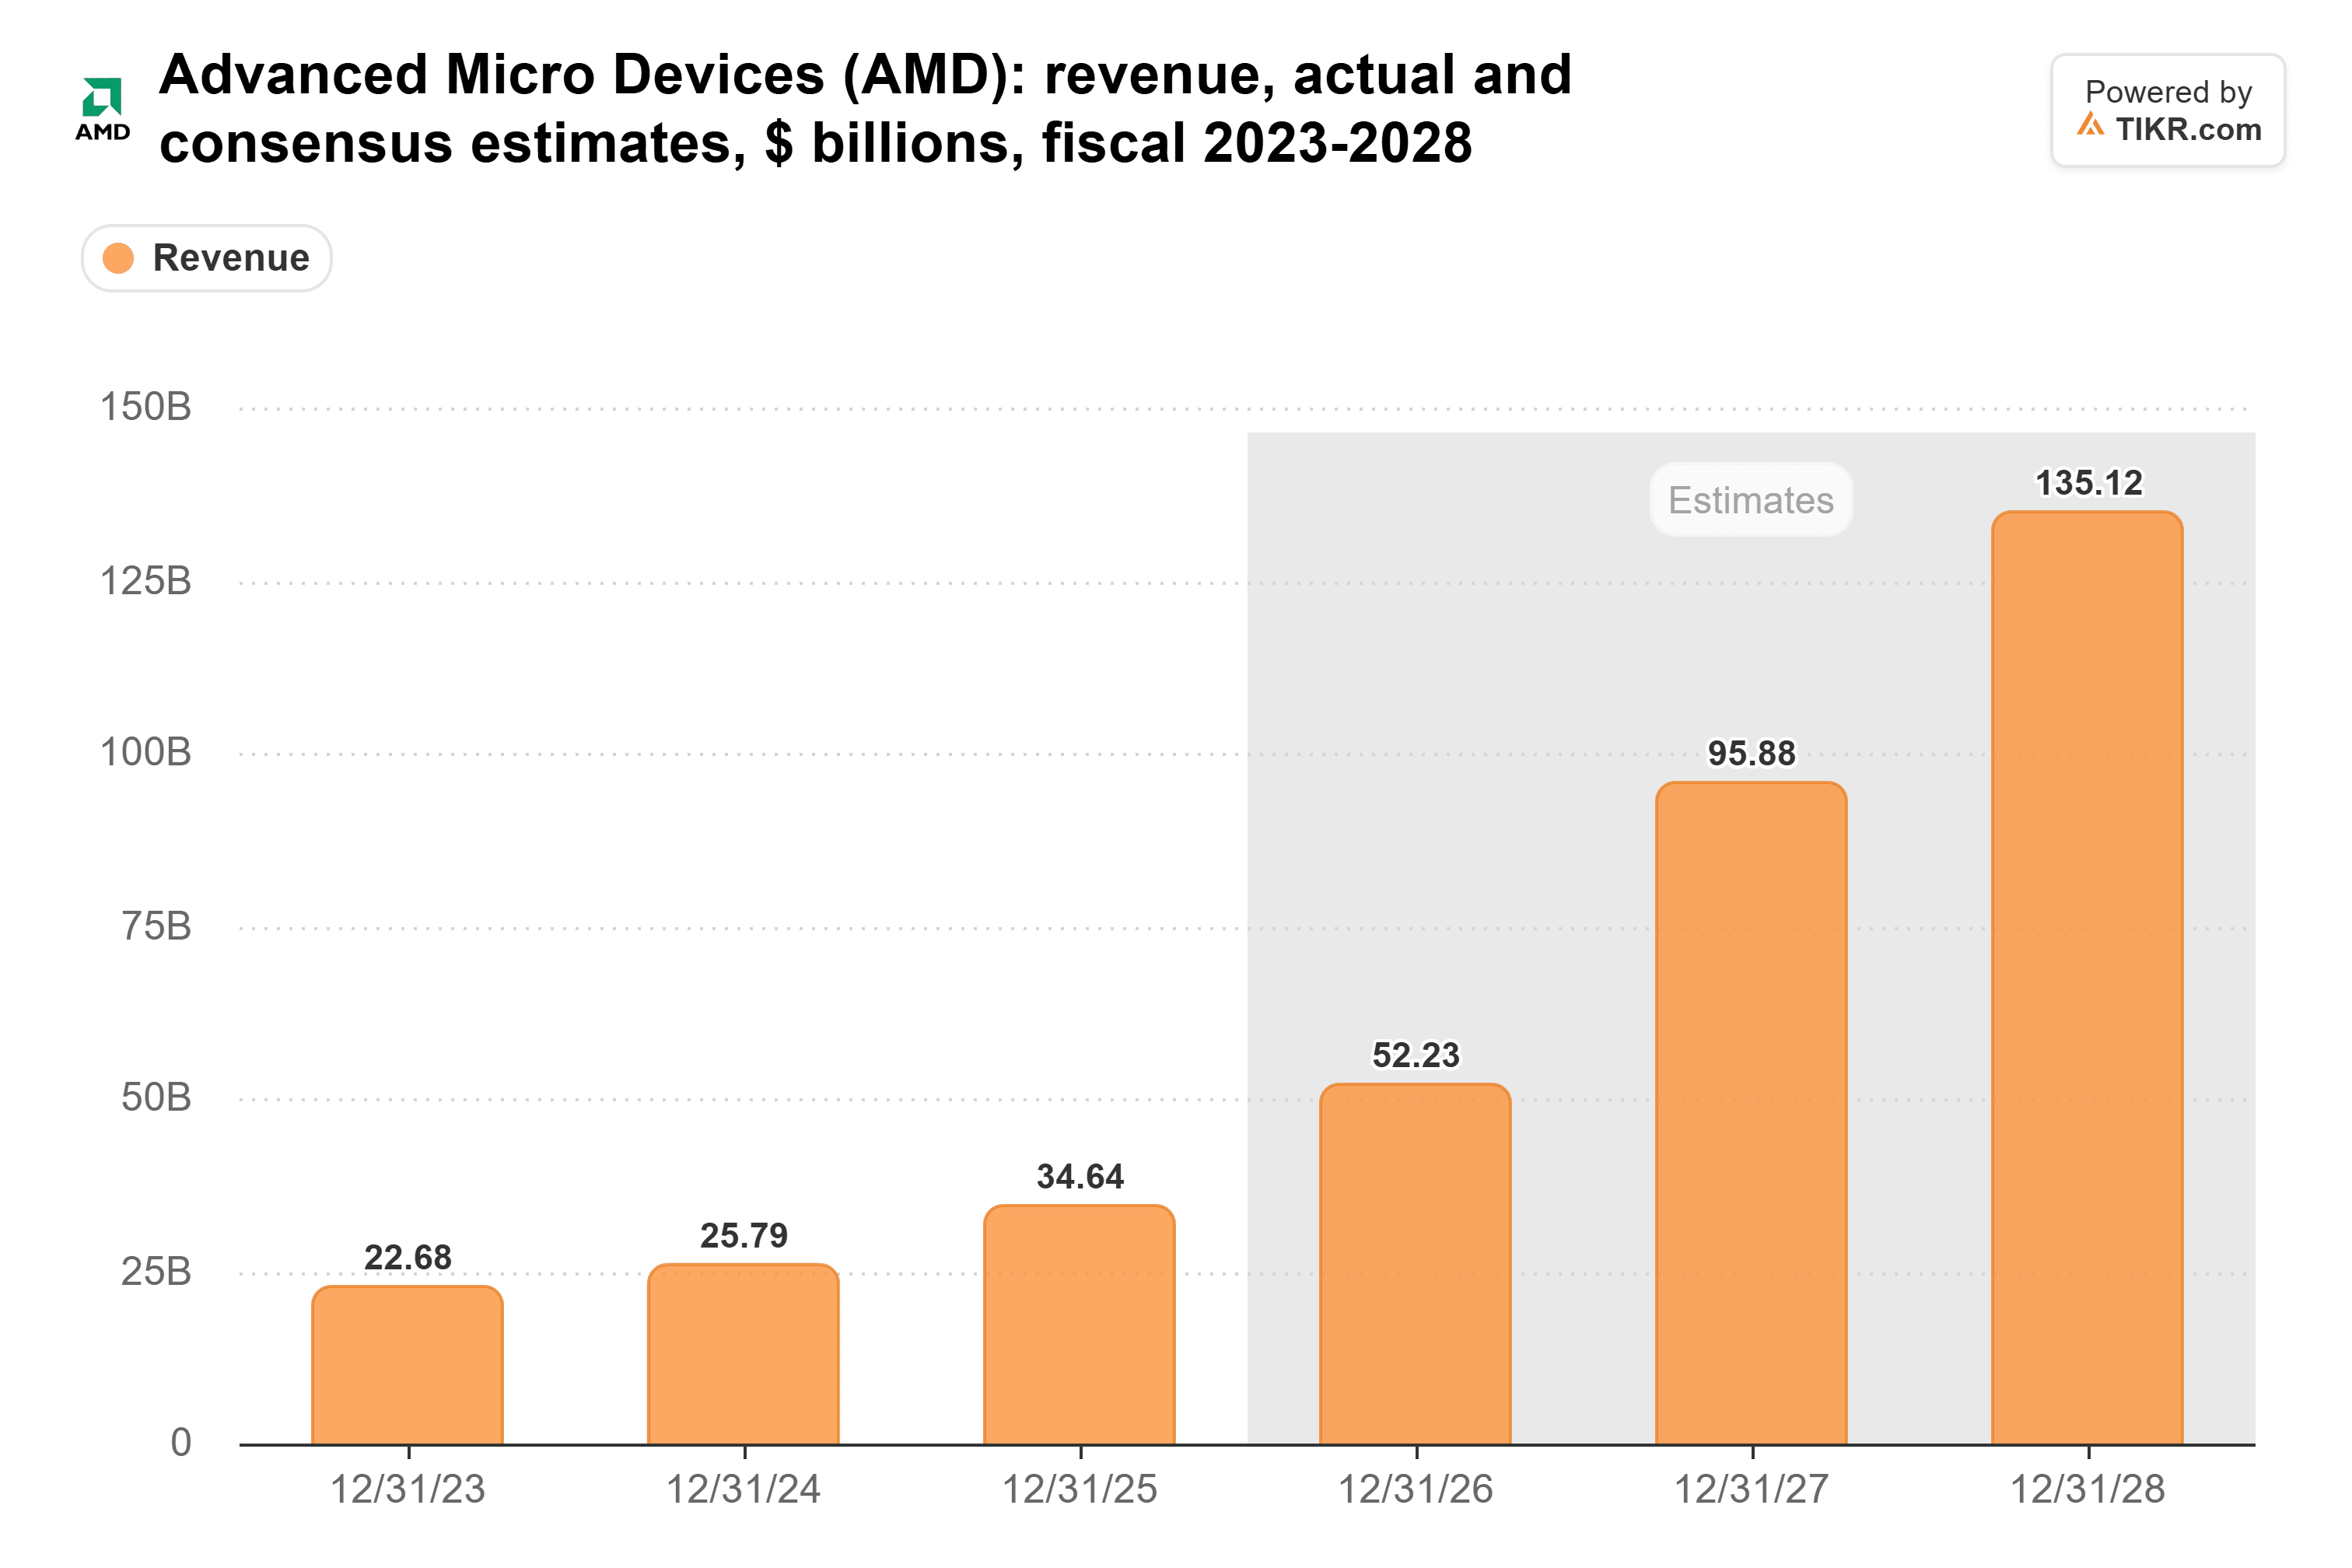
A good chunk of that 2027 jump depends on OpenAI’s gigawatts arriving, and getting paid for, on schedule. That’s why AMD has the most riding on OpenAI’s cash burn, and why its estimates have the most room to fall if Altman is right.
TIKR tracks 40 analysts on SpaceX. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SpaceX, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SpaceX’s Analyst Ratings
OpenAI’s losses are Oracle’s problem too
A supplier can live with a customer that loses money, as long as it keeps raising more. OpenAI’s revenue rose about 50% from the second quarter to $10 billion in the third, but its adjusted operating loss was $10.9 billion, the Wall Street Journal reported. Its latest funding round has reached about $15 billion, CNBC reported, not much more than that one quarter’s loss.
Oracle has spent heavily on data center capacity for OpenAI, which S&P estimated in July makes up about half of Oracle’s backlog. Its free cash flow went from $11.8 billion in fiscal 2024 to negative $23.7 billion in fiscal 2026, the year ended May 2026:
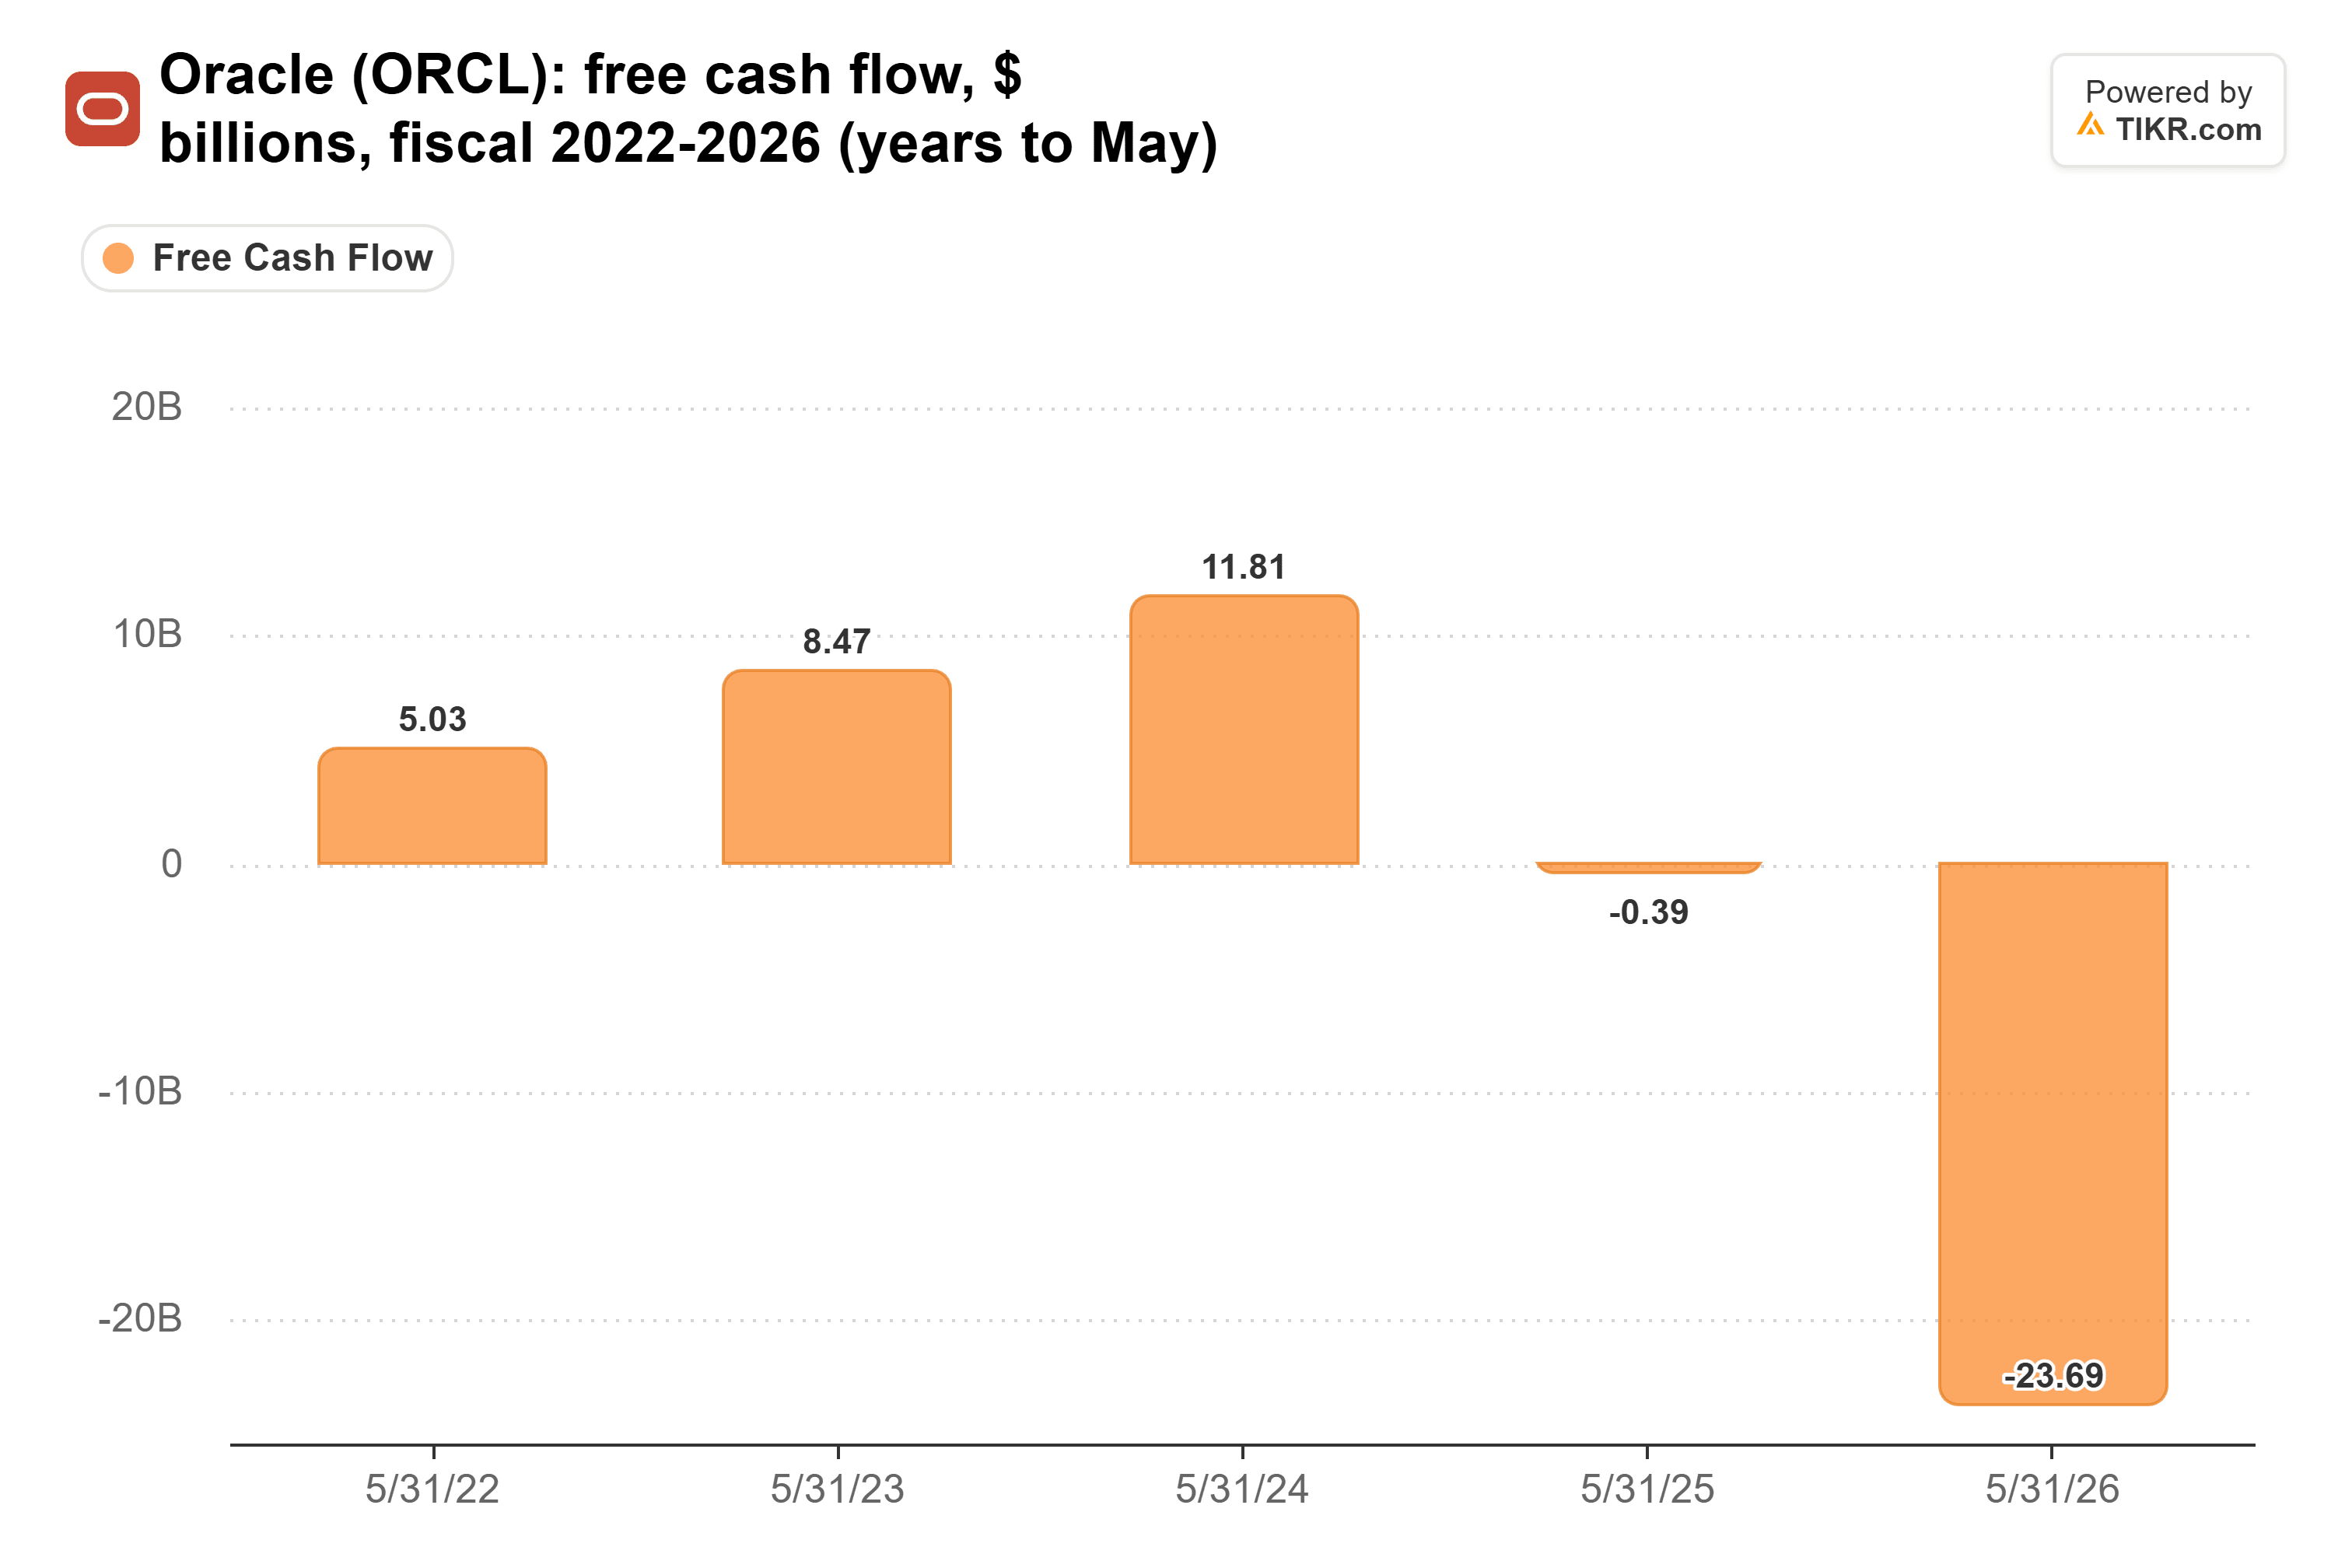
That money is already spent, and it only pays off if OpenAI grows into the capacity and keeps paying for it.
SpaceX has a big customer of its own
SpaceX does lean heavily on one AI lab, though. One customer supplied 34.5% of SpaceX’s third-quarter revenue, its 10-Q shows, and Bloomberg has reported that the customer is Anthropic. SpaceX’s original contract with Anthropic ran $1.25 billion a month through May 2029, and Anthropic’s IPO filing shows it has since agreed to spend up to $120.5 billion with SpaceX through 2029. But either side can still walk away on 90 days’ notice.
Still, Anthropic is the better customer to be owed money by. Its IPO filing shows a $567 million operating loss on $17 billion of third-quarter revenue, before any adjustments. Anthropic’s lead on revenue backs Musk’s jab about OpenAI’s products, and its IPO this week should put even more cash behind those monthly payments.
Musk’s jab lands. AMD and Oracle sized their plans around a customer losing billions a quarter. SpaceX rents to one that nearly breaks even. Of course, that could change fast. The next tests are AMD’s fourth-quarter report early next year, to see whether its $95.9 billion 2027 consensus holds, and SpaceX’s fourth-quarter results, which will show whether that one customer is still near 34.5% of revenue.
So what is SpaceX stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SpaceX could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!