

Key Takeaways
- At a Senate Budget Committee hearing this week, Sen. Mark Warner floated raising Social Security’s full retirement age to 68 by 2050 and 69 by 2075, but he gave no schedule for phasing it in.
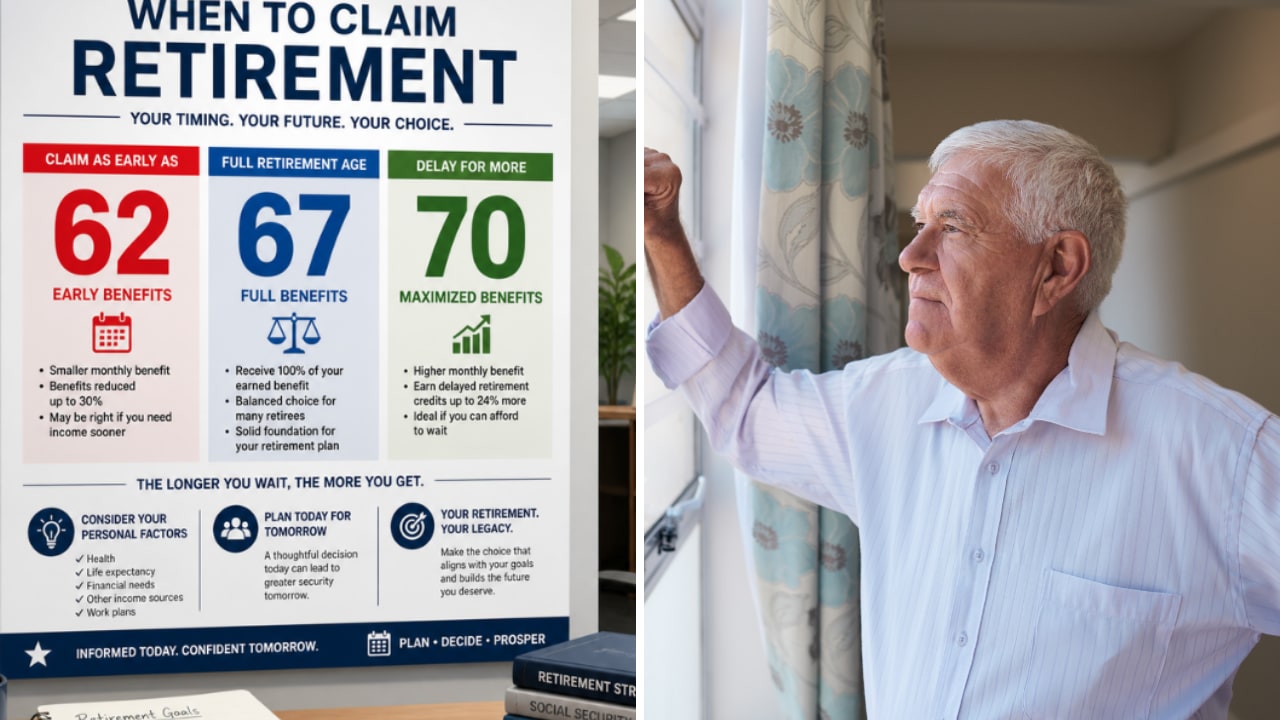
- Today, full retirement age is 67 for anyone born in 1960 or later. Each year of waiting after that adds 8% until 70, so a $2,000 benefit grows to $2,480 a month.
- If full retirement age were 68 and the credits stayed the same, a 40-year-old with a $2,000 benefit who waits until 70 would get $2,320 a month. That’s $1,920 a year less.
- A retiree who’s already collecting is a long way from a schedule that runs to 2050. Younger workers planning to wait until 70 are the ones who should run their numbers both ways.
Raising Social Security’s full retirement age is back on the table in Washington. At a Senate Budget Committee hearing this week, Sen. Mark Warner (D-Va.) said Congress could “slightly adjust the age the same way Tip O’Neill and Ronald Reagan did in 1983,” with a full retirement age of 68 by 2050 and 69 by 2075. “That gives you a lot of room,” he said.
The age was one of three fixes he listed, along with raising the cap on earnings that pay Social Security tax. He didn’t say how the new age would phase in. But if you’re decades from retiring and planning to wait until 70 for the biggest check, here’s the bad news: a later full retirement age makes the reward for waiting smaller.
Today, waiting until 70 adds 24%
Let’s take a hypothetical: you’re 40, and your Social Security statement puts your benefit at full retirement age at $2,000 a month. You were born in the mid-1980s, so you fall under today’s rule for anyone born in 1960 or later, and your full retirement age is 67. From there, each year you wait adds 8% to the check, and the increase stops at 70. If you wait the full three years, you get 24% more, and your $2,000 becomes $2,480 a month for life.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
At 68, the same wait pays $160 a month less
Now say Congress moves your full retirement age to 68, and the credits still pay 8% a year and still stop at 70. Your $2,000 would arrive at 68 instead of 67, so waiting until 70 would earn two years of credits instead of three. Two years at 8% is 16%, which makes the check at 70 $2,320 a month. That’s $160 a month less than under today’s rules, or $1,920 a year across 12 checks, for as long as you collect.
Anyone young enough to face a full retirement age of 69 would have only one year of credits left. Their $2,000 would become $2,160 at 70, which is $320 a month less than today’s $2,480. And people who wait wouldn’t be the only ones getting a smaller check. With the full $2,000 arriving later, claiming at 67 or earlier would come with a reduction for claiming early.
A retiree today is a long way from 2050
At 40, you’d turn 68 in the mid-2050s, after Warner’s 2050 date. So if a full retirement age of 68 were in place by then, it would apply to you in full. And since Warner gave no schedule, there’s no telling whether 69 would reach you too.
Now take a hypothetical 66-year-old who’s already collecting. Nothing Warner described touches a check that’s already being paid, and the 1983 change he pointed to took decades to arrive. Jason Fichtner, executive director of the LIMRA Retirement Income Institute, told the committee that the 1983 law raised the full retirement age from 65 to 67 “over a 40 year period.” That slow pace is also the catch with Warner’s “lot of room.” As Fichtner put it, a change made that way “wouldn’t affect the cash flows coming in, but it would affect future beneficiaries.”
Plan for 70 at both numbers
Under today’s law, nothing has changed: your full retirement age is 67, and waiting until 70 still adds 24%. If waiting is your plan, pull up your Social Security statement and find the estimate at 70. Then run your budget at the lower figure too: $2,320 for every $2,000 of full benefit. Frankly, I’d still wait under Warner’s idea, since a 16% raise for life is a lot to pass up. But if that extra $160 a month was the cushion in your plan, you’ve got decades to build it somewhere else.
For now, it’s just an idea Warner floated at a hearing. Before any of these numbers become real, Congress would have to decide when 68 phases in and whether the credits stay at 8% a year until 70. With the retirement trust fund’s reserves projected to run out in the fourth quarter of 2032, per the 2026 Trustees Report, I wouldn’t expect the debate to go away.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!






