Key Takeaways
- Prana Capital Management, which manages $4.31 billion, sold all of its HCA Healthcare, Berkshire Hathaway and PulteGroup stock in the third quarter.
- All three stocks have risen since Sept. 30. Analysts’ average targets now sit just 2% above HCA’s price, 6% above PulteGroup’s and below Berkshire’s.
- In the same quarter, the fund more than doubled its Nasdaq stake and grew its Citigroup stake more than fivefold, and analysts see 36% upside in Citi.
- Berkshire’s sale is the easiest to defend: it trades at about 25x forward earnings, and analysts expect earnings to barely grow.
Prana Capital Management held HCA Healthcare (HCA), Berkshire Hathaway (BRK.B) and PulteGroup (PHM) at the end of June. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows none of them.
The firm manages $4.31 billion, and its 13F holds $3.11 billion of US stocks in 122 positions. In the same quarter, it more than doubled its Nasdaq (NDAQ) stake and grew its Citigroup (C) stake more than fivefold.
All three stocks it sold have climbed since Sept. 30. Analysts don’t see much more in them.
HCA’s rebound has mostly played out
Prana held 193,779 HCA shares at June 30, worth $76 million, or 2.3% of its 13F stocks. The stock is up 11% since Sept. 30.
The business is holding up. In its Oct. 27 release, HCA reported third-quarter revenue up 3.6% to $19.85 billion and GAAP diluted EPS up 4.5% to $7.27, even as net income fell 3.9%. Management now expects full-year results in the upper half of the guidance ranges it set in July. It said that holds despite an unfavorable shift in its payer mix.
At the last close of $475.57, HCA trades at about 16x forward earnings. Analysts’ average target of $486 is just 2% above that, and it has barely moved in a year:
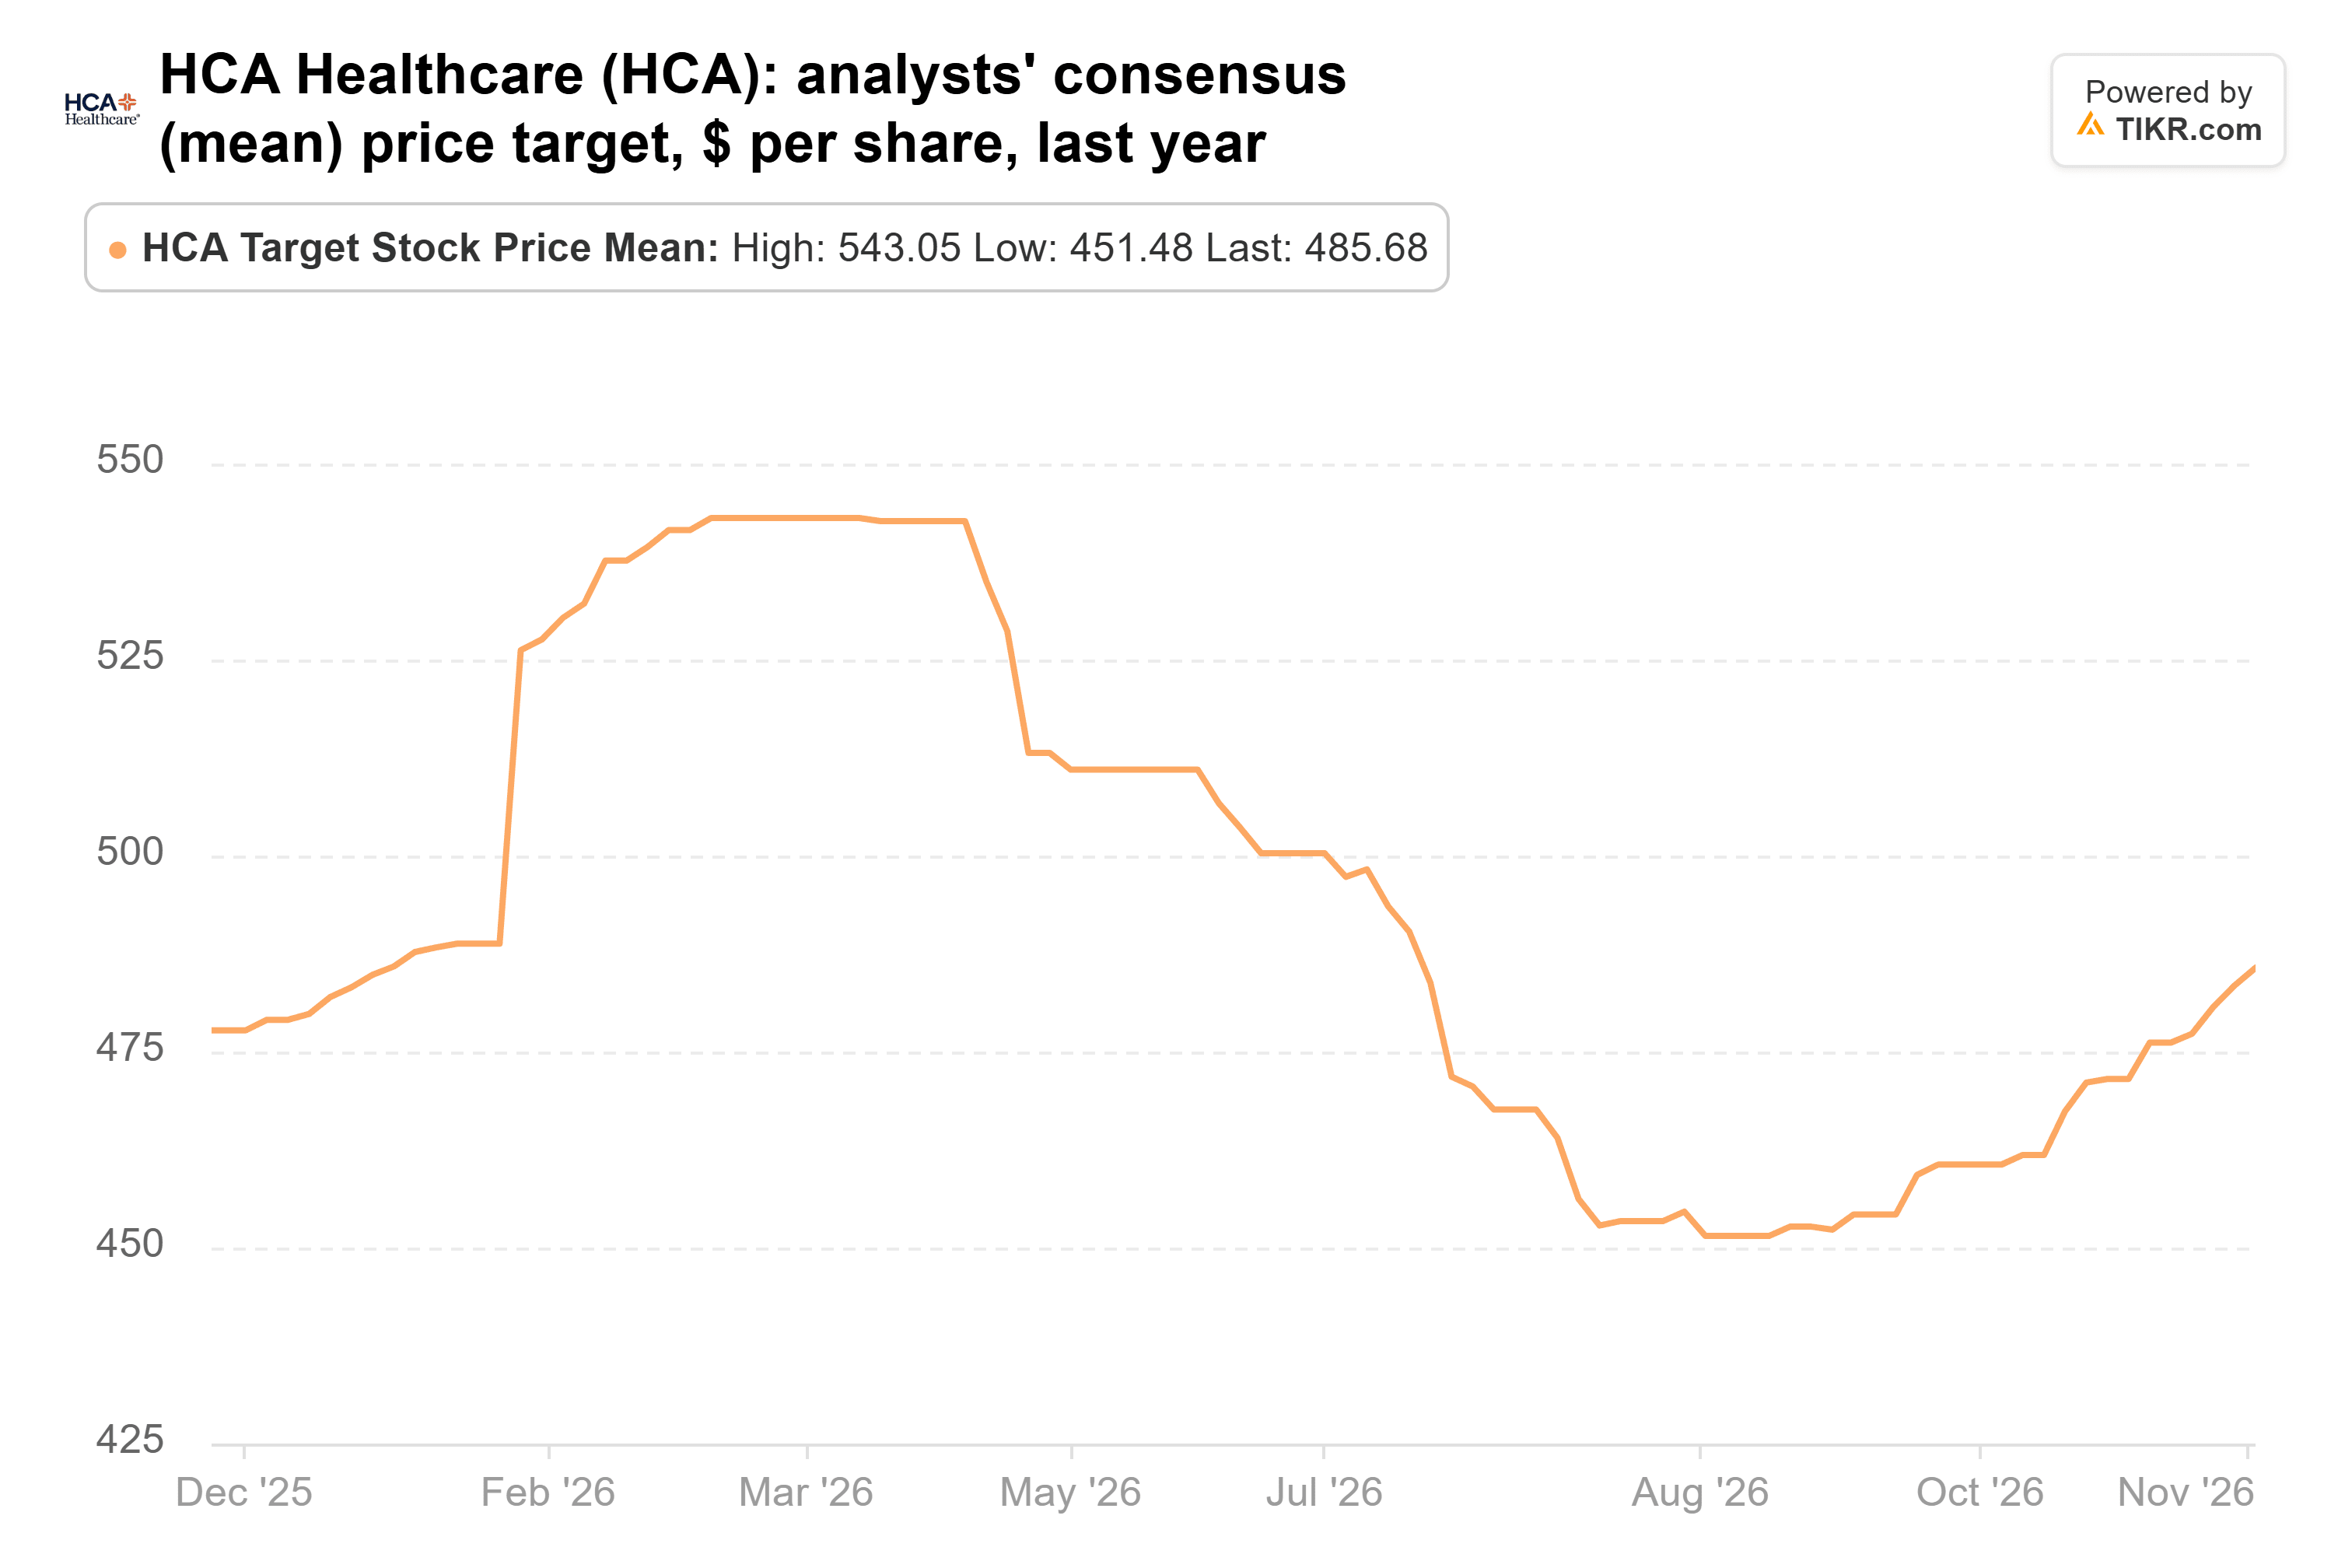
It peaked at $543 in March. With the stock 15% below its 52-week high, analysts see little left in the rebound.
TIKR tracks 26 analysts on HCA Healthcare. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on HCA Healthcare, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See HCA Healthcare’s Analyst Ratings
Berkshire is priced for more than its estimates show
Prana held 136,632 Class B shares at June 30, worth $68 million, or 2.1% of its 13F stocks. The stock is up 14% since Sept. 30.
That run followed a soft quarter. Berkshire’s third-quarter operating earnings fell 5.8% to $12.7 billion, and GEICO’s pre-tax underwriting profit dropped to $982 million from $1.77 billion. Buybacks picked up, though: $9.6 billion in the quarter, against $4.5 billion in the second.
At $570, Berkshire trades at about 25x forward earnings, above its five-year average of 22x. Analysts expect normalized EPS of $22.56 this year and $22.82 next, which is barely any growth. And the stock has already run past their average target:
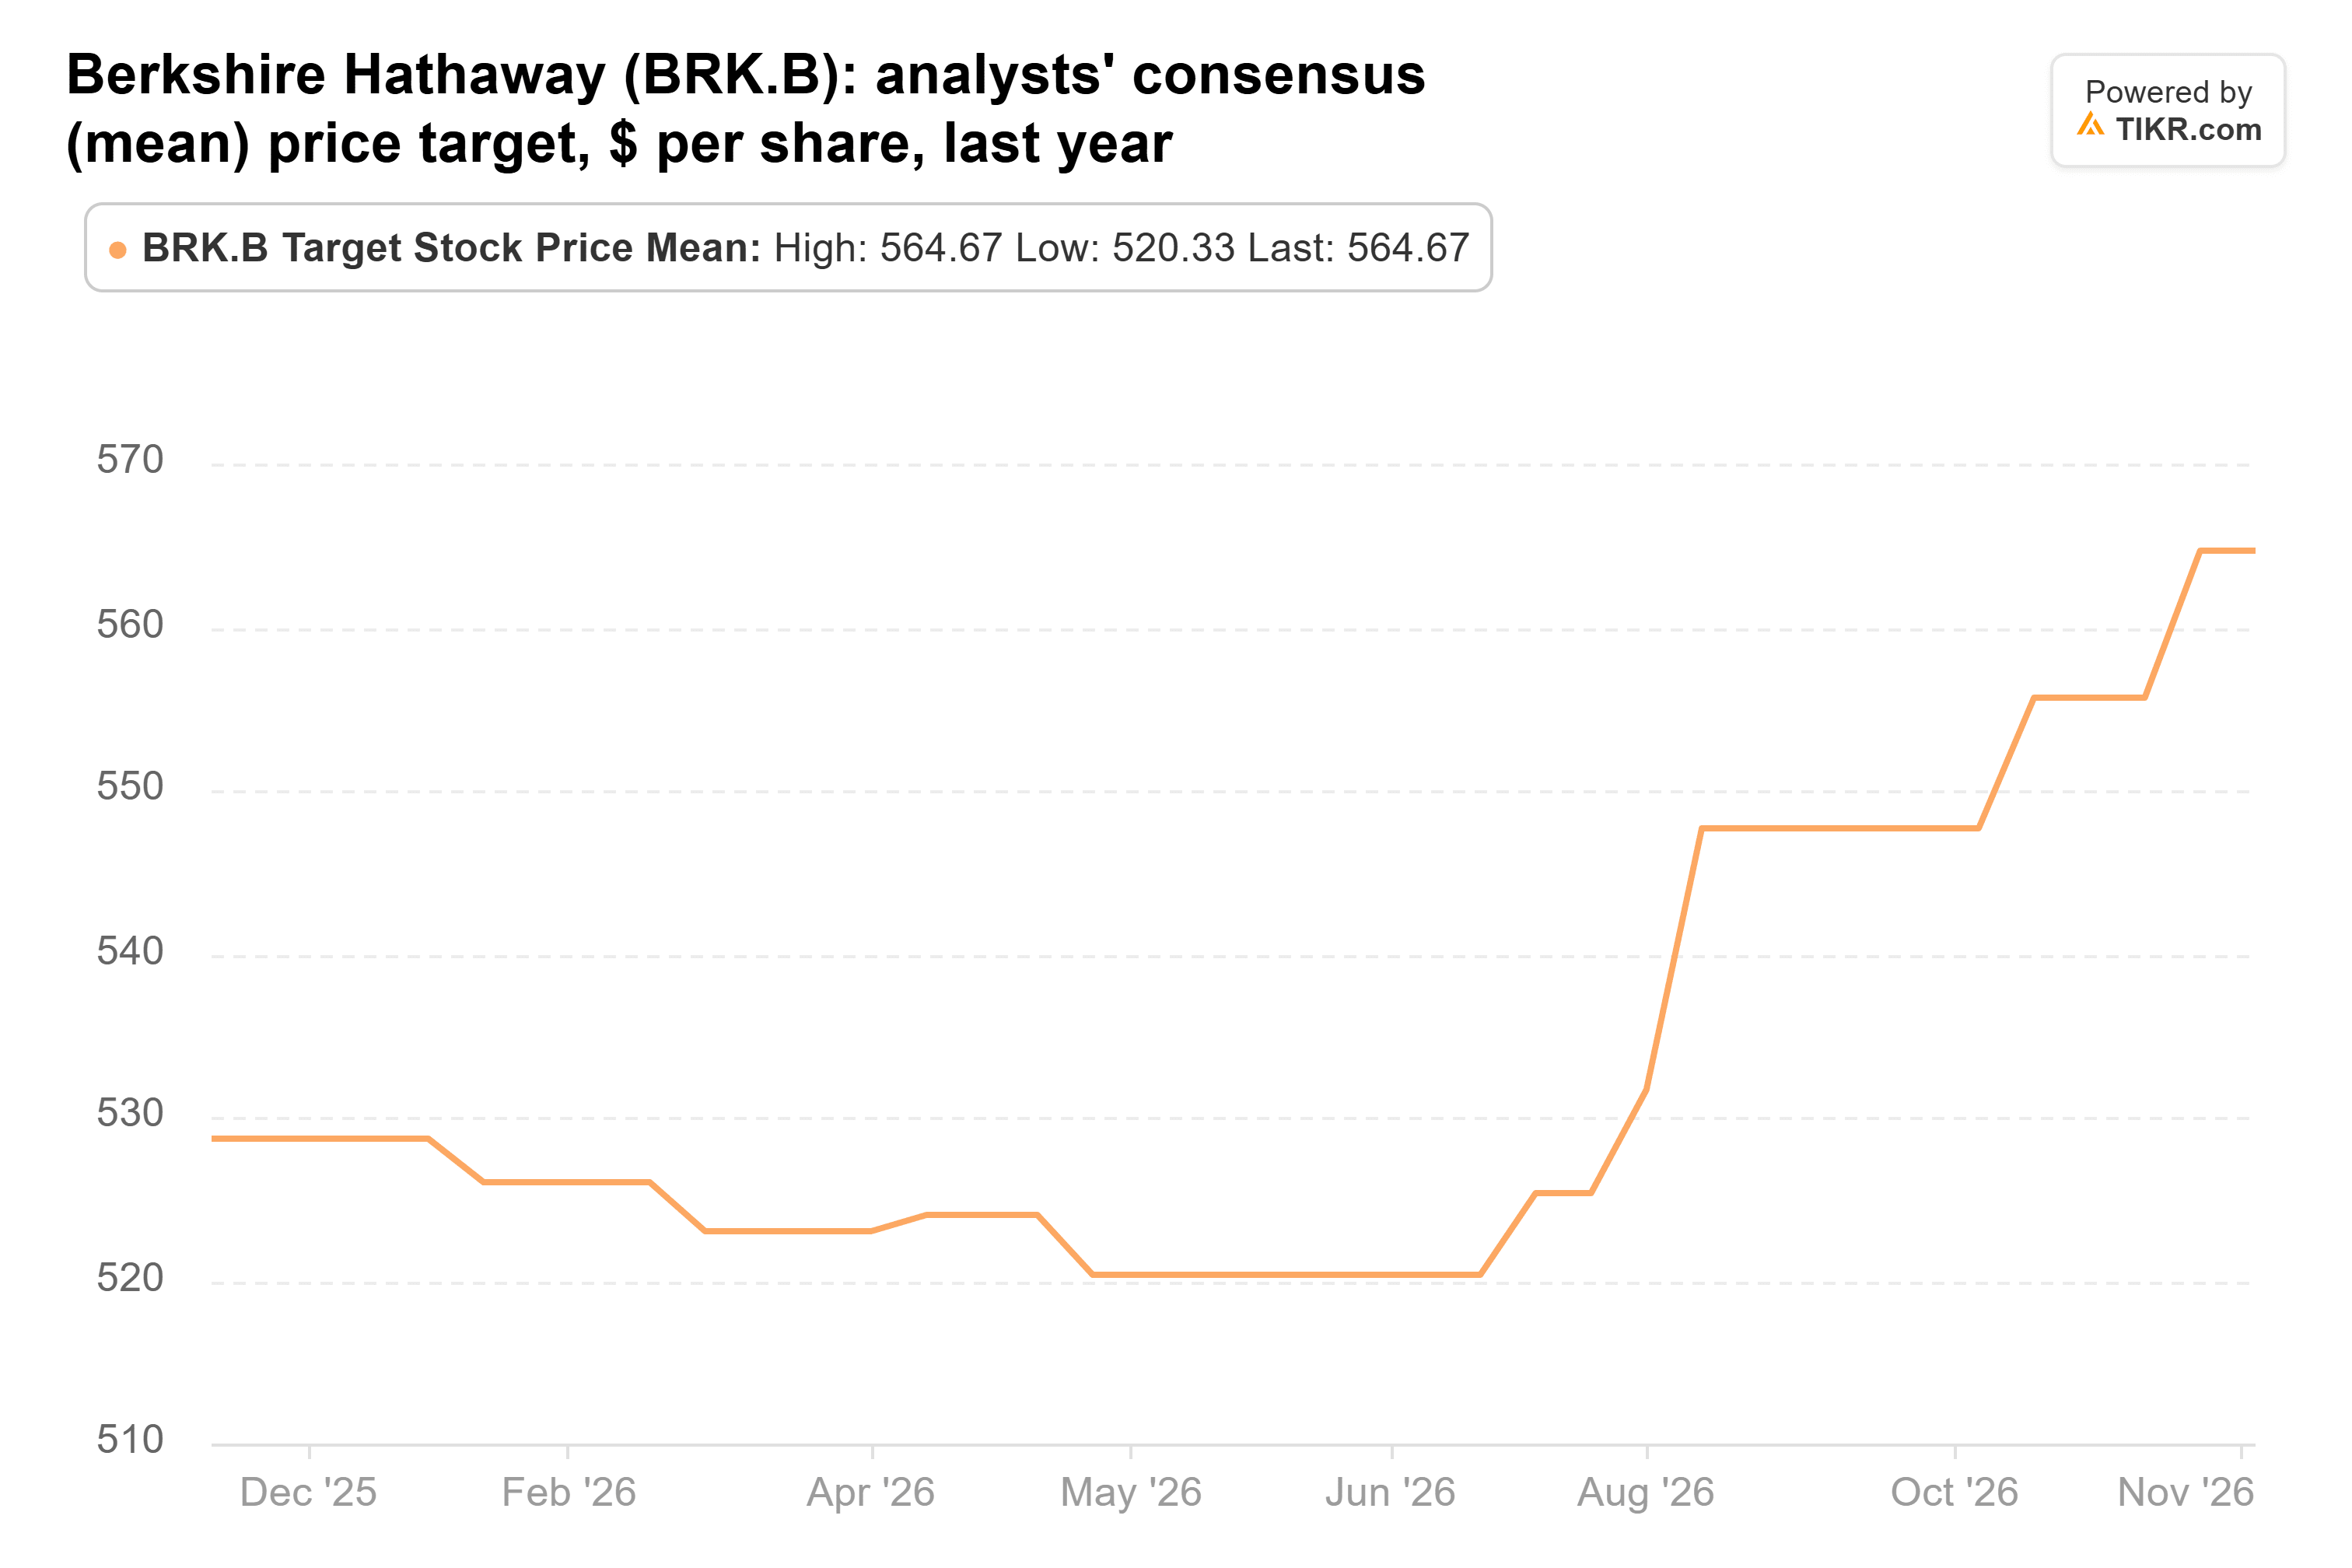
That target has climbed from $529 to $565 over the year and is still below the stock price.
PulteGroup’s orders keep shrinking
Prana and Berkshire part ways on homebuilding. Berkshire bought homebuilder Taylor Morrison for about $6.8 billion this year, while Prana sold all 441,025 of its PulteGroup shares, worth $61 million at June 30, or 1.8% of its 13F stocks. PulteGroup is up 7% since Sept. 30.
Its third quarter showed a housing market that’s still slowing. Closings fell 9% to 6,876 homes, orders fell 6% to 6,208, and home sale gross margin slipped to 24.8% from 26.2%. Land impairments took about 70 basis points off the latest figure. Backlog did rise 4%, to 10,298 homes.
At $124.67, PulteGroup trades at about 13x forward earnings. Its $132 average target is 6% above that price, but the target has been coming down all year:
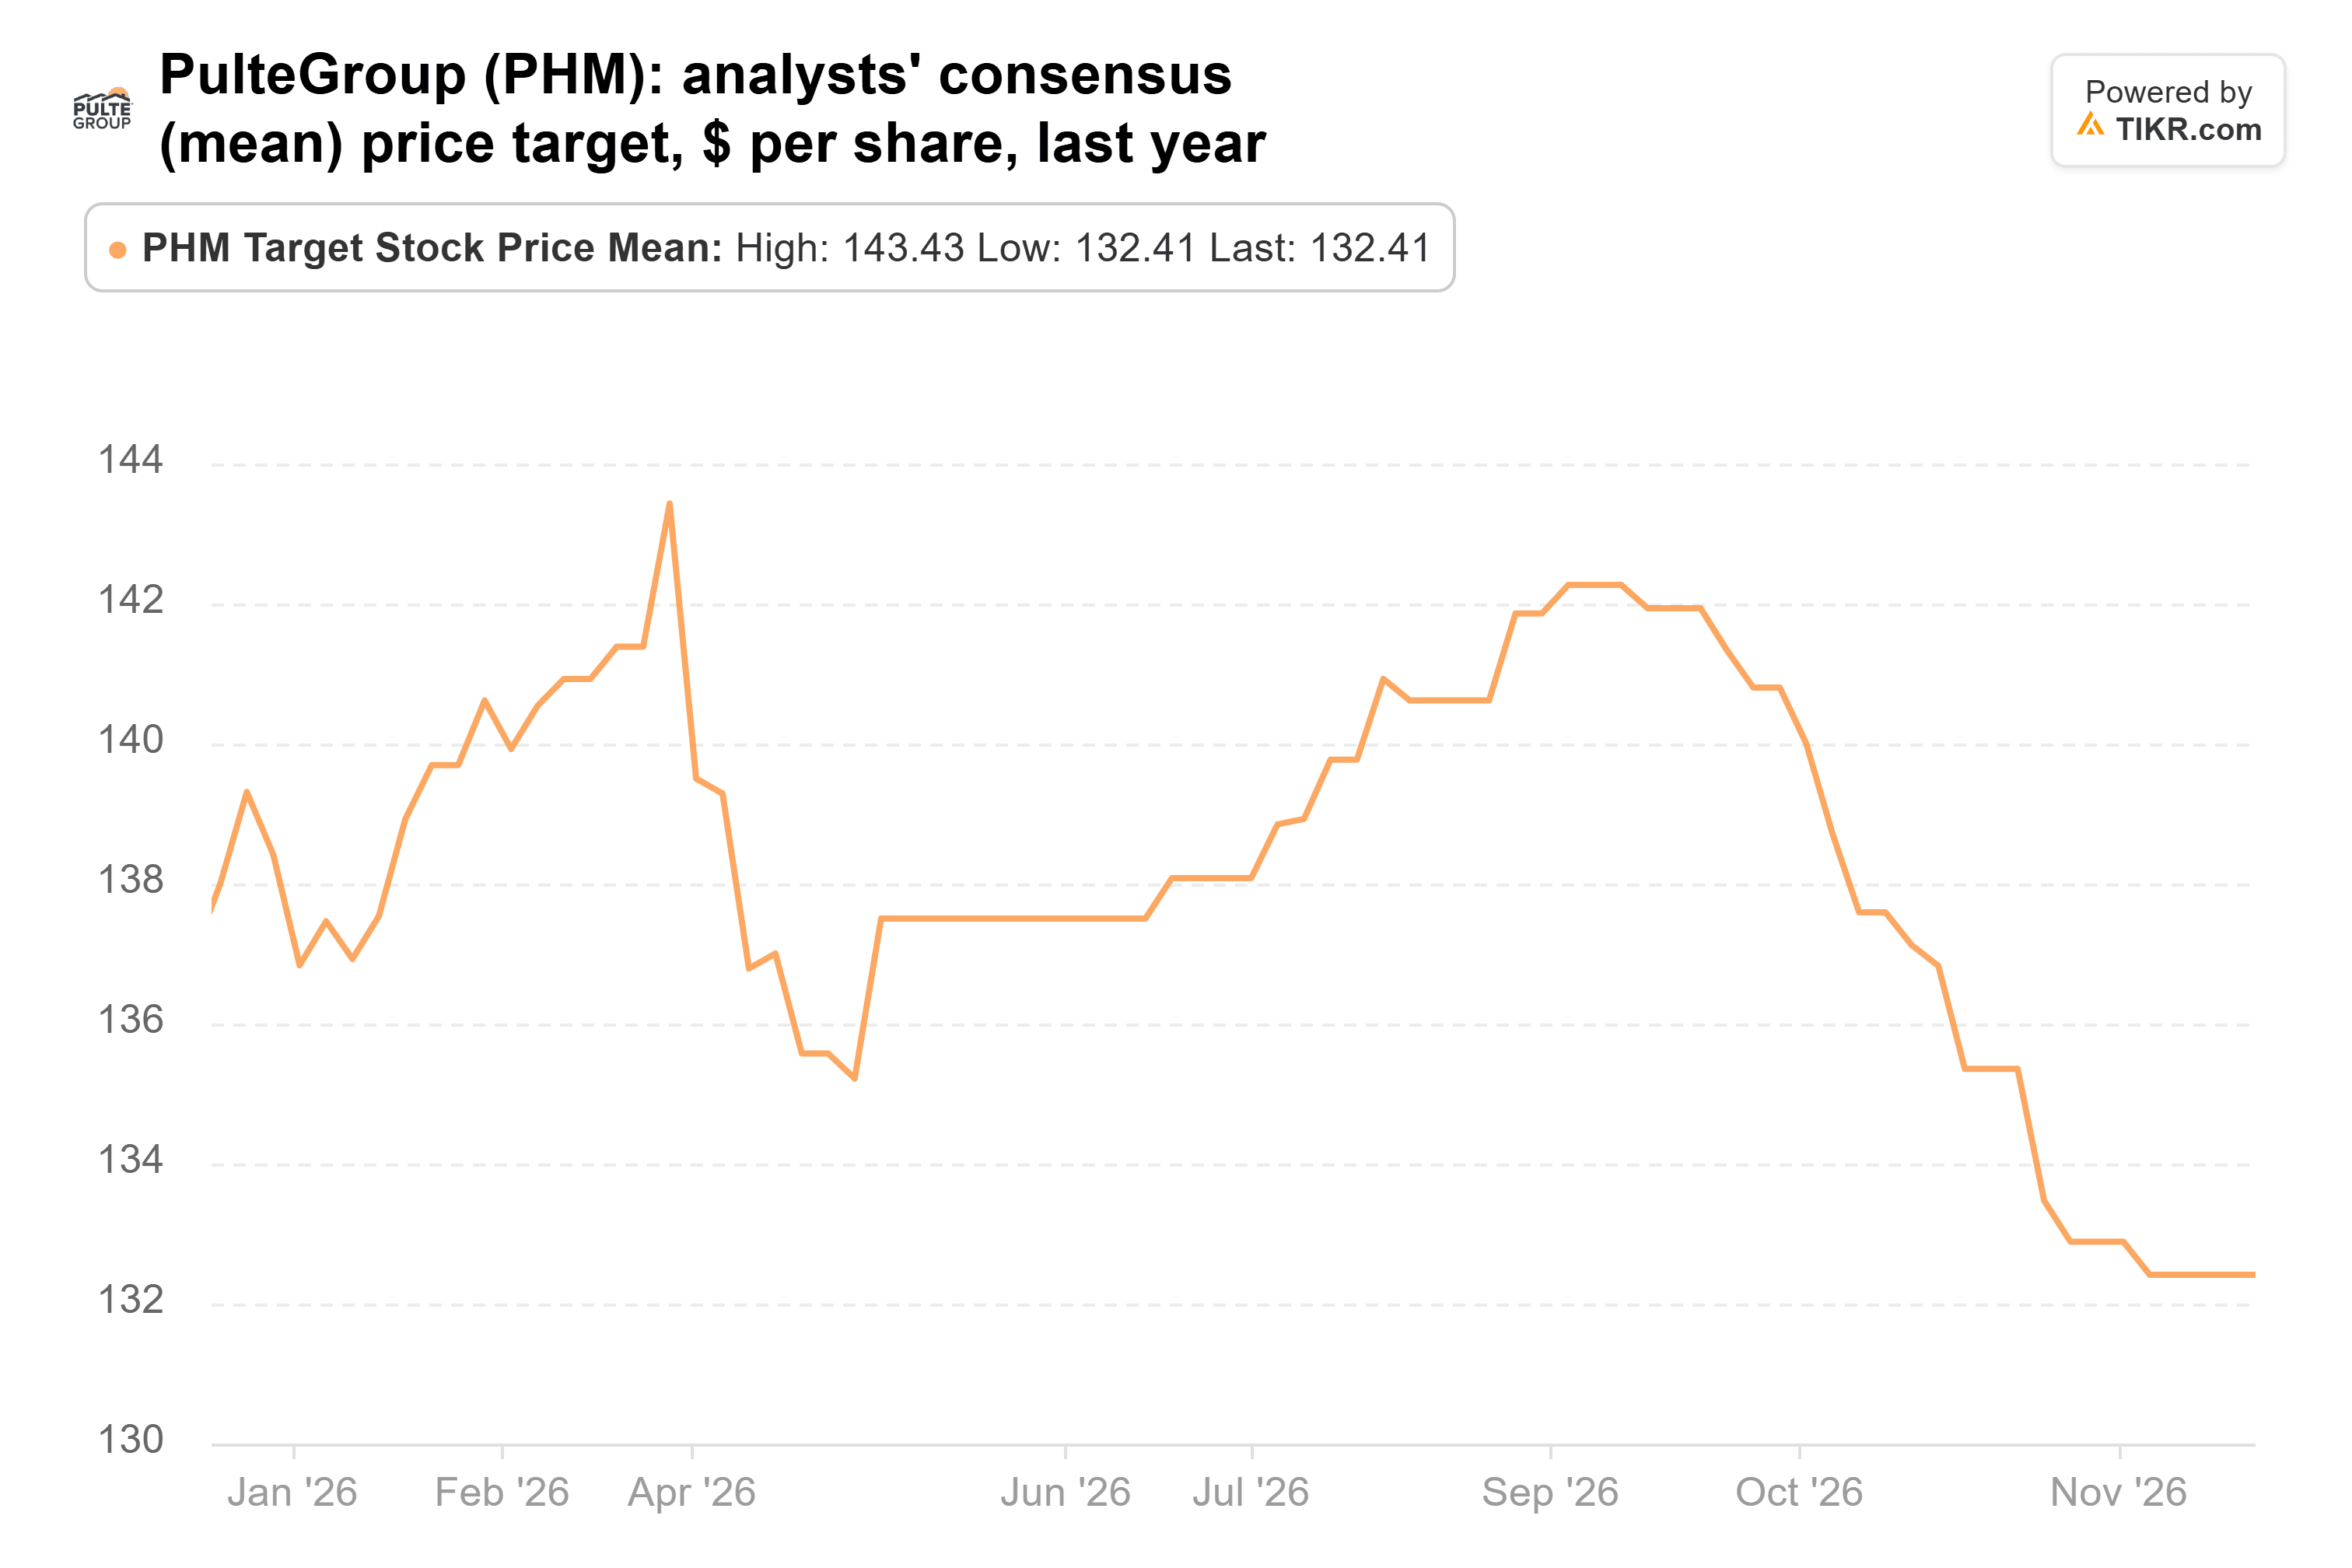
It’s down from $138 a year ago and $143 in March, and it hit its low for the year this month.
Where the Street sees more room
Analysts see more upside in the two stocks Prana added to. Its 957,241 Nasdaq shares were worth $88 million at Sept. 30, 2.8% of its 13F stocks, and it also held put options with a $4 million notional value. Nasdaq is up 12% since then and trades at about 22x forward earnings. Its $115 average target is 12% above the last close.
Citigroup has gone the other way. Prana’s 640,638 shares were worth $83 million at Sept. 30, 2.7% of its 13F stocks, and the stock is down 15% since then. Citi’s return on tangible common equity slipped to 11.5% in the third quarter from 13.0% in the second. Management expects fourth-quarter Markets revenue to fall about 20% or more from the third. At about 9x forward earnings, Citi trades below its one-year average of 11x, and analysts have raised their target sharply over the year:
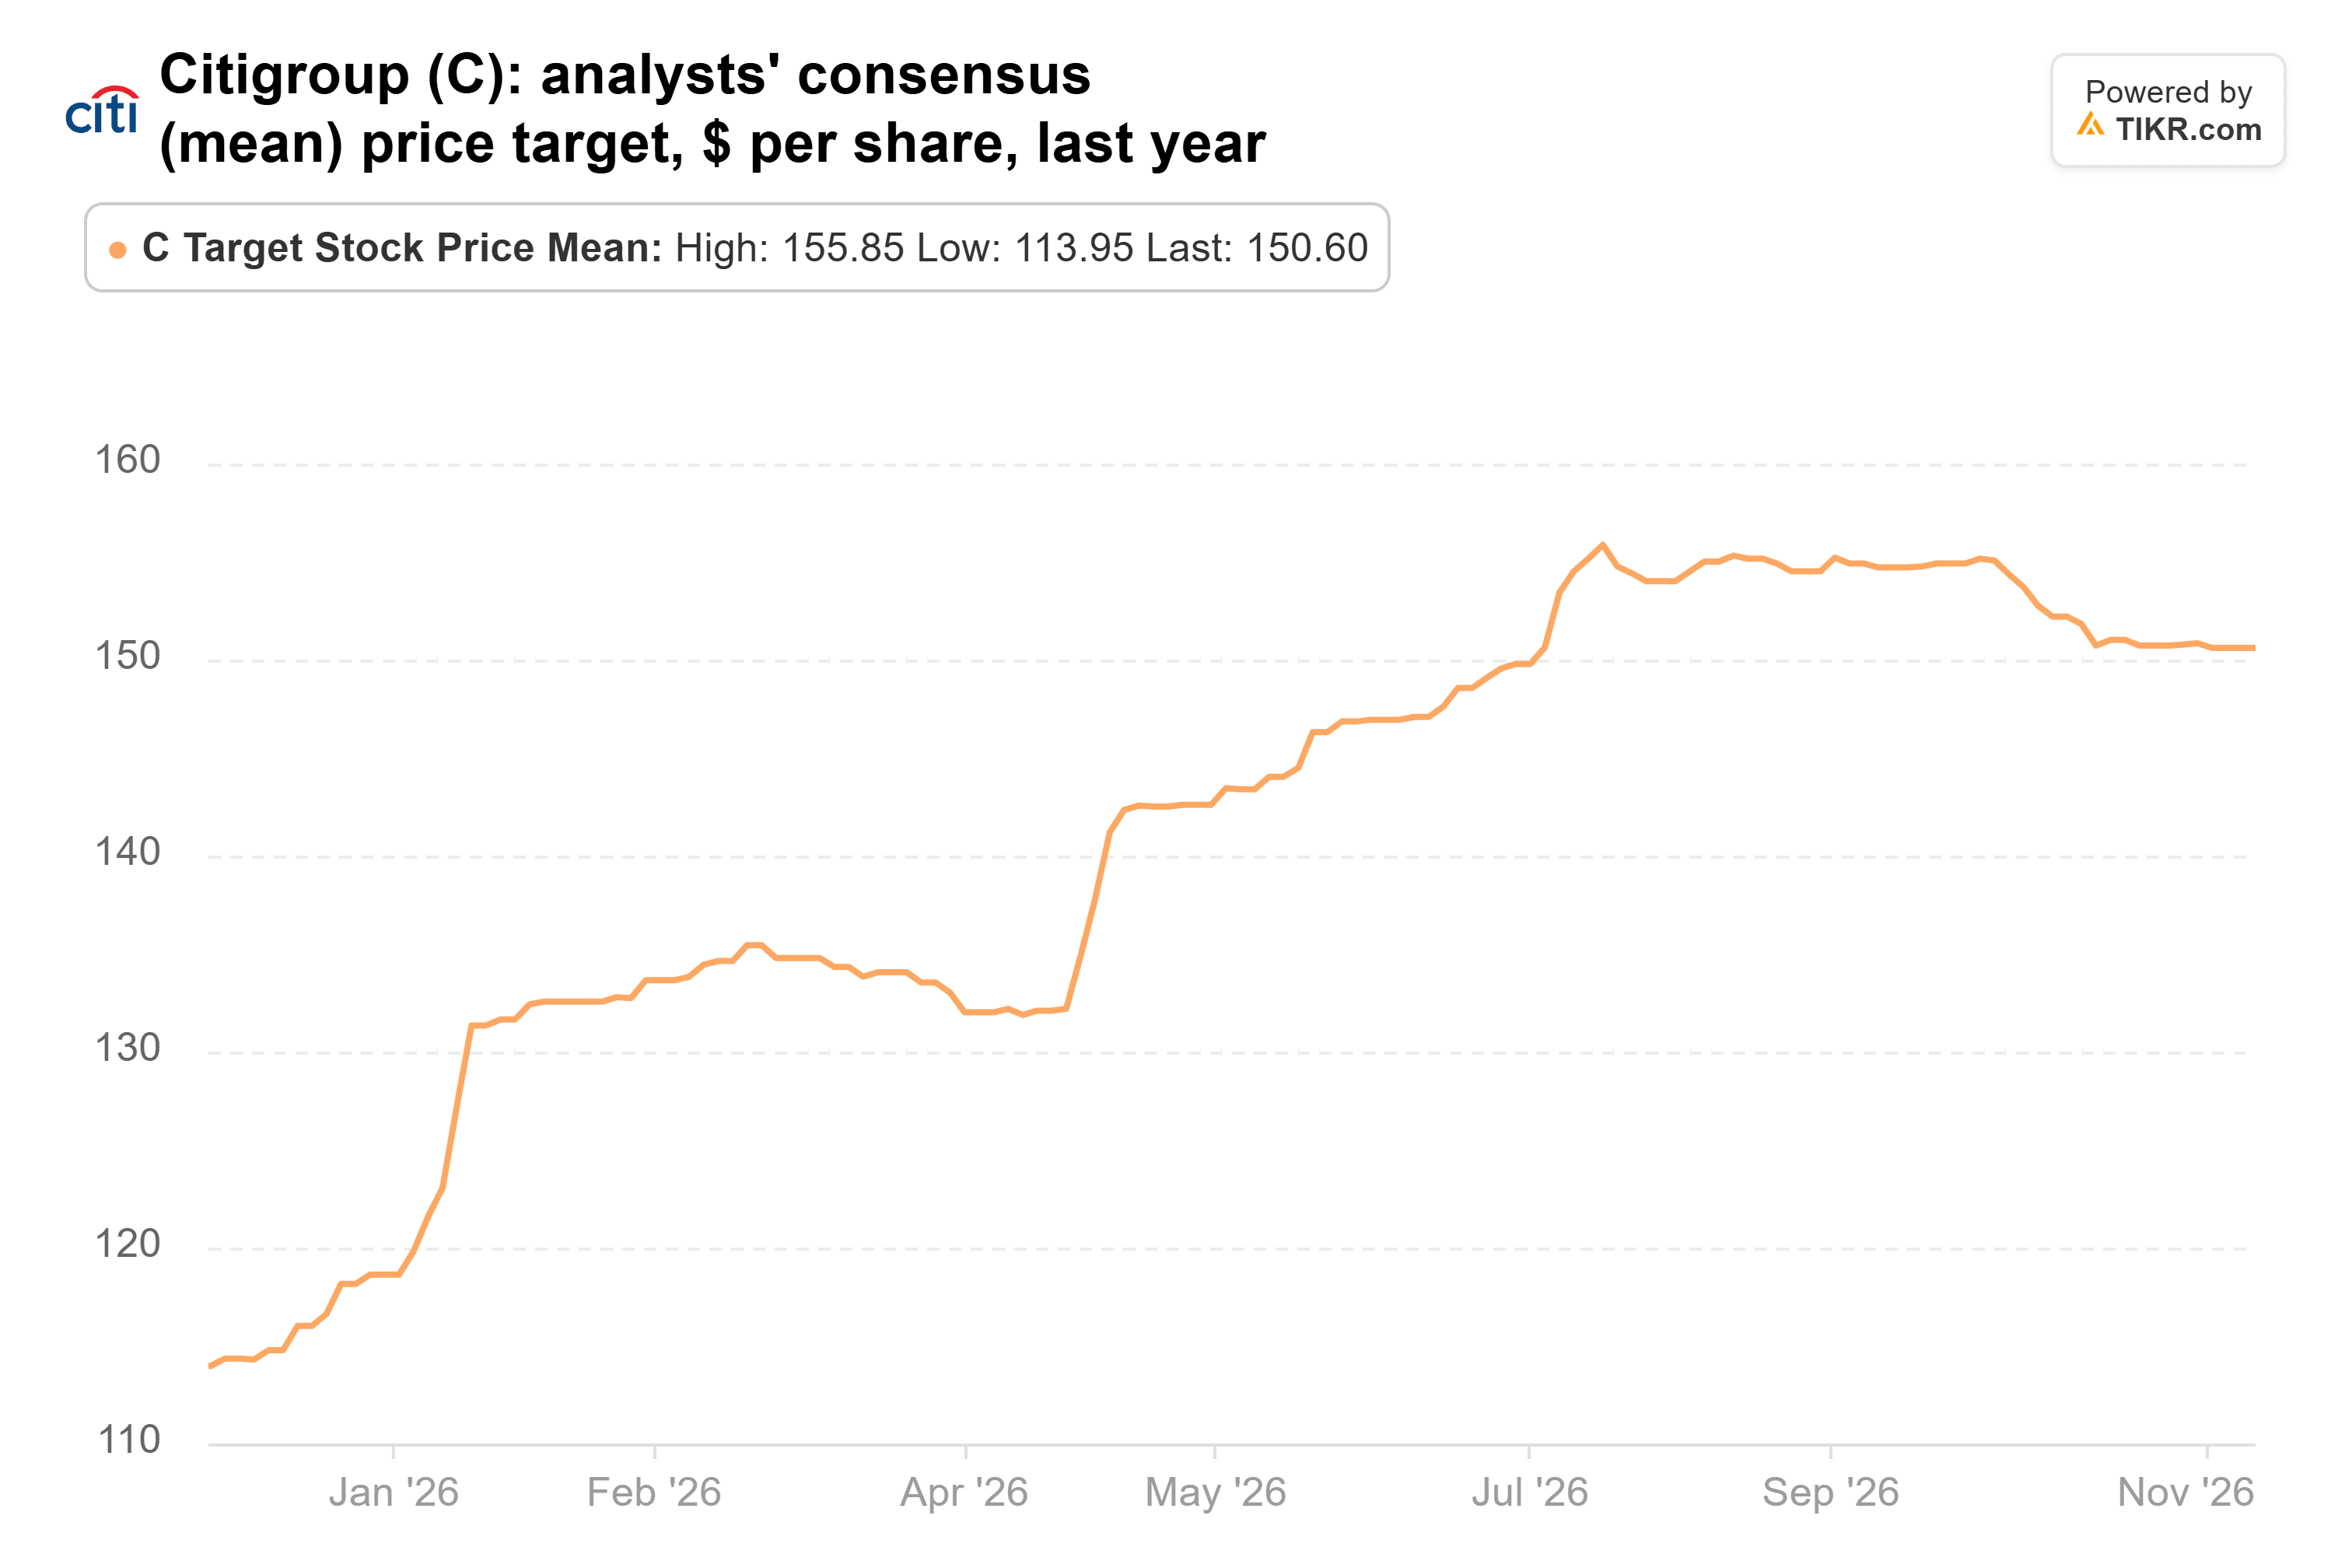
The average target is now $151, 36% above the last close and a little below July’s $156 peak. That’s far more upside than analysts see in any of the three stocks Prana sold.
The Berkshire sale holds up best
The risk in selling any of these is that the businesses keep delivering. HCA is guiding to the upper half of its ranges, and Berkshire is buying back stock faster.
Still, if I had to back one of these sales, it’d be Berkshire. It trades at 25x forward earnings, estimates barely grow and the average target is below the price, so there’s little room for error.
Citi’s fourth-quarter report on Jan. 14 is the next test for the stake Prana grew the most. Its next 13F, due in mid-February, will show whether it kept adding.
So what is HCA Healthcare stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what HCA Healthcare could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!