Key Takeaways
- Seagate shares rose 10% today after CoreWeave beat estimates and raised its 2026 guidance.
- The selloff in Seagate and Western Digital went well beyond any slowdown in AI storage demand.
- Analysts expect Seagate’s normalized EPS to more than quadruple from fiscal 2026 to fiscal 2028.
- Dell’s Nov. 24 report and Seagate’s 2028 pricing are the next tests.
Seagate Technology (STX) is up 10% today after CoreWeave reported what CEO Michael Intrator called “a breakout quarter.”
Seagate had dropped about 30% in a month by early November on fears that AI spending was running out of road. Its closest rival, Western Digital (WDC), is up 8%. Dell Technologies (DELL), which counts CoreWeave among the customers it builds AI clusters for, reports on Nov. 24.
The buyers are still building
CoreWeave’s third-quarter revenue jumped 168% to $3.66 billion, and its backlog reached $132.5 billion. It raised the low end of its 2026 capex range to $37 billion.
Storage is part of that bill. CoreWeave signed a multi-year deal for priority access to SSD capacity from Solidigm, a subsidiary of SK hynix (SKHY). SK hynix is up 10% and Sandisk (SNDK) is up 14%, since both sell the flash memory inside those drives.
For Seagate, data center revenue was $3.4 billion in the quarter to Oct. 2, 81% of the total.
It isn’t just Seagate
Western Digital’s revenue rose 55% in its quarter to Oct. 2, and it expects growth of 66% to 72% this quarter. Both drive makers sold off even as they guided higher, which I read as a swing in the market’s mood about AI.
Dell is the next check on that spending. It ended July with a record $95 billion AI server backlog. If that backlog holds when Dell reports, those servers will need somewhere to keep their data.
TIKR tracks 26 analysts on Seagate Technology. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Seagate Technology, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Seagate Technology’s Analyst Ratings
Still priced for a peak
Analysts expect Seagate’s earnings to keep climbing fast through fiscal 2028:
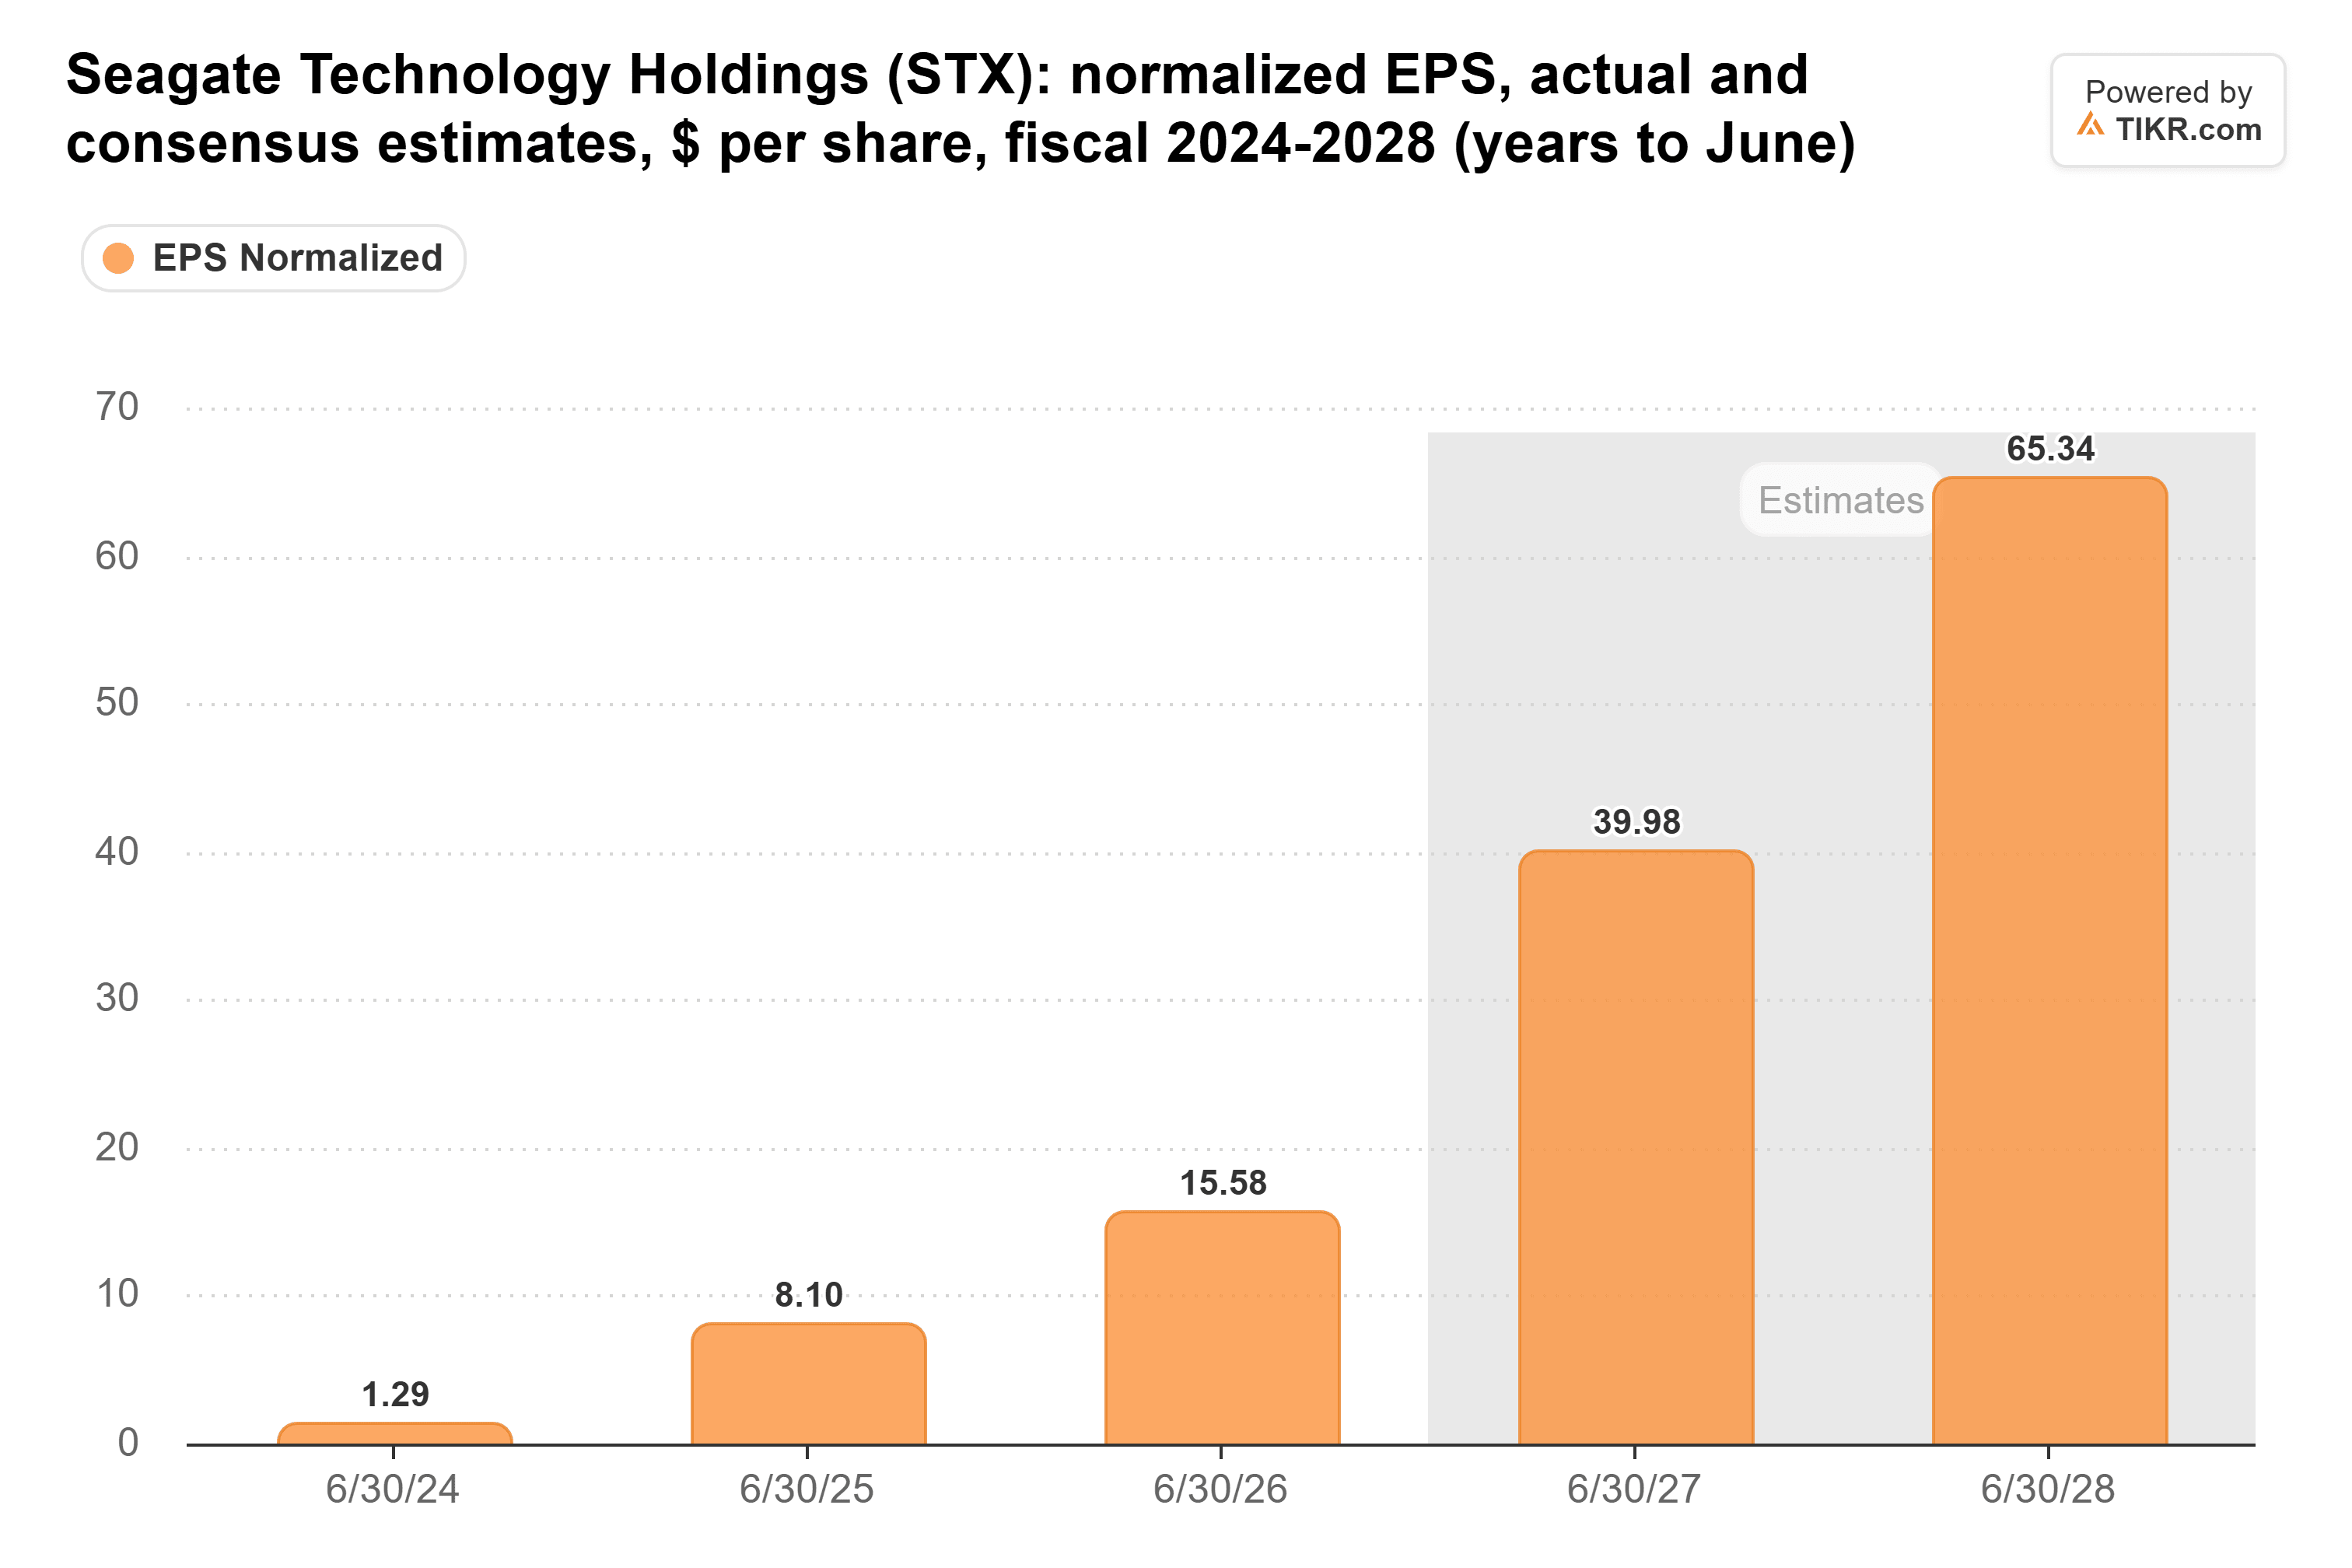
Analysts shouldn’t need to change fiscal 2027 much on CoreWeave’s news, since Seagate has already set its prices through calendar 2027. But customers still building at CoreWeave’s pace give Seagate leverage on fiscal 2028 supply, which it has allocated but not yet priced.
Yet the stock trades far below its usual multiple:
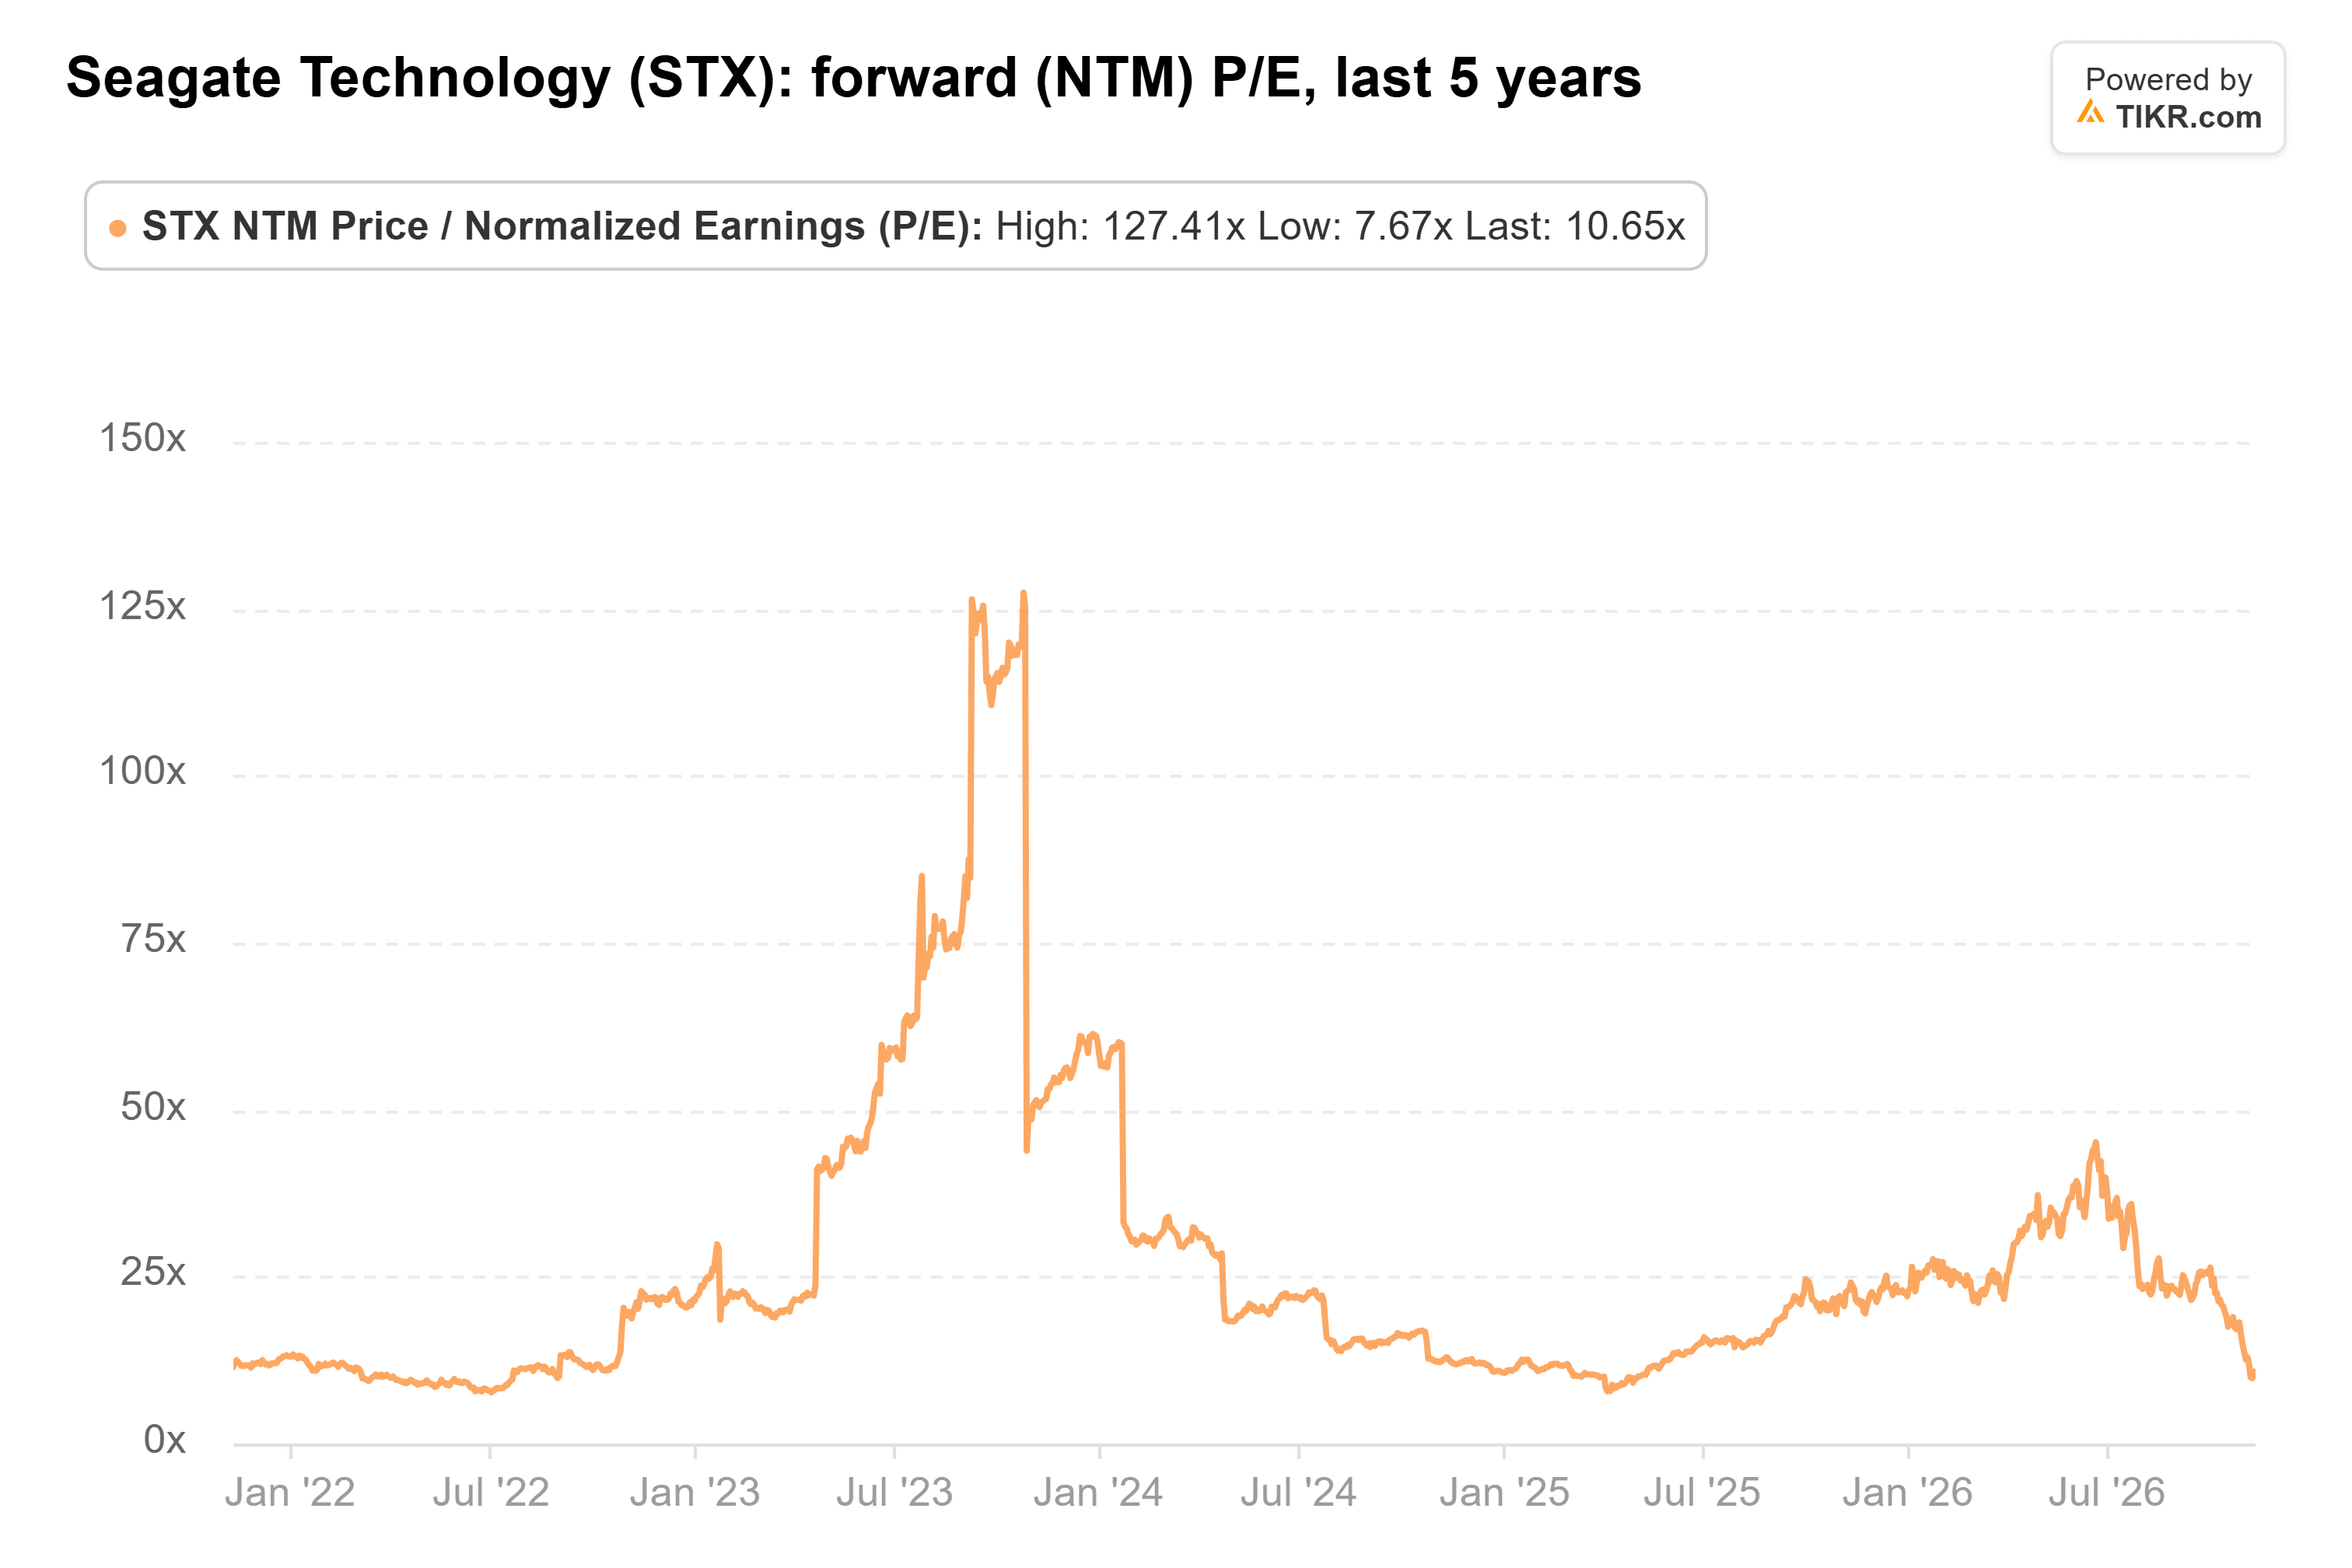
That’s about 11x at the last close, against a five-year average of 26x, and still only about 12x after today’s jump. Western Digital trades at 10x.
The selloff went too far
CoreWeave still lost $709 million last quarter, so its spending depends on lenders staying open. But Seagate is priced for peak earnings while its biggest customers keep building, and I think more of today’s bounce can stick. Seagate’s own report in late January should show what it can charge for 2028.
So what is Seagate stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Seagate could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!