Key Takeaways
- AMD jumped 4% after CoreWeave raised its 2026 revenue forecast.
- CoreWeave’s growing backlog supports AMD’s guidance for server revenue to double next year.
- Intel and Arm sell into the same boom, and UBS has Arm taking server CPU share from Intel.
- AMD trades near its average forward P/E, with analysts expecting its earnings to more than double in 2027.
Advanced Micro Devices (AMD) shares are up 4% today after CoreWeave beat estimates and raised its 2026 outlook.
Intel (INTC) is rising on the same news, and Arm Holdings (ARM) keeps winning server CPU share.
CoreWeave’s backlog backs AMD’s big guide
CoreWeave’s third-quarter revenue rose 168% to $3.66 billion. Its backlog climbed to $132.5 billion from about $104 billion in June, and its 2026 forecast now beats the $12.9 billion analysts expected. Most of that money goes to Nvidia’s chips. But demand this strong outruns what any one supplier can ship, and that’s AMD’s opening.
On CNBC’s Closing Bell Tuesday, Bernstein’s Stacy Rasgon summed up AMD’s guide: “AMD is effectively guiding for their server revenues next year to double and their GPU revenues to almost triple.”
Analysts expect AMD’s revenue to nearly double in 2027, to $95.9 billion:
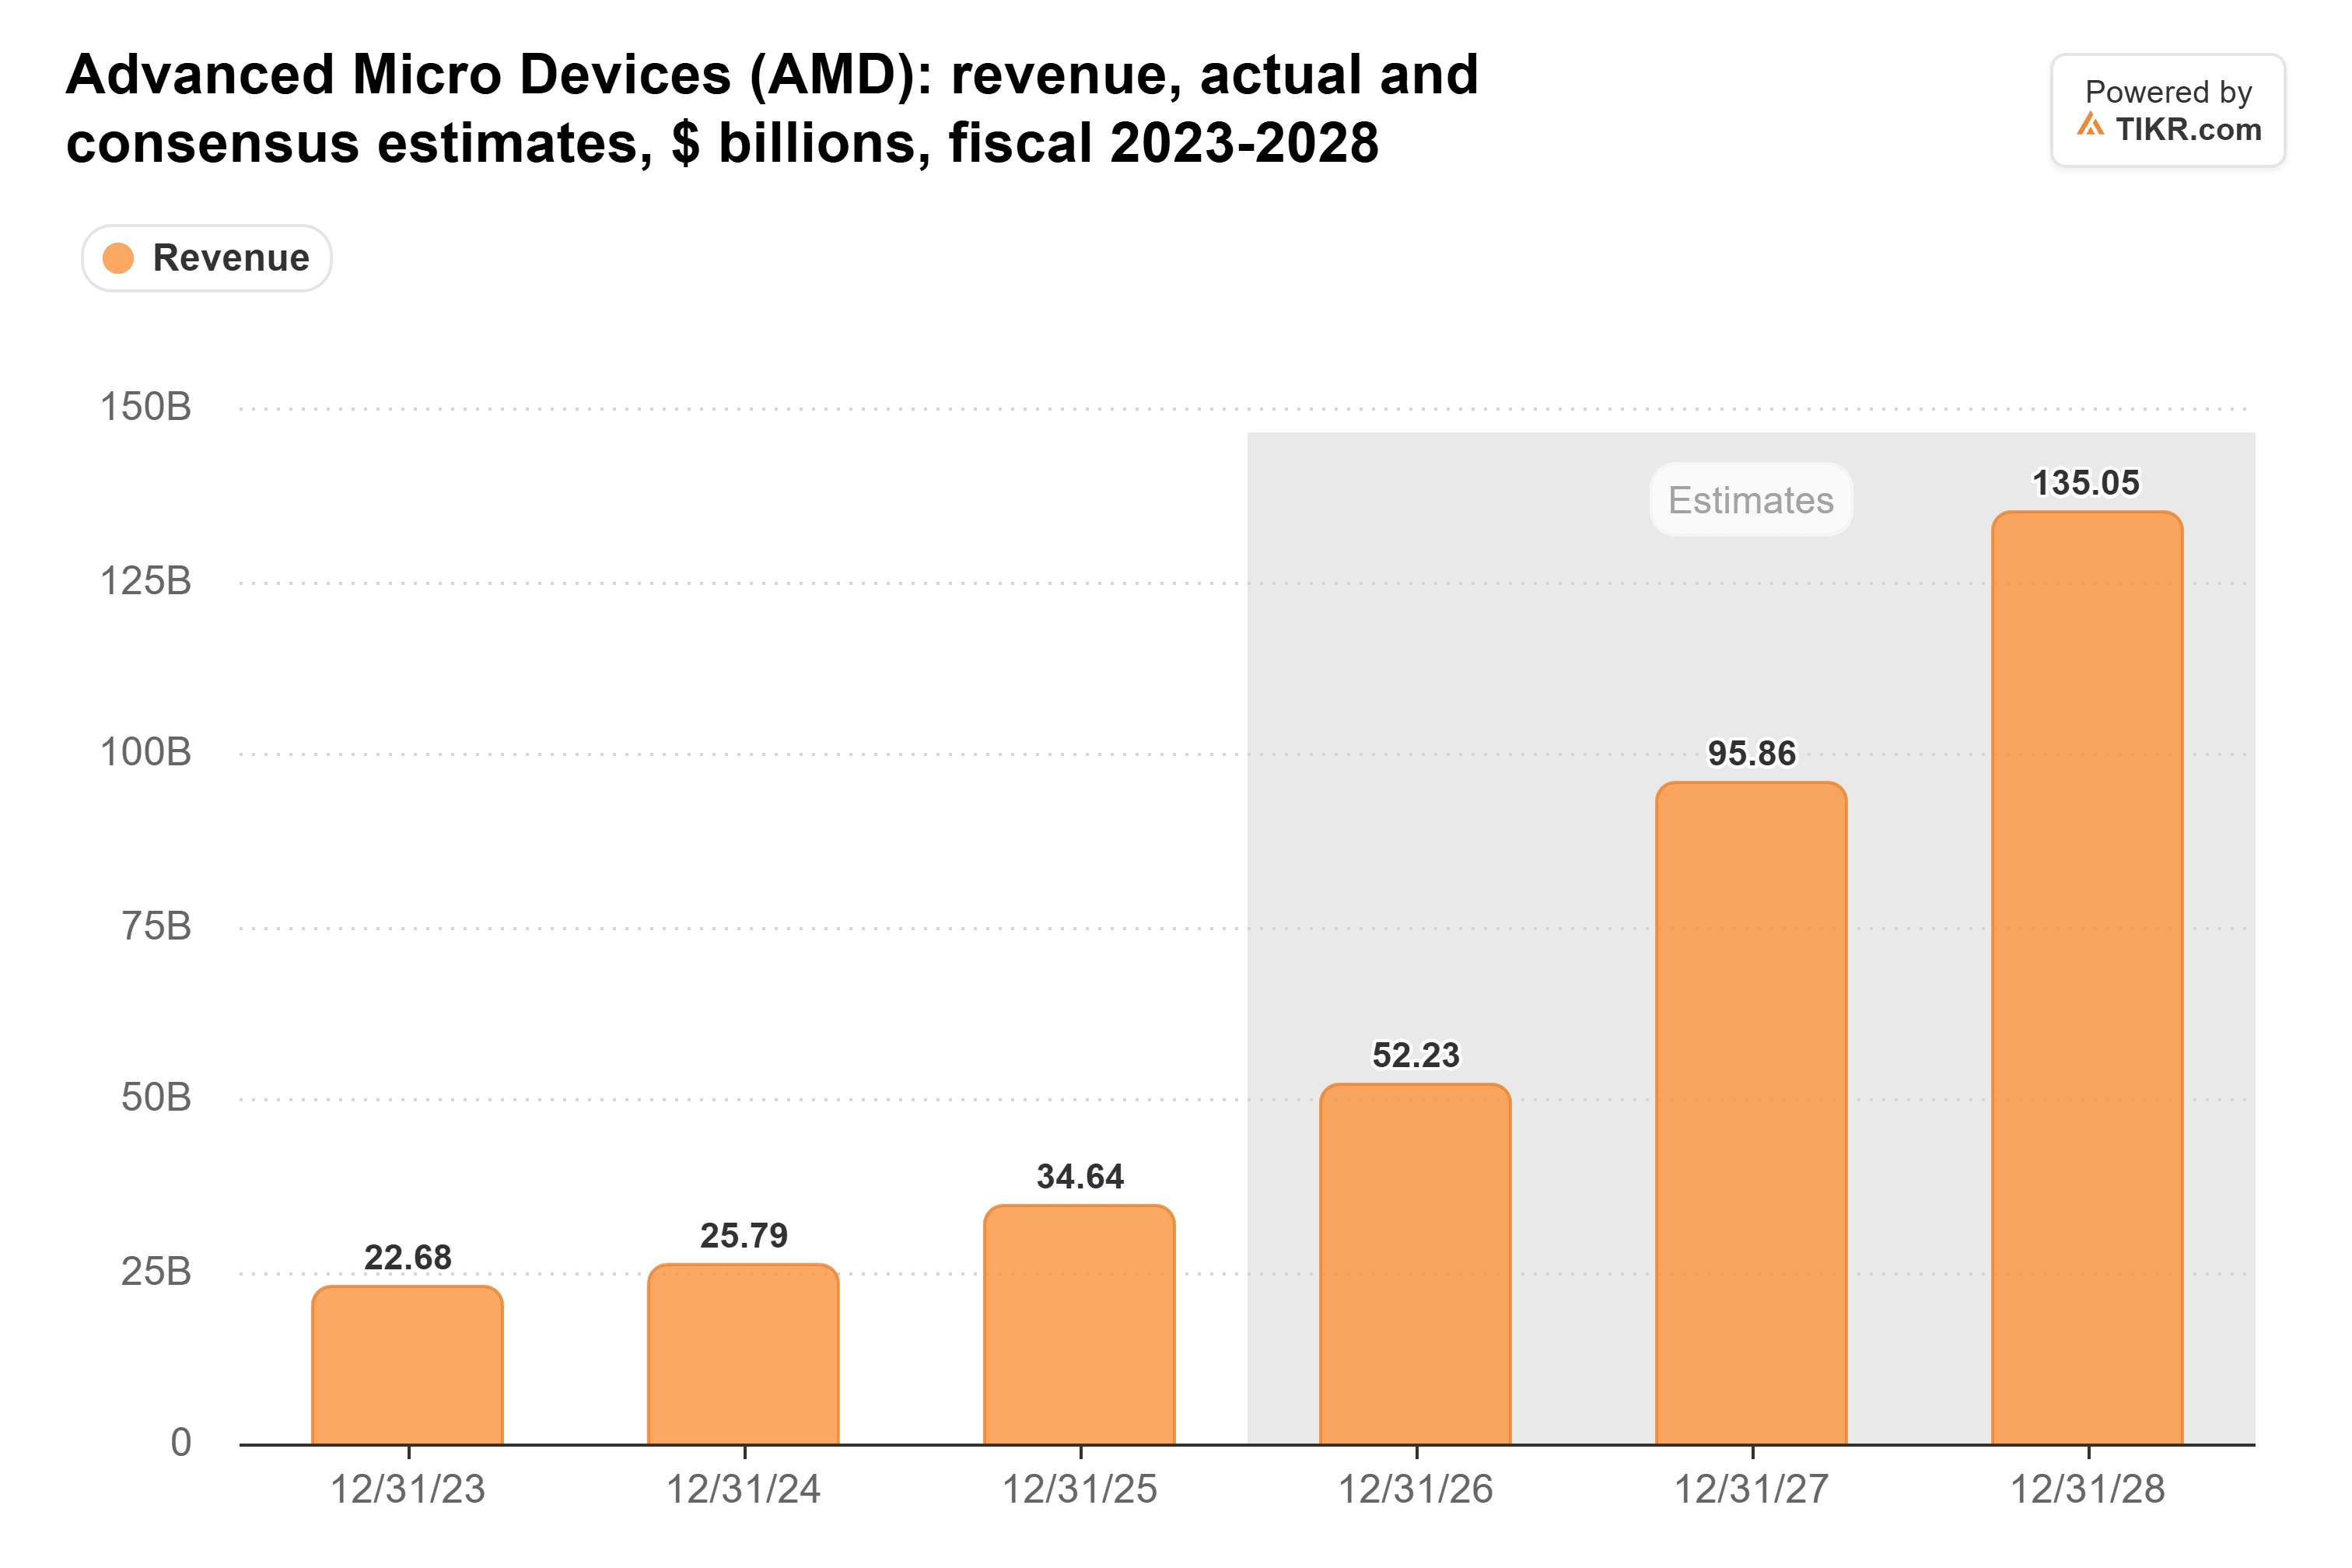
CoreWeave’s quarter gives analysts no reason to cut those numbers.
Intel is short on chips, and Arm is filling the gap
Intel is up 6% too. Its Data Center and AI revenue rose 78% to $7.3 billion in the third quarter, but it can’t make enough chips.
UBS’s Timothy Arcuri said Wednesday that third-quarter server CPU shipments rose 31% from a year earlier. Arm’s unit share rose about 2.5 points to 20.1% and Intel’s fell to 51.5%, while AMD’s stayed roughly flat at 28.4%. So for now, AMD’s server growth is coming from a fast-growing market.
TIKR tracks 53 analysts on AMD. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AMD, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AMD’s Analyst Ratings
AMD trades near its usual multiple
AMD’s forward P/E was 34x at the last close. That’s around its five-year average of 35x and half its June peak of 67x:
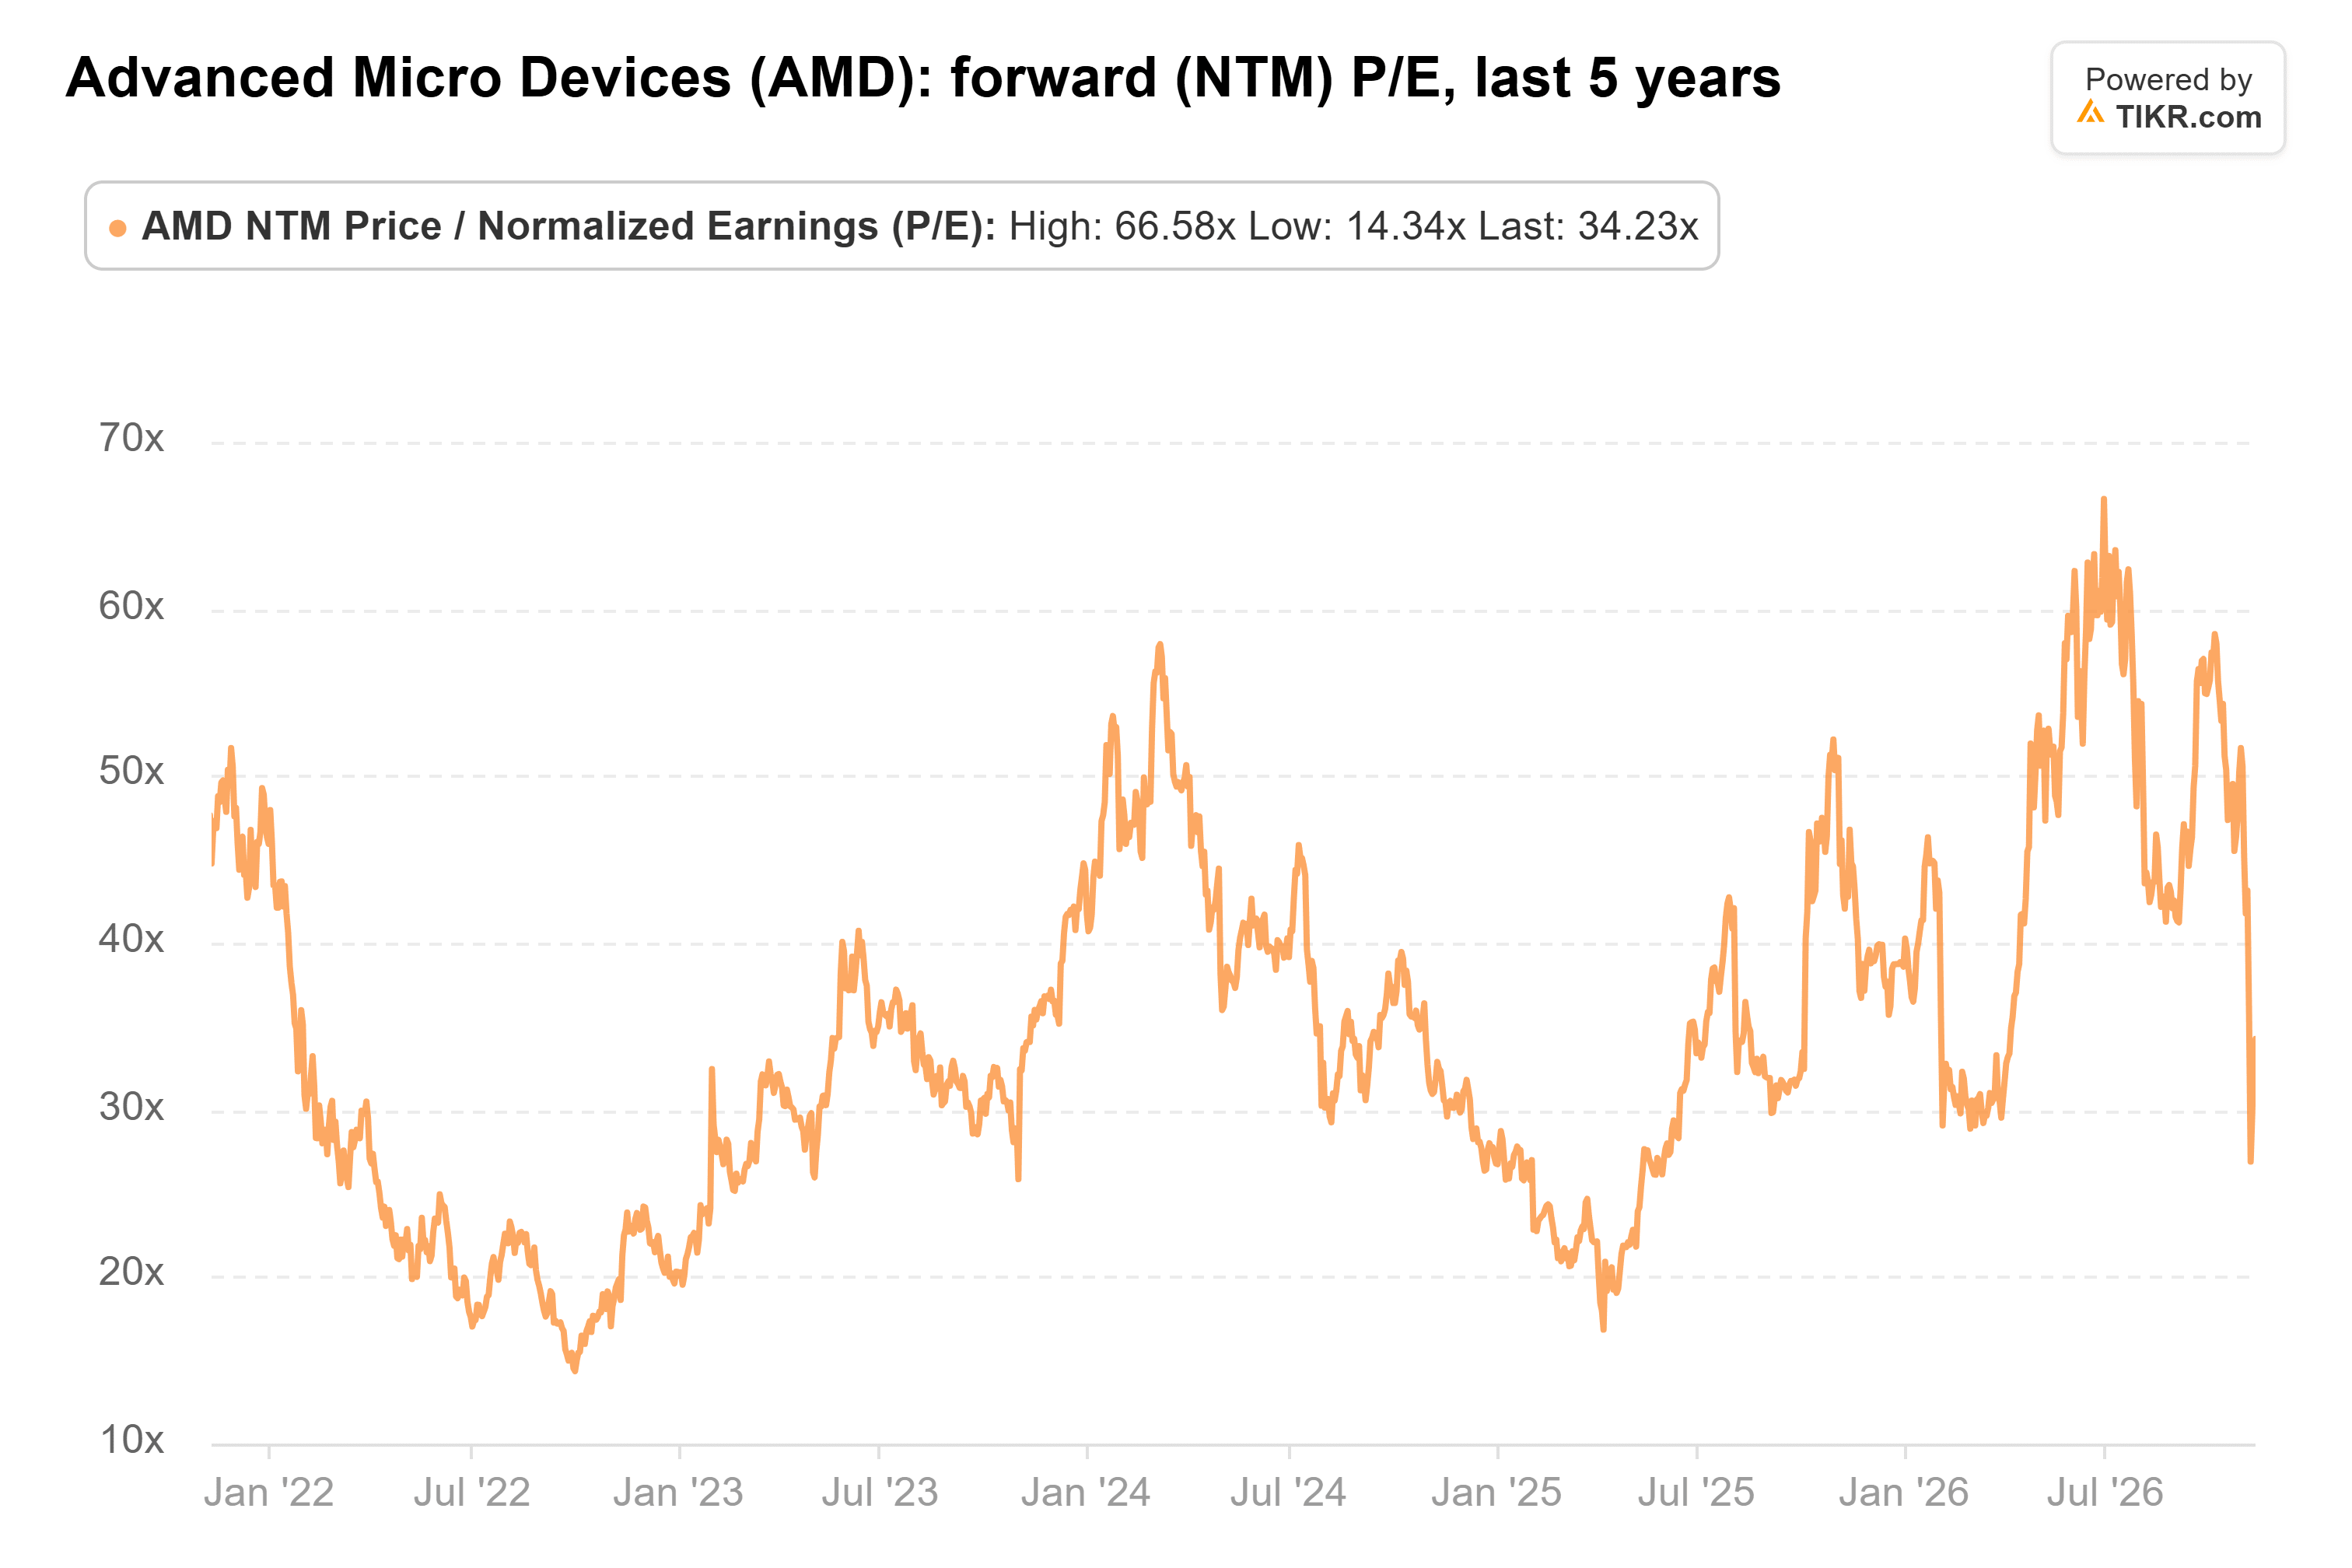
At today’s price, it’s a bit higher. Investors are paying a normal multiple because analysts expect normalized EPS to more than double, from $8.08 this year to $17.69 in 2027.
CoreWeave’s quarter makes those numbers easier to believe, and AMD doesn’t need a bigger multiple to work from here. The risk is interest rates. CoreWeave’s $846 million of interest expense last quarter was four times its $207 million of operating income. AMD’s fourth-quarter report in early February is the next test.
So what is AMD stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AMD could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!