Key Takeaways
- Anthropic priced its $81.3 billion IPO at $83 a share. Riot Platforms’ 10-Q names Anthropic as the tenant on about $37 billion of Riot’s roughly $38 billion of contracted revenue.
- A well-funded, public Anthropic lowers the main risk behind Riot’s future rent and the project debt it plans to raise against it.
- What to watch: whether Riot can raise Corsicana’s project debt without investment-grade credit support or a fallback to 12% rent credits.
Anthropic (ANT) priced its $81.3 billion IPO at $83 a share and starts trading on Nasdaq today. The stock with the most riding on that cash might be a bitcoin miner: Riot Platforms (RIOT).
Riot’s 10-Q names Anthropic as the tenant on both of its big data center leases. TeraWulf (WULF) has a $19 billion Anthropic lease of its own, but Google backstops those leases once they’re delivered, so TeraWulf leans on Anthropic’s credit far less than Riot does.
One Tenant, $37 Billion at Riot
Riot’s third-quarter release values its Corsicana lease at about $28 billion over 15 years, and the Rockdale lease adds about $9.1 billion over 20 years. Management projects about $2.3 billion of lease revenue in 2029, roughly 3.5x Riot’s 2025 revenue of $647.4 million, most of which came from mining bitcoin.
Analysts expect revenue to nearly triple by 2028:
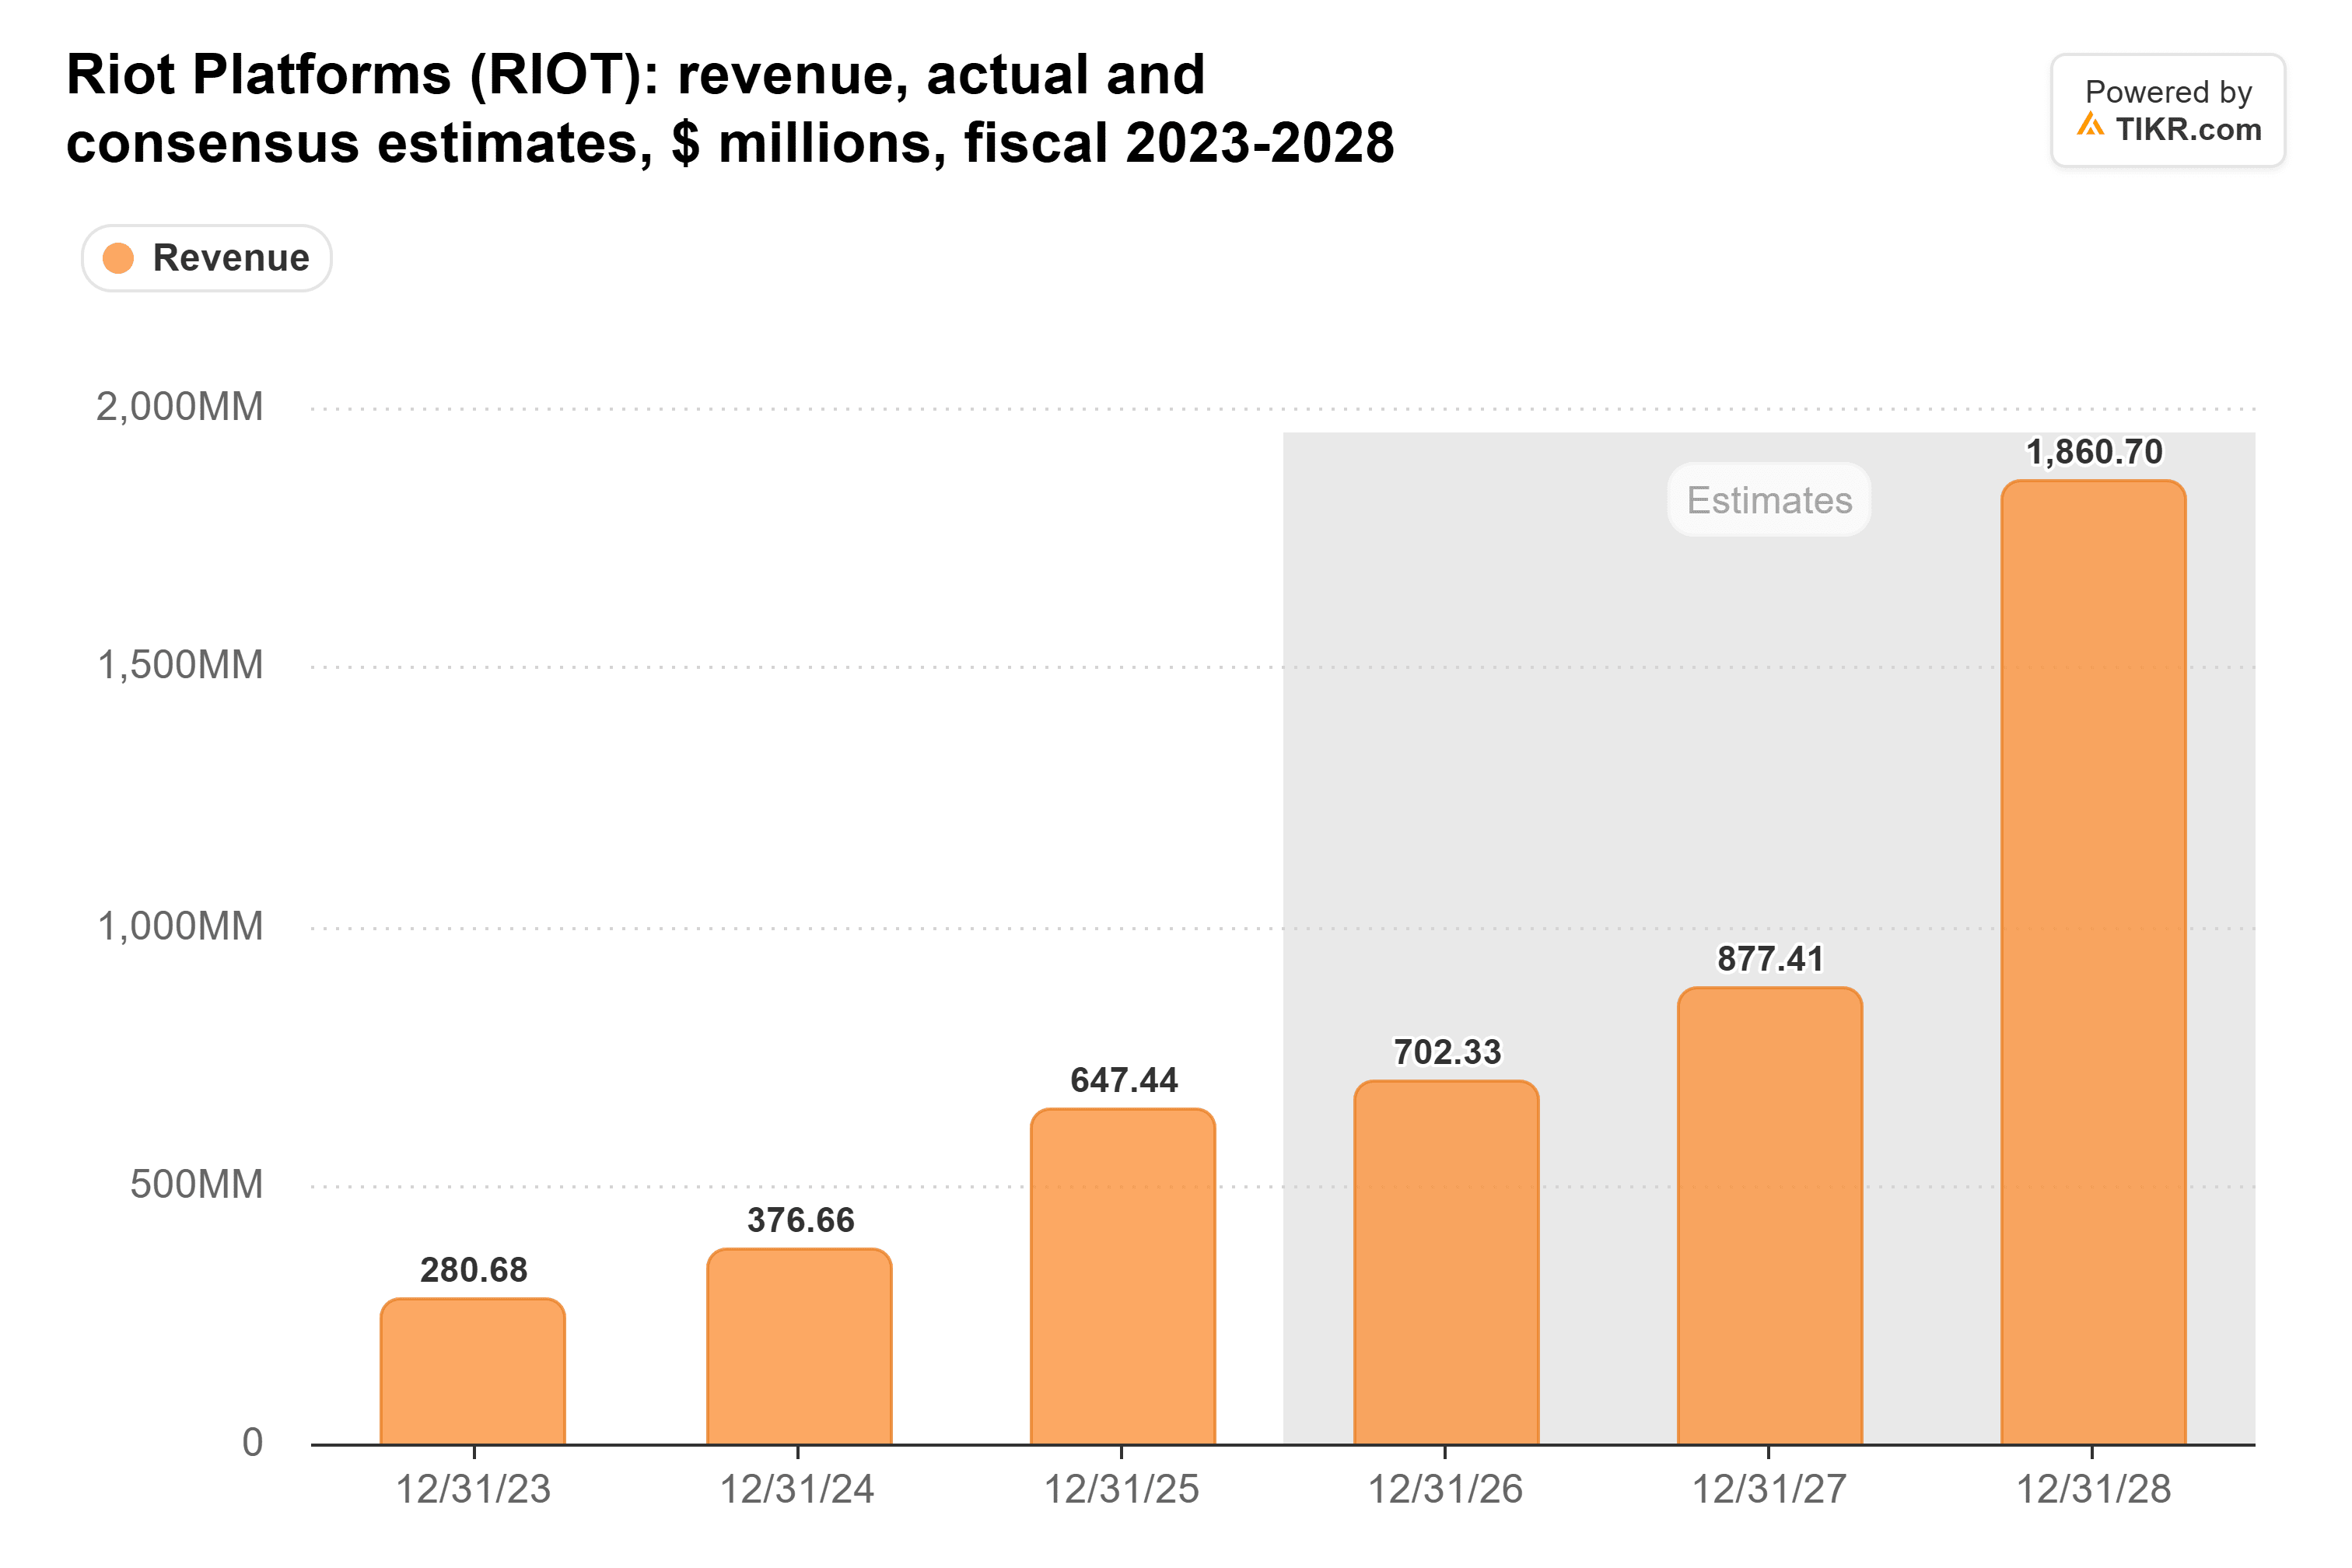
Even the 2028 estimate of $1.86 billion sits below that $2.3 billion, because Corsicana comes online in phases: a first block in June 2027 and the full 400 MW by September.
TIKR Tracks 22 Analysts on Riot Platforms. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Riot Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Riot Platforms’ Analyst Ratings
Lenders Care Who Pays the Rent
Riot plans to fund the buildout mostly with non-recourse project debt sized to the rent, and the two sites need about $7.6 billion to $7.8 billion of capital. Debt sized against rent gets priced on the tenant’s ability to pay it.
That’s why Keefe, Bruyette & Woods downgraded Riot to Market Perform on Nov. 11, citing its reliance on Anthropic and the Corsicana lease’s lack of investment-grade credit support. KBW also doubted Anthropic would earn an investment-grade rating soon. An $81.3 billion IPO, a $26 billion private placement at the same price and quarterly public financials, starting with $17 billion of third-quarter revenue, go a long way toward answering that worry.
Riot Still Has to Pay for the Buildings
The IPO doesn’t build anything. Riot ended September with $690 million of total debt and $669 million of cash and short-term investments:
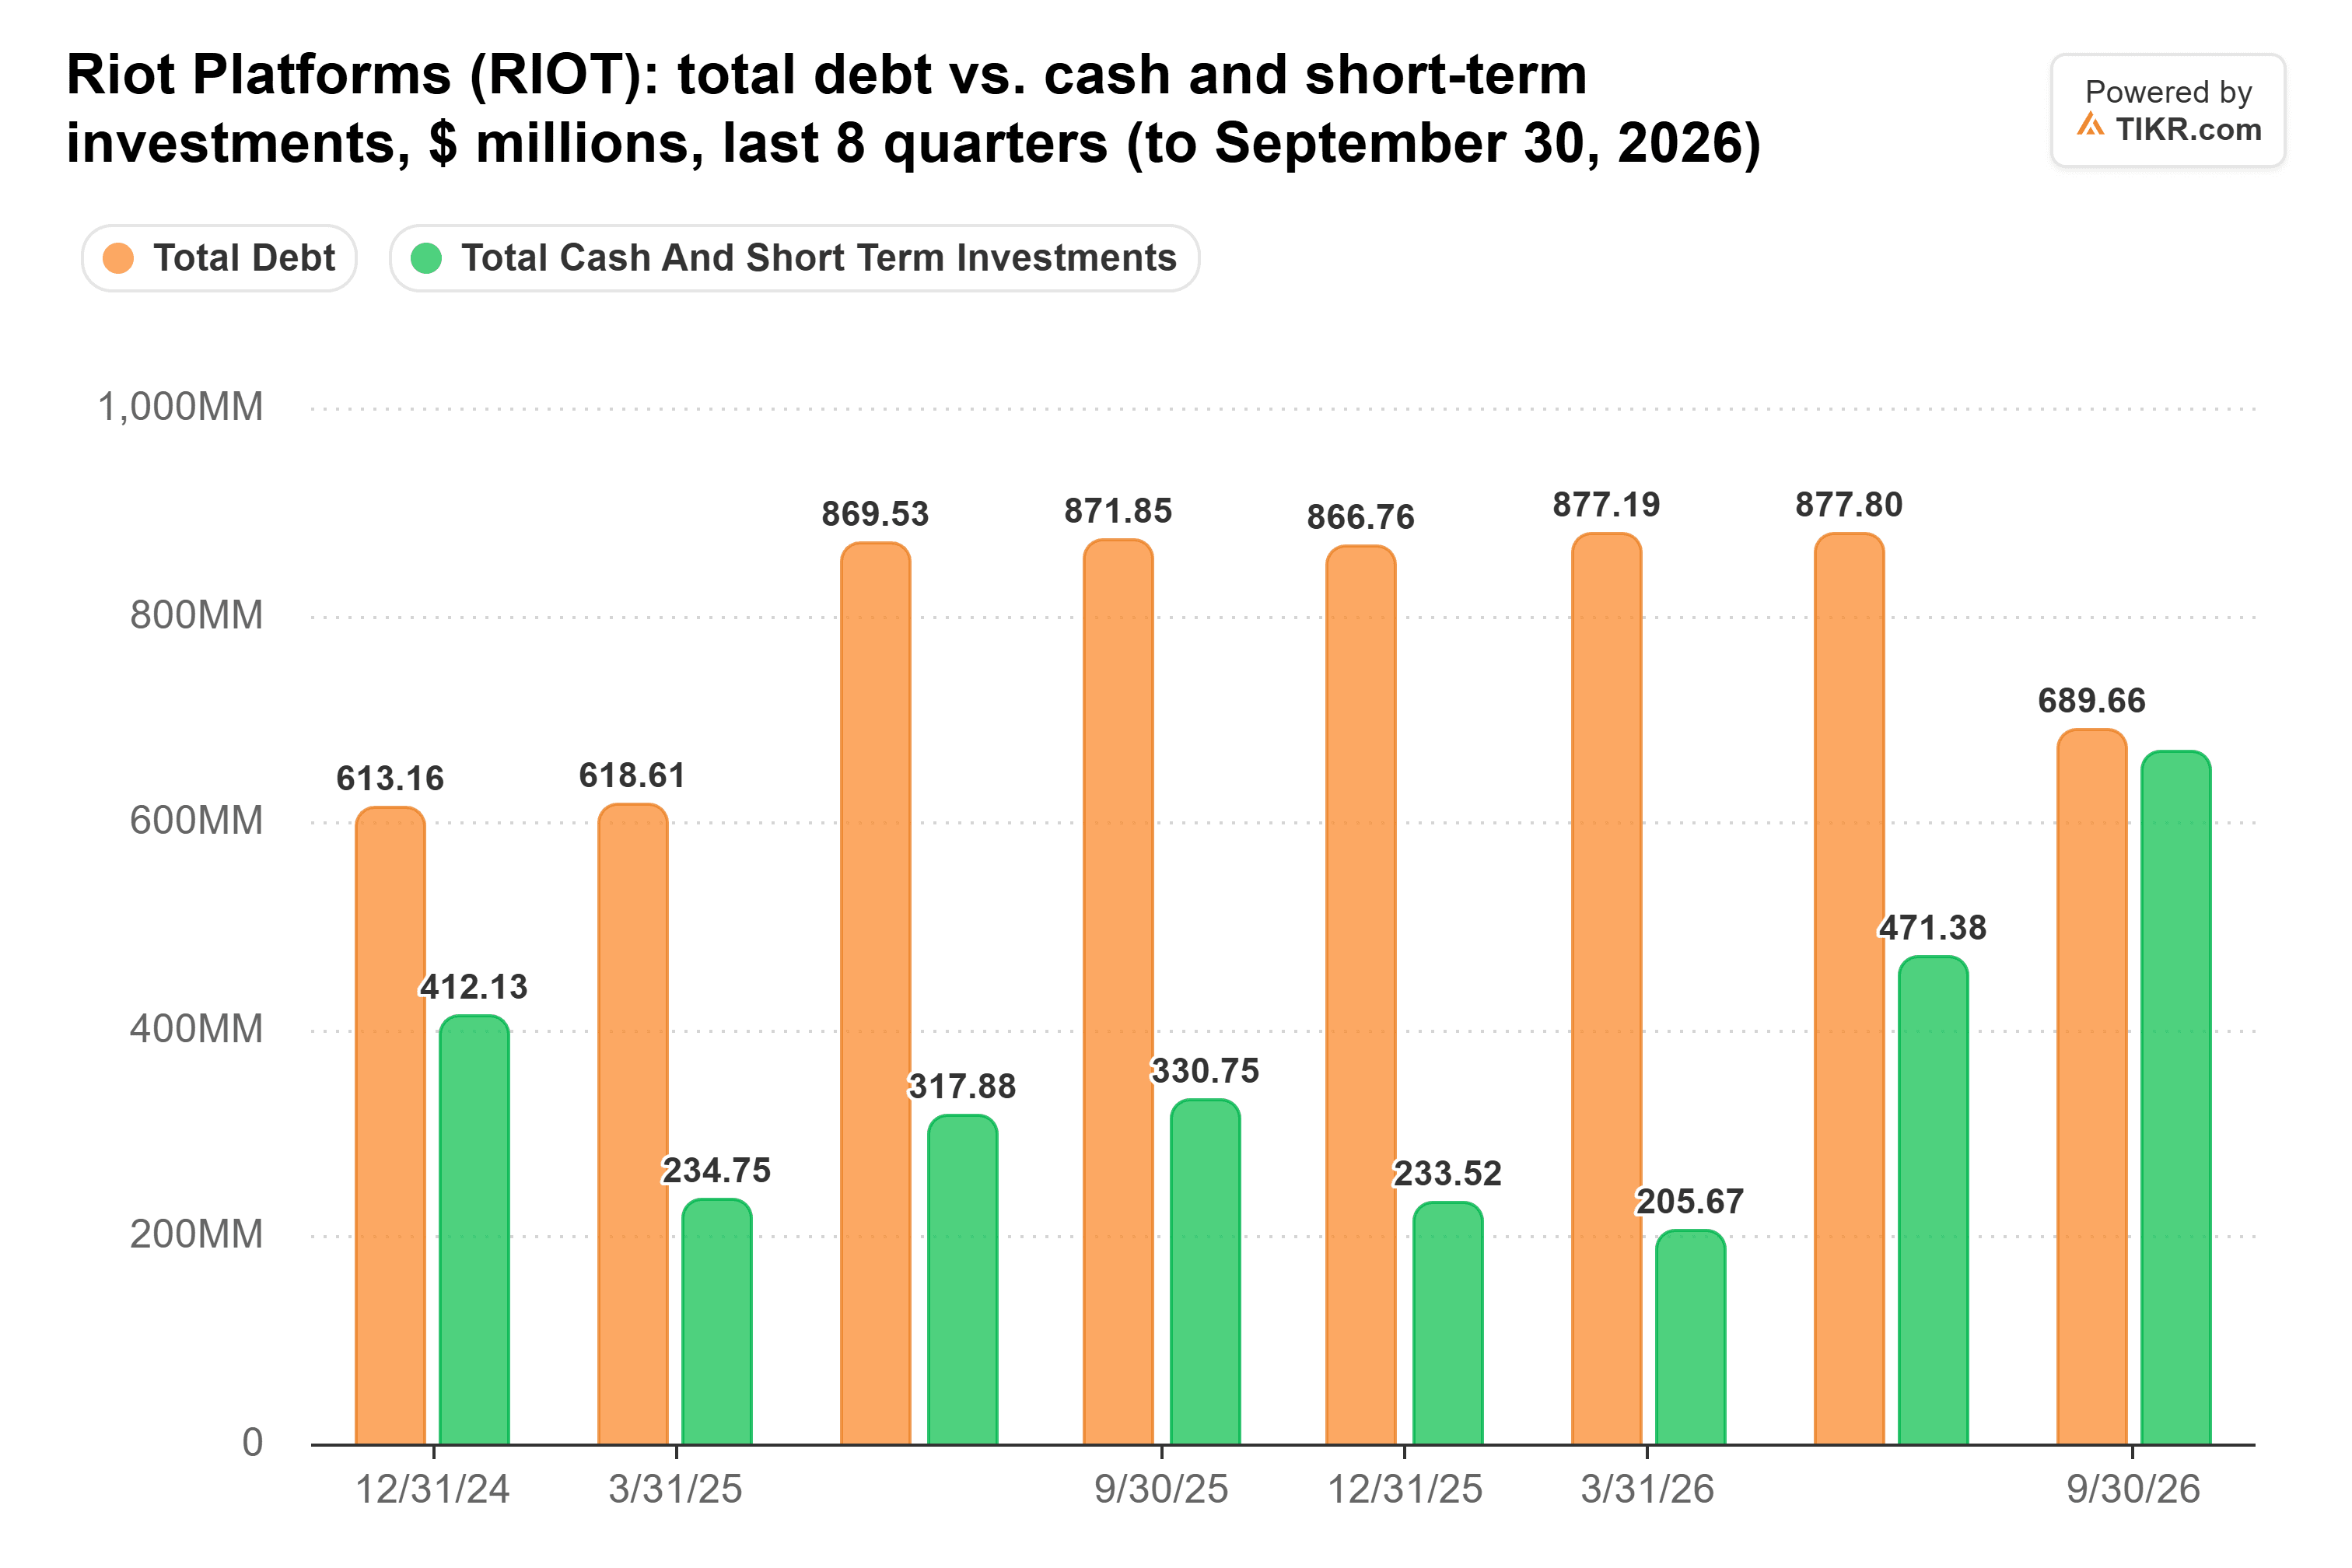
So lenders supply most of the money. At Rockdale, that started with a Morgan Stanley bridge facility of up to $573 million that matures Dec. 31. Riot expects no equity issuance. At Corsicana, if it can’t raise acceptable financing for tenant reimbursements, it owes Anthropic rent credits covering them plus 12% a year, cutting cash rent instead.
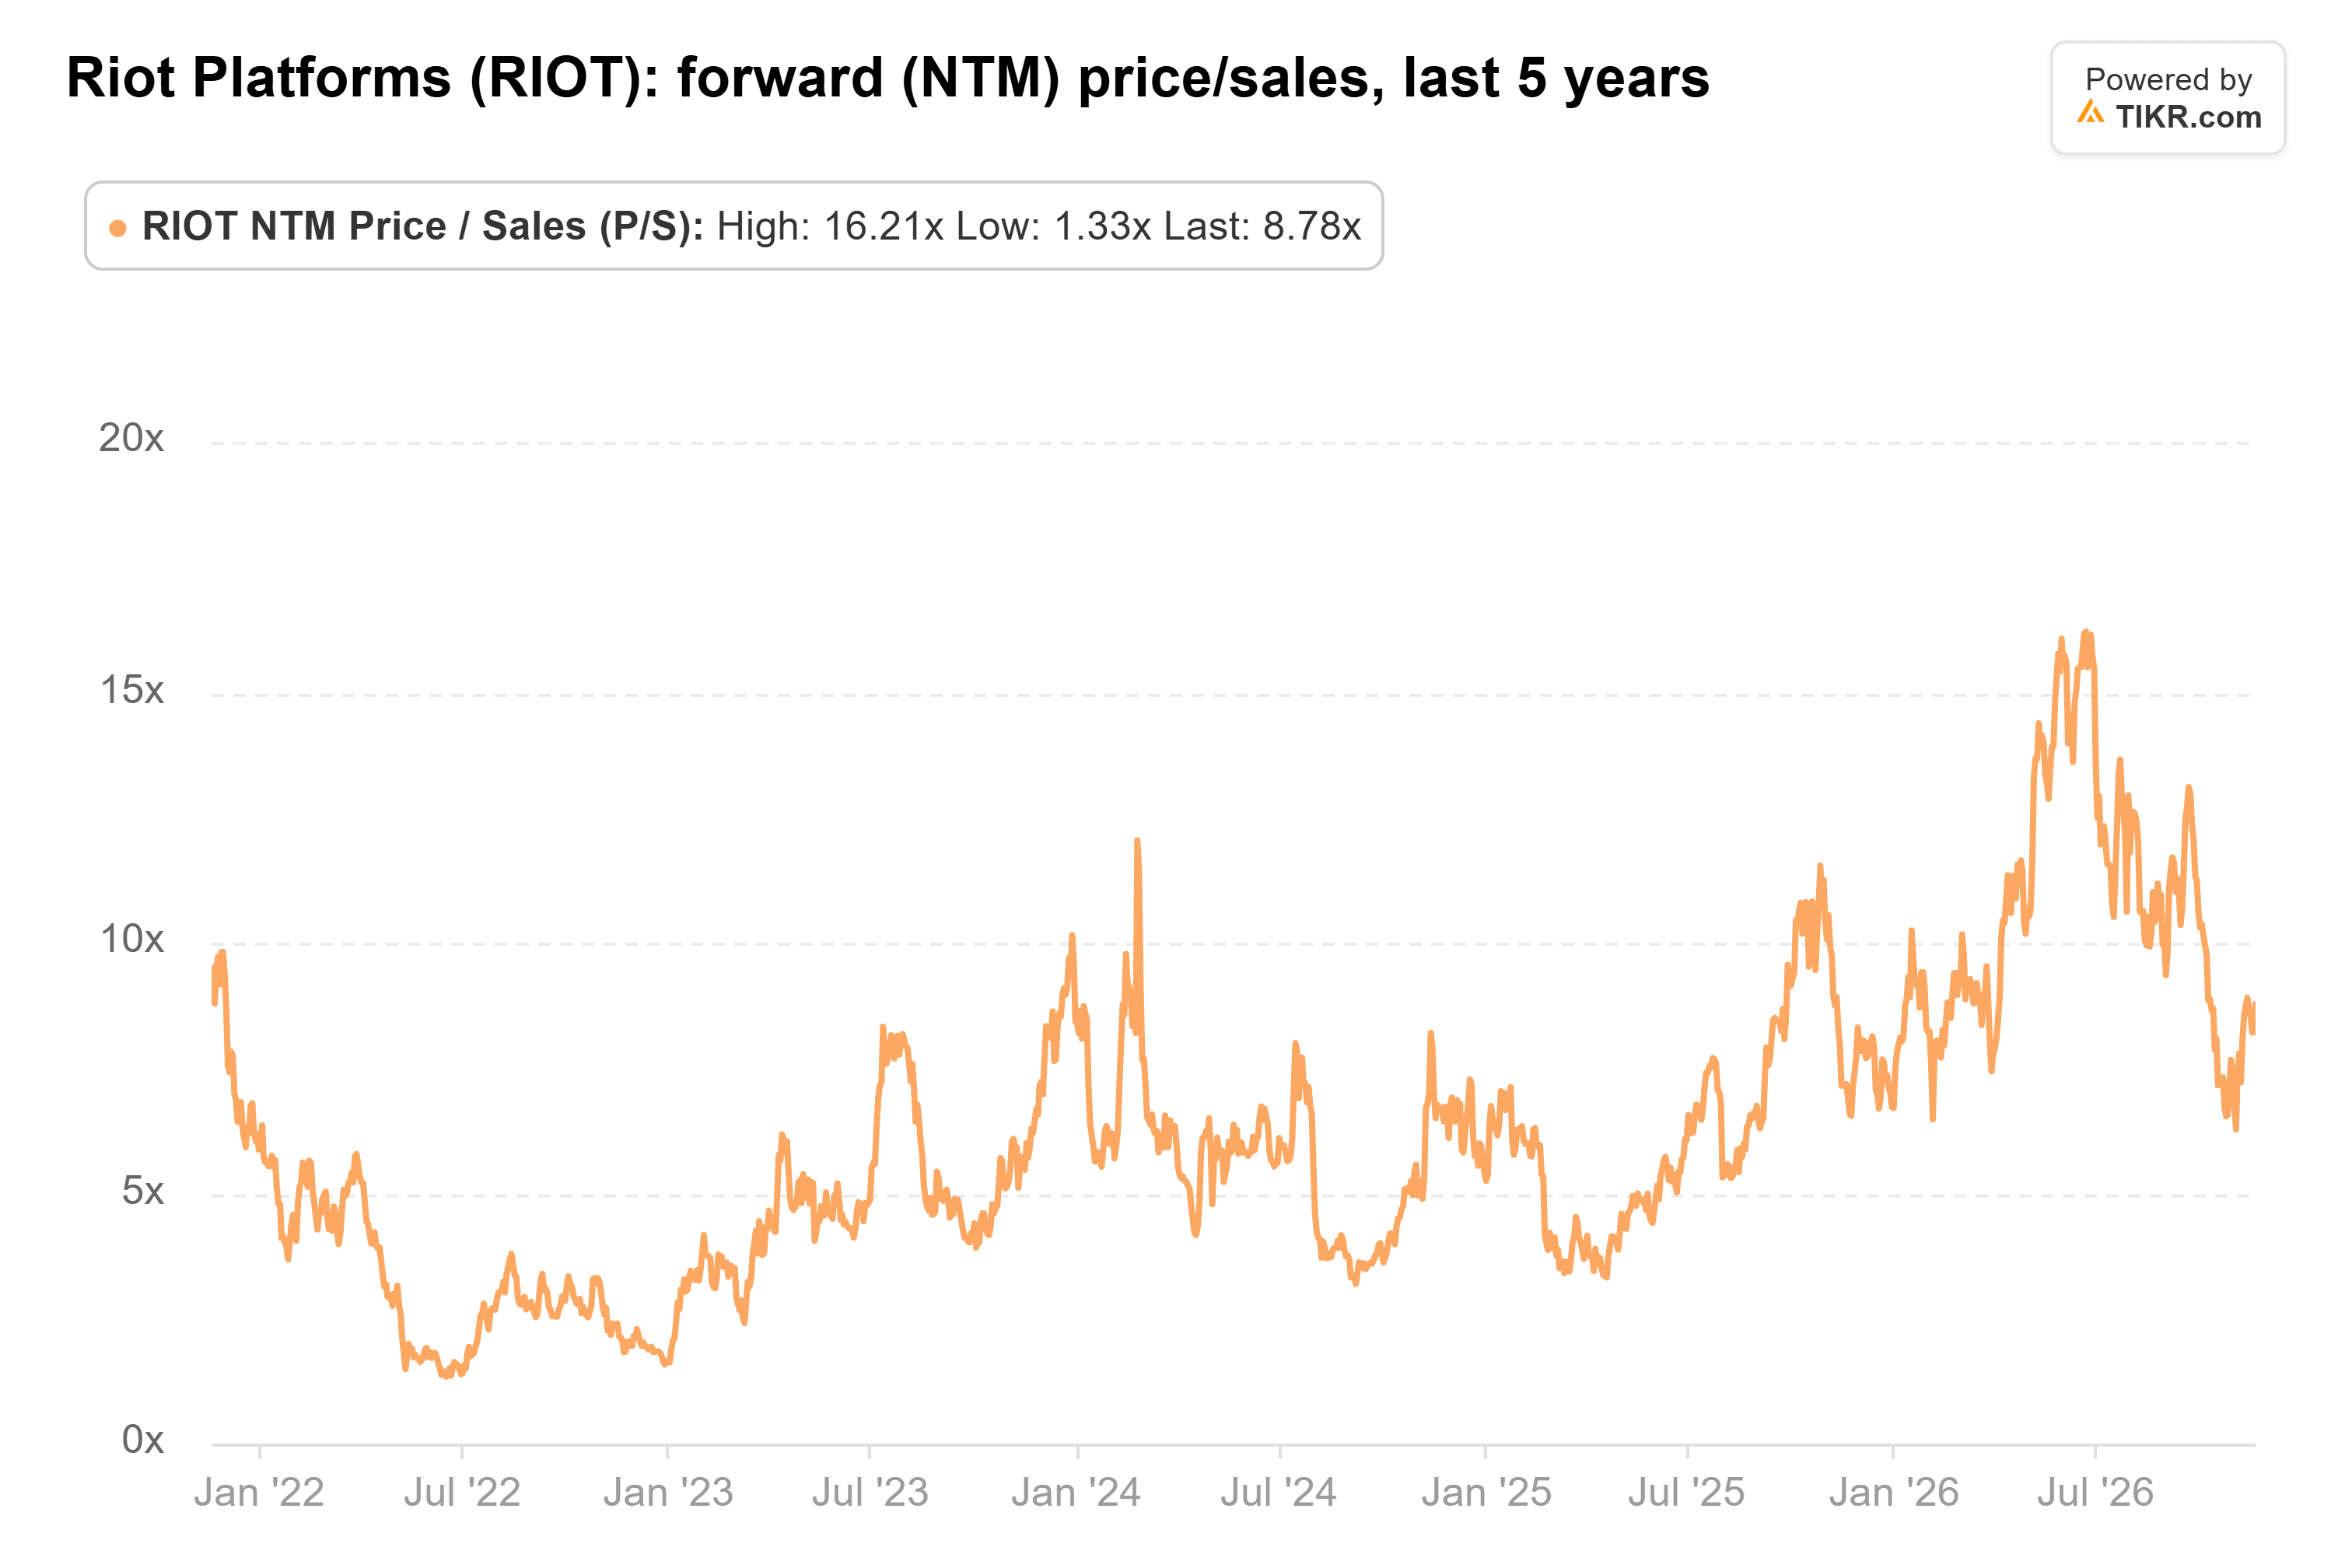
Riot now trades at a lower multiple of forecast sales than before it signed either lease. Its forward price/sales of 8.8x is above its 6.2x five-year average, but about half the 16x of June:
What Riot’s Bridge Refinancing Will Tell Us
The Rockdale bridge was set up while Riot was still working on an investment-grade backstop, so if that support comes through, refinancing it says little about Anthropic’s own credit. Corsicana is the real test. Management has pointed to 80% to 90% loan-to-cost debt there, with no investment-grade support.
If Riot secures debt in that range without an investment-grade backstop, that would support the case that Anthropic’s credit is strong enough to finance Corsicana on the strength of its rent. If Riot has to use the 12% rent credits instead, KBW’s concern about tenant credit would remain unresolved.
So What Is Riot Platforms Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Riot Platforms could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!