Key Takeaways
- Prologis director Alfred F. Kelly, Jr., Visa’s former CEO, bought $587,350 of Prologis stock on Nov. 18 at an average of $124.97 a share.
- The stock is about 18% below its July closing high as higher interest rates weigh on property values, even though its third-quarter results held up.
- EastGroup Properties also had a strong third quarter, which suggests warehouse demand isn’t what’s holding Prologis back.
- Prologis trades at about 24x forward AFFO, below its 27x five-year average, and the consensus target is well above the price.
Alfred F. Kelly, Jr. joined the board of Prologis (PLD) in June, after running Visa as its CEO and then its executive chairman. On Nov. 18, he bought 4,700 Prologis shares at a weighted average of $124.97, or $587,350 in all, according to the Form 4 he filed the next day.
He bought a stock that closed on Nov. 19 about 18% below its July 16 closing high of $150.06. And the leasing market doesn’t look like the reason. Marshall Loeb, CEO of fellow warehouse landlord EastGroup Properties (EGP), said in October that leasing “has been much more stable than headlines would lead one to expect.”
Blame the bond market
In the third quarter, Prologis agreed to combine with UK warehouse owner SEGRO. SEGRO’s shareholders approved the deal on Sept. 28, and Prologis sold $2.4 billion of new stock to help pay for it. It expects the deal to close in the first half of 2027. Then rates jumped. On the Oct. 15 call, Prologis CEO Dan Letter said, “We think the recent move in rates will slow transaction activity and could put some pressure on values.”
The business held up. Third-quarter core FFO rose to $1.60 a share from $1.49 a year earlier, and occupancy ended the quarter at 95.6%. EastGroup’s quarter looked much the same: average occupancy rose to 96.1% from 95.7%, and same-property NOI grew 7.1% on a cash basis. Yet EastGroup’s stock is up about 10% over the past year, while Prologis’s has gone nowhere.
TIKR tracks 17 analysts on Prologis. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Prologis, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Prologis’ Analyst Ratings
A big step up for a new director
Before this purchase, Kelly held 278 Prologis shares directly, with another 286 held by his spouse. His direct stake is now 4,978 shares, about 18x as many, worth about $622,000 at the price he paid. That’s real money from someone who’s been on the board for less than five months.
Do the numbers back him?
The few analysts who forecast normalized EPS have been raising their numbers. The 2026 consensus has climbed to $3.96 from $3.26 three months ago, and 2027’s to $3.60 from $3.40.
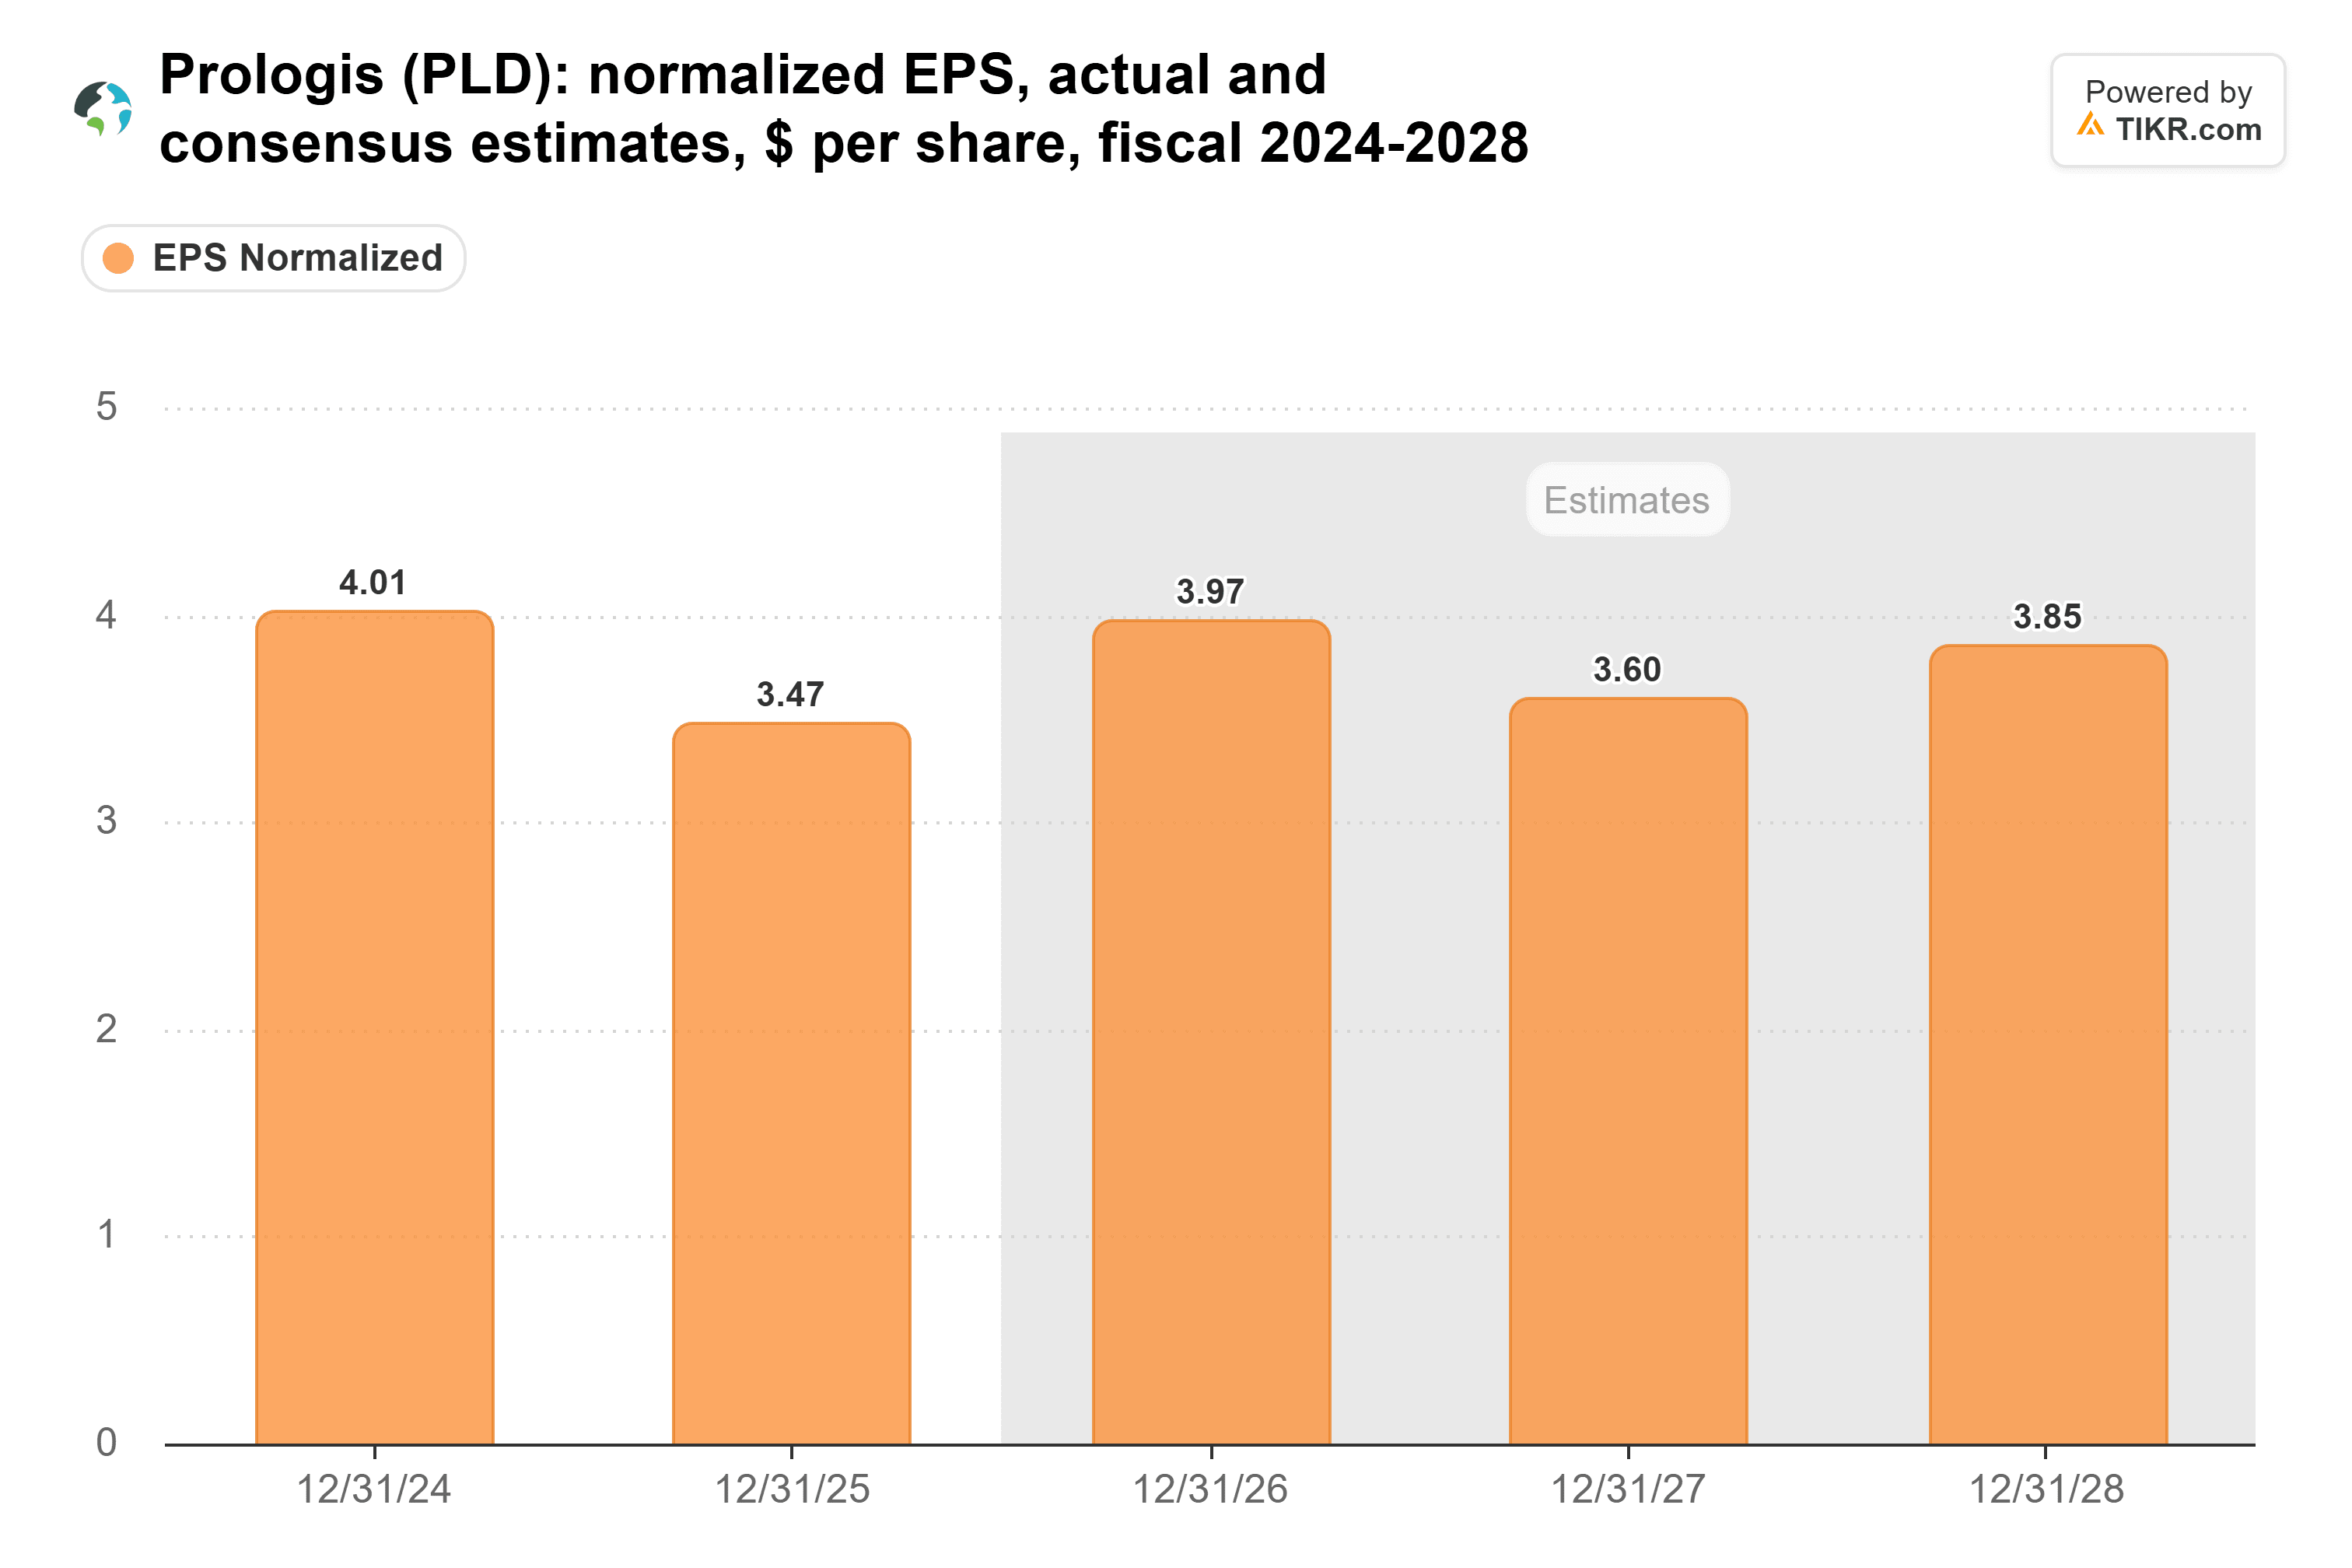
For a REIT, though, core FFO is the figure that counts. In October, Prologis narrowed its 2026 core FFO guidance to $6.25-$6.29 a share, from $6.22-$6.30, even as it cut its net earnings outlook to $4.05-$4.15 from $4.40-4.55.
Kelly also paid a below-average multiple. At $124.97, Prologis trades at about 24x the AFFO analysts expect over the next 12 months, below its five-year average of 27x.
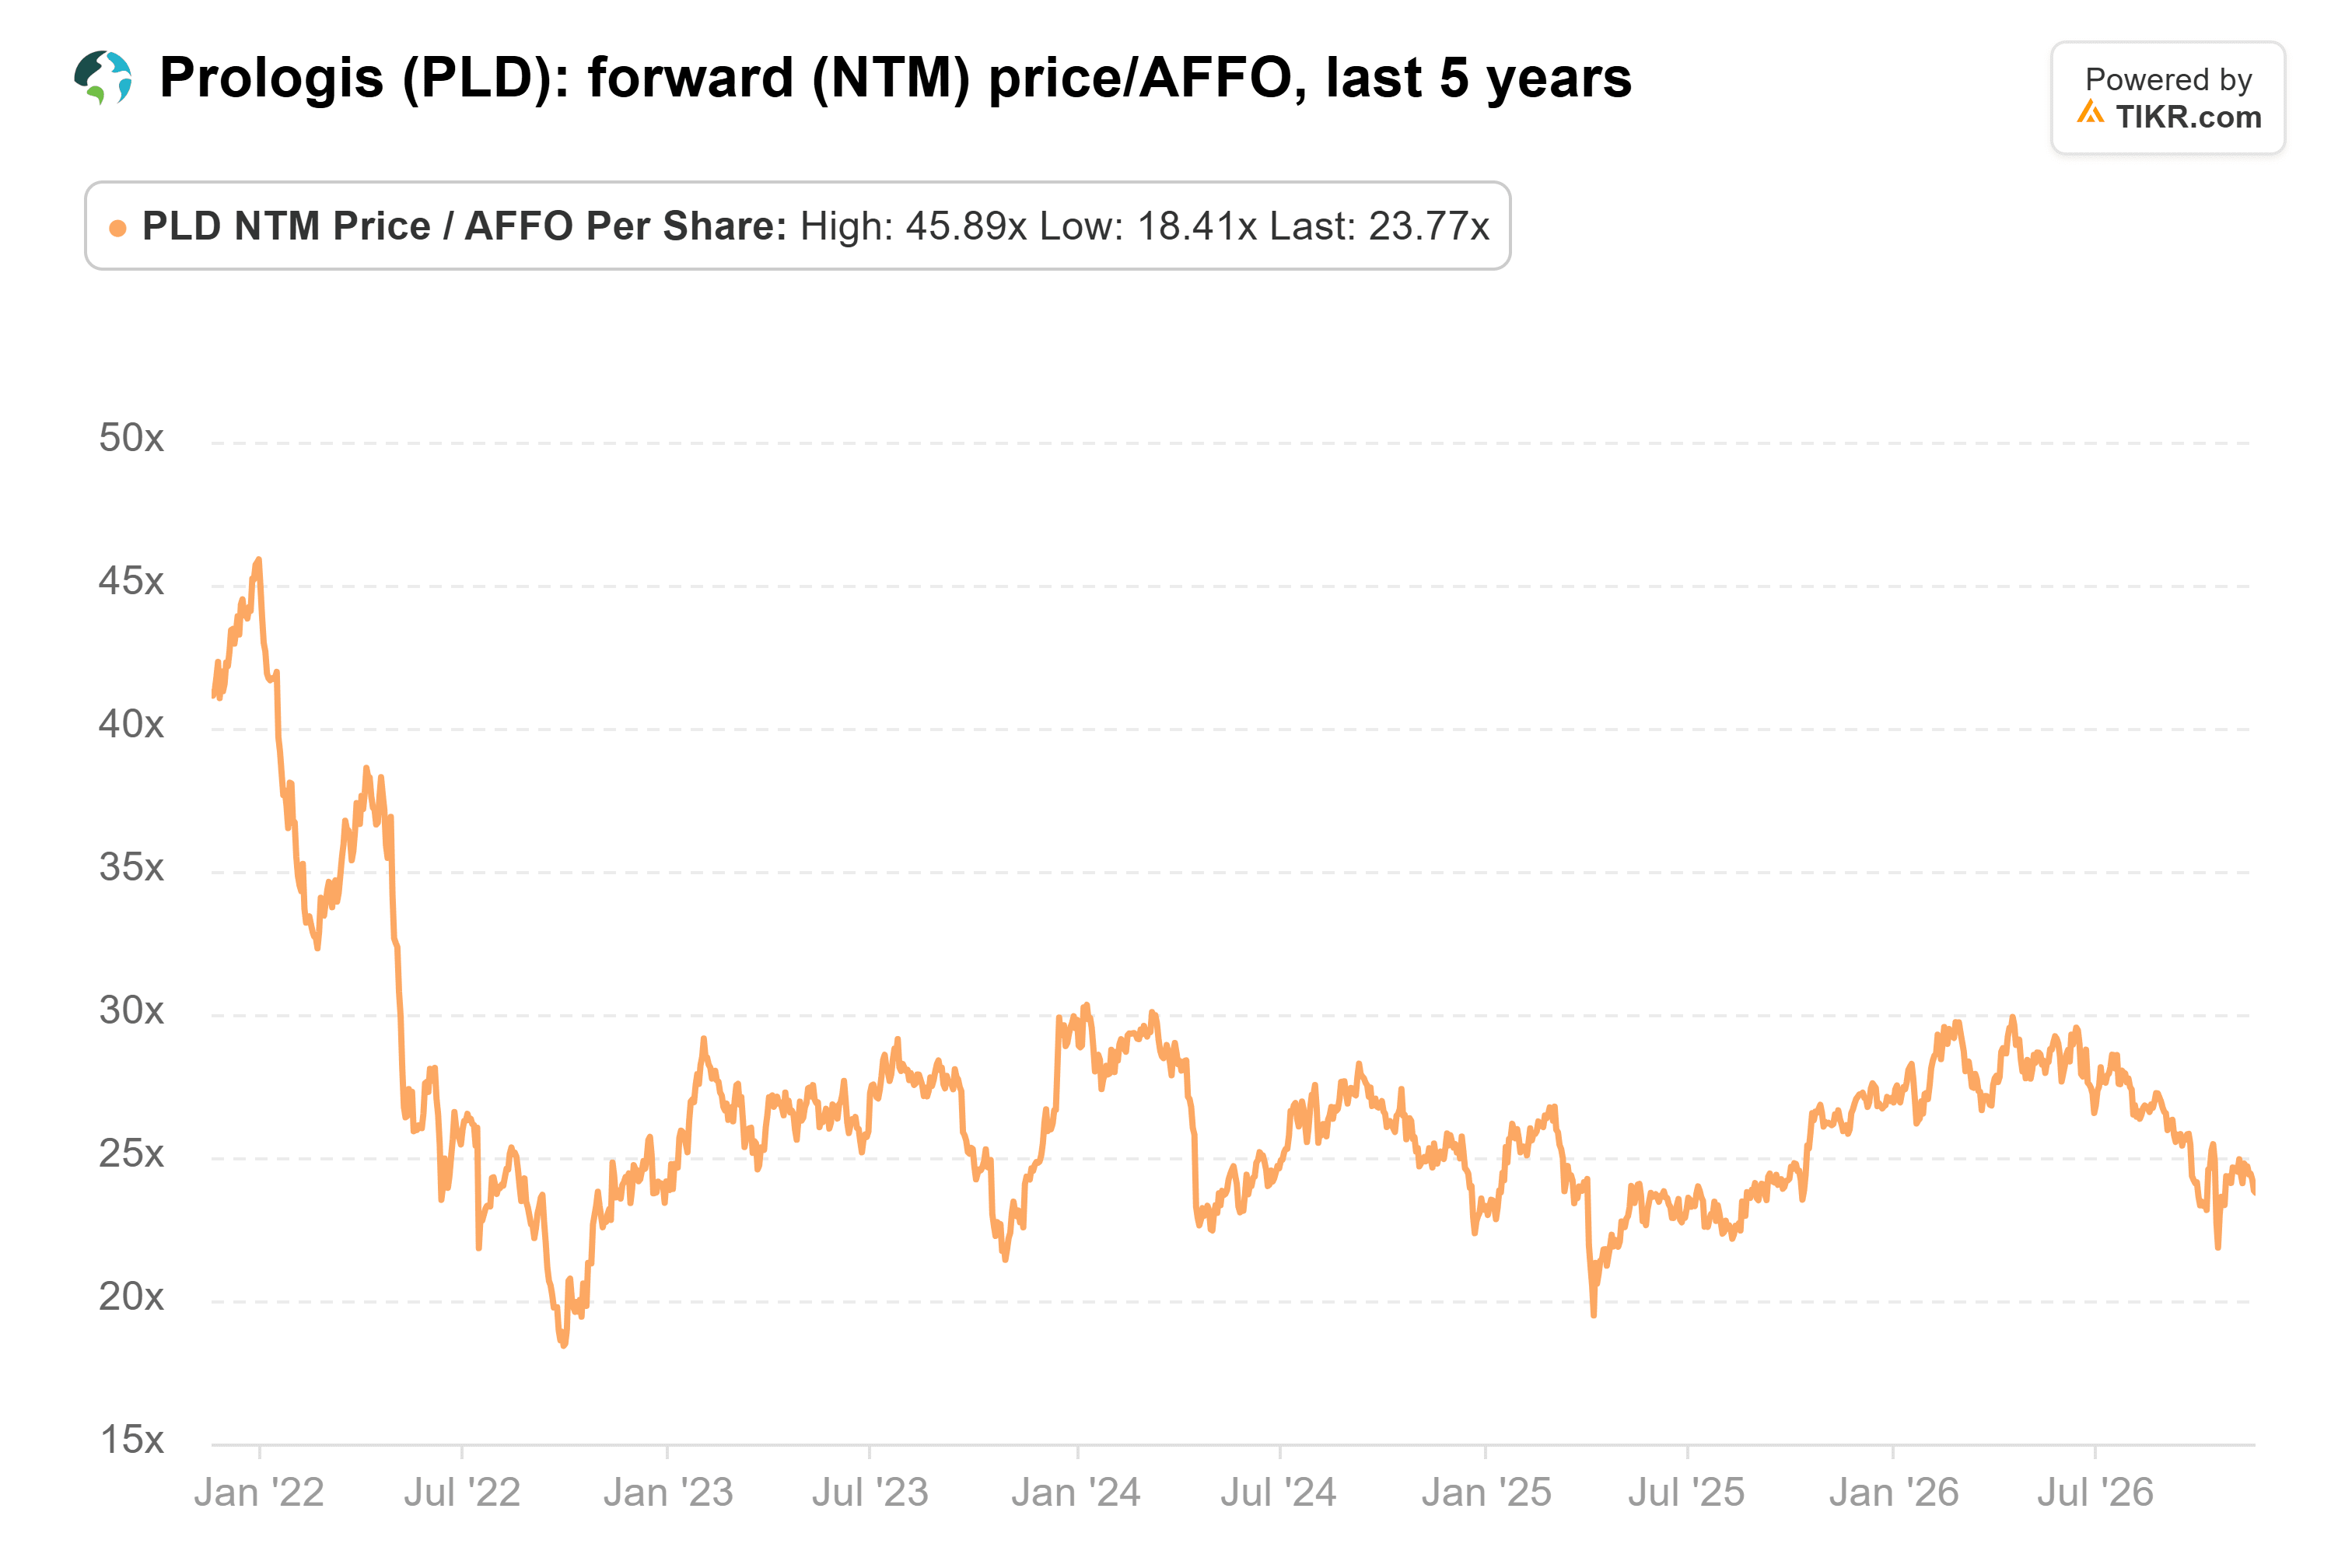
It got as cheap as 18x in September 2022, so there’s room to fall if rates keep climbing.
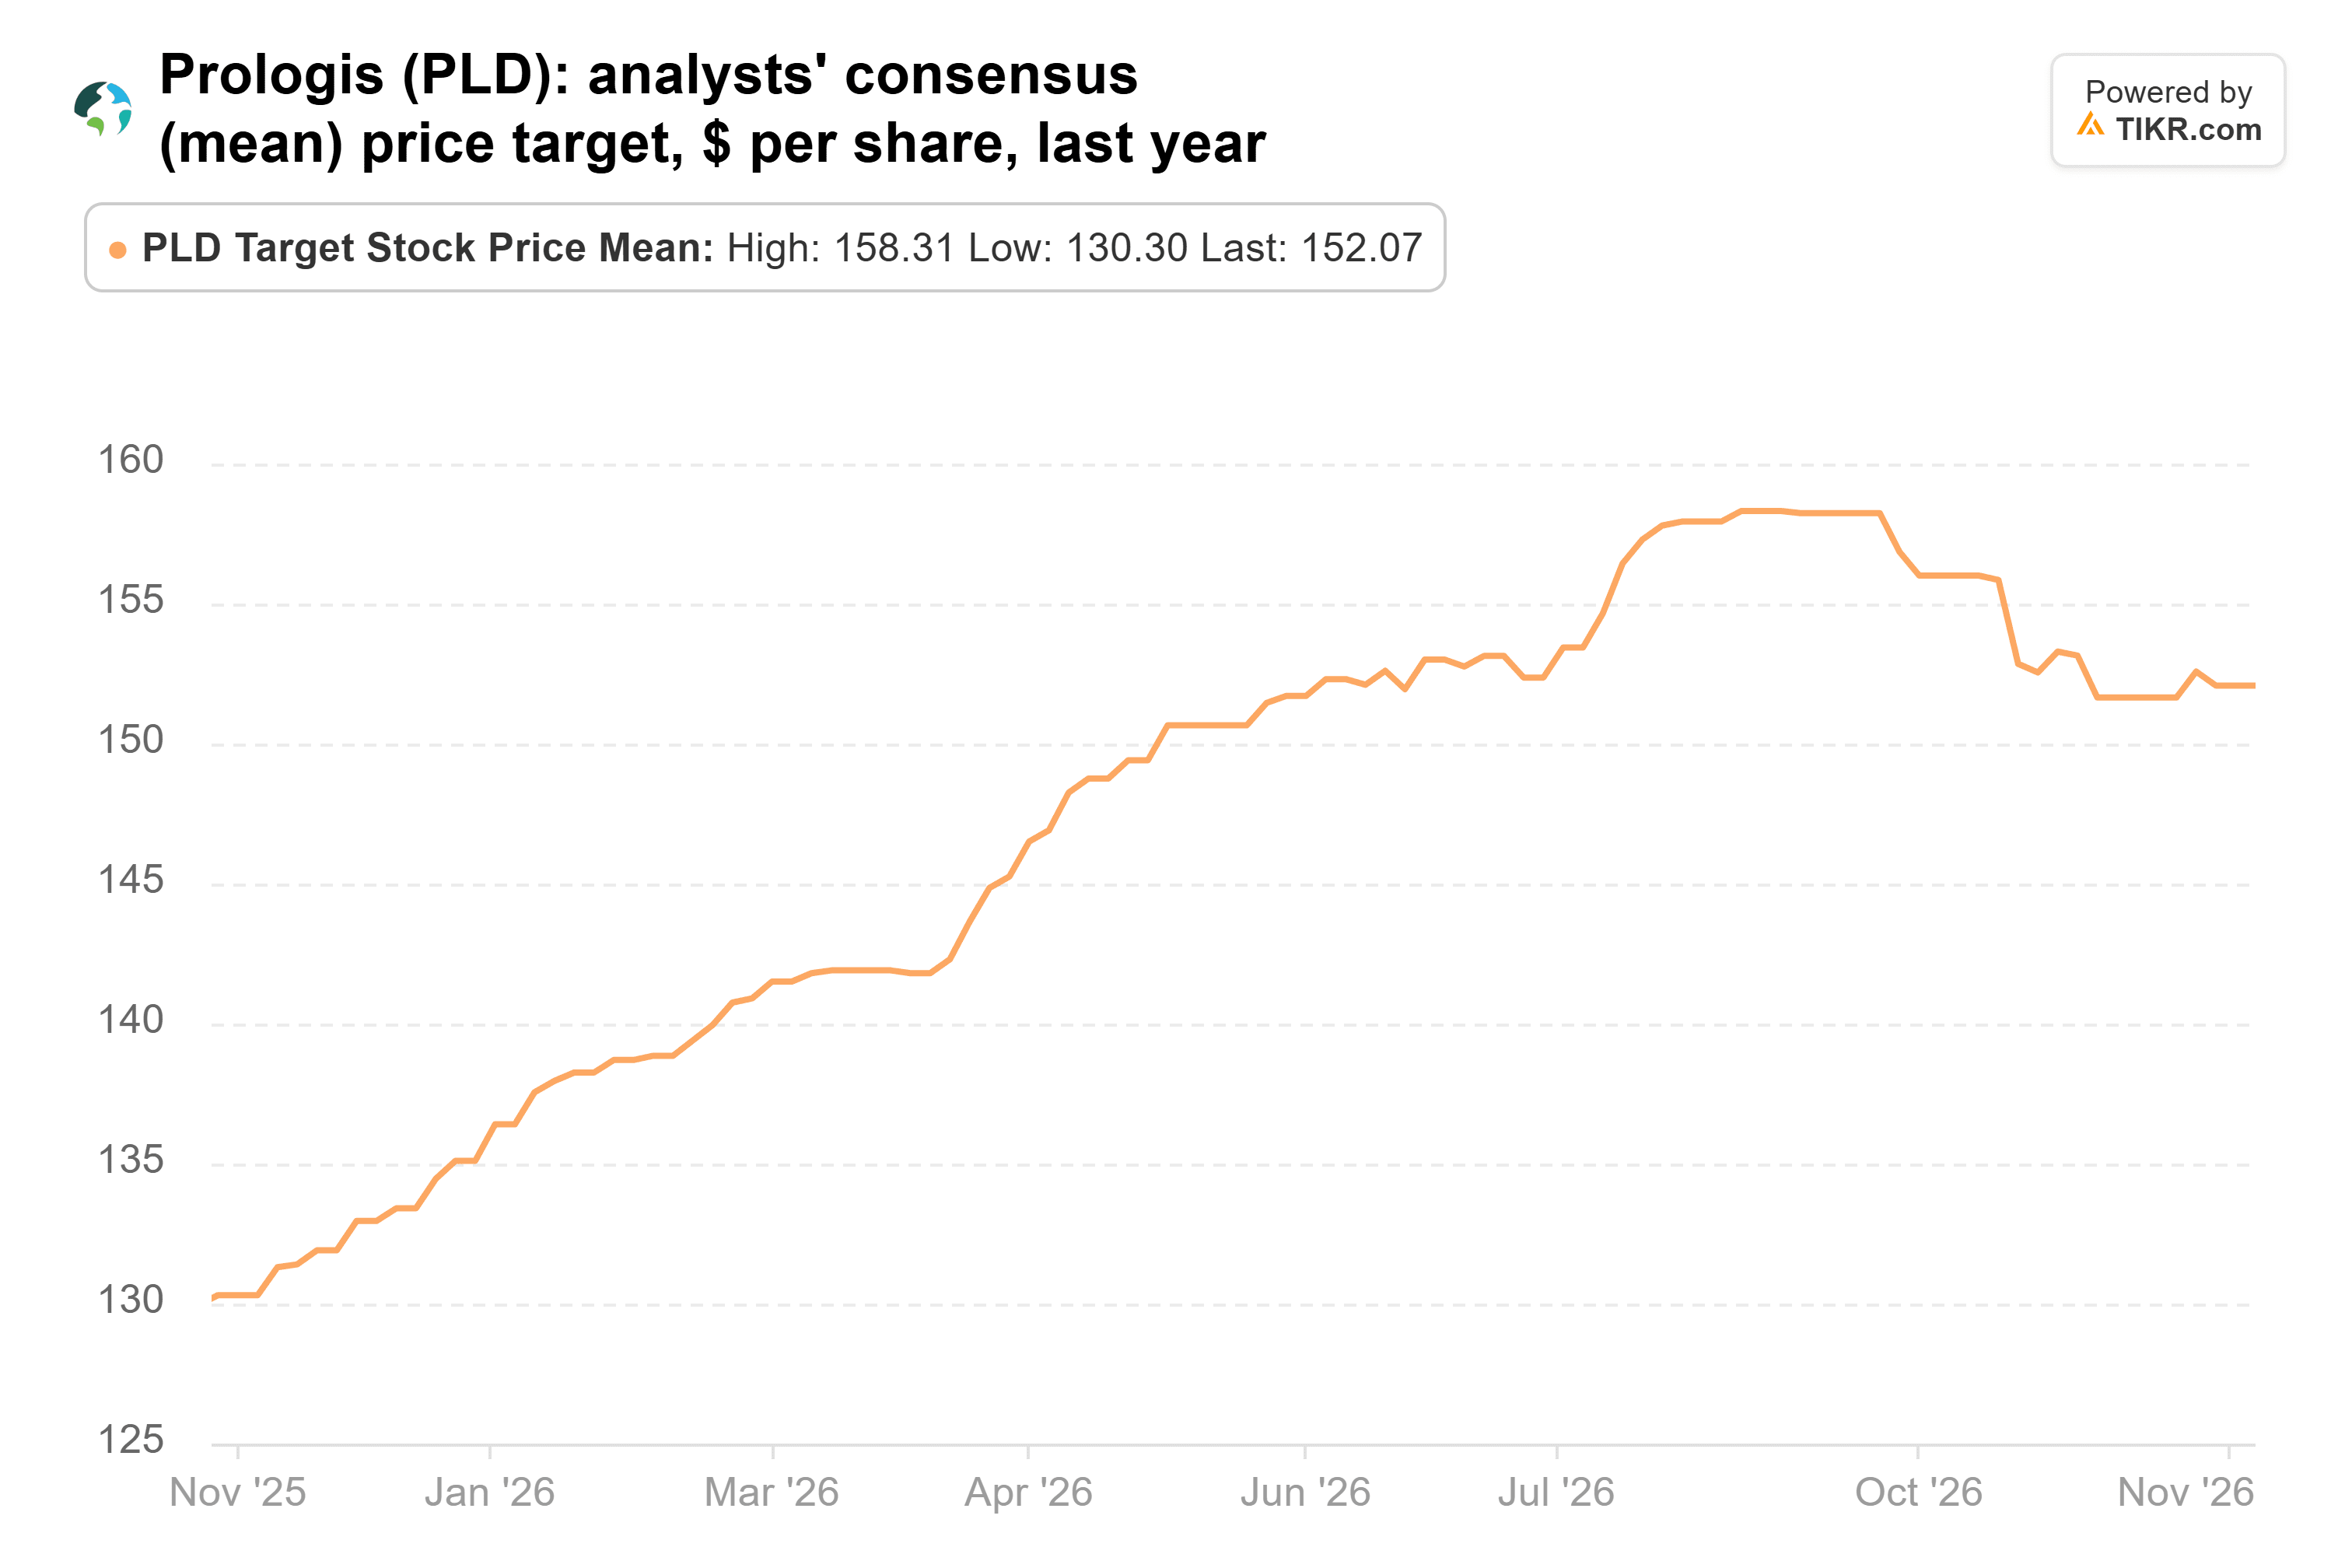
The consensus target is $152, about 23% above the Nov. 19 close of $123.36, and even the lowest target, $136, is above it. Truist cut its target to $141 from $162 in late October but kept its Buy rating. Raymond James upgraded the stock to Outperform from Market Perform with a $163 target on Oct. 21.
What has to go right
The data give his purchase some support. The business is growing, the stock trades below its usual multiple, and every analyst target sits above the price. The risk is that rates keep rising and push property values down further. About 95% of Prologis’s debt is fixed, though, with about eight years left on average.
Still, one director’s buy is a signal, and the case rests on the business. The next test comes with fourth-quarter results in January. Watch whether rent change on rollover holds near the third quarter’s 38%, and what Prologis guides for 2027 core FFO.
So what is Prologis stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Prologis could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!