


Key Takeaways
- Pinterest repurchased $2.02 billion of stock in the first nine months of 2026, helped by convertible notes that raised about $980 million.
- Non-GAAP EPS rose 21% to $0.46 in the third quarter. Non-GAAP net income grew only 3%.
- Third-quarter stock-based compensation of $292 million nearly matched $300 million of free cash flow, and Europe revenue was flat.
- The fourth-quarter report, expected in early February, needs revenue near the top of its $1.425 billion to $1.475 billion guide.
Pinterest’s holiday quarter is underway, and it carries more weight than usual this year.
Pinterest (PINS) spent $2.02 billion buying back its own stock in the first nine months of 2026. It also sold convertible notes that raised about $980 million. Meanwhile, cash and marketable securities fell to $1.47 billion from $2.47 billion at the end of 2025.
That bet looked bolder after October 29. Third-quarter revenue rose 12% to $1.17 billion, short of the company’s own $1.19 billion to $1.21 billion outlook, because cross-border sellers in Europe cut spending.
Snap (SNAP) offers a useful contrast. It grew revenue 14% to $1.72 billion in the same quarter, yet its share count edged up to 1.72 billion from 1.71 billion a year earlier.
Where the $2 billion went
Pinterest front-loaded the buyback. It repurchased $2.02 billion of stock through June, then bought nothing in the third quarter.
The funding came from three places:
- Cash and marketable securities, down about $1 billion this year
- Convertible notes that netted about $980 million, with $99 million spent on capped calls
- Free cash flow of $882 million over nine months
On top of that, Pinterest spent $449 million on acquisitions, including tvScientific.
No quarter in the past two years comes close to the first half of 2026…
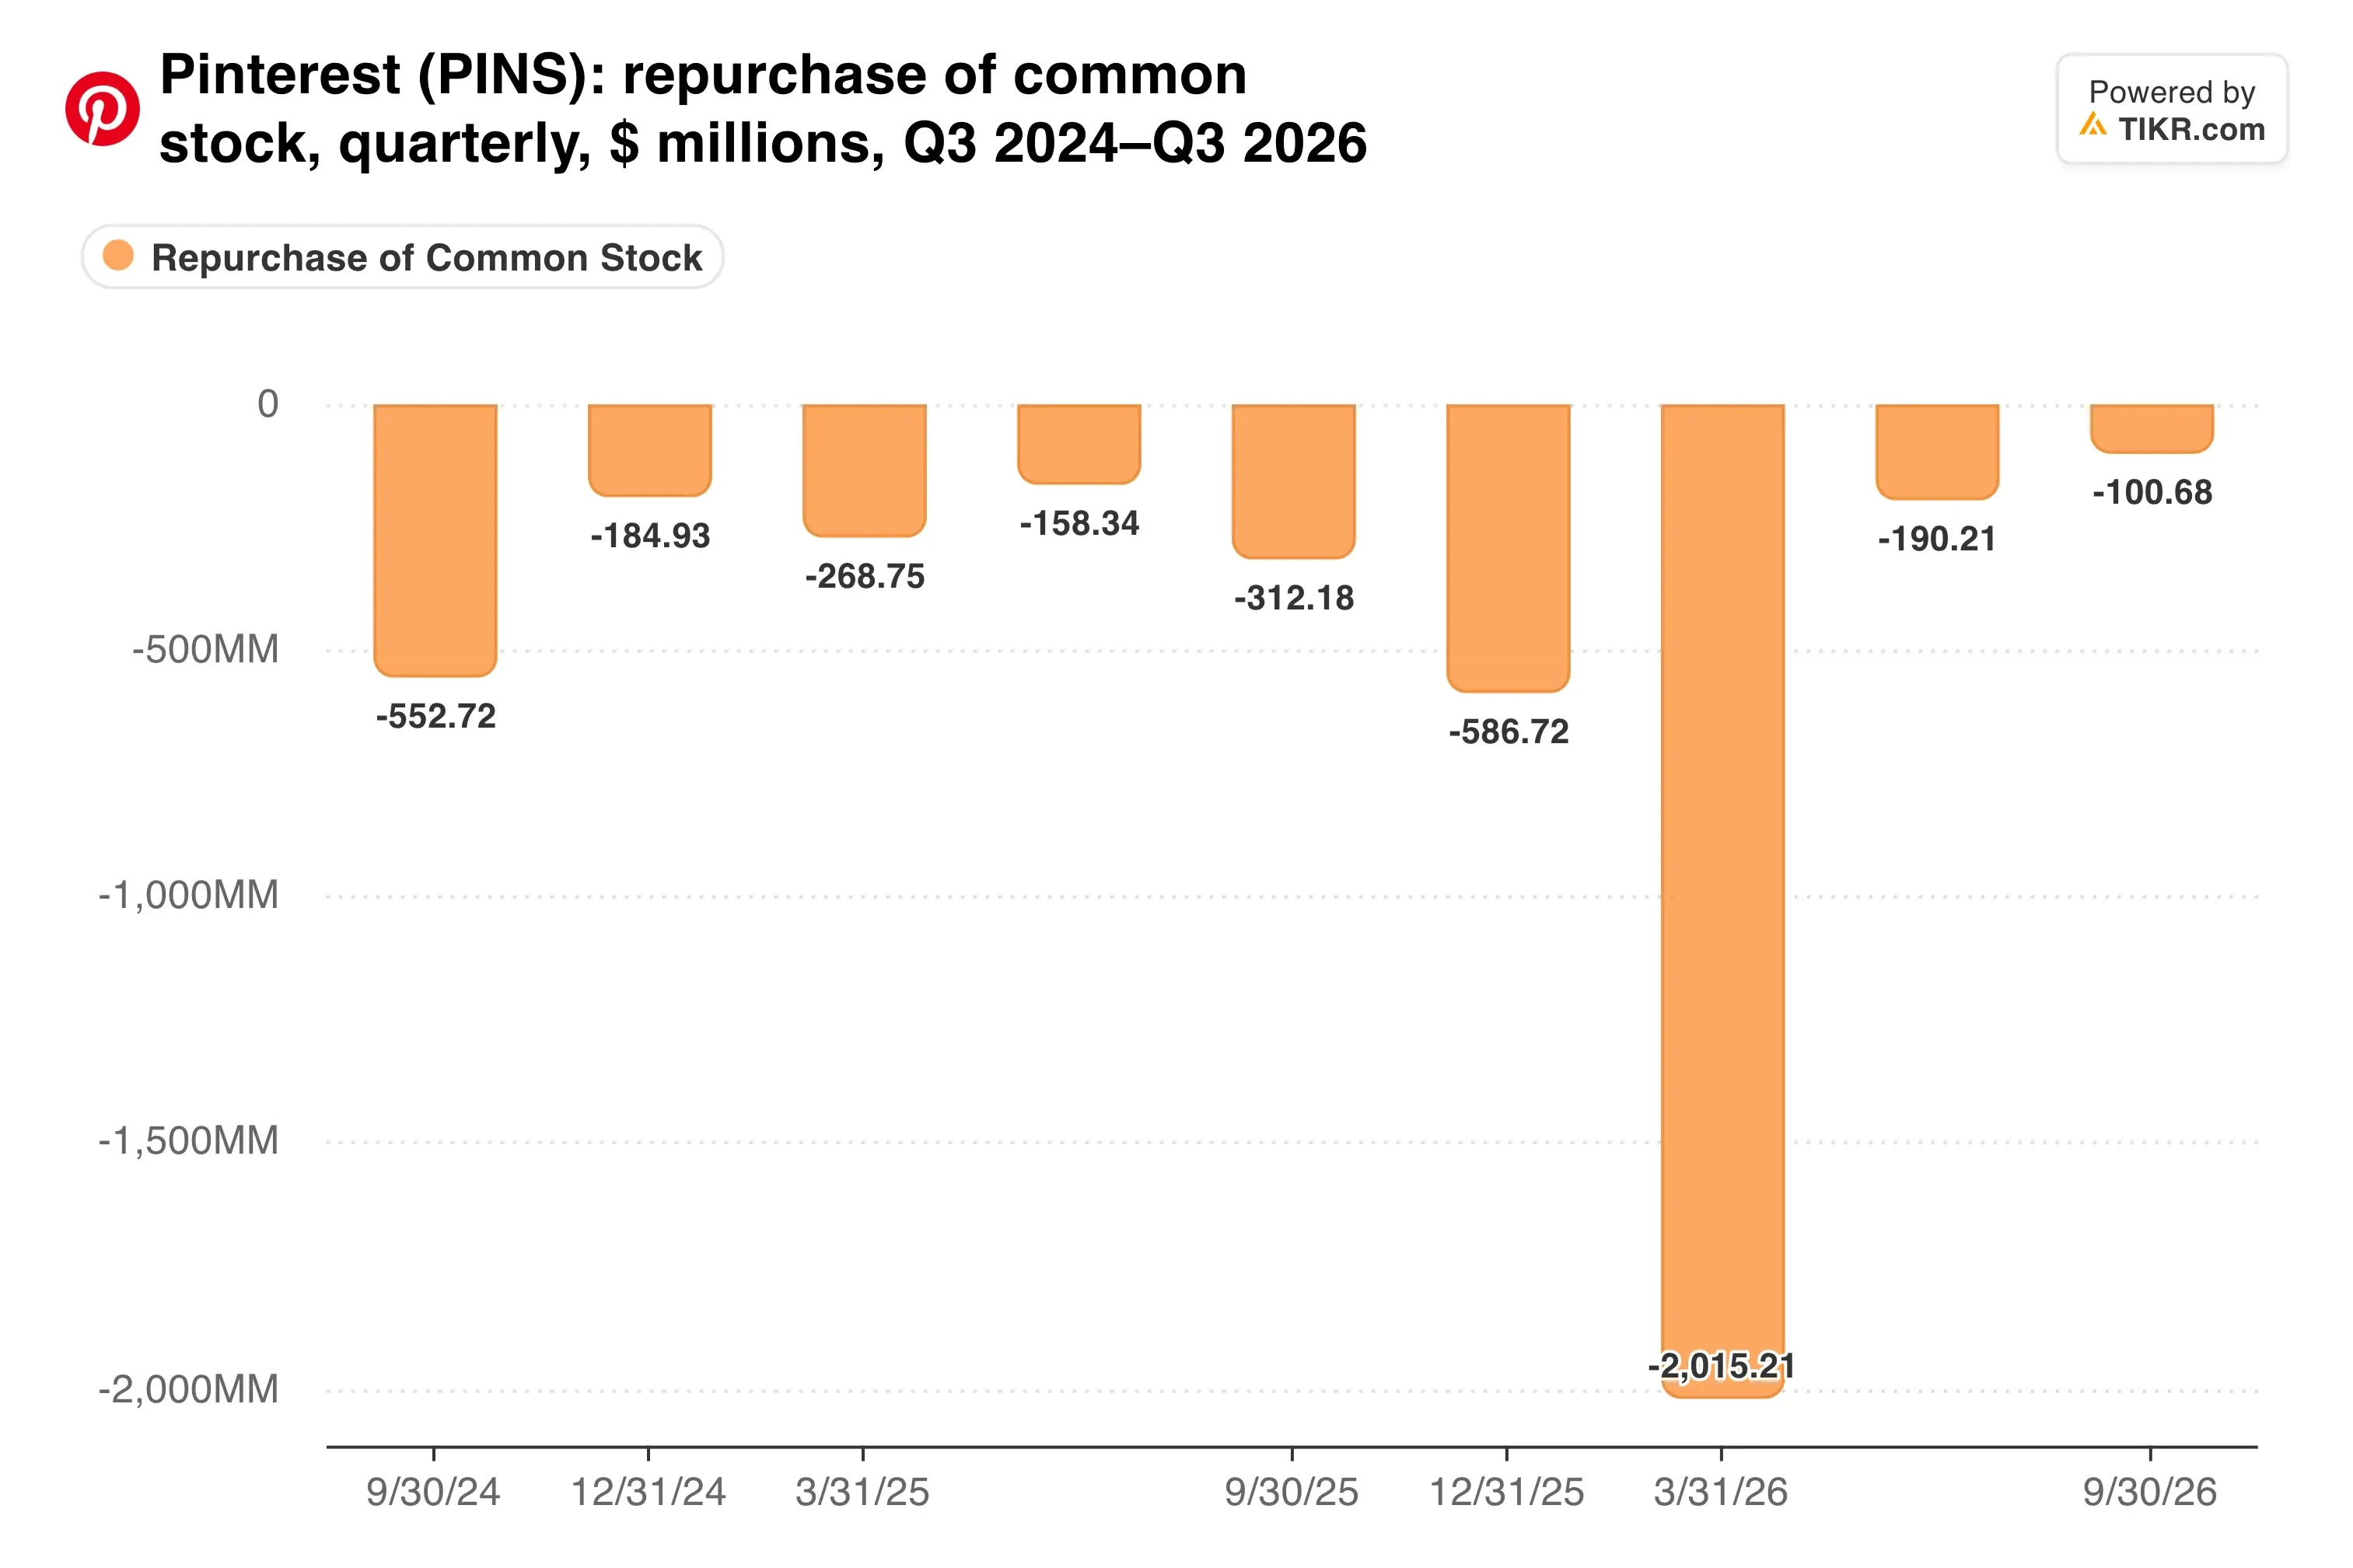
With the third quarter at zero, the heavy lifting looks done for now.
A smaller share count flatters EPS
The payoff shows up per share. Diluted shares averaged 582.7 million in the third quarter, down 16% from 694.5 million a year earlier.
So non-GAAP EPS climbed 21% to $0.46, although non-GAAP net income grew just 3% to $270 million. Adjusted EBITDA rose 11% to $339 million, holding a 29% margin.
How much of the EPS lift came from the shrinking denominator?
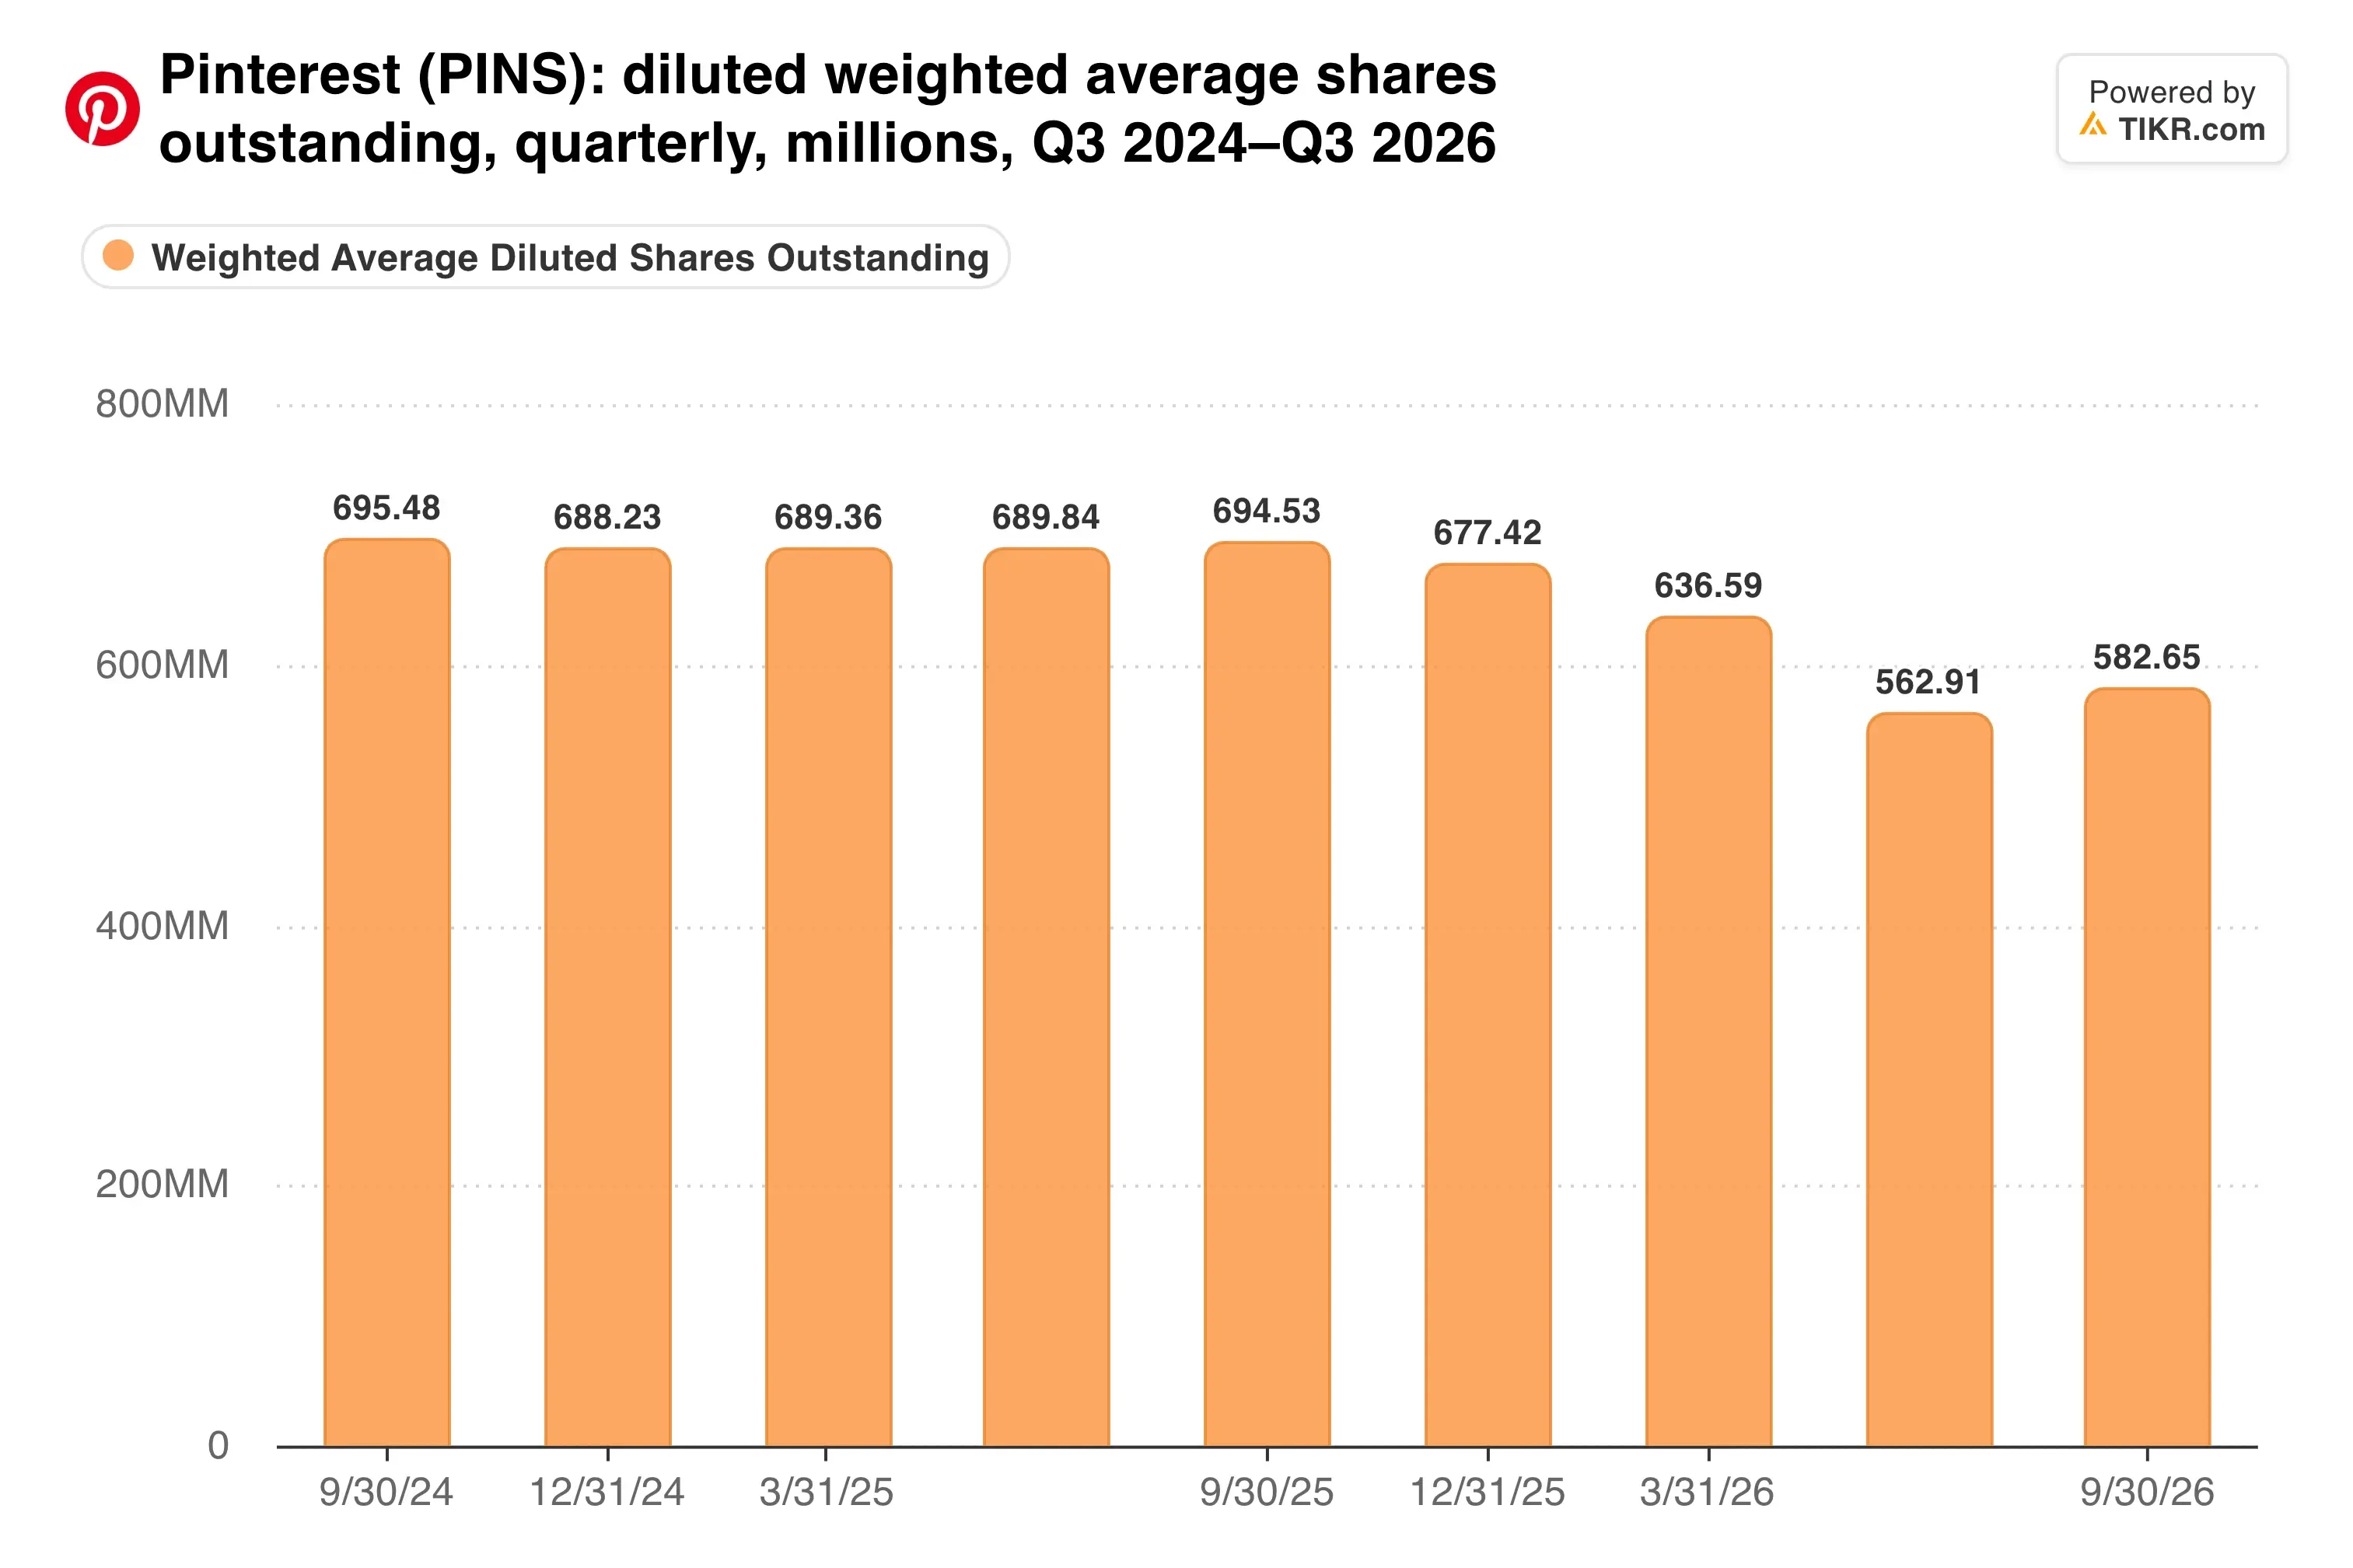
Most of it, judging by the gap between 3% profit growth and 21% EPS growth.
Meanwhile, the operating picture is split. US and Canada revenue rose 14% to $894 million, but Europe was flat at $193 million and European ARPU fell 7%.
In the earnings release, CEO Bill Ready said the company is focused on “sharpening our execution” and scaling performance ads. International sales remain the weak spot.
TIKR tracks 39 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
Stock comp swallows the cash
Here the picture gets harder. Stock-based compensation was $292 million in the third quarter, nearly matching $300 million of free cash flow.
Across nine months, stock comp reached $848 million against $882 million of free cash flow. Pinterest also spent $281 million on shares withheld for employee taxes.
Put free cash flow beside stock comp, and the cushion looks thin…
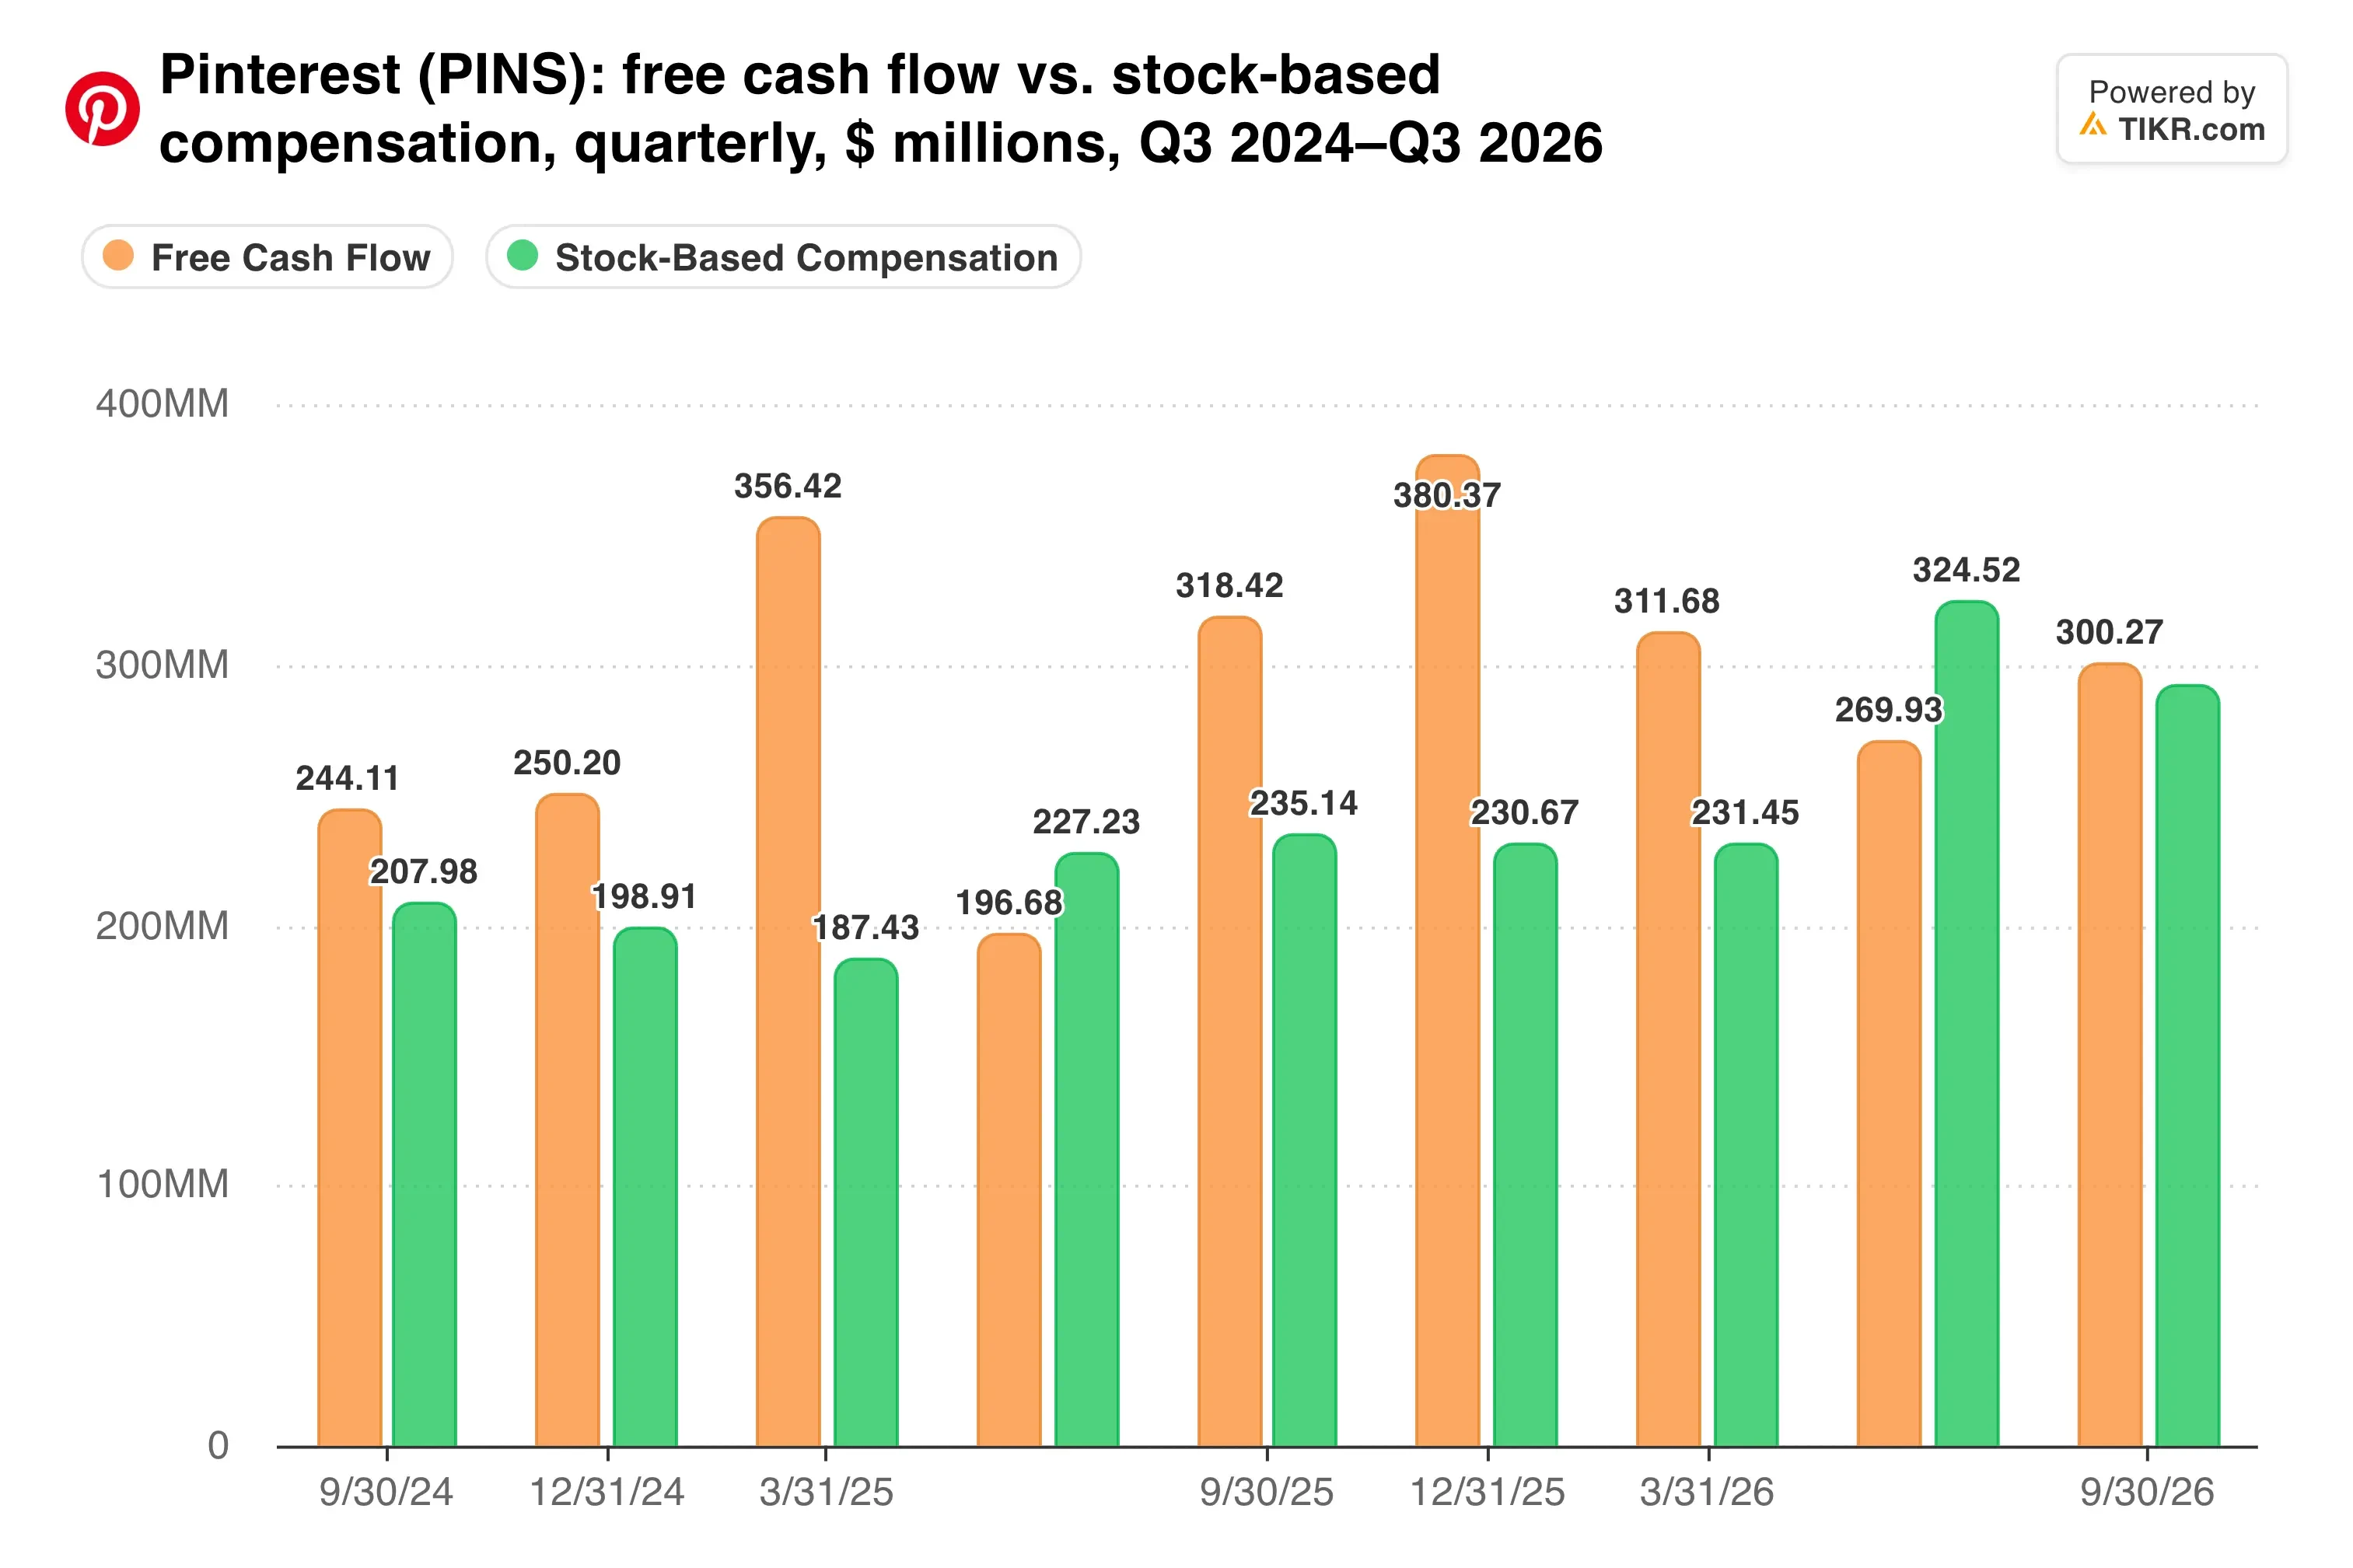
Still, Snap produced only $164 million of free cash flow on far higher revenue, so Pinterest converts better than its closest peer.
Spending down cash has a cost too. GAAP net income fell 77% to $22 million as net interest income dropped to $6 million from $29 million.
My take: The buyback was a defensible use of strong cash generation, and the lower share count is real. Yet Pinterest took on roughly $1 billion of convertible debt while Europe stalled, so organic growth now has to carry the story. I’d wait for proof before trusting the EPS growth.
The fourth-quarter report, expected in early February, is the next test. Revenue needs to land near the top of the $1.425 billion to $1.475 billion guide, with adjusted EBITDA of $538 million to $588 million. It should also show whether Europe is growing again.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


