Key Takeaways
- Peter Thiel’s Thiel Macro raised its Vista Energy stake 59% in the third quarter, to 1.89 million shares worth $123 million, or 26.8% of the US stocks in its 13F.
- Vista’s stock is down 21% since Sept. 30, as oil slid in early November and YPF, Argentina’s other big shale oil producer, fell with it.
- Vista posted record production in the third quarter, and analysts expect its normalized earnings to more than triple this year.
- At 4.5x forward earnings against a 7.2x five-year average, the numbers back Thiel’s bet, as long as oil holds up.
Peter Thiel’s macro fund now has more than a quarter of its US stocks in one Argentine oil producer, Vista Energy (VIST). That’s according to Thiel Macro’s 13F for the quarter ended Sept. 30, filed Nov. 16.
It’s been a rough ride since then. The whole drop came in November, as oil prices slid and pulled down YPF (YPF), the biggest operator in Argentina’s Vaca Muerta shale, along with Vista.
More than a quarter of the fund
Thiel Macro’s 13F holds $460 million of US stocks across just five positions. Vista is the third-largest: 1.89 million shares worth $123 million at Sept. 30, or 26.8% of the total, after the fund raised its share count 59% during the quarter. That’s a concentrated bet on a single shale producer.
A 13F only shows what a fund held on the quarter’s last day. So it can’t tell us when Thiel added, what he paid, or whether he still owns every share. The 21% drop runs from Vista’s price at the quarter’s end to its latest close, so it isn’t Thiel’s own return. Anyone following him now gets in far below the price in the filing.
TIKR tracks 12 analysts on Vista Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Vista Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Vista Energy’s Analyst Ratings
The business is doing just fine
Vista reported its third quarter on Oct. 28, and it was a strong one. Production hit a record 169,000 barrels of oil equivalent a day, up 33% from a year earlier. A full quarter of the Bandurria Sur and Bajo del Toro stakes, which Vista has consolidated since May 1, helped. Adjusted EBITDA rose 78% to $841 million and free cash flow came to $334 million. Net debt fell to 1.12x adjusted EBITDA from 1.41x the quarter before.
The weak spot was price. Vista realized $84.20 a barrel, 6% less than in the second quarter, as Brent cooled.
Oil fell harder in early November. On Nov. 4, Vista dropped 9% and YPF 7%. YPF’s third quarter had also brought record Vaca Muerta output, with its shale production up 32%. When the basin’s two biggest oil producers fall together right after record quarters, the market is trading oil. Neither company’s results gave it a reason to sell.
Vista seems to see it that way too. It bought back $55 million of stock in the third quarter under a $150 million plan for the year. In November it has reported buying back 30,000 shares on most trading days.
Cheap against its own history
Analysts expect Vista’s earnings to keep climbing:
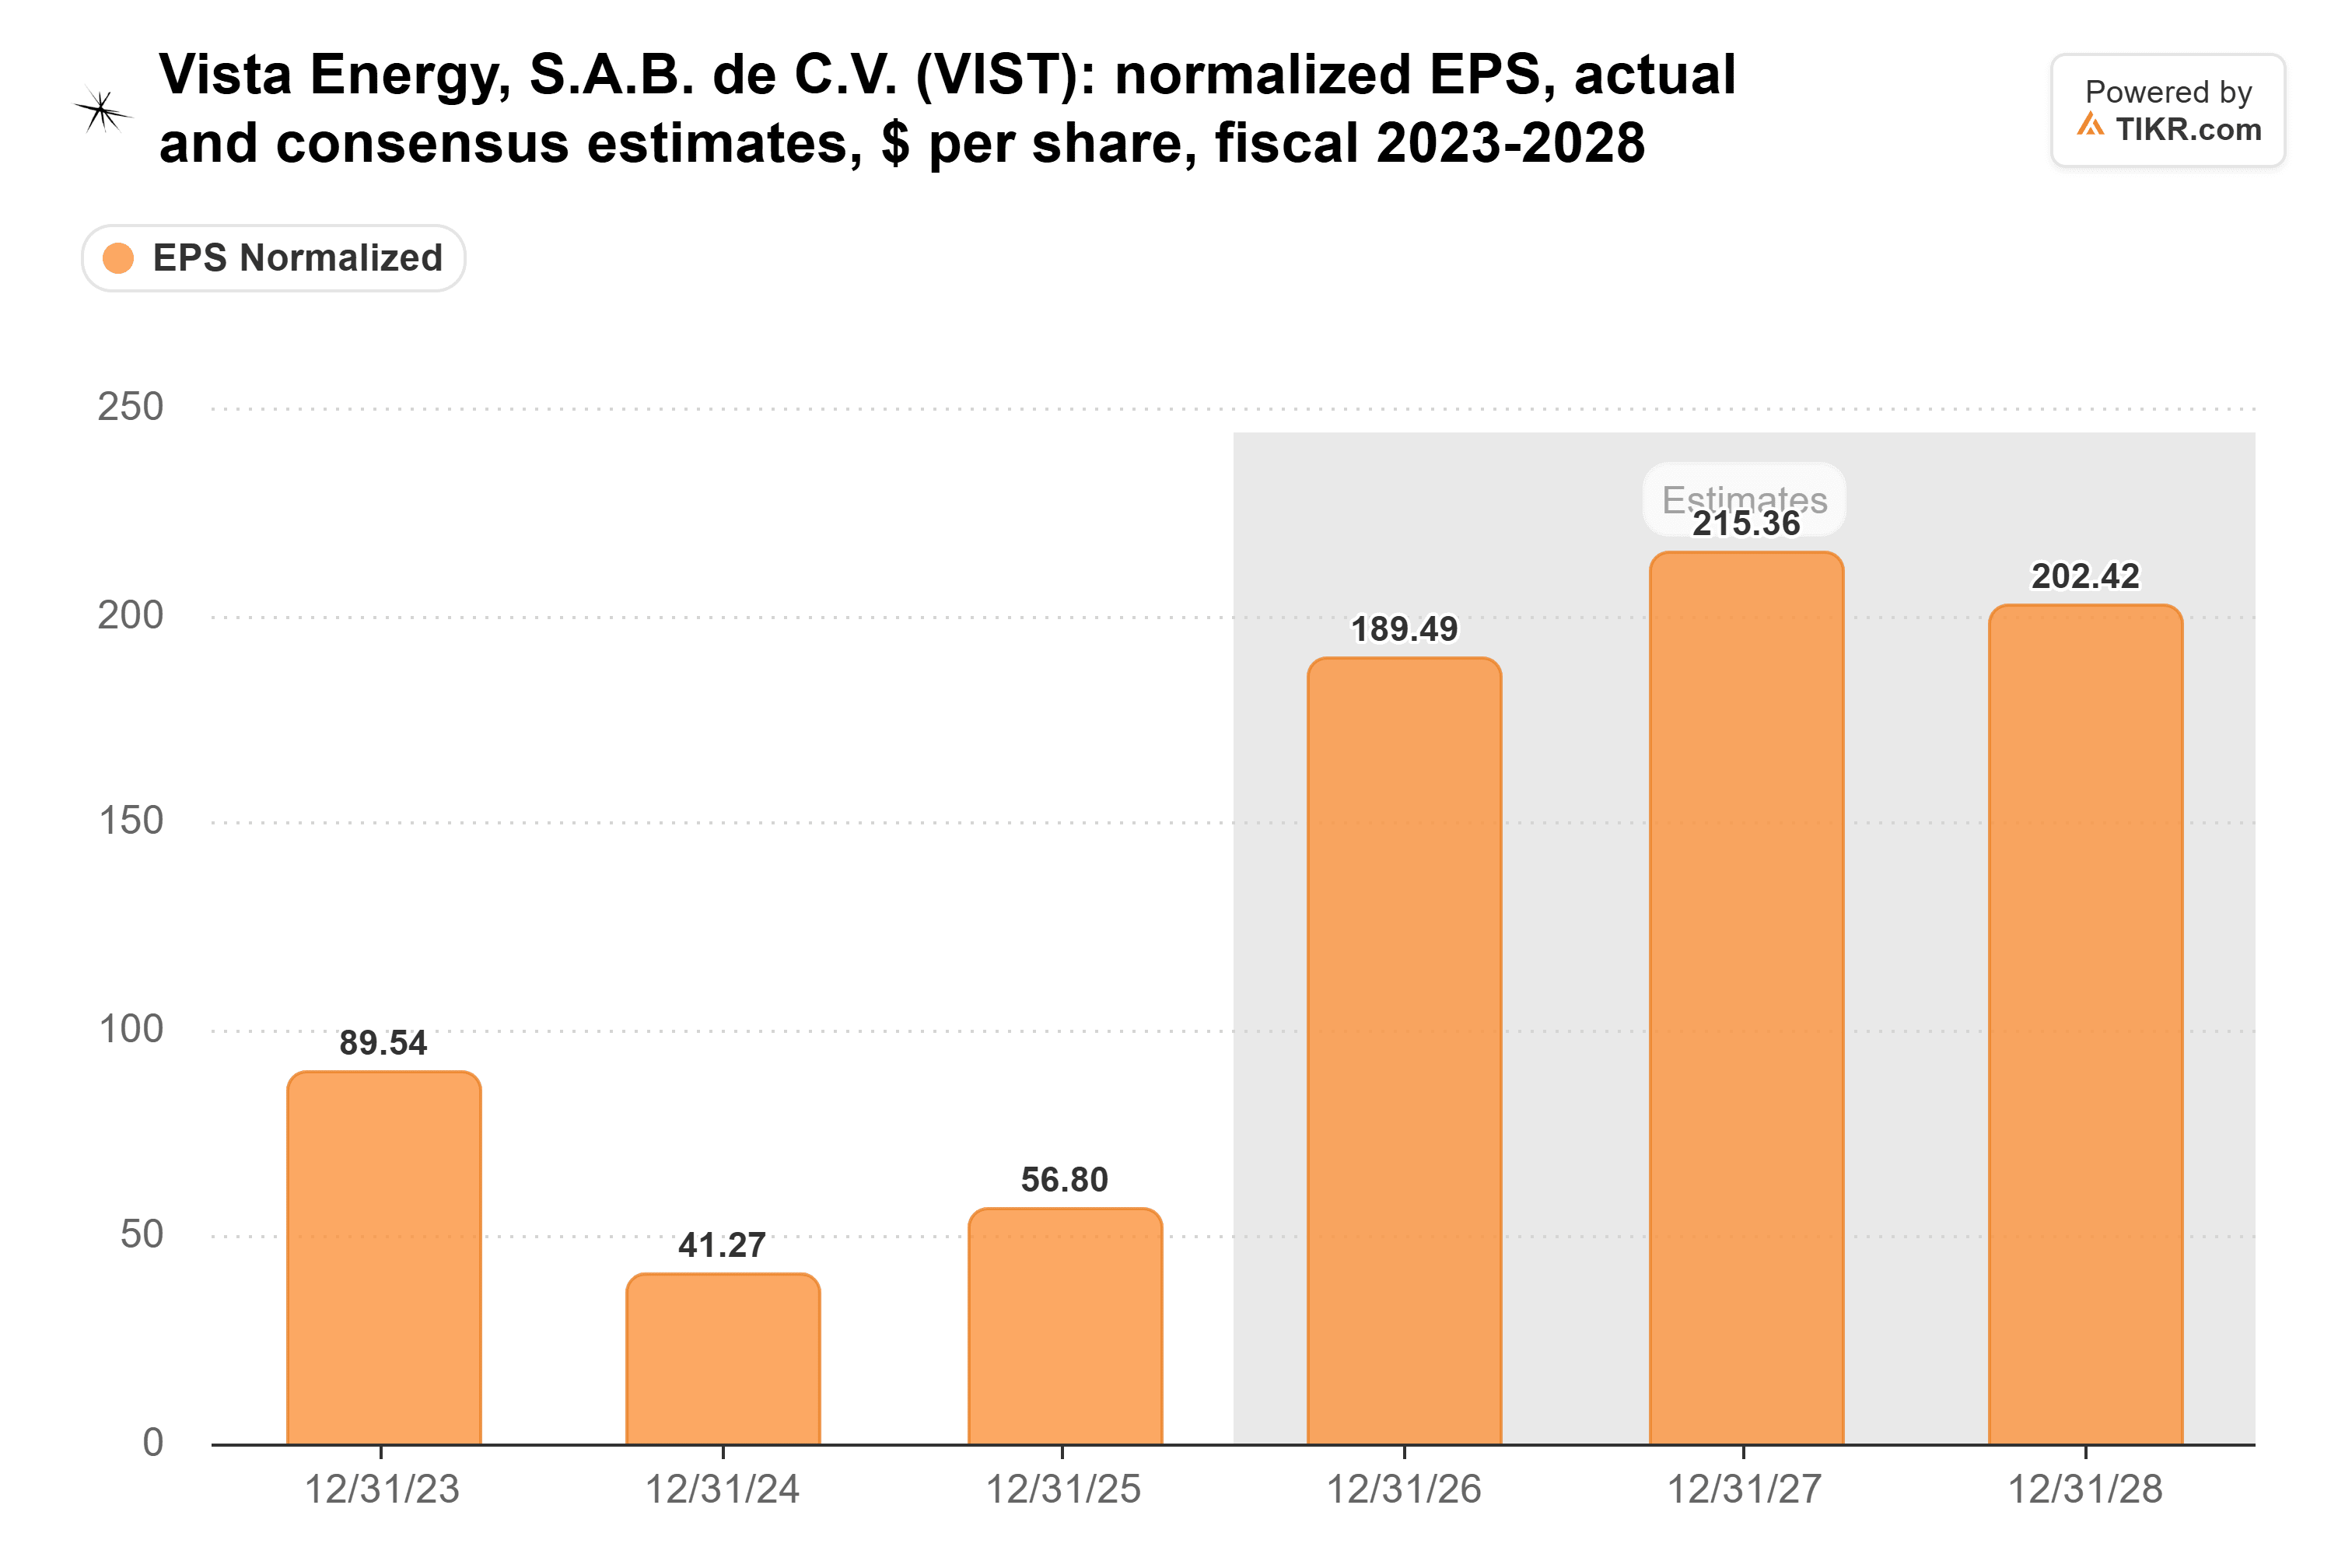
Consensus has fiscal 2026 normalized EPS at more than 3x fiscal 2025’s, with another step up in 2027 and a small dip in 2028. Those estimates came before oil’s November slide. Vista’s 2027 target of 185,000 barrels a day assumes Brent at $80, so a weaker oil price could still pull them down.
The stock already trades well below its usual multiple:
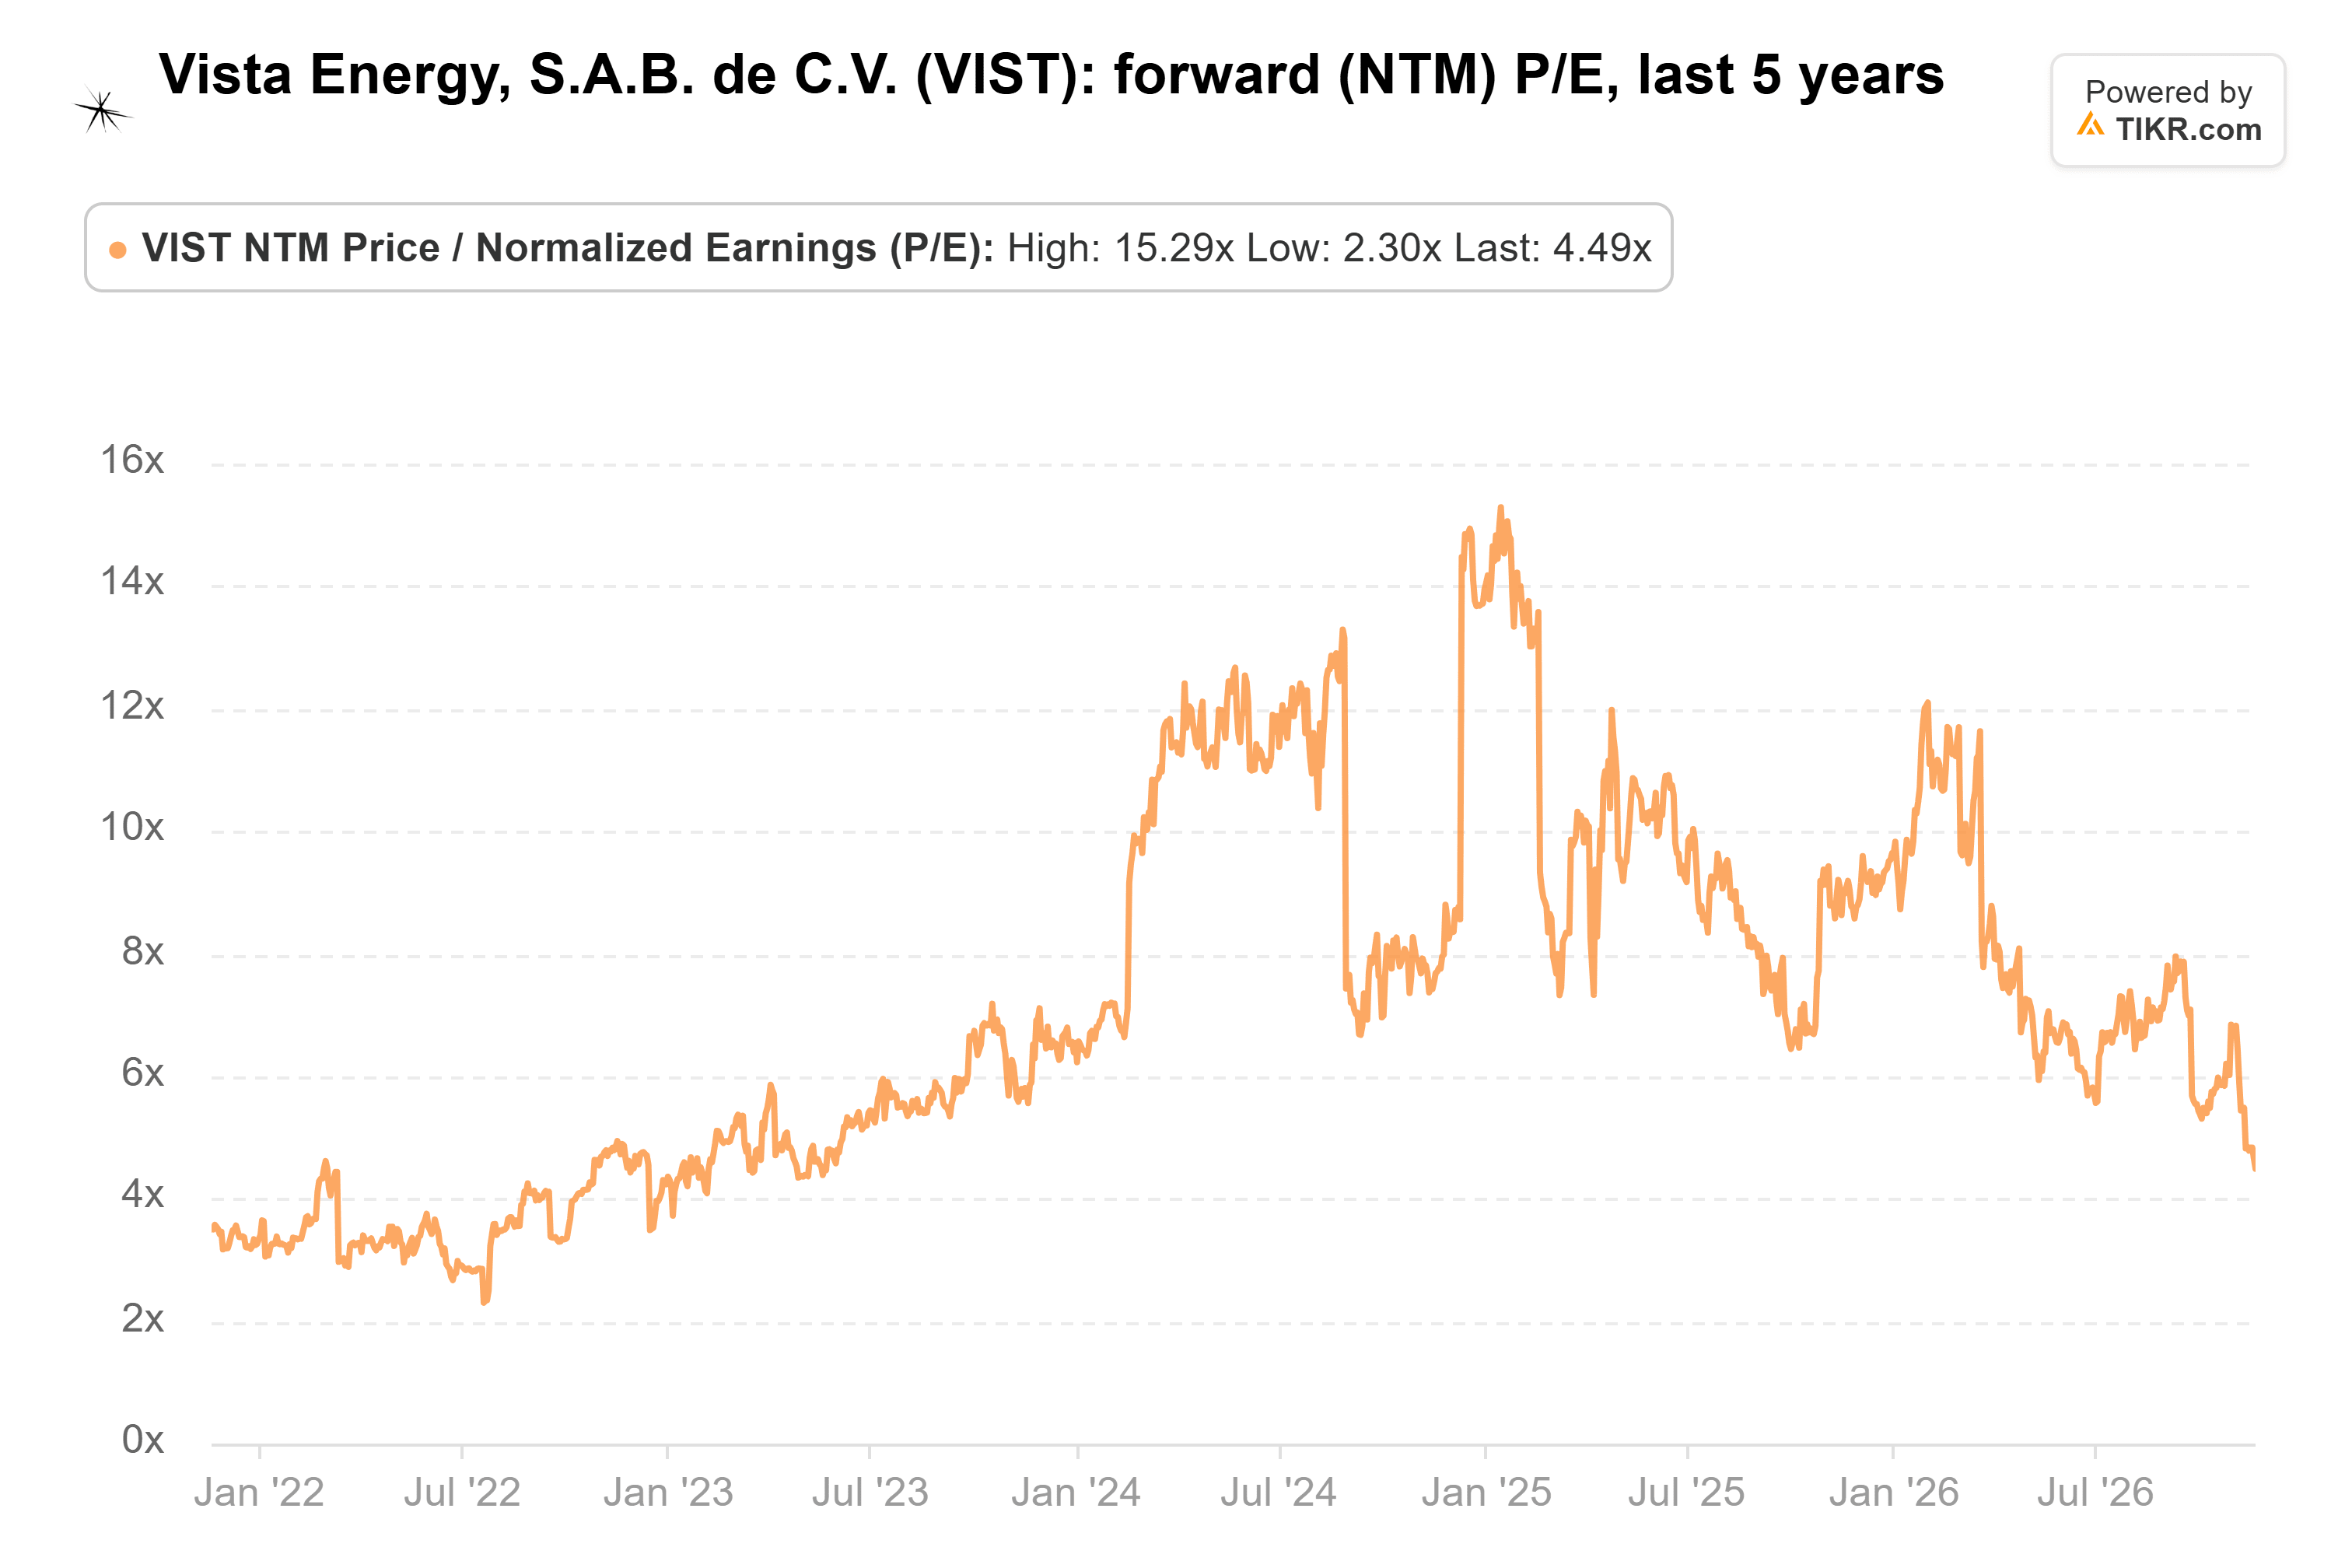
At 4.5x forward earnings, Vista sits well under its 7.2x five-year average and nowhere near the 15.3x it hit in January 2025.
Over the past year, the analysts’ average target has risen by more than 40%, while the stock has ended up about where it started:
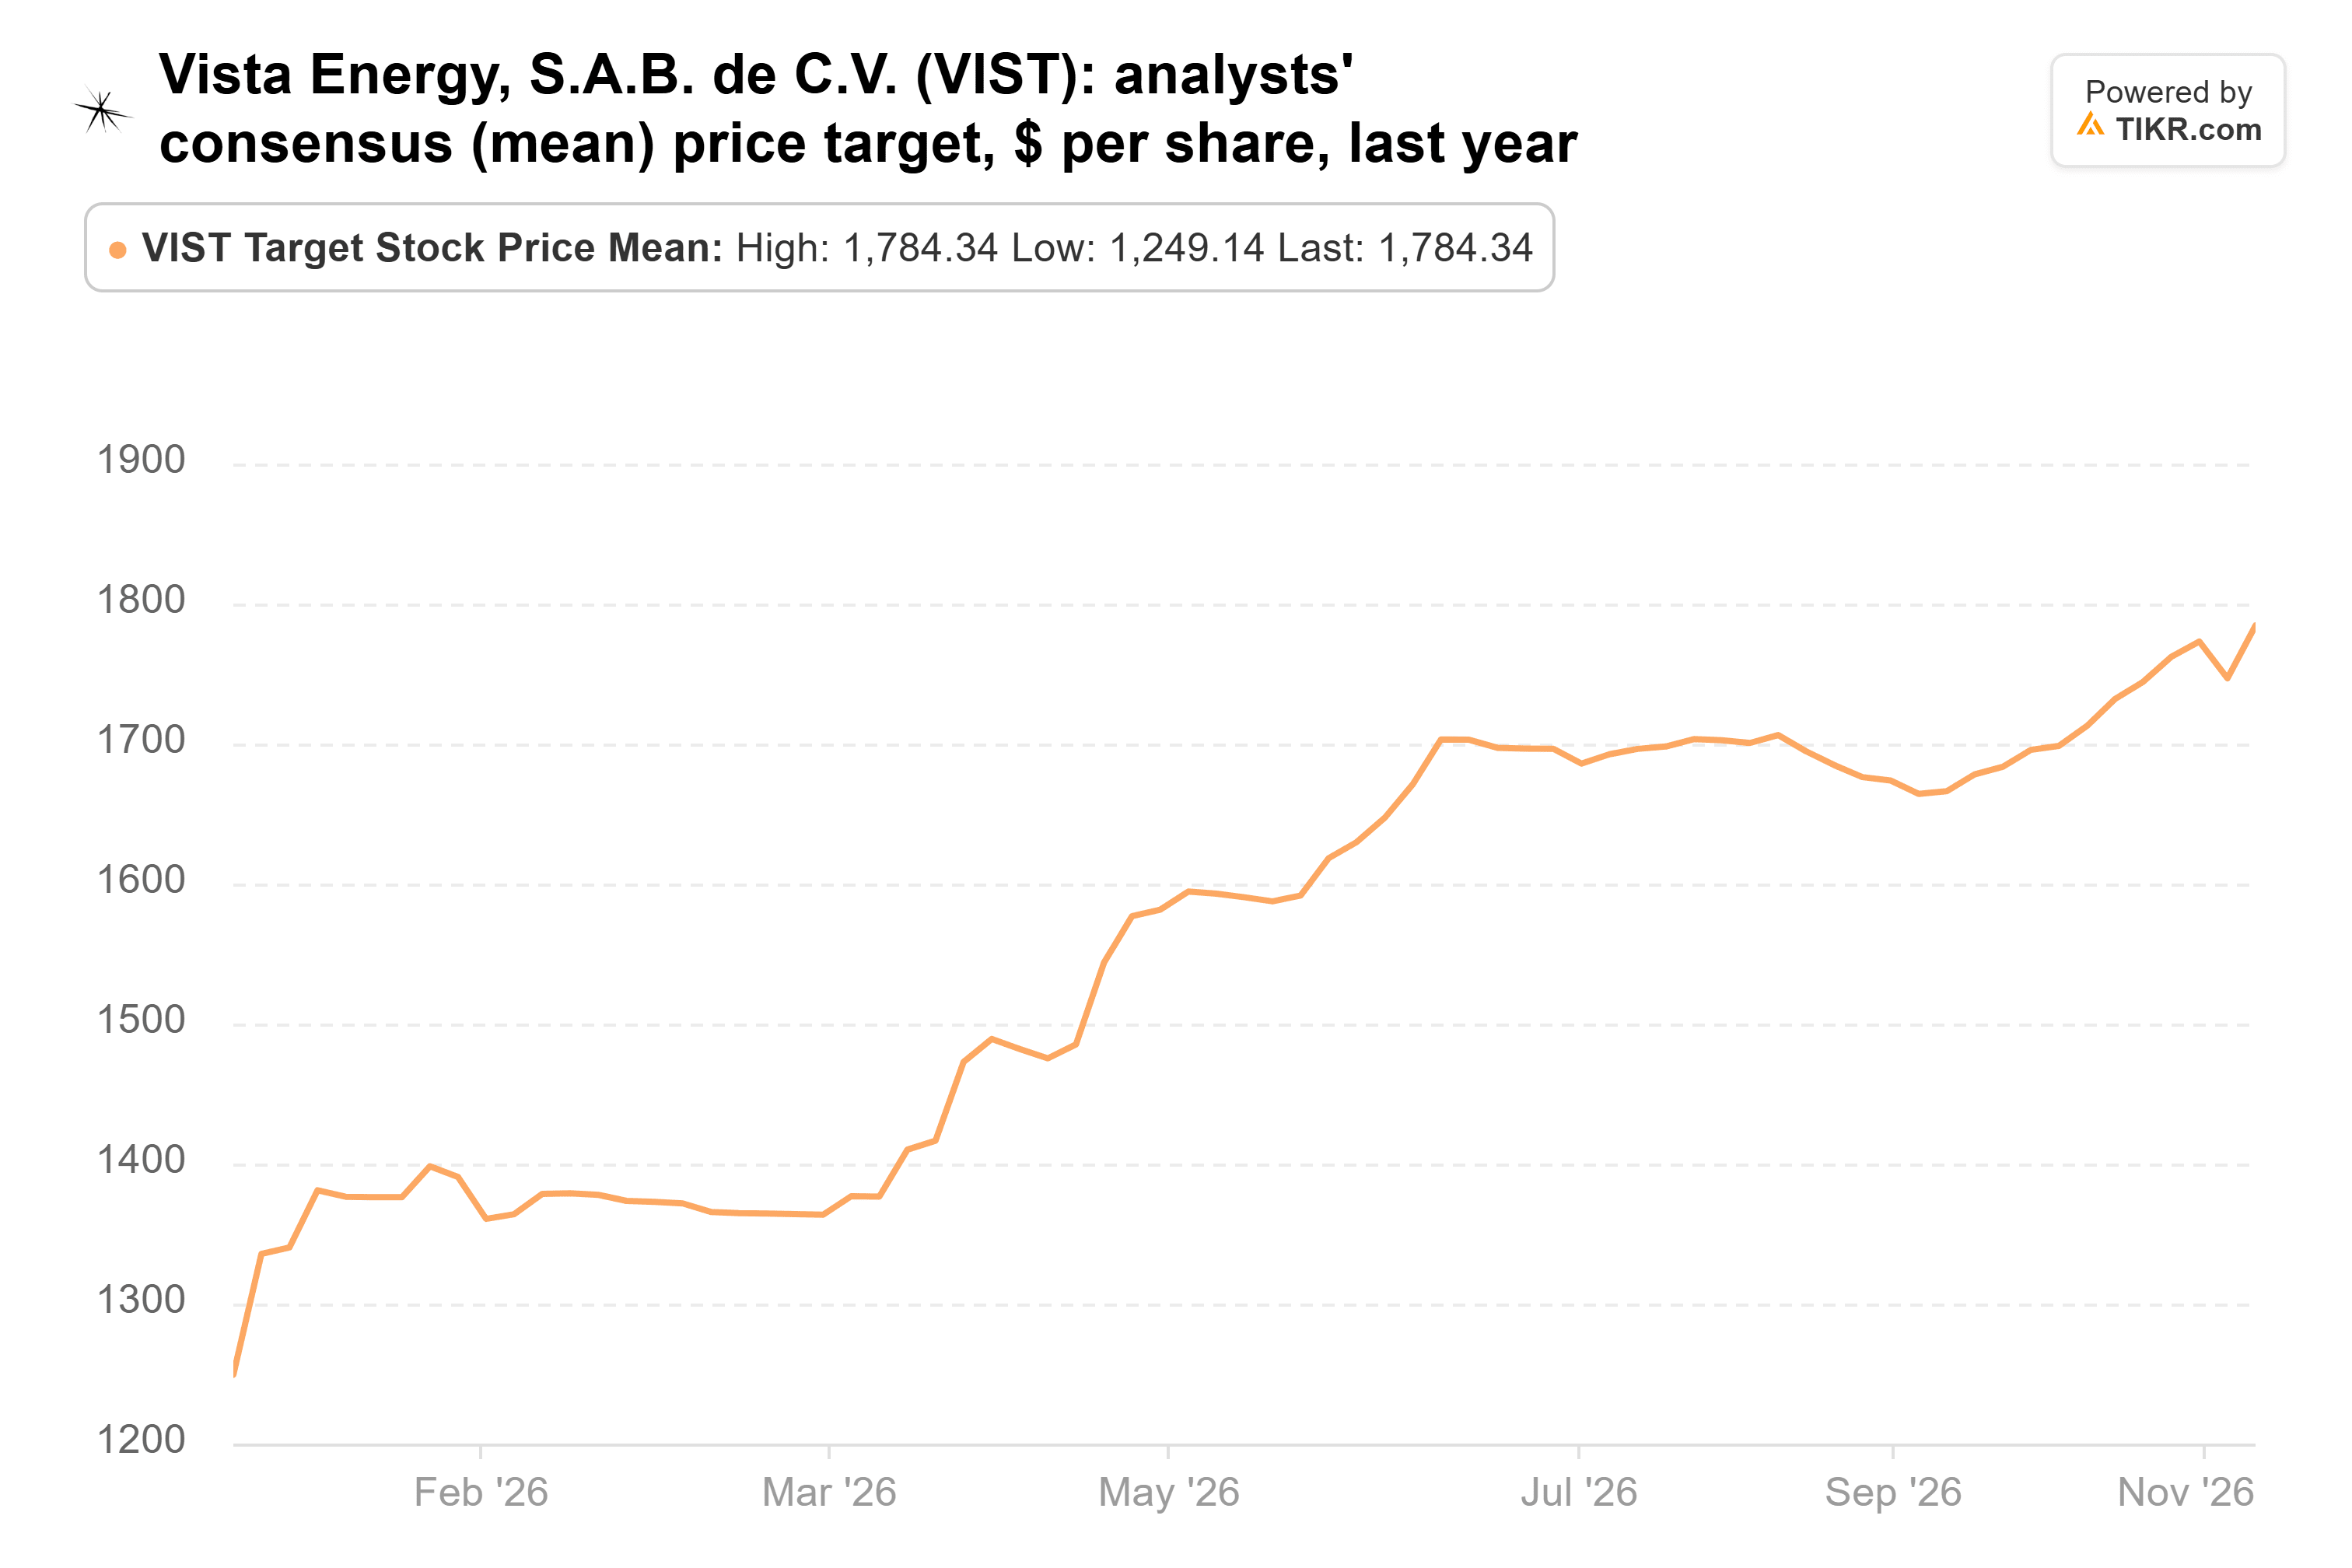
Twelve analysts cover Vista, and their average target of $96.07 sits 85% above the latest close. UBS raised its target to $100 from $80 this week. By my math, that average target is about 9x 2028 earnings, a bit above Vista’s own average. Since 2028 estimates sit a touch below 2027’s, nearly all of that upside would have to come from a higher multiple.
The numbers are on Thiel’s side
The risk is plain: Vista’s earnings rise and fall with oil, and Argentina’s peso and export rules add risks a US producer doesn’t face.
The way I see it, record production, falling debt and a 4.5x multiple back Thiel’s bet, and the November drop makes it a better deal for anyone buying today. The Street’s $96 target asks for more than Vista’s usual multiple. A move back to that 7.2x average, with estimates holding, would already be a big gain from here.
The test is Brent holding near Vista’s $80 assumption, and 2027 guidance at or above 185,000 barrels a day when Vista reports its fourth quarter early next year. Thiel Macro’s next 13F, due in mid-February, will show whether he held through the slide.
So what is Vista Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Vista Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!