Key Takeaways
- Greenlight Capital raised its PG&E stake 51% to 10 million shares in the third quarter, making it the fund’s biggest add, and also bought more Dauch and opened a new stake in Century Aluminum.
- PG&E trades at 7.9x forward earnings, against a five-year average of 12x, while analysts expect its earnings to grow about 10% a year through 2028.
- The analysts’ consensus target fell from $21 to $18 over the past year, and California’s wildfire liability rules are still the main risk.
- The numbers back Einhorn’s bet: the $18 consensus target is only about 9x analysts’ 2028 earnings estimate, well below PG&E’s usual multiple.
David Einhorn’s Greenlight Capital made PG&E (PCG) its biggest add of the third quarter, raising its stake 51% to 10 million shares, according to its 13F for the quarter ended Sept. 30, filed Nov. 16. It’s a bet on a utility trading near its lowest multiple in five years.
Einhorn went bargain hunting
At the end of September, those shares were worth $122 million. That’s 3.4% of Greenlight’s 13F stocks and its sixth-largest position out of 45. (DME Capital Management, Greenlight’s firm, manages $4.80 billion in all, and its 13F held $3.55 billion of US stocks.)
Greenlight bought into two other beaten-down stocks, too. It raised its stake in Dauch (DCH) 49% to 18.41 million shares, now 2.7% of its 13F stocks, and opened a new position of 2.27 million shares in Century Aluminum (CENX), another 2.3%. Both trade more than 50% below their 52-week highs, at about 5x and 3x forward earnings.
Measured from the quarter-end price, PG&E is up 12% since, while Dauch is down 16% and Century Aluminum is down 12%.
TIKR tracks 17 analysts on PG&E. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PG&E, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PG&E’s Analyst Ratings
Guidance held, and that’s what matters
PG&E’s third quarter, reported Oct. 22, looked soft at first glance. Non-GAAP core EPS fell to $0.41 from $0.50 a year earlier, and GAAP EPS slipped to $0.34 from $0.37.
But core EPS for the first nine months came to $1.24, up from $1.14. Management also reaffirmed its 2026 guidance of $1.64 to $1.66 and its 2027 range of $1.78 to $1.82. Hitting the 2026 range takes $0.40 to $0.42 in the fourth quarter, right around the $0.41 it just earned.
PG&E is also carrying out a $2 billion cut to its 2027 capital plan, and it’s running a strategic review aimed at making it an investment-grade company. CEO Patti Poppe said plainly what’s still missing. In the release, she said “we still believe California needs a durable wildfire liability framework that delivers for customers and investors.”
Analysts’ estimates sit at the midpoints of that guidance and keep climbing through 2028:
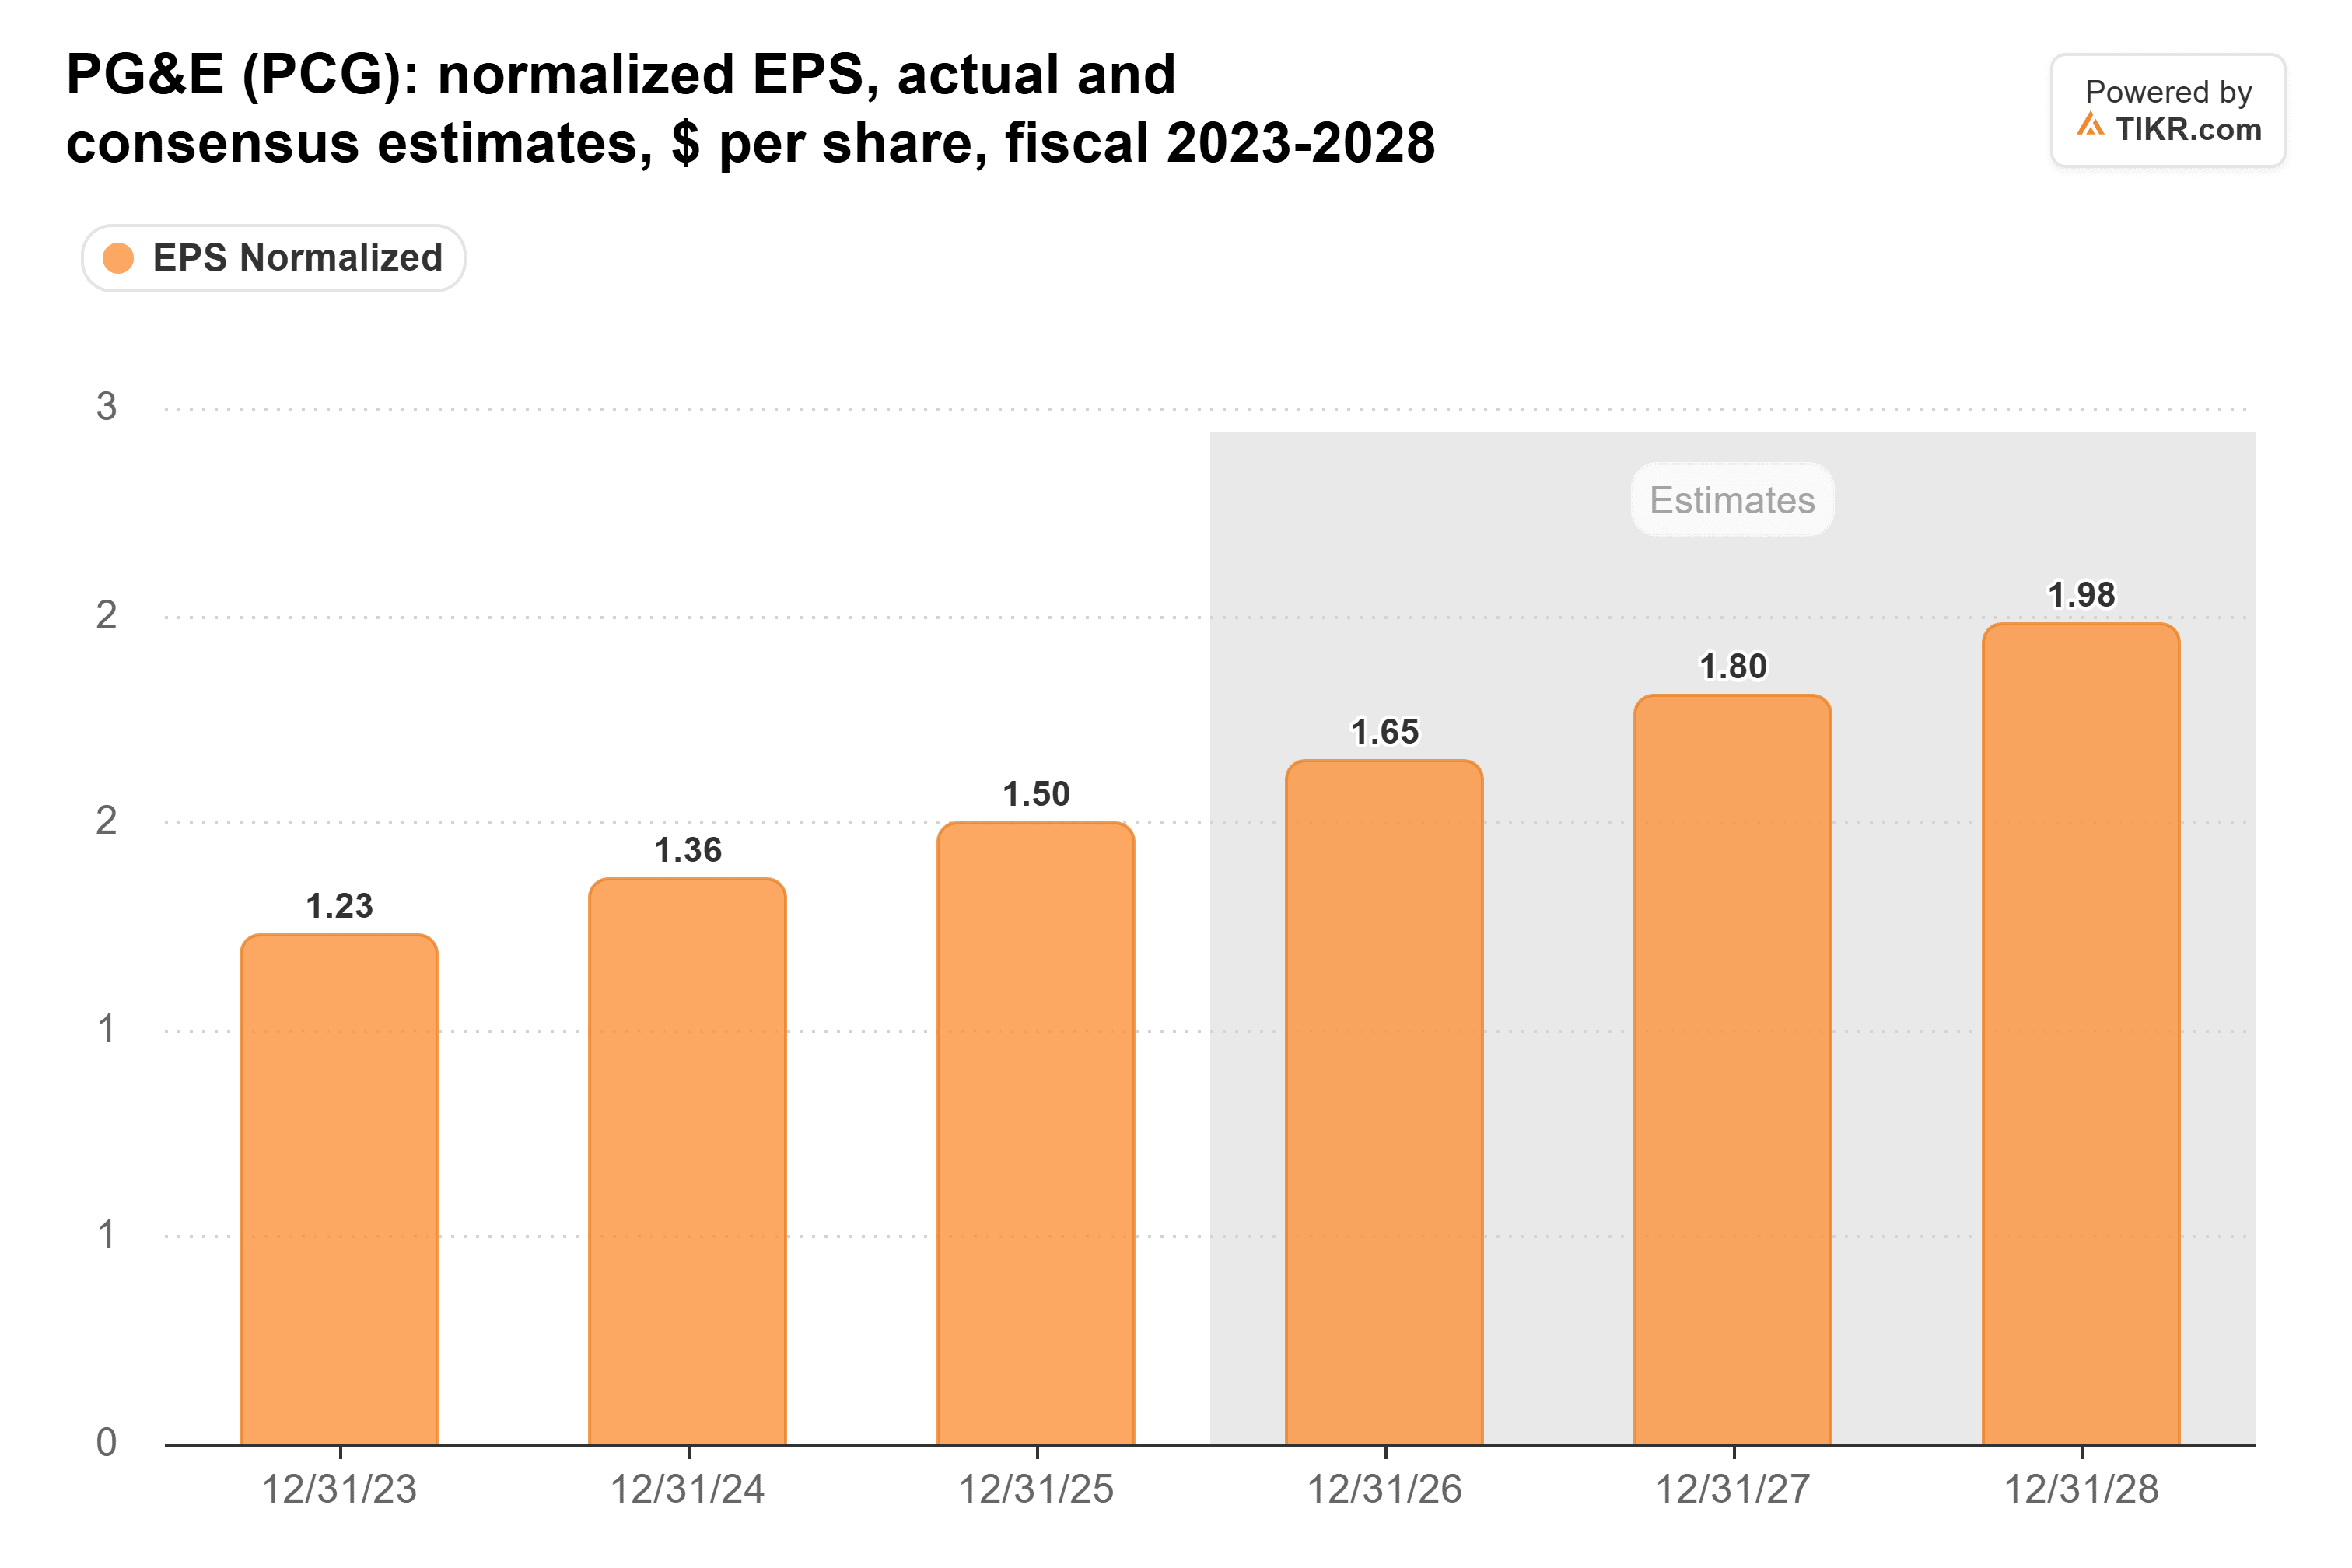
That’s growth of about 10% a year, from $1.50 in 2025 to $1.98 in 2028. The reaffirmed guidance gives no reason to expect those estimates to fall.
Does the price add up?
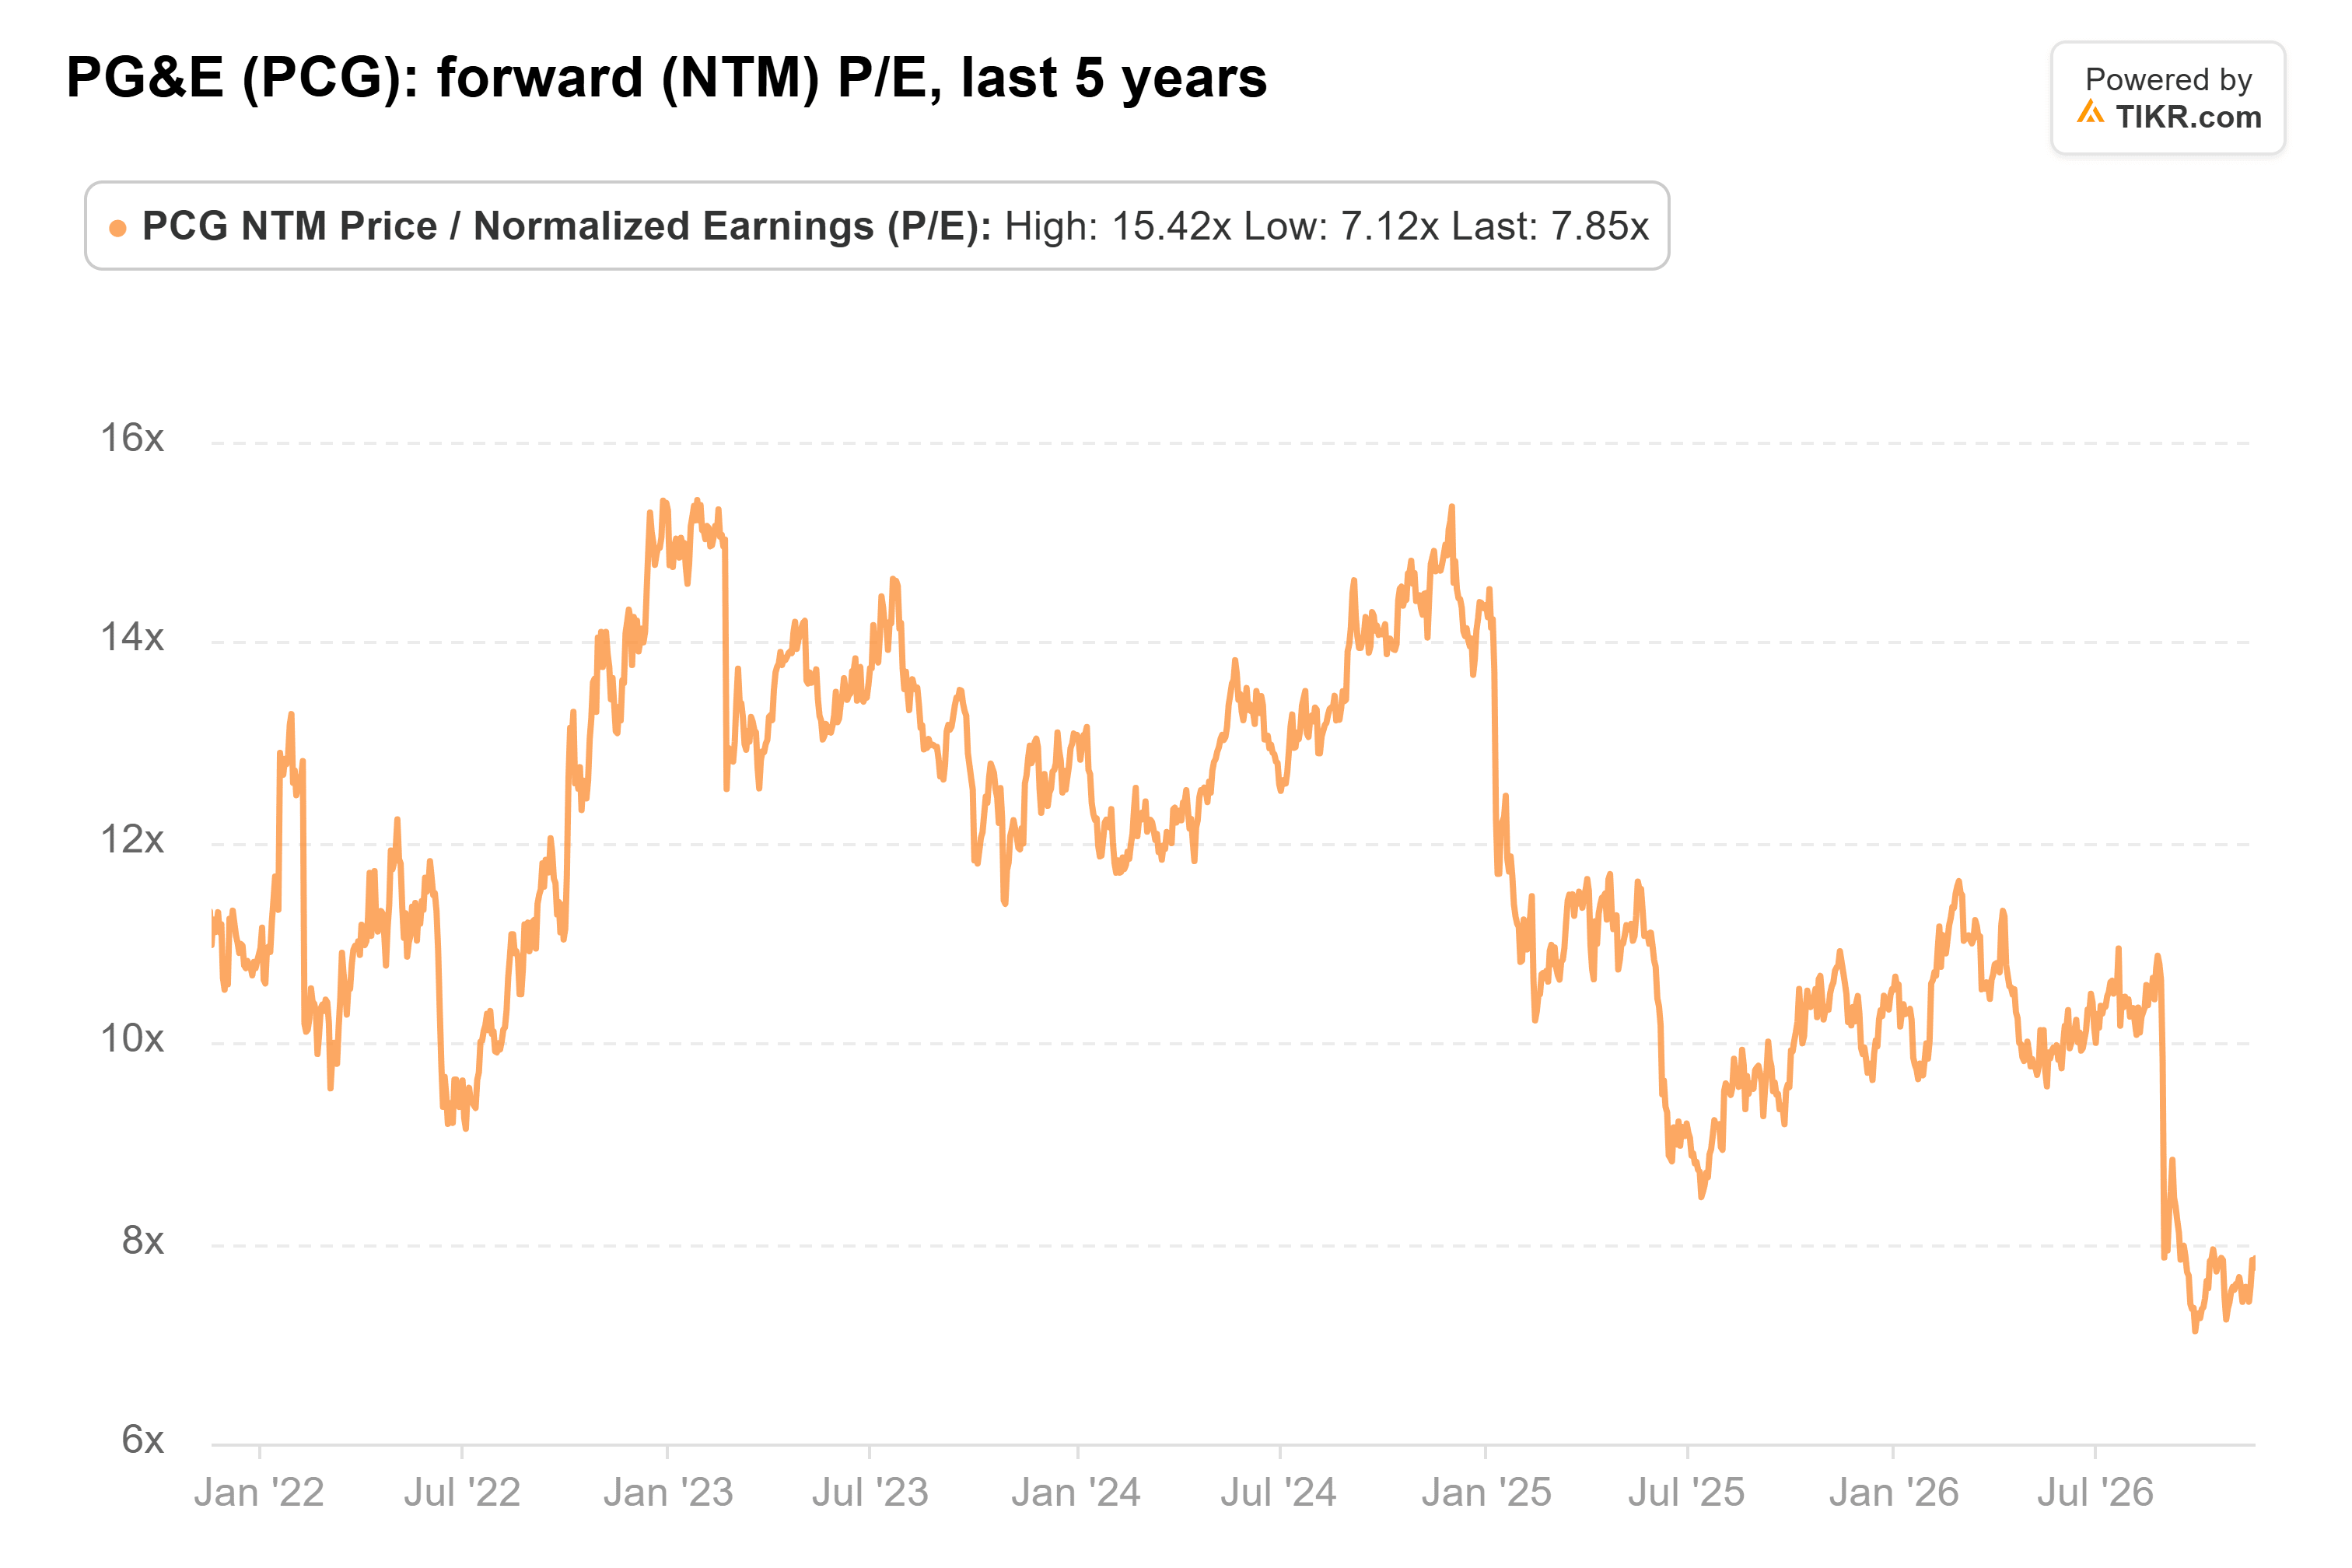
PG&E trades at 7.9x forward earnings. That’s far below its five-year average of 12x and close to the five-year low of 7.1x it hit on Sept. 28, the day the stock closed at its one-year low of $11.95. The chart shows how far the multiple has fallen from its 15x peak in January 2023:
Wall Street has been cutting too. The 17 analysts who cover PG&E have lowered their consensus target to $18 from $21 a year ago, and individual targets now run from $14 to $24. Most of that cut came after the consensus target peaked near $23 in July:
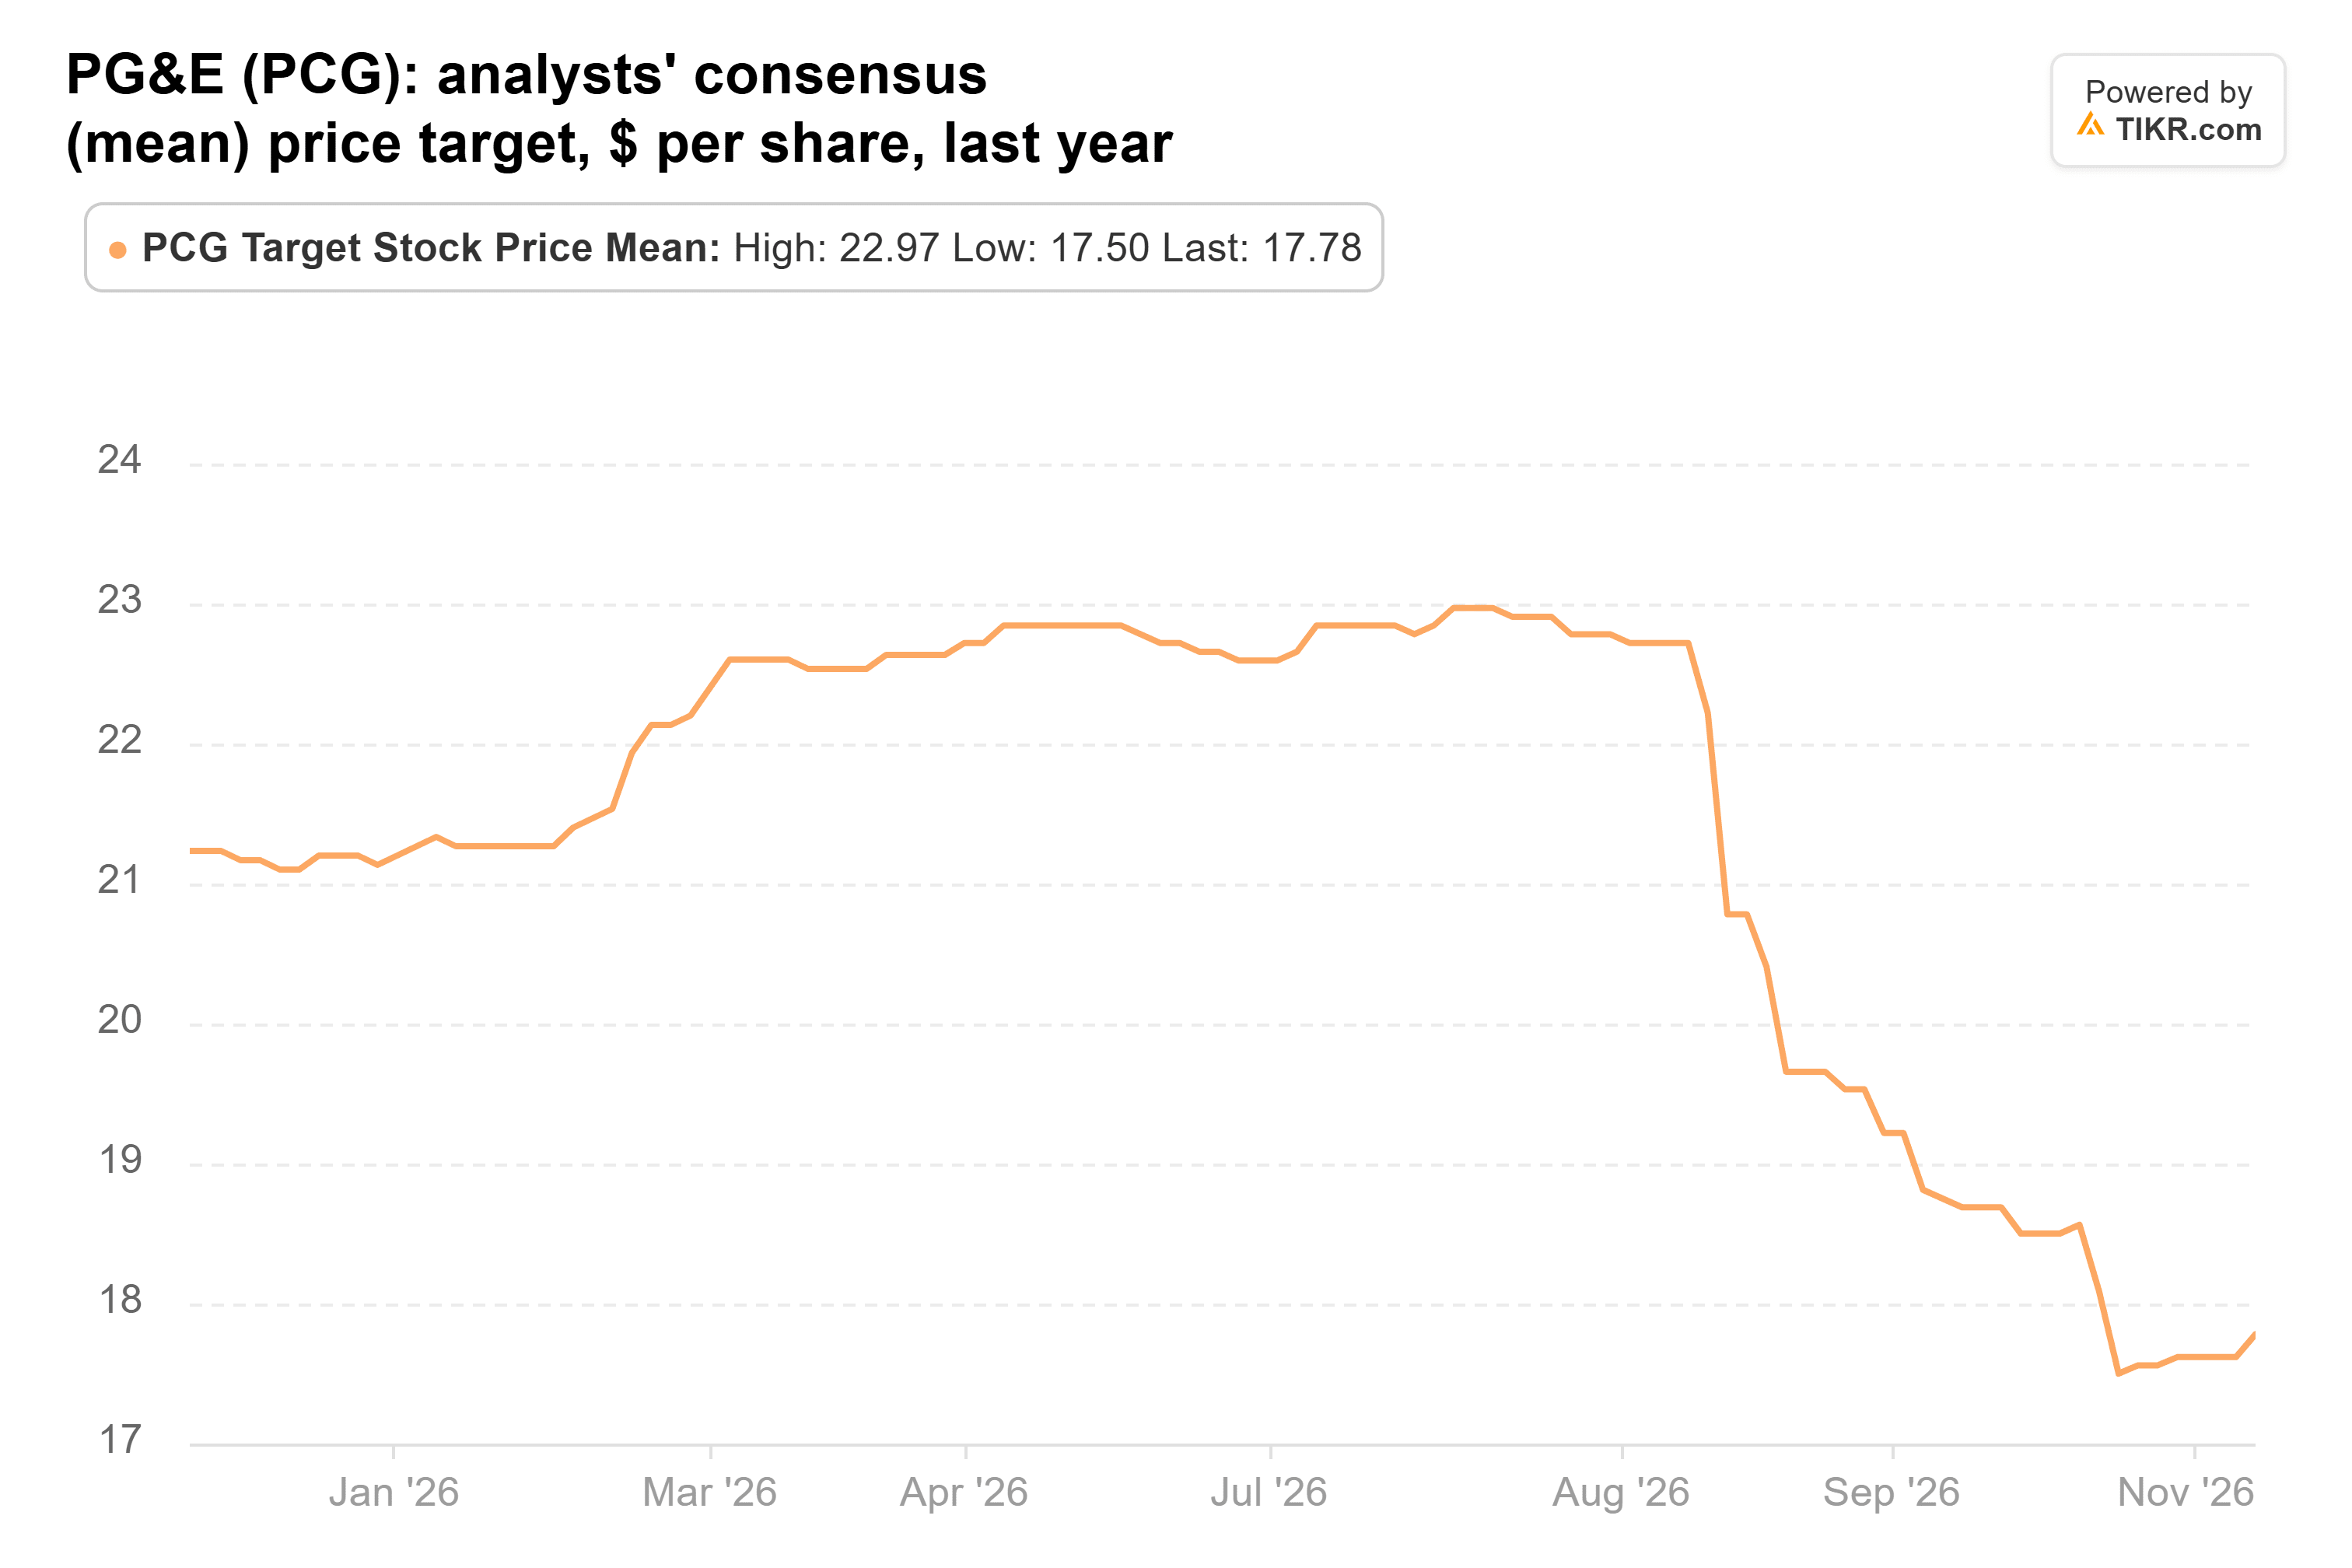
Even so, the $18 target sits 30% above the last close of $13.71, and it doesn’t ask much. On our math, it’s about 9x the $1.98 analysts expect PG&E to earn in 2028. Roughly half of that upside comes from earnings growth and half from the multiple rising to 9x, which is still well below its 12x average. Back at that average, 2028’s estimate would put the stock near $23, close to the Street’s highest target.
Einhorn has this one right
I suspect the discount comes down to wildfire liability. PG&E’s own CEO says California’s rules still aren’t where they need to be, and a bad fire season would only add to that worry. But at 7.9x earnings that management keeps guiding higher, the numbers back Greenlight’s bet. PG&E only needs its estimates to hold, plus a modest re-rating, to reach the Street’s $18 target.
The next test is PG&E’s fourth-quarter report early next year. Core EPS of at least $0.40 for the quarter would land the year inside guidance. News from the strategic review matters too, and Greenlight’s next 13F, due by mid-February, will show whether it kept buying.
So what is PG&E stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PG&E could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!