Key Takeaways
- Jim Cramer said on Mad Money on Oct. 27 that Penguin Solutions “sells at a low multiple.” The stock trades at 11.6x forward earnings, against a three-year average of 13.7x.
- That multiple assumes normalized EPS rises 59% to $4.56 in fiscal 2027, a little above the $4.45 midpoint of management’s own guidance.
- Management expects gross margin to stay flat to slightly lower, so the earnings growth has to come from sales rising about 40%.
- The low multiple looks real on the company’s own outlook. The first-quarter report in early January is the first real test of it.
During the lightning round on Mad Money on Oct. 27, a caller asked whether to buy or sell Penguin Solutions (PENG). CNBC’s Jim Cramer kept his answer short:
“Penguin Solutions sells at a low multiple, and I don’t mind a low multiple tech stocks because they are not going to get hurt as much as the others.”
He’s right about the low multiple. (The second half hasn’t held up as well: even after a 172% gain in 2026, the stock sits 41% below its 52-week high.)
A low multiple is only a bargain if the earnings behind it actually arrive.
Cheap If the Street Is Right
Wall Street expects normalized EPS to jump 59%, from $2.87 in fiscal 2026 to $4.56 in the year ending August 2027, and then to climb another 15% to $5.26:

Those estimates sit just above what management has guided. On Oct. 6, Penguin Solutions raised its fiscal 2027 outlook. It now guides to non-GAAP EPS of $4.45, give or take $0.70, on net sales of about $2.43 billion at the midpoint, which would be growth of about 40%.
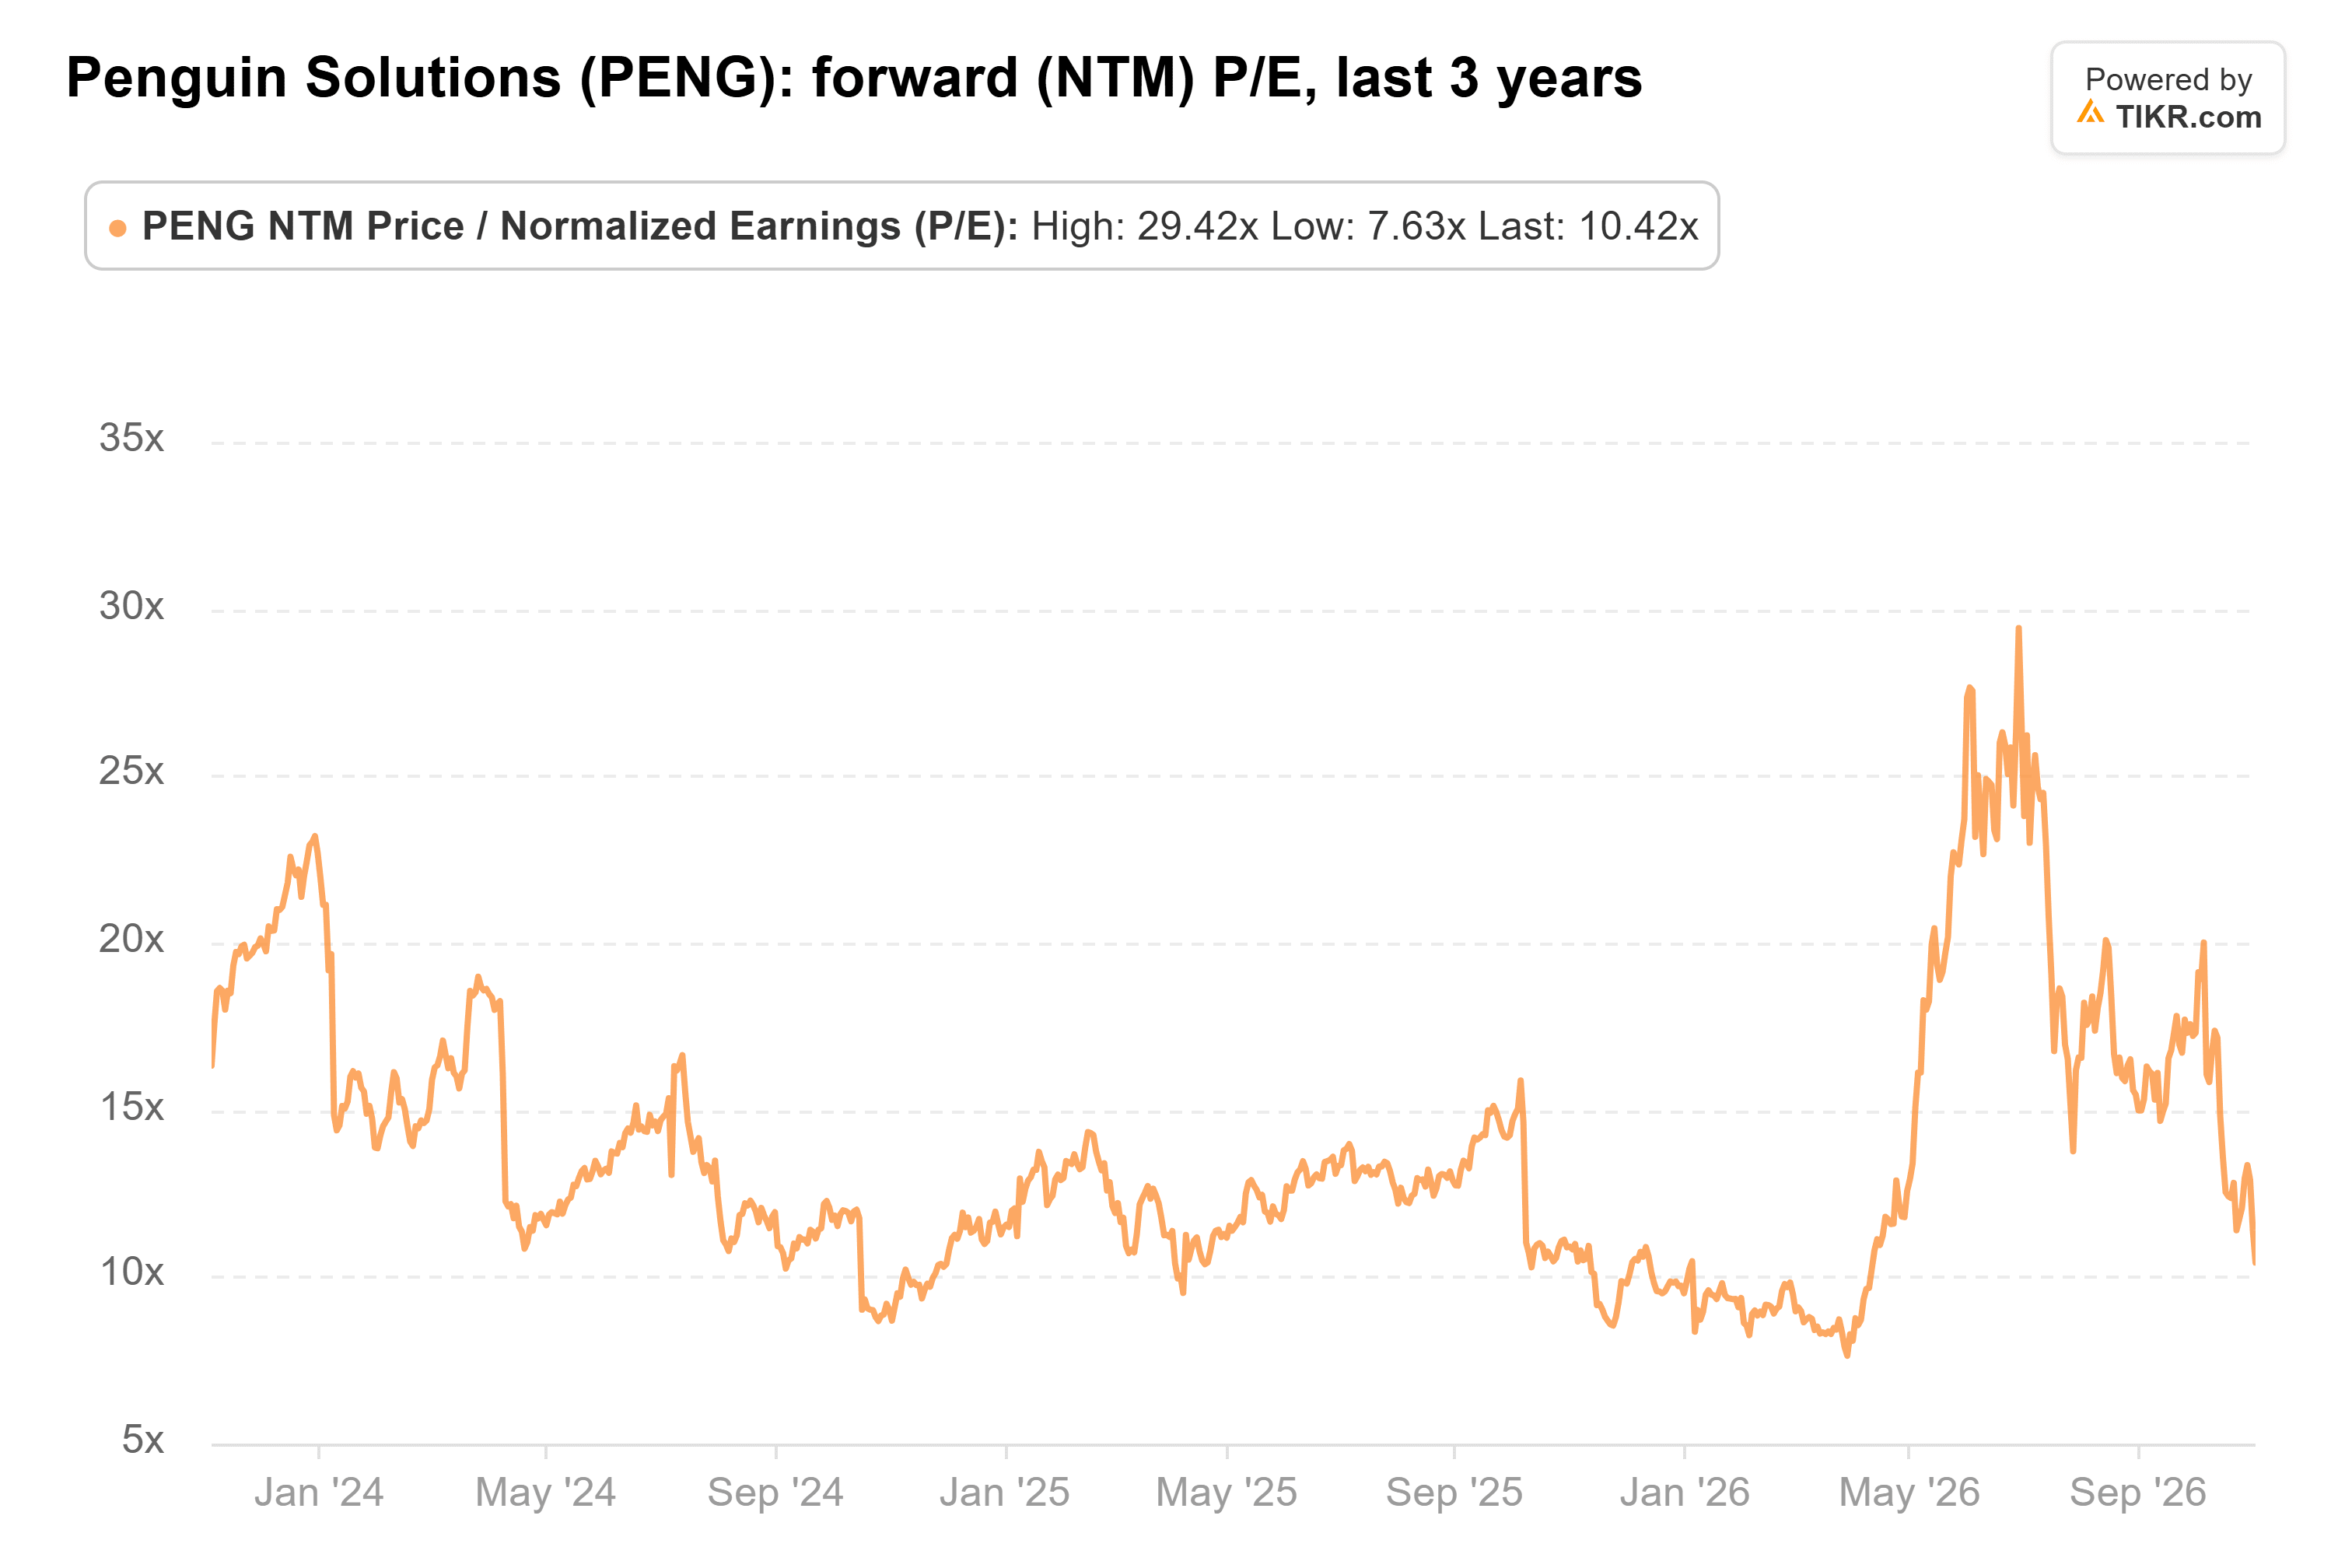
On those estimates, the stock traded at 10.4x forward earnings at the Nov. 2 close, well under its three-year average of 13.7x. The 12% jump on Nov. 3 lifted that to about 11.6x, still below average:
Measured against its fiscal 2026 non-GAAP EPS of $2.87, though, the Nov. 3 close of $53 works out to 18.5x. So the bargain only exists on next year’s numbers.
Margins Won’t Help Much
Penguin Solutions’ gross margin has slipped from 29.5% in fiscal 2023 to 27.6% in fiscal 2026:

Management doesn’t expect a rebound. Its fiscal 2027 outlook calls for a GAAP gross margin of 27%, give or take 2 points. That means the guided 55% jump in EPS has to come from higher sales and from holding operating costs down.
Demand looks strong. Fourth-quarter sales rose 68% to $567 million, and memory supplied about $209 million of the $229 million increase. The company also won six new AI infrastructure customers in the quarter, four of them neoclouds, and said in its release that it raised its outlook “based on this continued momentum, particularly the strength in AI Infrastructure.”
Memory is a cyclical business, though, so the segment supplying most of the growth is also the one most likely to swing.
TIKR Tracks 8 Analysts on Penguin Solutions. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Penguin Solutions, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Penguin Solutions’ Analyst Ratings
The Multiple Has Swung Before
The forward P/E fell to a three-year low of 7.6x on March 30, two days before the company raised its full-year outlook. It then hit a high of 29.4x on June 30. With estimates moving this fast, the multiple moves with them, and a single quarter can’t confirm a full year of 40% growth.
Analysts who updated after the October report still see a lot of upside. Rosenblatt raised its target to $100 from $80 on Oct. 7, and Bank of America initiated coverage at Buy with a $100 target on Oct. 9.
What Penguin’s January Report Has to Show
Penguin Solutions hasn’t announced a date yet, but its first-quarter report should come in early January, as last year’s did. For the stock’s 11.6x to look like a real bargain, that report needs sales on pace for something close to 40% growth, a gross margin near 27%, and no cut to the $4.45 EPS outlook.
Cramer has a point. Management’s own guidance covers most of the Street’s number, so the low multiple looks real, not like a trap. If January brings a raise, $4.56 starts to look conservative.
Still, a business selling large AI systems can have a lumpy quarter, so the full-year outlook in that report matters as much as the quarter’s own results.
So what is Penguin Solutions stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Penguin Solutions could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Penguin Solutions for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!