Key Takeaways
- Palantir’s third-quarter revenue rose 96% to $2.313 billion, beating the $2.18 billion consensus, but total contract value grew just 6%.
- U.S. commercial revenue jumped 148% to $984 million, passing U.S. government revenue for the first time in company history.
- The GAAP operating margin hit 47%, and full-year revenue guidance rose to about 91% growth, yet the shares still fell after the report.
- The fourth-quarter report will show whether contract value can get back toward last year’s record of $4.26 billion.
Palantir Technologies (PLTR) just posted the kind of quarter most software companies only show in a bull case. Revenue rose 96% to $2.313 billion, beating the $2.18 billion consensus, and adjusted EPS of $0.44 beat the $0.41 estimate.
For contrast, Datadog (DDOG) grew revenue 35% to $1.20 billion in the same quarter.
Still, Palantir shares fell more than 7% in premarket trading the morning after the report. The problem was bookings: total contract value grew only 6% to $2.918 billion.
CEO Alex Karp sounded unbothered. In the earnings release, he said Sovereign AI is creating “the most dramatic dichotomy between haves and have nots” he has seen in 30 years of business.
So the question for investors is simple. Can bookings catch up before revenue growth starts to fade?
Commercial finally takes the lead
The headline numbers were hard to argue with:
- U.S. commercial revenue rose 148% to $984 million, topping U.S. government revenue of $953 million for the first time.
- Total commercial revenue crossed $1 billion, up 113% to $1.168 billion.
- U.S. revenue grew 119% to $1.937 billion.
New business was the softer spot. U.S. commercial contract value rose just 11% to $1.463 billion. Management tied the slowdown to Sovereign AI customers signing shorter deals, and it expects those contracts to grow in size and length.
Here’s how the two halves of the business have tracked over the past two years…
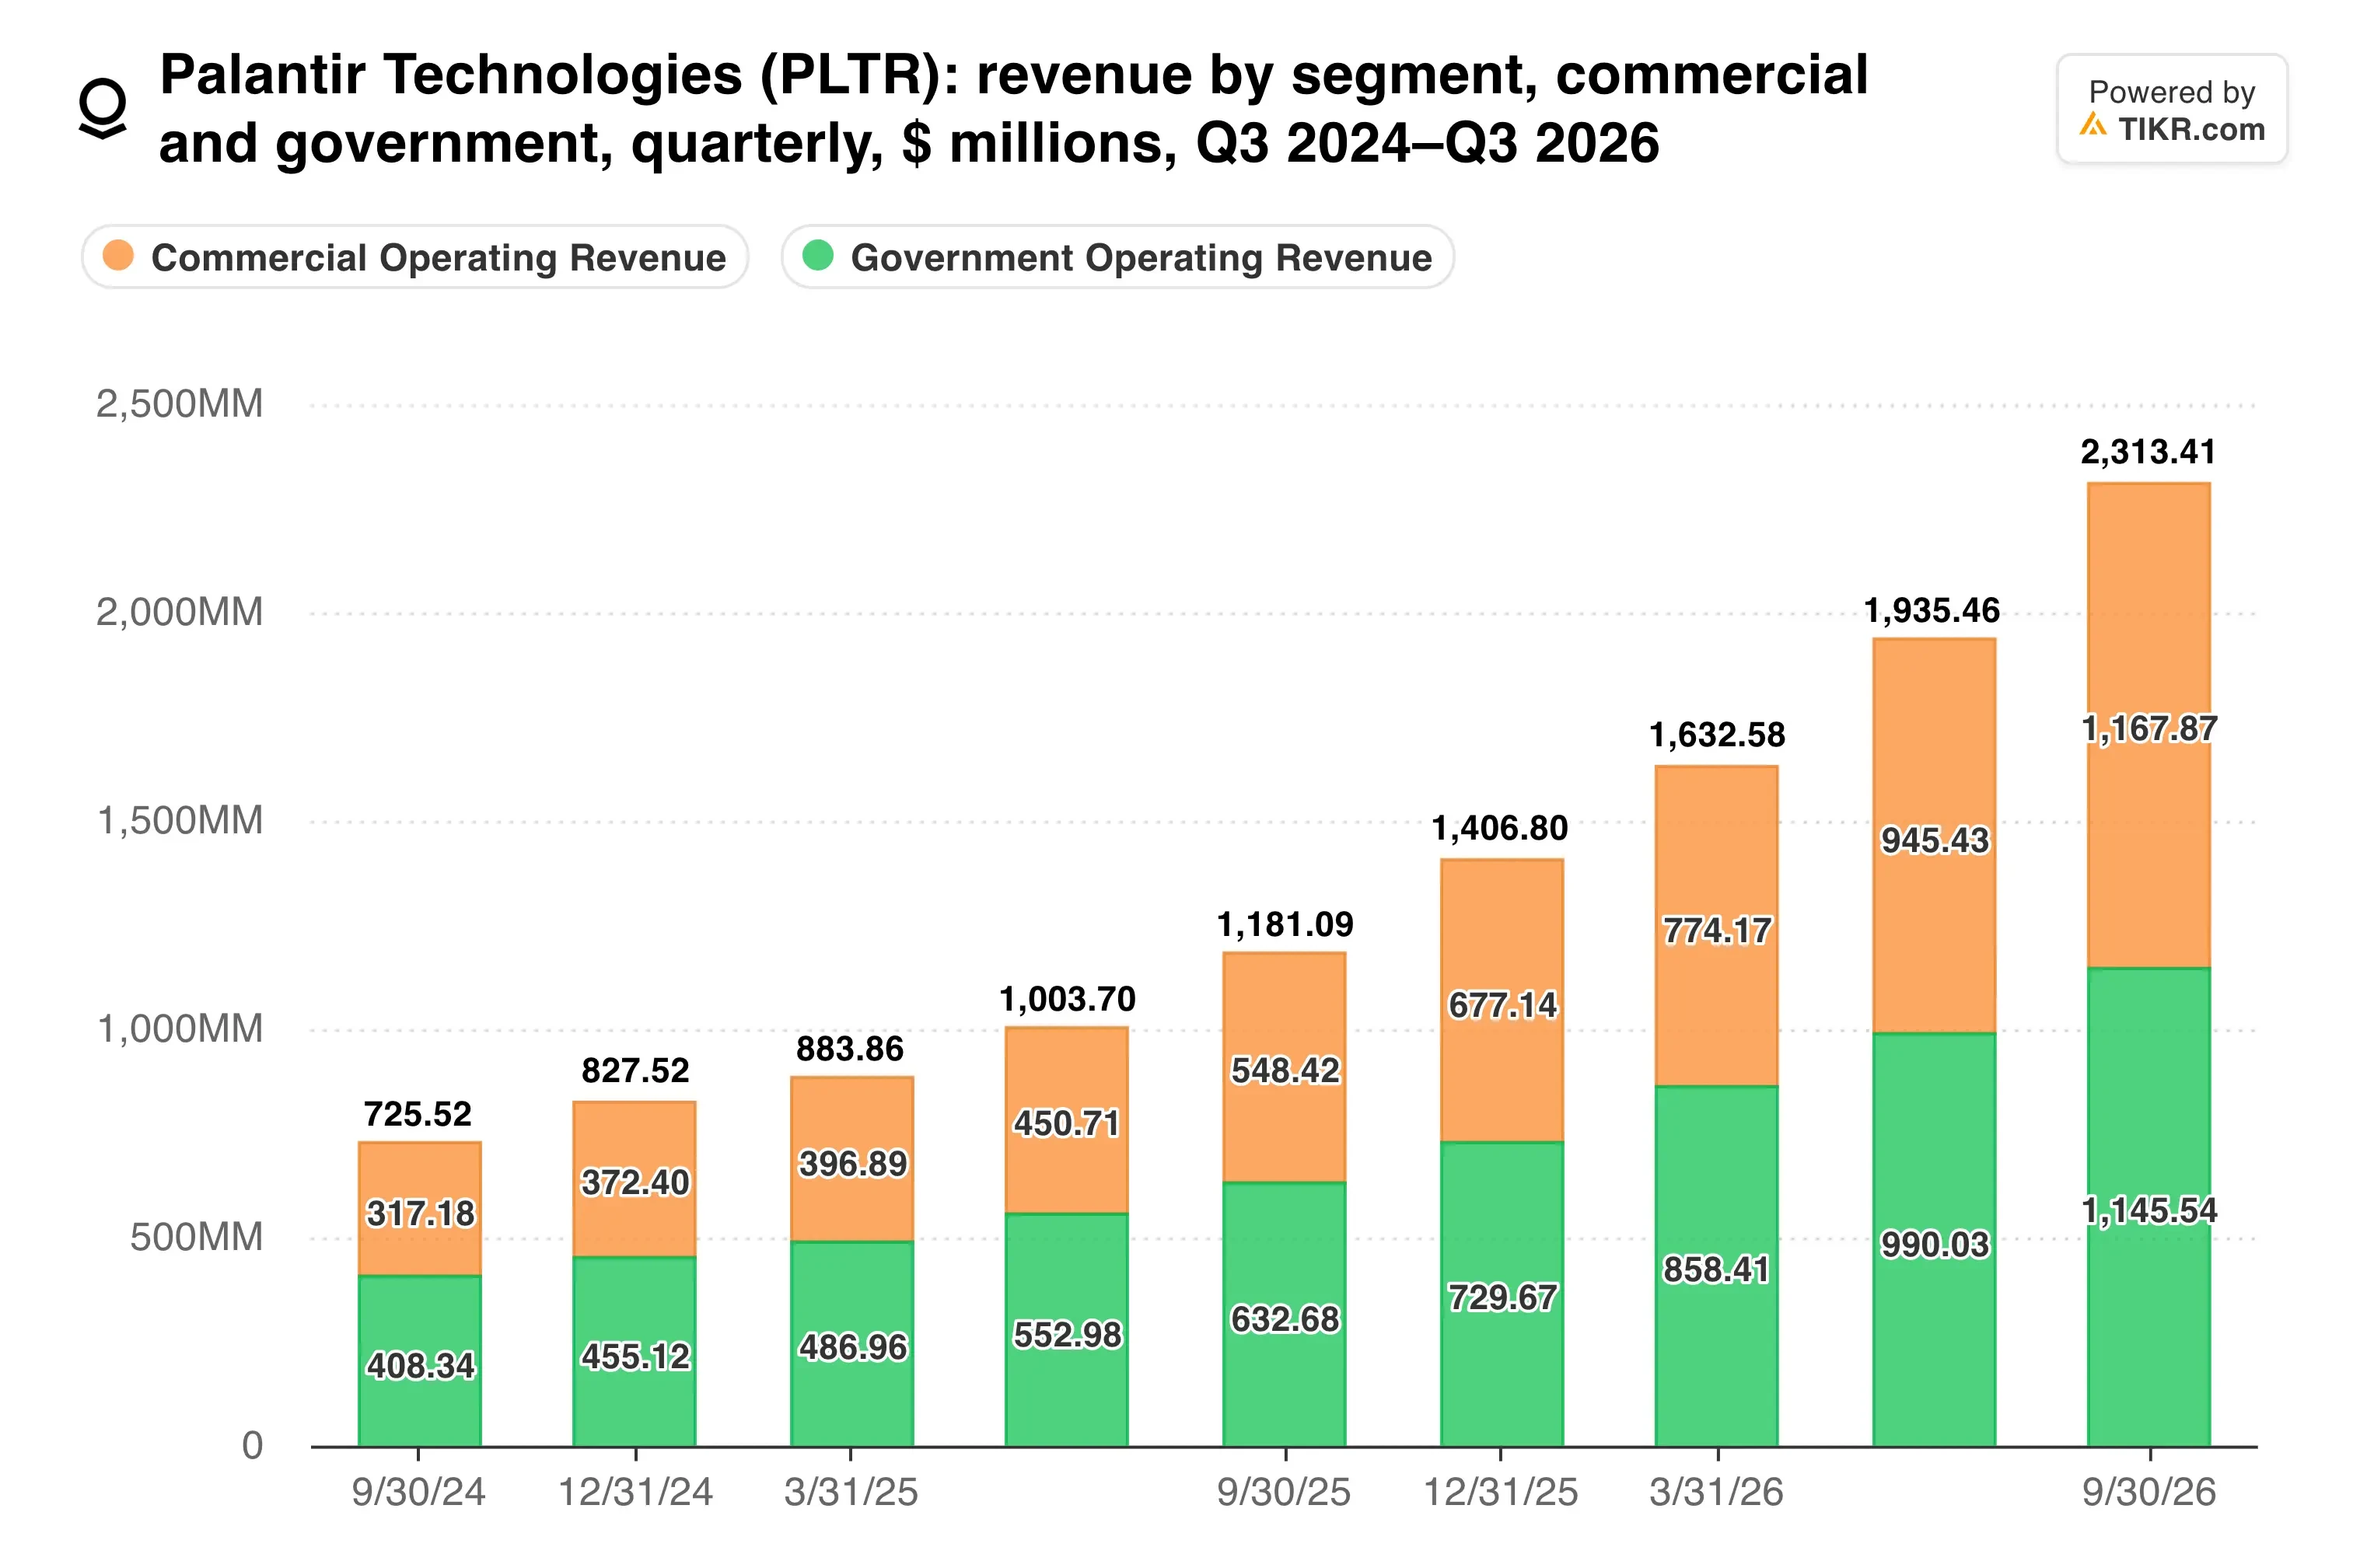
Commercial now carries the growth, and that is exactly where bookings cooled.
Profits are scaling faster than sales
Palantir’s costs simply aren’t keeping pace with its sales. GAAP operating margin hit 47% in the third quarter, up from 33% a year earlier, while adjusted operating margin reached 62%.
And cash followed the profits. Adjusted free cash flow came to $1.216 billion, a 53% margin, and cash plus Treasuries reached $10.4 billion.
So how fast has that margin climbed?
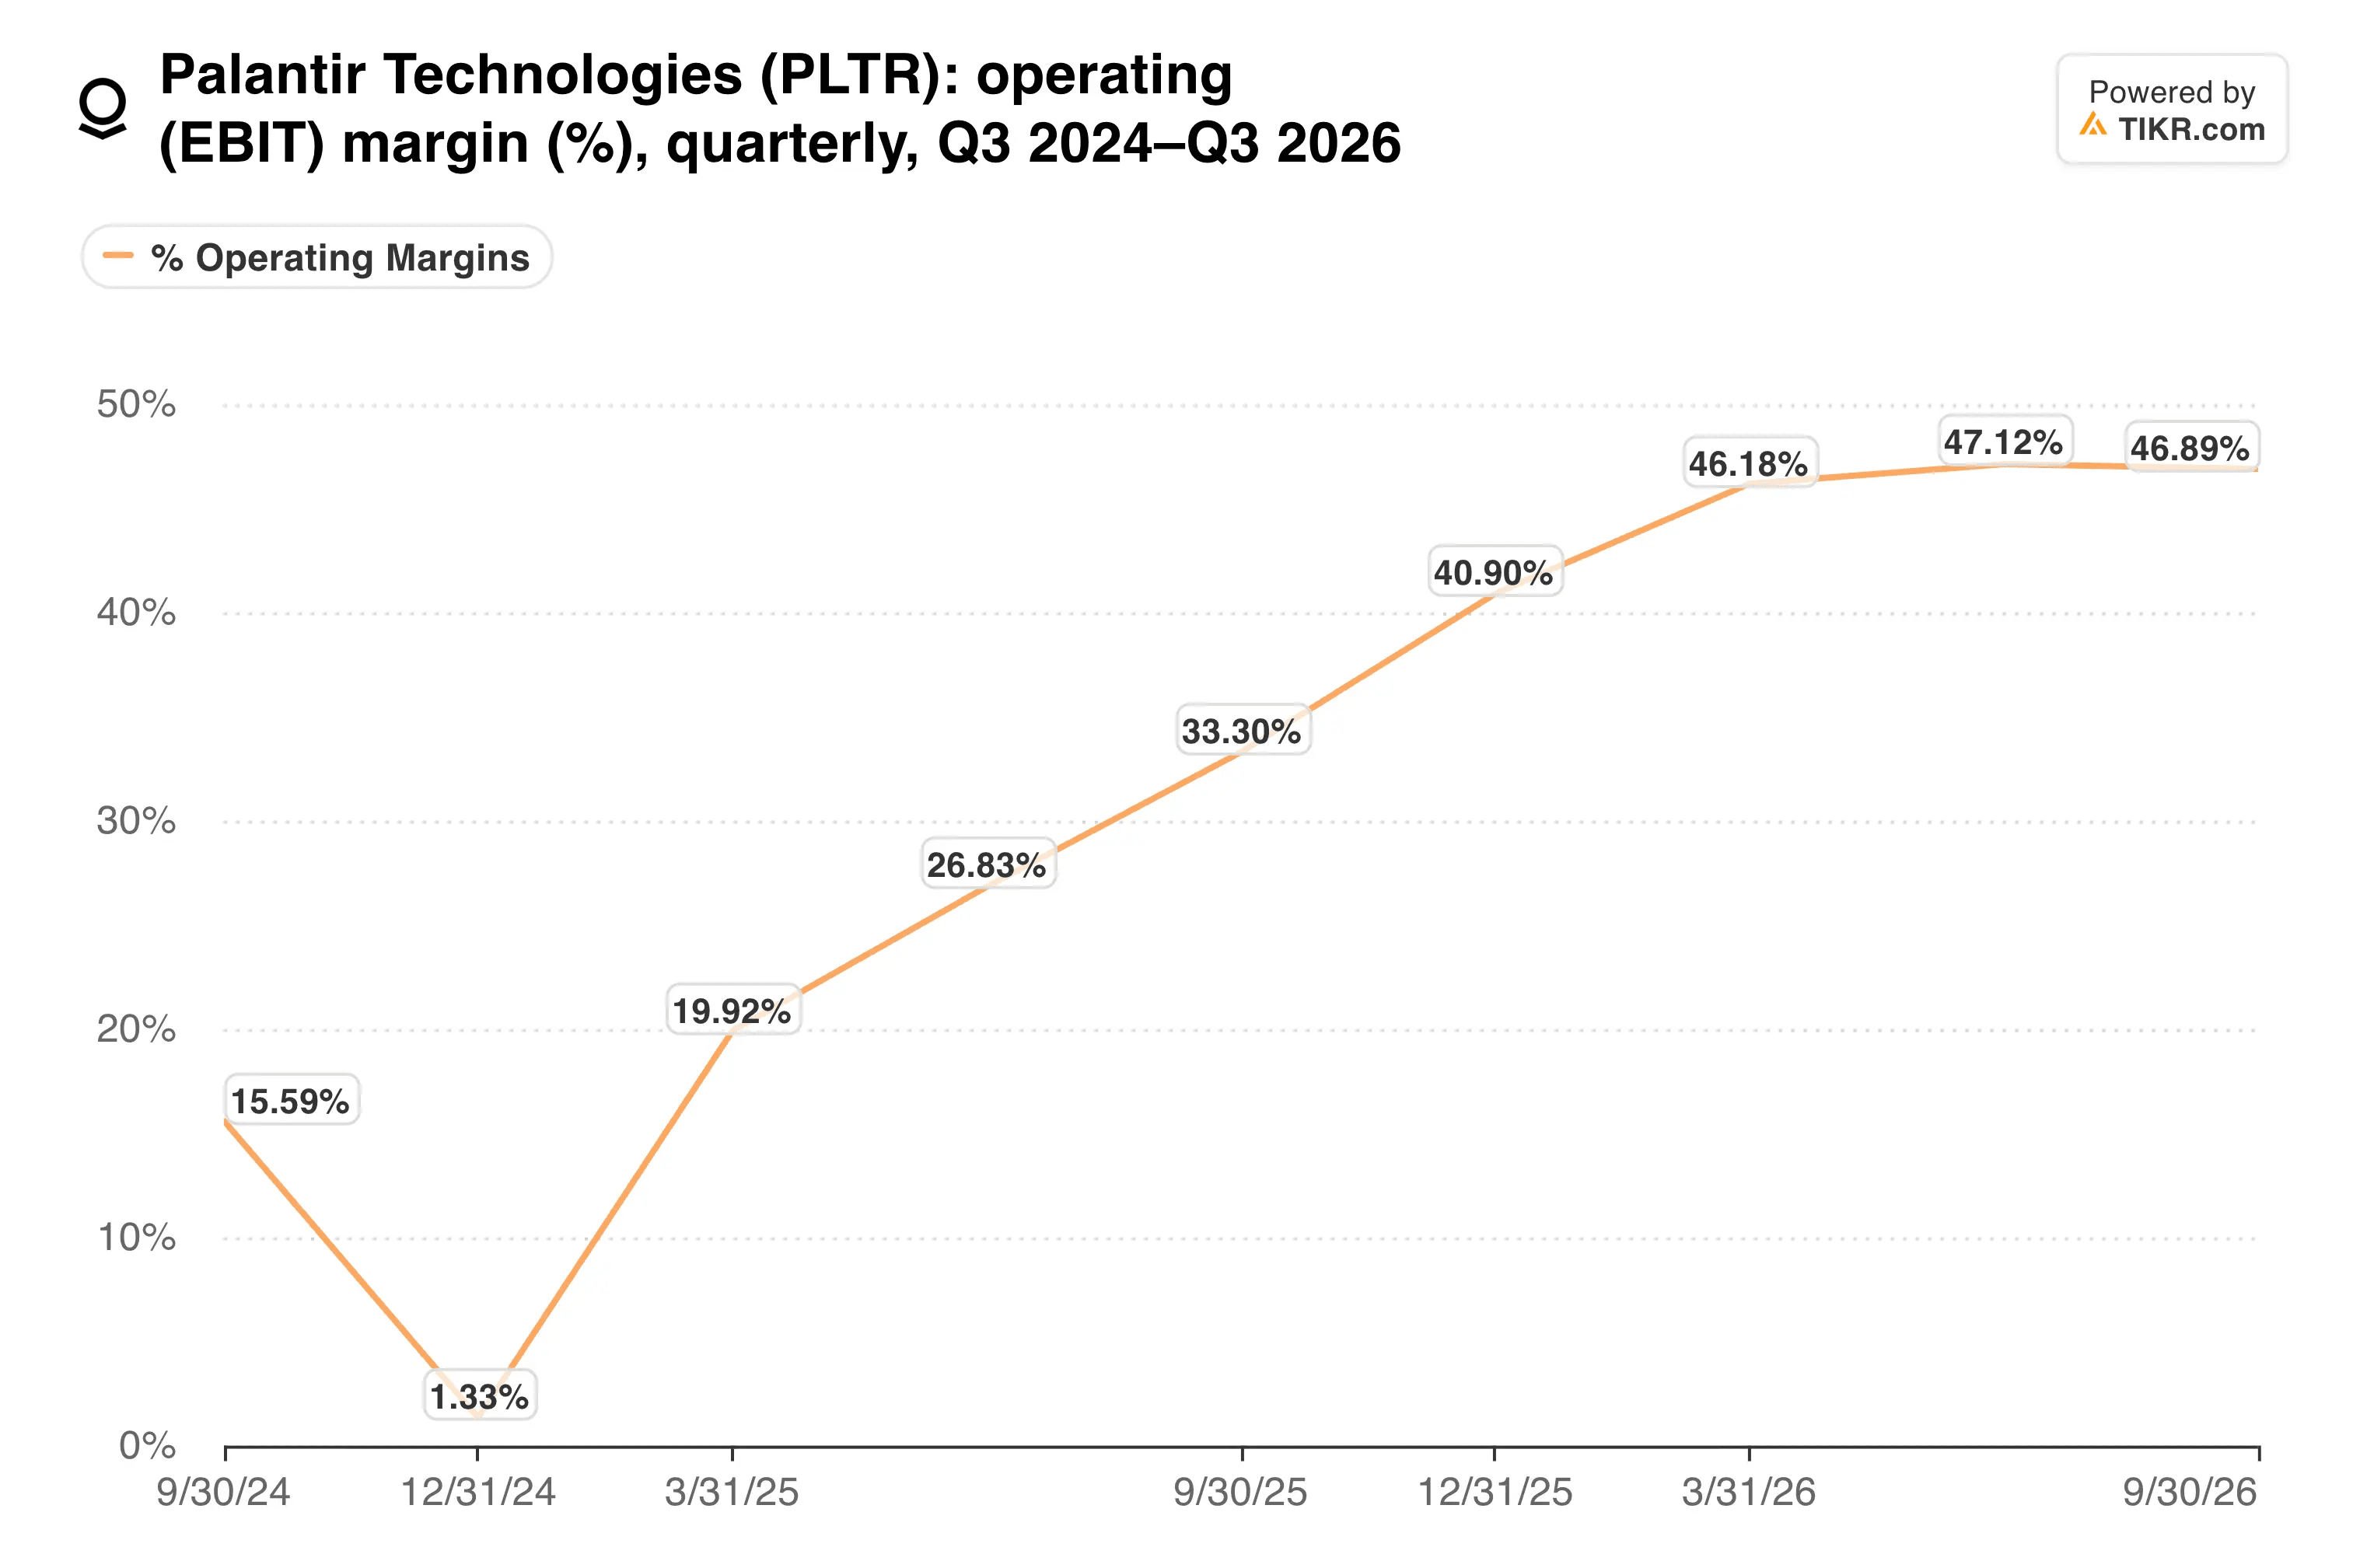
In the fourth quarter of 2024, GAAP operating income was just $11 million. Now quarterly GAAP net income of $1.128 billion nearly matches Datadog’s entire quarterly revenue.
Guidance moved up again too. Palantir now expects full-year revenue of $8.530 billion to $8.534 billion, about 91% growth. It also raised its adjusted free cash flow target to $4.8 billion to $5.0 billion.
The fourth-quarter guide of $2.649 billion to $2.653 billion implies roughly 88% growth over last year’s $1.407 billion. That pace needs fresh contracts behind it.
TIKR tracks 32 analysts on Palantir. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palantir, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palantir’s Analyst Ratings
Bookings now carry the multiple
Here’s where the bookings worry gets concrete. In the fourth quarter of 2025, Palantir closed a record $4.262 billion of contract value, up 138%. Matching that would take a sharp rebound from the third quarter’s pace.
U.S. commercial remaining deal value rose 79% to $6.517 billion. However, it grew only 4% from the prior quarter.
Meanwhile, the valuation leaves little room for a stumble…
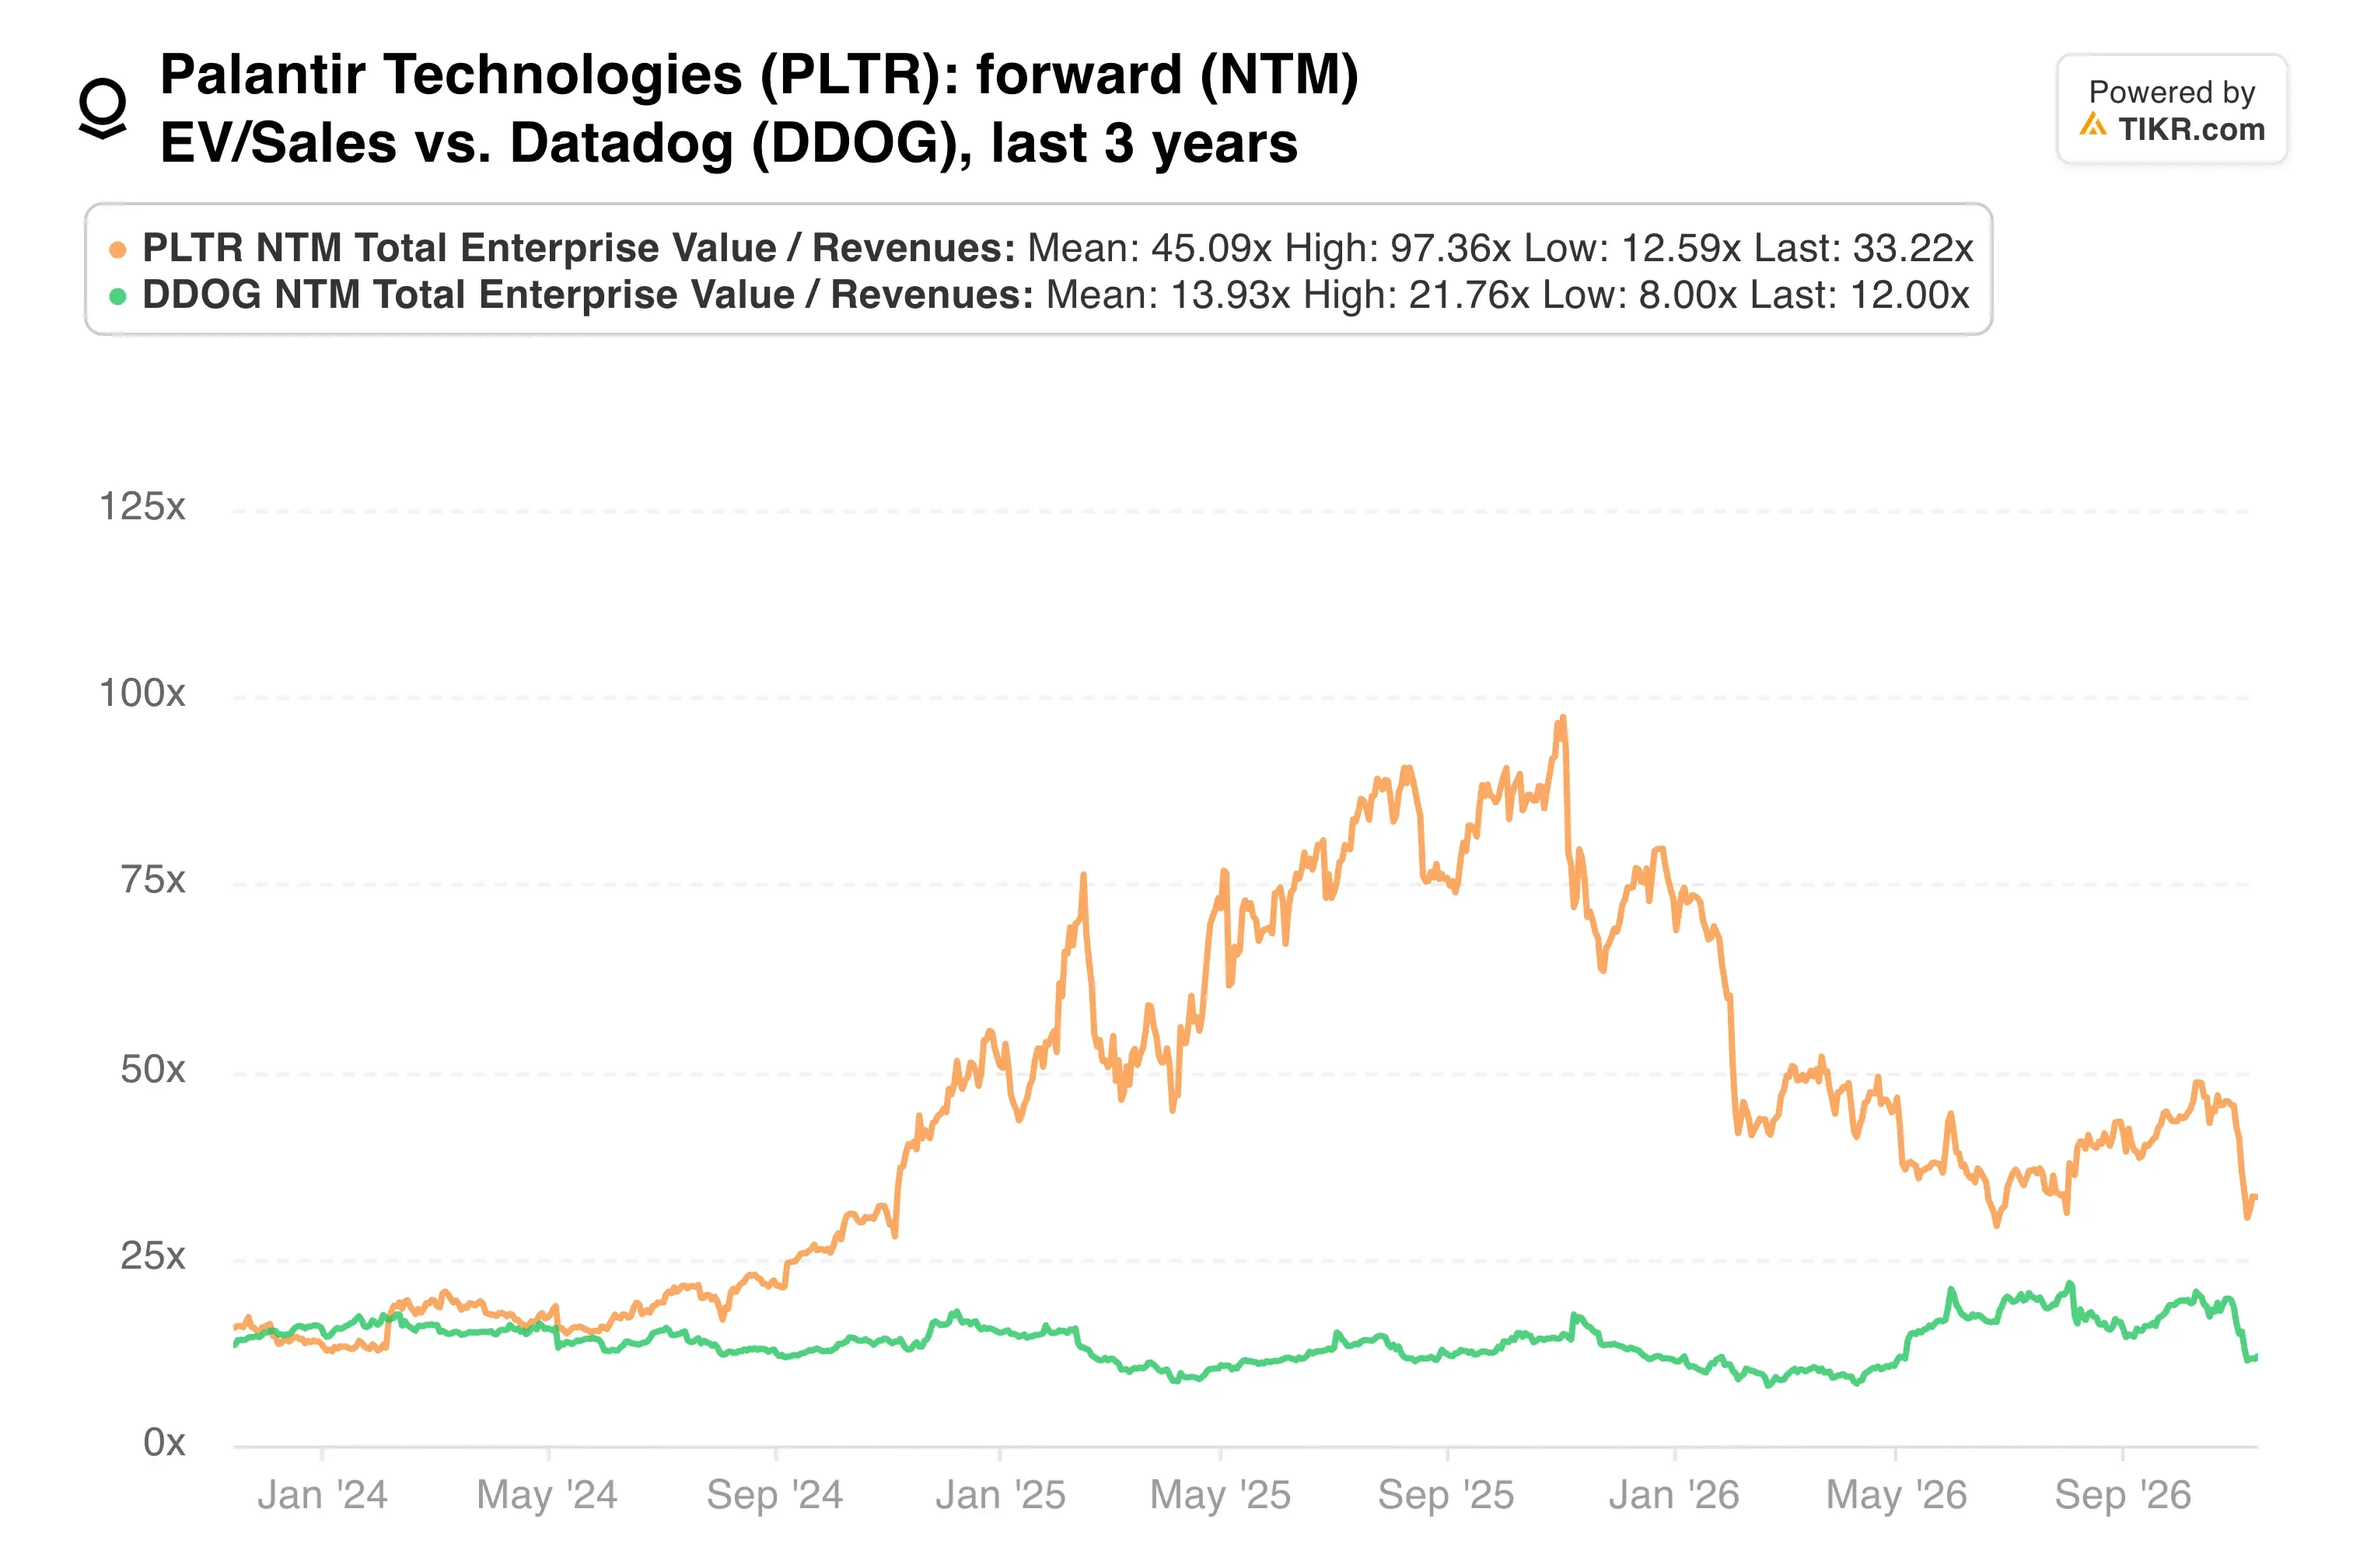
Even after the pullback, Palantir’s forward sales multiple sits far above Datadog’s, so the market is still paying for flawless execution.
Yet Wall Street remains split. Morgan Stanley raised its target to $233 from $205 but kept an equal-weight rating. William Blair’s Louie DiPalma was more upbeat, writing that Palantir’s growth looks “more resilient than others.”
My take: one soft bookings quarter doesn’t break this story, because revenue, margins and cash flow are all improving together. Still, a stock priced this richly can’t afford a second miss on contract value. I’d wait for bookings to recover before adding.
The fourth-quarter report, expected in early February, is the real test. If contract value gets anywhere near last year’s $4.26 billion record, this selloff will look like noise.
So what is Palantir stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palantir could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!