Key Takeaways
- Ouster stock has dropped 34% in the past month after a hot September inflation report started a sell-off in AI and chip stocks.
- Ouster’s own news this month was good: a defense milestone with Forterra and a new robotics product. The drop says more about the market than about the business.
- Analysts expect revenue to grow about 31% this year to $222 million, though Ouster still burns cash: $64.9 million of negative free cash flow in 2025.
- Third-quarter results come Nov. 3 after the close, and the stock looks like a buy for investors who can handle big swings.
Ouster (OUST) stock has dropped 34% in the past month, far more than the Nasdaq 100’s 9% fall over the same stretch.
Almost all of that came from a hot inflation report and a rout in AI and chip stocks. Meanwhile, the company kept putting out good news.
Blame the inflation report
The selling picked up on Oct. 14. September’s consumer price index came in at 3.7% a year, above the 3.6% economists expected and up from 3.4% in August. That raised the odds of a Federal Reserve rate hike, and AI hardware stocks took the worst of it: Nvidia, AMD and CoreWeave all fell sharply that day.
Higher rates make the AI buildout more expensive to fund, and chip stocks kept falling on Oct. 15. They slid again on Oct. 30, when Intel plunged and Amazon missed expectations.
Ouster kept winning work
On Oct. 1, just before the slide began, Ouster partnered with Seneca to put its Rev8 color lidar on Seneca’s autonomous drones for wildfire response.
On Oct. 21, Ouster said Forterra’s Lancer autonomous ground vehicles had completed 1,426 missions and 88 casualty evacuations in Ukraine using its sensors. A battlefield record like that should help Ouster win more defense work.
And on Oct. 27, Stereolabs, an Ouster company, launched its ZED Box 2 Series of edge AI computers for production robots.
See analyst ratings on Ouster (it’s free):
See the full breakdown of Buy, Hold, and Sell ratings on Ouster, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Ouster’s Analyst Ratings
Why Ouster fell harder
The business is growing fast. Second-quarter revenue rose 56% to $55 million, and analysts expect plenty more growth ahead:

Consensus calls for $222 million of revenue this year and $299 million in 2027, growth of about 31% and 35%. Nothing Ouster announced this month gives analysts a reason to cut those numbers.
But Ouster still loses money and burns cash, so most of its value rests on profits years away. When rates look set to rise, those future profits are worth less today, and investors sell stocks like Ouster first.
Half off the high, and still not cheap
Even after the drop, the stock is up 35% in 2026, but it’s 53% below its June 30 high. Its forward price/sales multiple shows how much of the excitement is left:
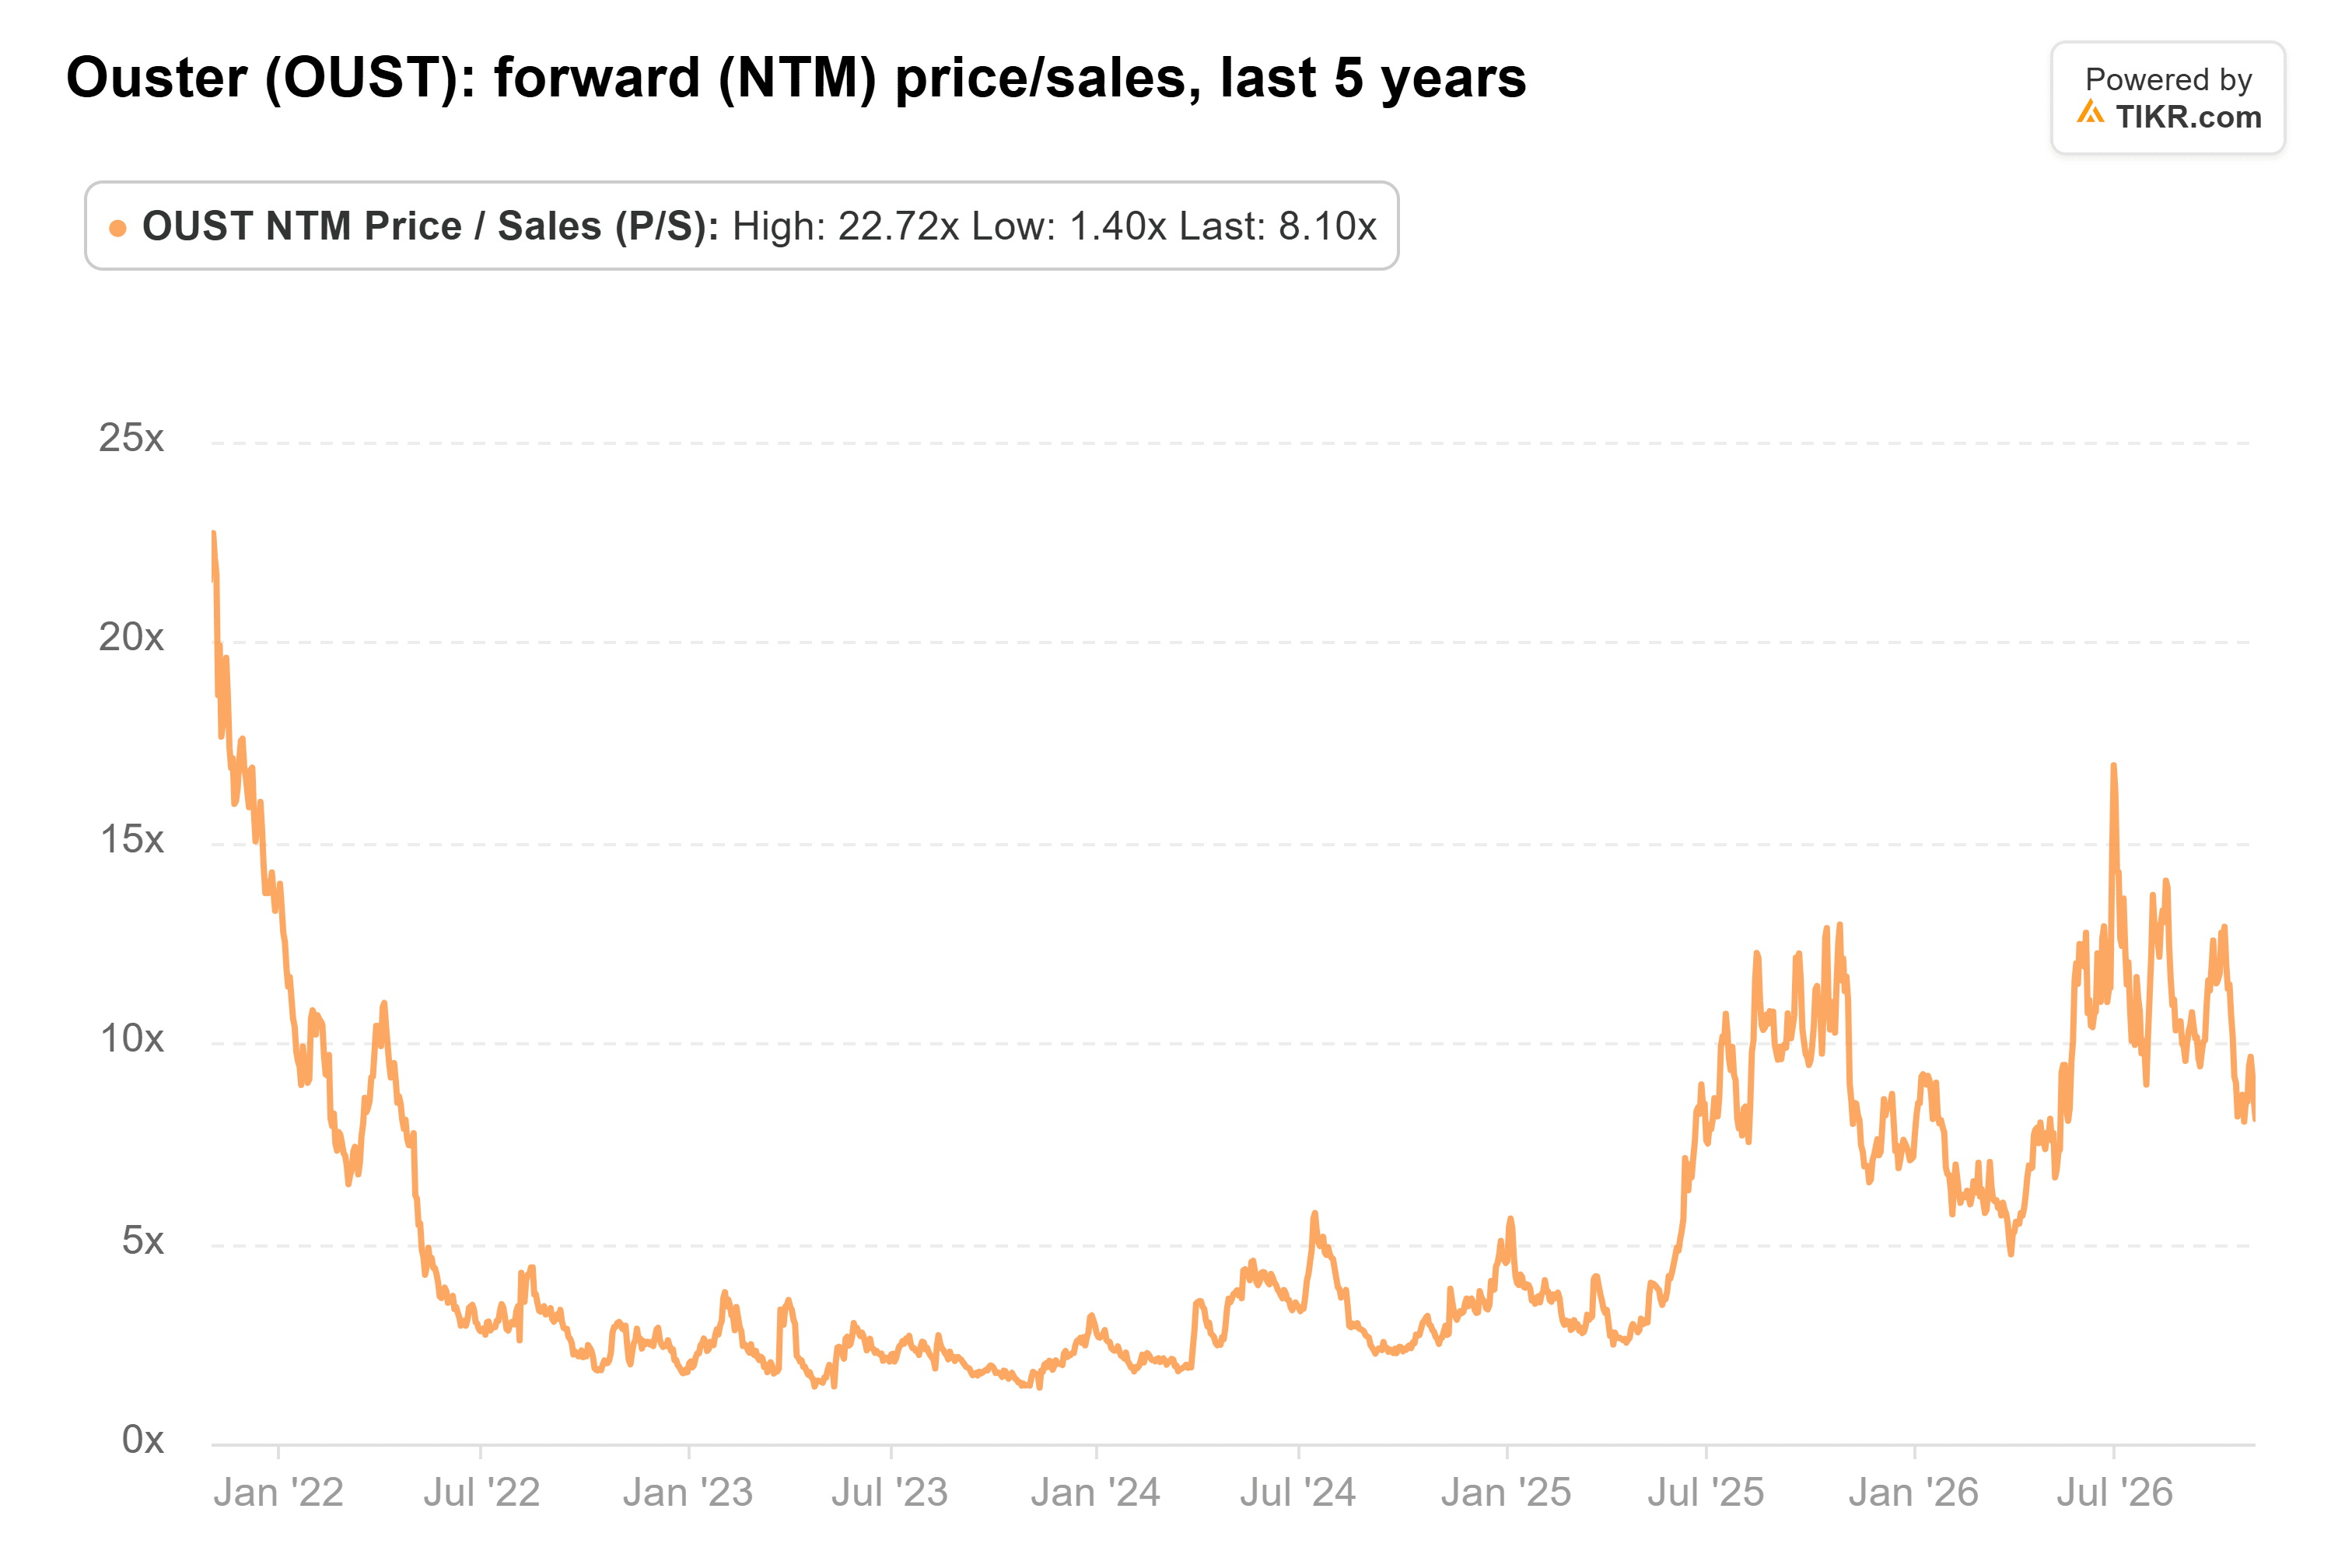
At 8.1x, Ouster trades far below its 23x peak of November 2021 but above its 5-year average of 5.5x. The $59 consensus target from the 6 analysts who cover the stock is about twice where it closed Monday.
Watch the cash burn on Tuesday
Ouster reports third-quarter results on Tuesday, Nov. 3, after the close. Revenue against the consensus matters, and so do gross margin and any word on Rev8 and defense demand. But the cash burn may matter most:
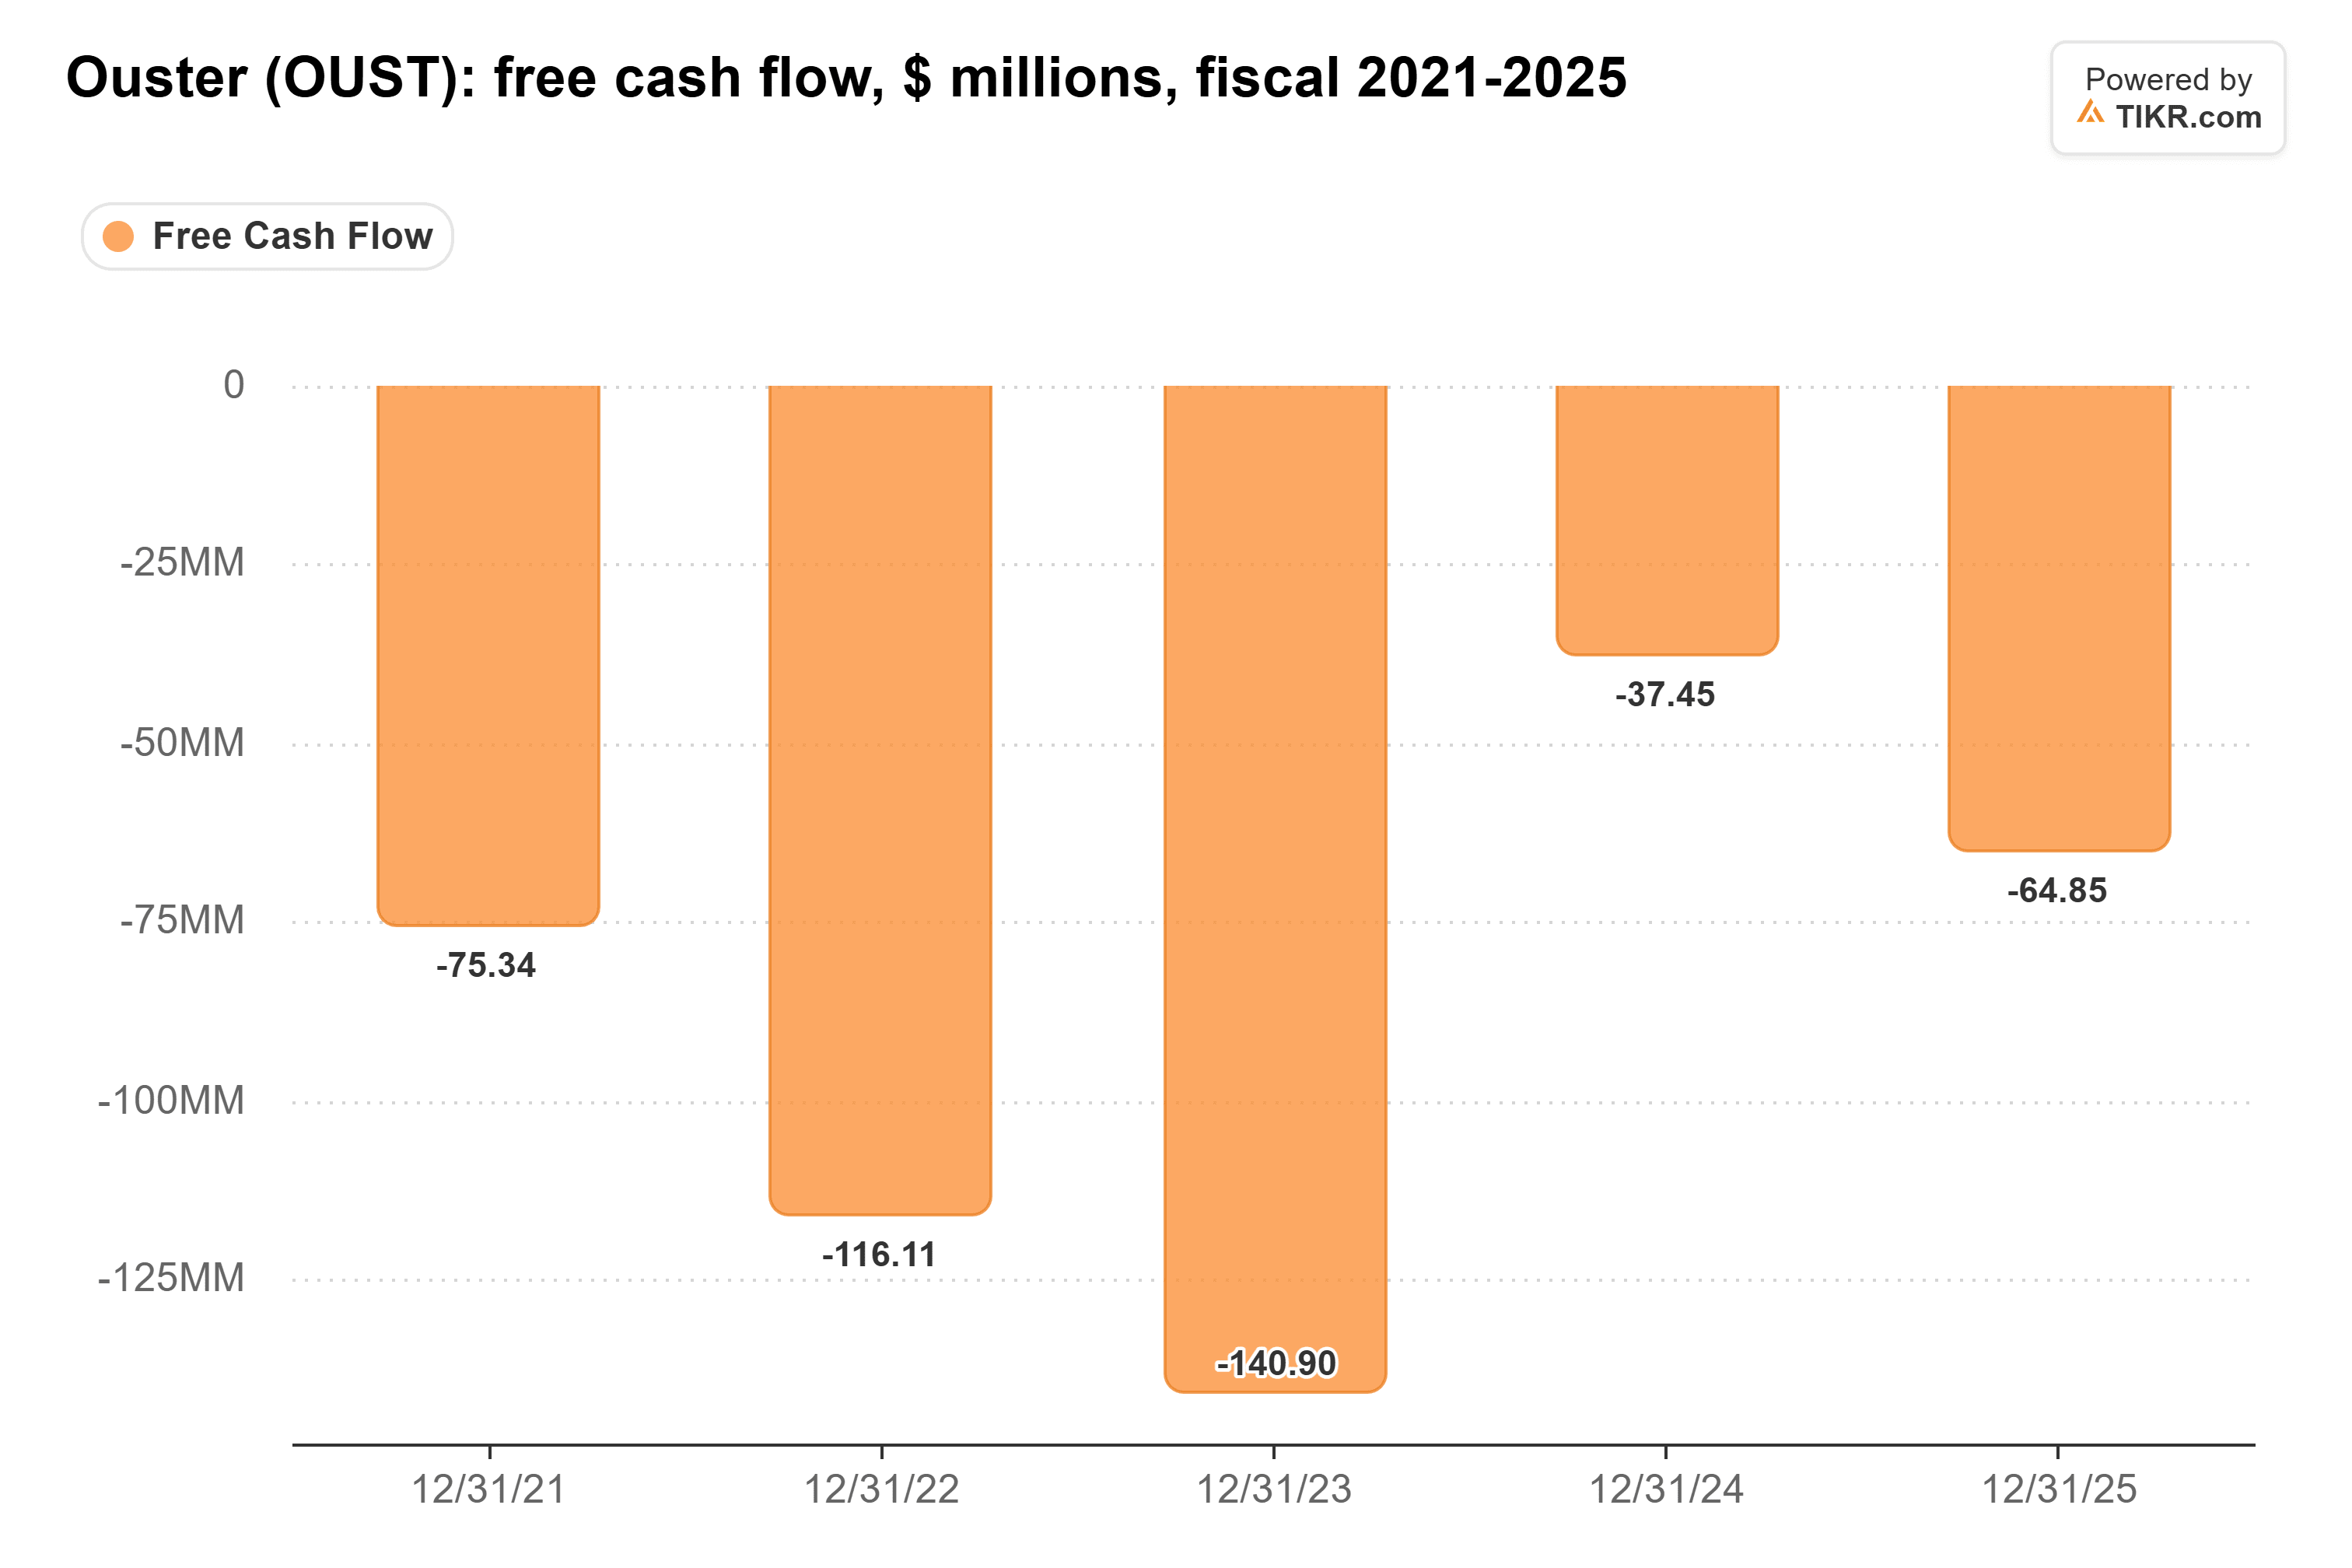
Ouster burned $64.9 million of free cash flow in 2025, more than the $37.5 million it burned in 2024 but less than half the $141 million of 2023. A quarter where the burn shrinks again and growth holds up would go a long way.
I’d load up, carefully
Here’s where I land: with growth estimates intact and the stock at about 8x forward sales, I’d rather be buying Ouster than selling it, as long as you can sit through big swings.
Of course, the AI sell-off may not be done. Another hot inflation report or another rough week for chip stocks could pull Ouster lower whatever Tuesday’s quarter shows.
So what is Ouster stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Ouster could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!