Key Takeaways
- Oppenheimer raised its Amazon price target to $310 from $285 on Nov. 20, 26% above Friday’s close, and kept its Outperform rating.
- The whole raise comes from Anthropic’s IPO, which lets Oppenheimer value Amazon’s stake in the AI lab at about $25 a share after a discount.
- A year out, $310 is about 22x analysts’ 2028 earnings estimates, below Amazon’s multiple today and less than half its five-year average.
- The call looks right: $310 needs a slightly lower multiple than Amazon trades at today, and the $25 for Anthropic is the part that can swing.
Amazon (AMZN) fell 4.1% to $246.82 on Friday, Nov. 20, in the tech selloff, but Oppenheimer thinks it has 26% to go. That day, analyst Jason Helfstein raised his price target to $310 from $285 and kept his Outperform rating.
The raise has nothing to do with packages or AWS. It’s all about Anthropic (ANT), which priced its IPO at $83 on Nov. 18, closed its first day at $97.17, then fell 8.5% to $88.91 on Friday.
The Extra $25 Is Anthropic
Amazon has put $18 billion into Anthropic since 2023. Assuming Amazon converts everything it holds, Oppenheimer counts about 3.5 billion Anthropic shares, worth about $339 billion at $97 apiece. After a 15% holding-company discount, that adds about $25 a share to Amazon’s target. So the $285 Oppenheimer had on Amazon’s businesses stays where it was.
Two caveats. Amazon owns about 1.9 billion of those shares outright, and about 1.56 billion more sit in notes that convert only as Amazon’s ownership cap allows. And at Friday’s $88.91, the same math gives about $23, not $25.
Does Amazon’s $310 Add Up?
Analysts have lifted their average target to $326 from $293 a year ago, 32% above Friday’s close.
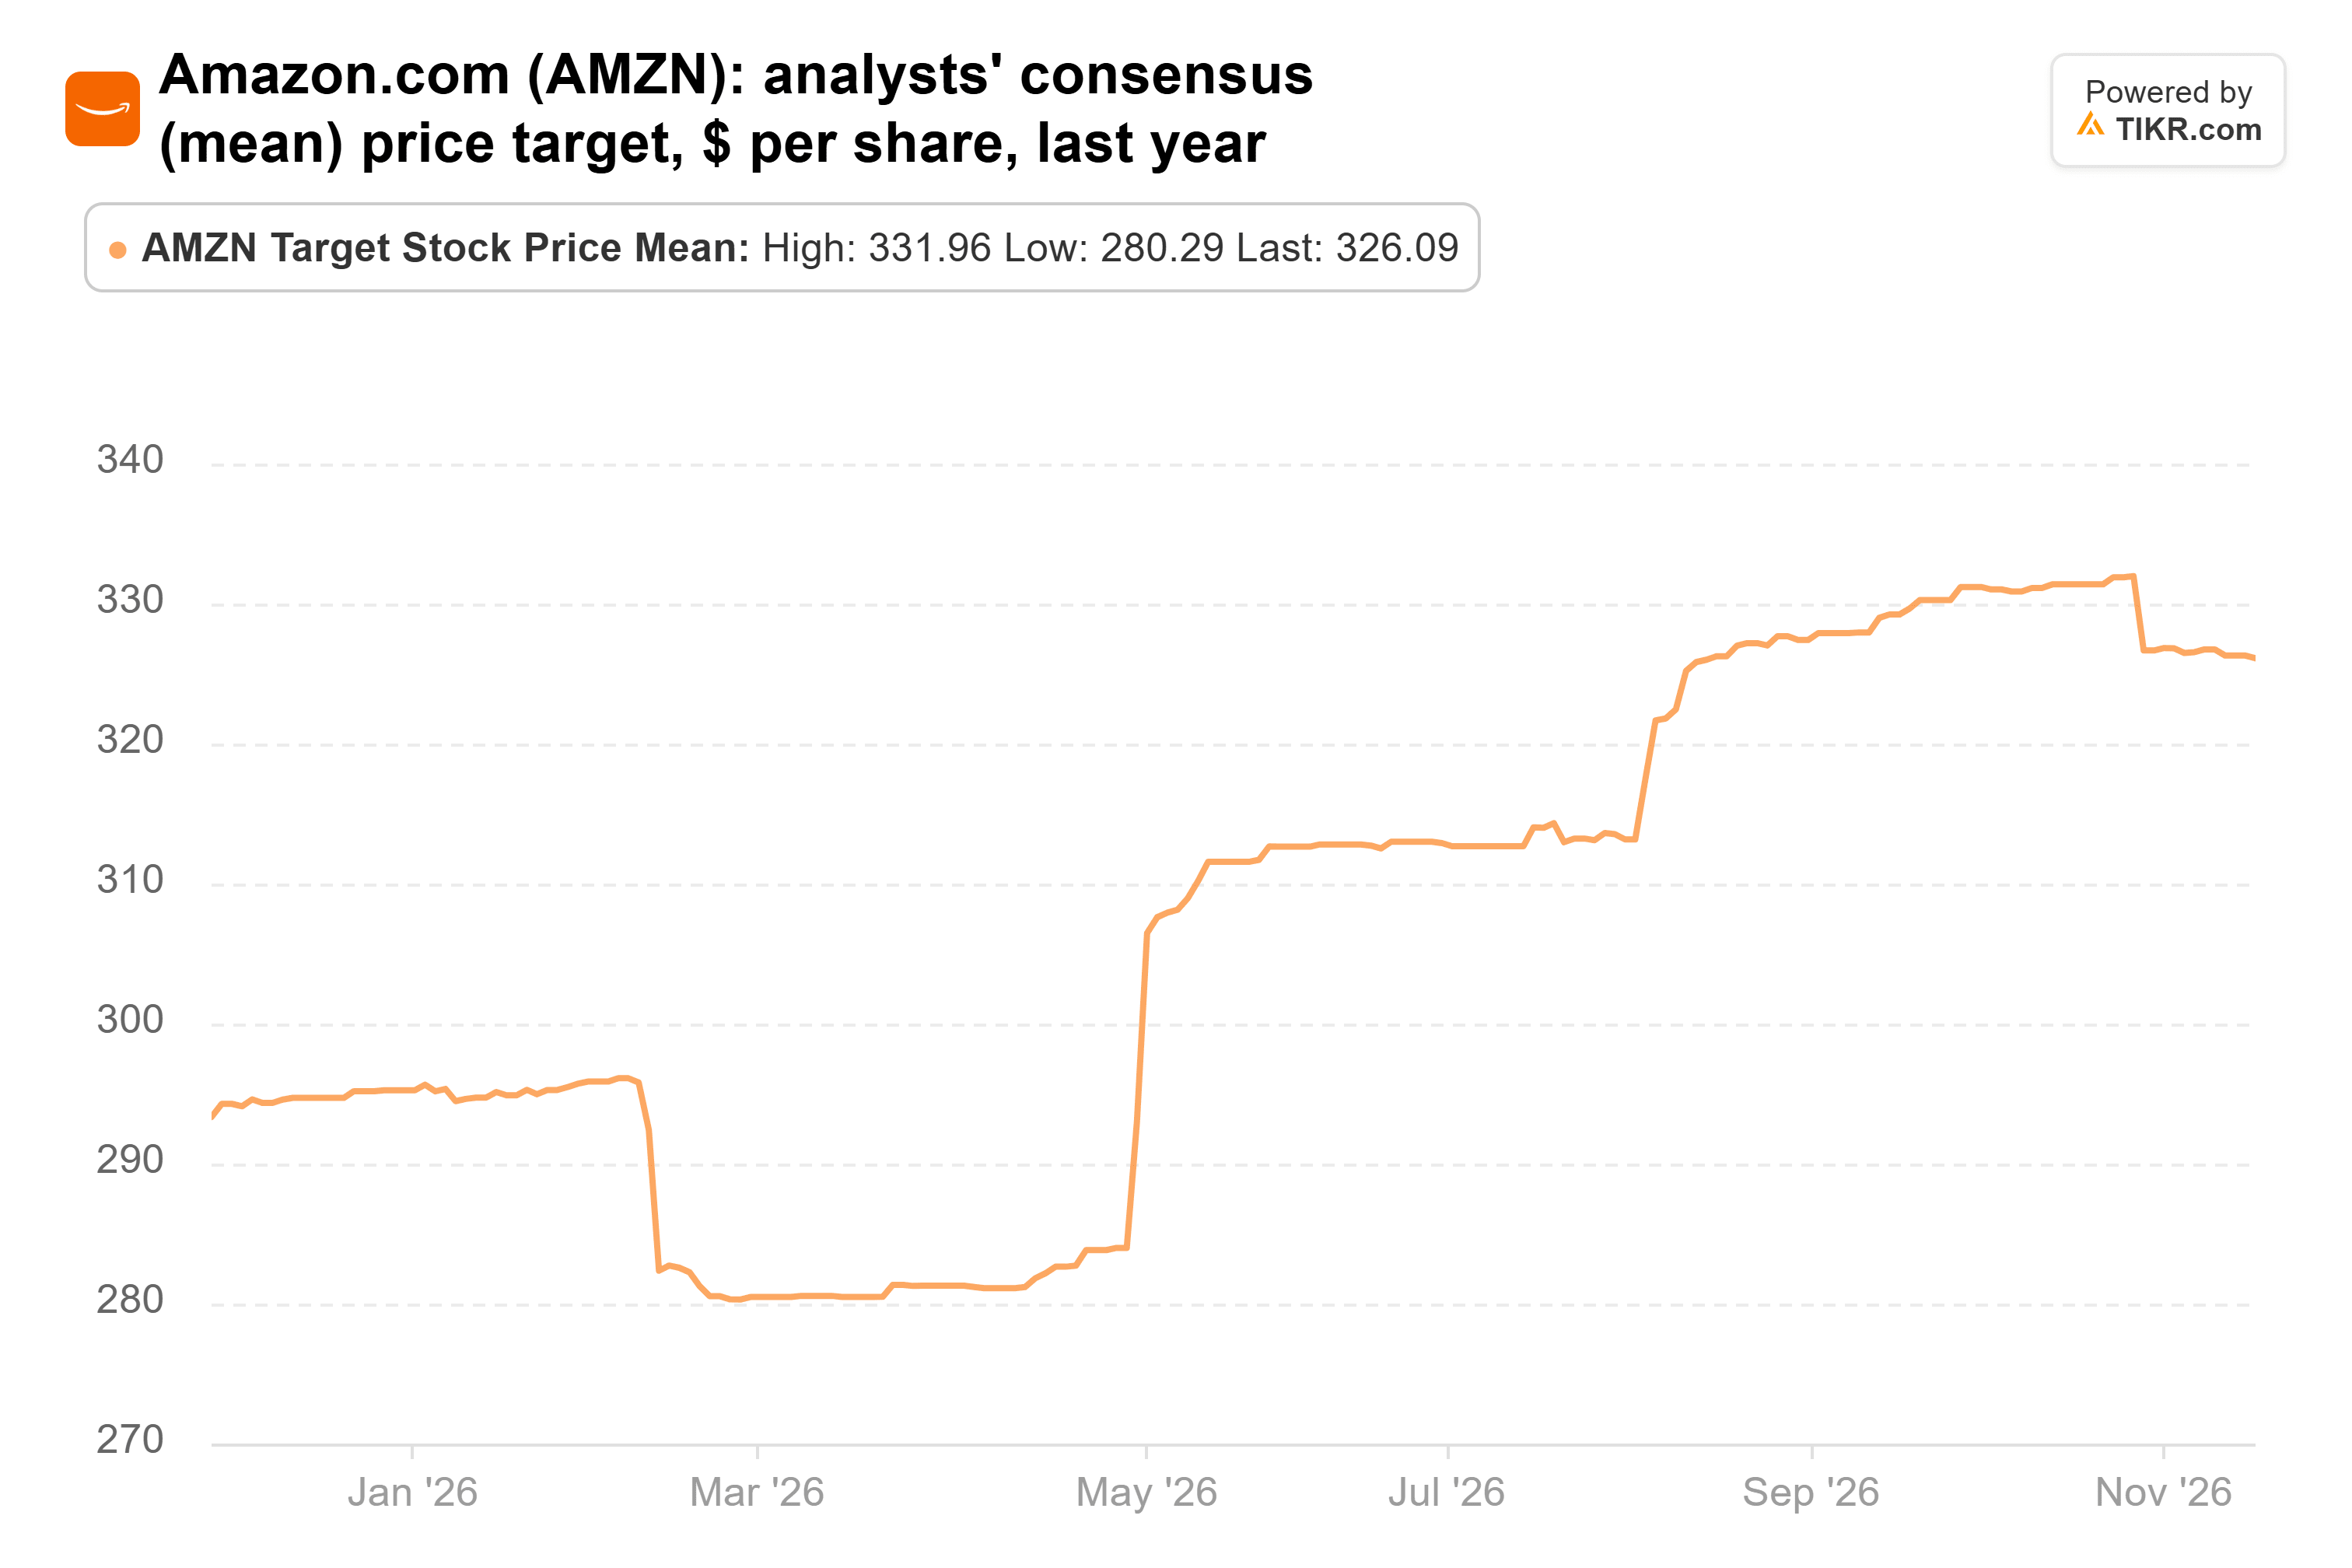
Oppenheimer’s $310 sits below that average, even with Anthropic in it.
Analysts expect normalized EPS to nearly double, from $7.17 in 2025, a year padded by Anthropic gains, to $14.07 in 2028.

Amazon gave them reason to in the third quarter. AWS grew 39.3%, its fastest in nearly five years, and Amazon’s overall operating margin hit 13.9%, its highest ever.
Amazon’s Multiple Is Near Its Five-Year Low
On those 2028 estimates, $310 is 22x earnings. Amazon trades at 24x its next 12 months of earnings, about half its five-year average of 48x.
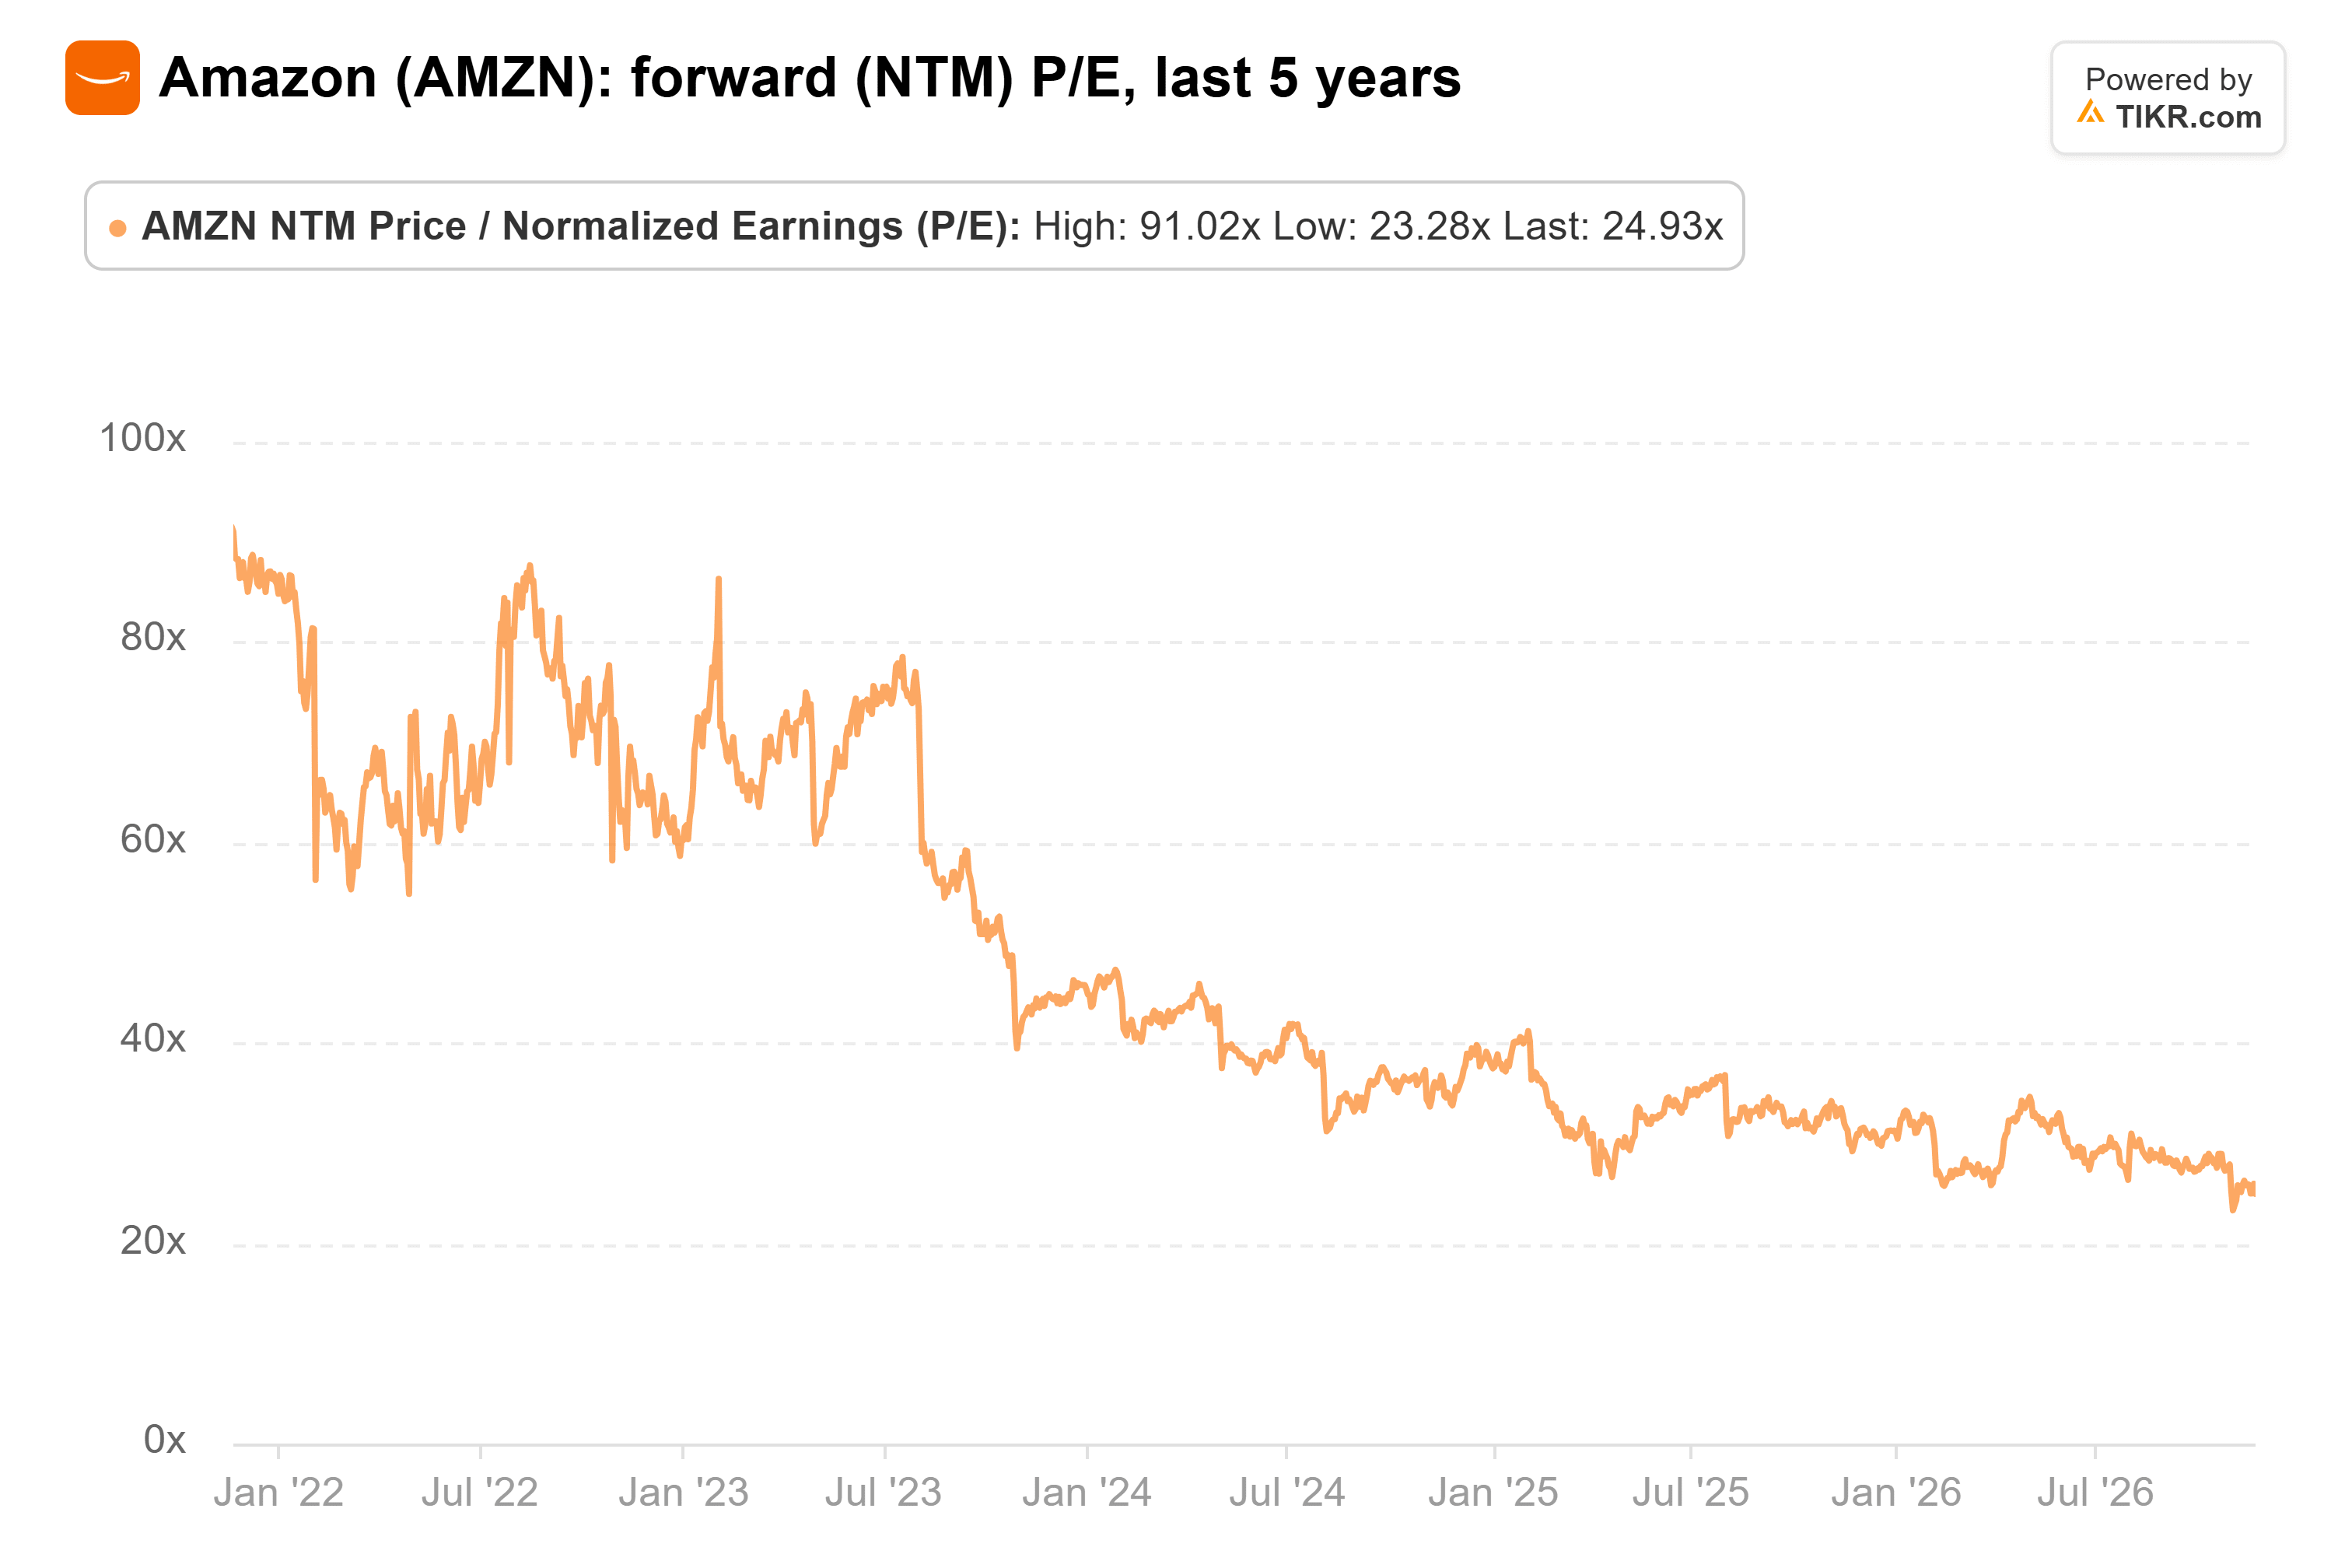
It hit a five-year low of 23x on Oct. 30, the day after that record quarter. At today’s multiple, $310 needs next-12-month EPS of about $12.97 a year from now, 26% above today’s $10.32. That window is mostly 2028, and with late 2027 blended in, estimates put it near $13.70, above $12.97.
TIKR Tracks 62 Analysts on Amazon. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
I’d Trust the $285 More Than the $25
The new $25 is the shaky part. Anthropic’s share price can swing Amazon’s earnings: gains on the notes sit in other comprehensive income until they convert, and more convert each quarter as the cap allows. And Amazon’s free cash flow was a $42.4 billion outflow over the 12 months to Sept. 30, with about $220 billion of capex planned this year and “meaningfully more” coming in 2027.
Even so, Oppenheimer’s $310 looks right to me. On that $13.70 blend, $310 works out to about 23x forward earnings a year from now, a little below today’s 24x, so the target doesn’t need Amazon to re-rate.
The fourth-quarter report, due in early February, is the next check. AWS growth needs to hold at or above the third quarter’s 39.3%, and operating income needs to land within the $28.5 billion to $33.5 billion guide.
So What Is Amazon Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!