Key Takeaways
- Anthropic set its IPO range at $70 to $78 a share. One investor on Reddit works that out to 35x to 39x trailing sales, compared with 53x for Palantir.
- An AI company that’s growing faster and listing at a lower sales multiple than Palantir makes Palantir’s premium harder to defend.
- Analysts expect Palantir’s revenue growth to slow from about 91% this year to 53% in 2027. Anthropic’s first-half revenue was about 14 times what it made a year earlier.
- Palantir is profitable and Anthropic isn’t yet. Palantir’s first 2027 guidance, expected in early February, is the next test.
Anthropic set its IPO price range this week, and the math is awkward for Palantir Technologies (PLTR).
The AI lab will offer 825 million shares at $70 to $78 apiece, according to its updated filing. It plans to list on the Nasdaq under the ticker ANT next week. A poster on Reddit’s r/ValueInvesting ran the numbers and summed it up like this:
“At its IPO range, Anthropic would cost less than Palantir on sales but nearly 3x Nvidia.”
The poster puts Anthropic at 35x to 39x trailing sales, compared with 53x for Palantir and 13x for Nvidia (NVDA). For Palantir shareholders, the top of that list is an uncomfortable place to sit.
Investors will make that comparison, too. On CNBC’s Squawk Pod, a host argued that a lower price for Anthropic pulls valuations down across AI. Plexo Capital’s Lo Toney answered that the listing “does put some pressure on those other companies,” since investors are going to “use Anthropic as a benchmark.” He was talking about private labs like OpenAI, but Palantir’s shareholders get the same benchmark next week.
TIKR tracks 33 analysts on Palantir. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palantir, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palantir’s Analyst Ratings
Palantir’s premium is built on growth
Palantir’s business is still firing. Third-quarter revenue rose 96% to $2.31 billion, and the company raised its 2026 revenue guidance to $8.53 billion. Even so, the stock is down 19% from its record close on Oct. 9. Part of the reason is that the value of new contracts it signed grew just 6% to $2.92 billion in the quarter, after 49% growth in the second quarter. Management blamed shorter contracts.
Analysts expect Palantir’s revenue growth to slow from here:
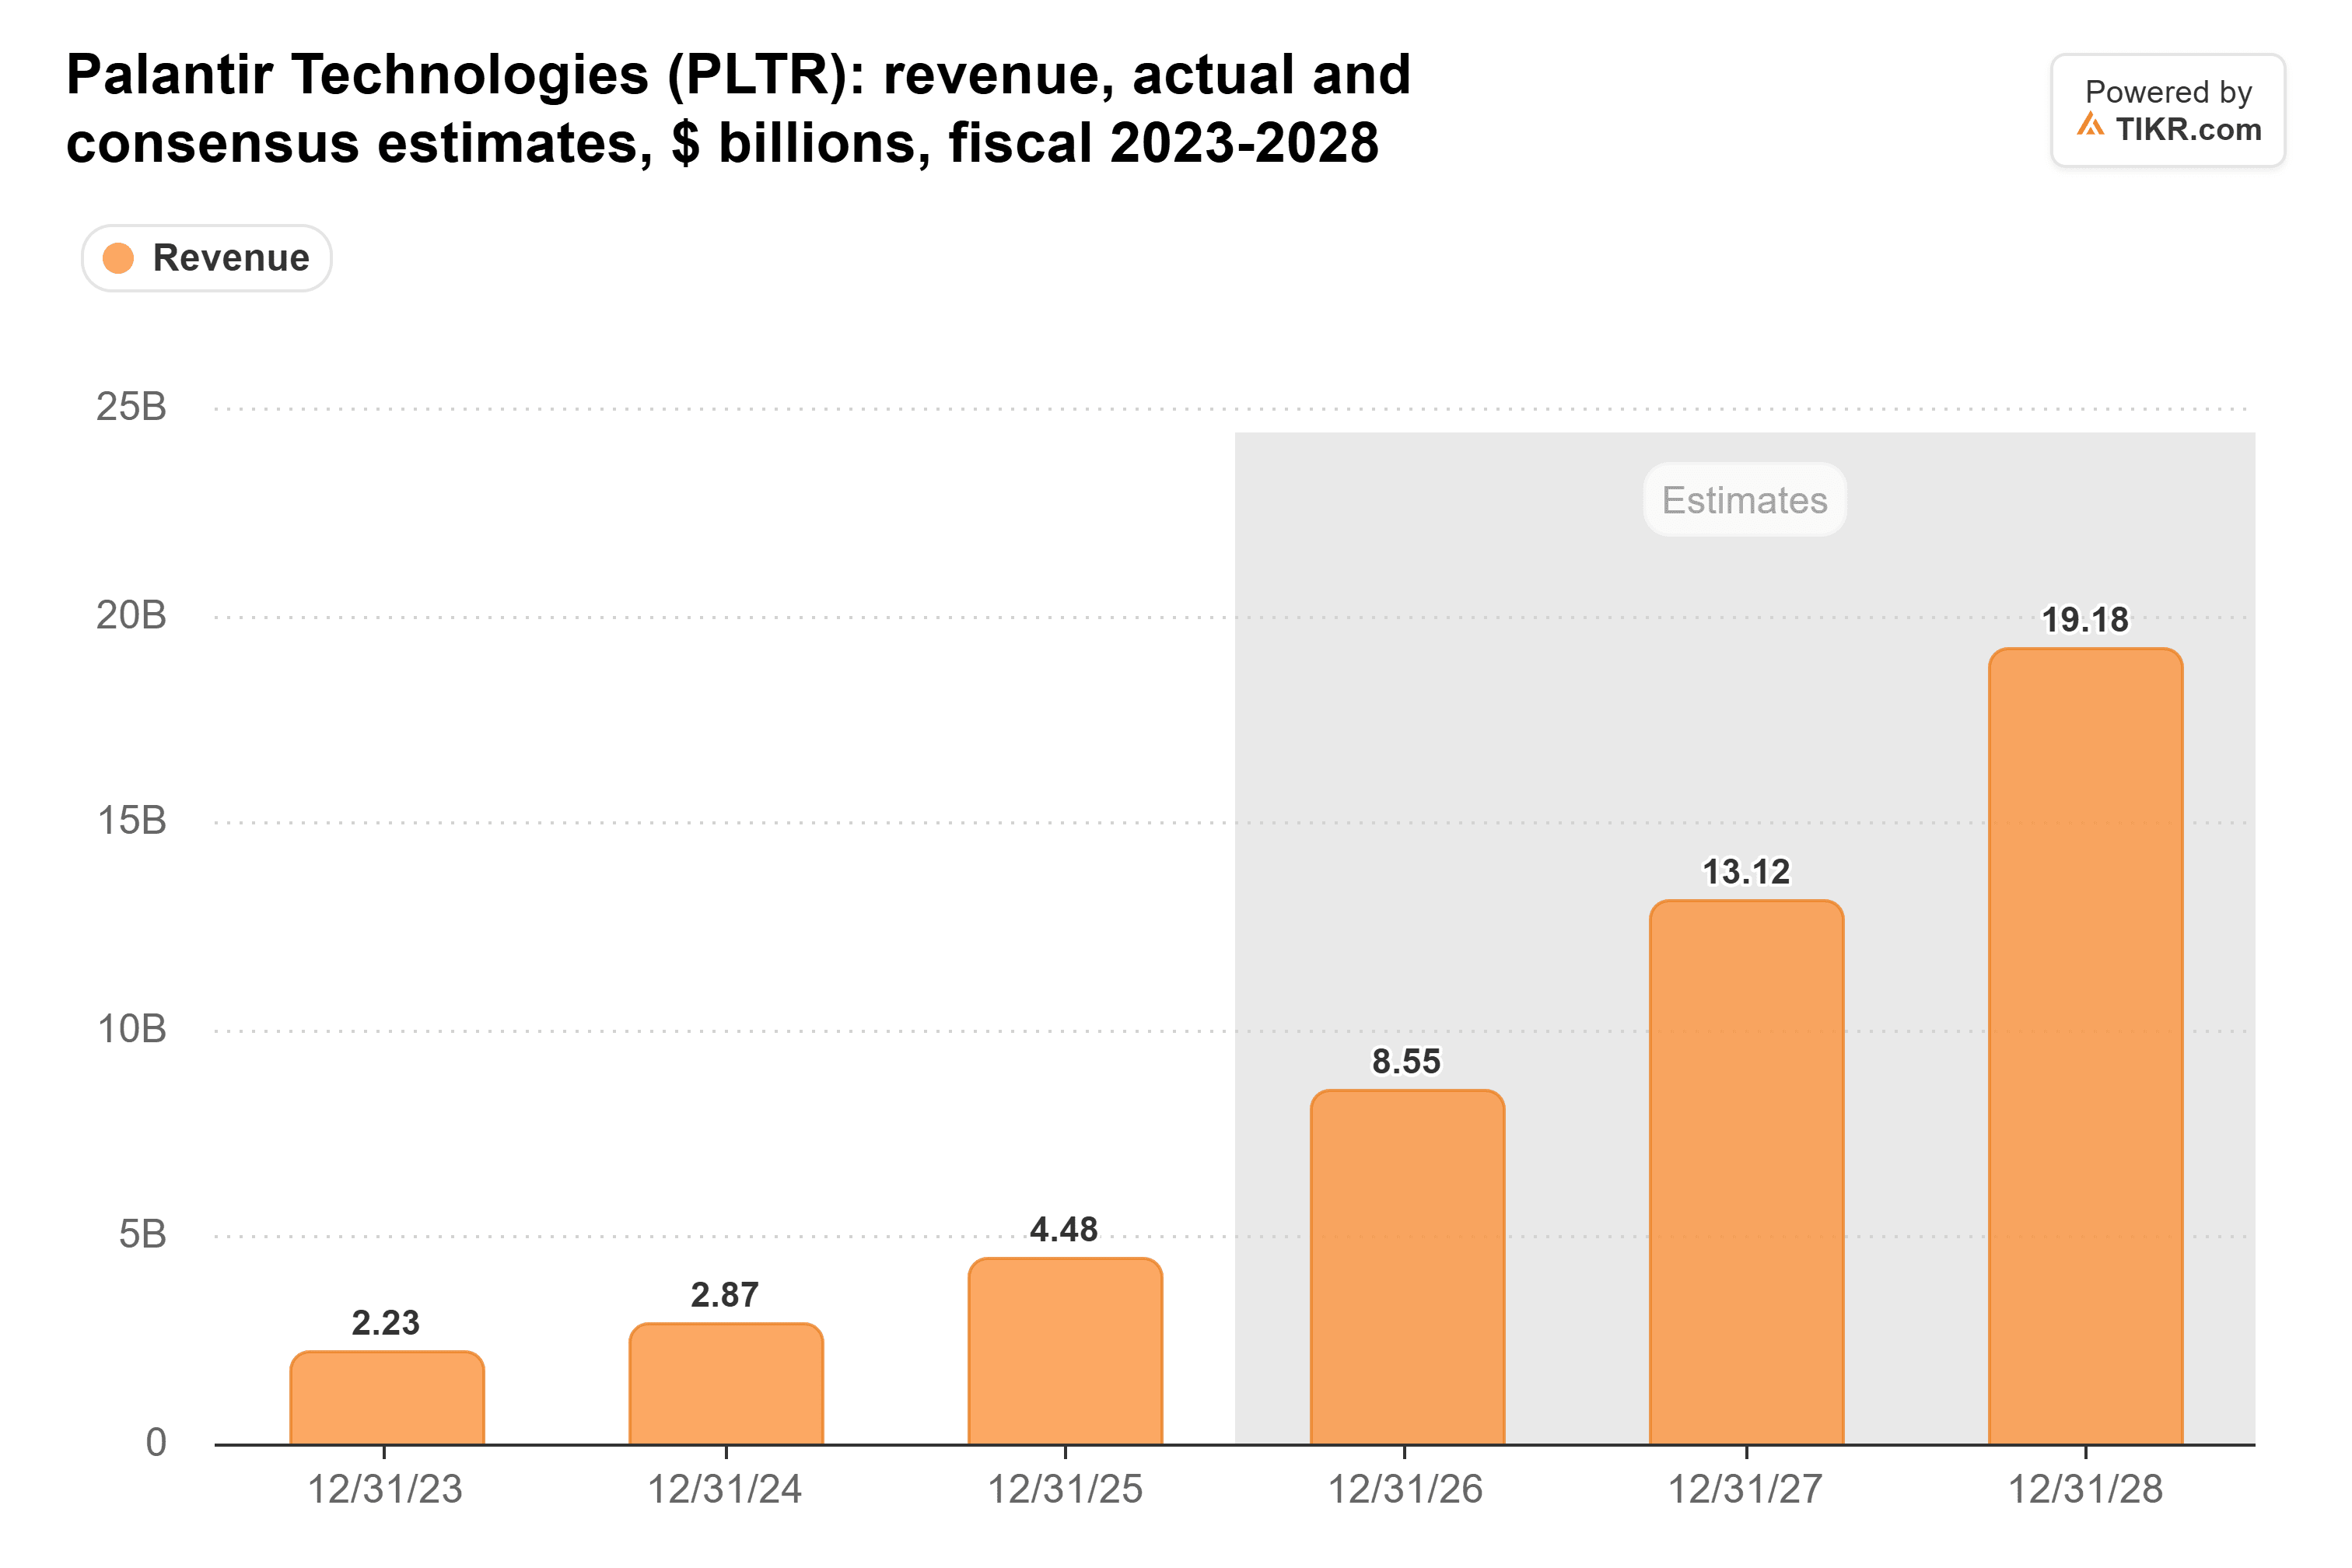
That’s about 91% growth this year, then 53% in 2027 and 47% in 2028. Those are still terrific numbers, but they’re a long way from the pace investors have been paying for.
Anthropic is growing far faster
Anthropic’s own numbers are on another level. Its S-1 shows $16.3 billion of revenue in the first half of 2026, about 14 times the $1.16 billion it brought in a year earlier. Second-quarter revenue alone was $11.6 billion, up from $4.7 billion in the first quarter. At that pace, its multiple on next year’s sales would be even lower than the poster’s trailing figure.
Not every AI stock comes off worse, though. Nvidia is at 13x sales on the poster’s list. It’s also one of the seven companies buying $26 billion of Anthropic stock at the IPO price in a private placement. So Anthropic’s price puts software premiums like Palantir’s under pressure, far more than it does a chipmaker priced at a fraction of either.
Palantir’s profits are already in the price
Of course, sales multiples flatter Anthropic. Palantir turned 47% of its second-quarter revenue into GAAP operating income, and it kept 55% of revenue as free cash flow over the 12 months to June. Anthropic posted a $693 million operating loss in the first half of 2026 and an $80.7 billion net loss. Most of that loss was a $72.4 billion non-cash charge tied to its rising valuation.
But investors already pay Palantir for those profits, and then some. Its forward P/E has come down hard, and it’s still rich:
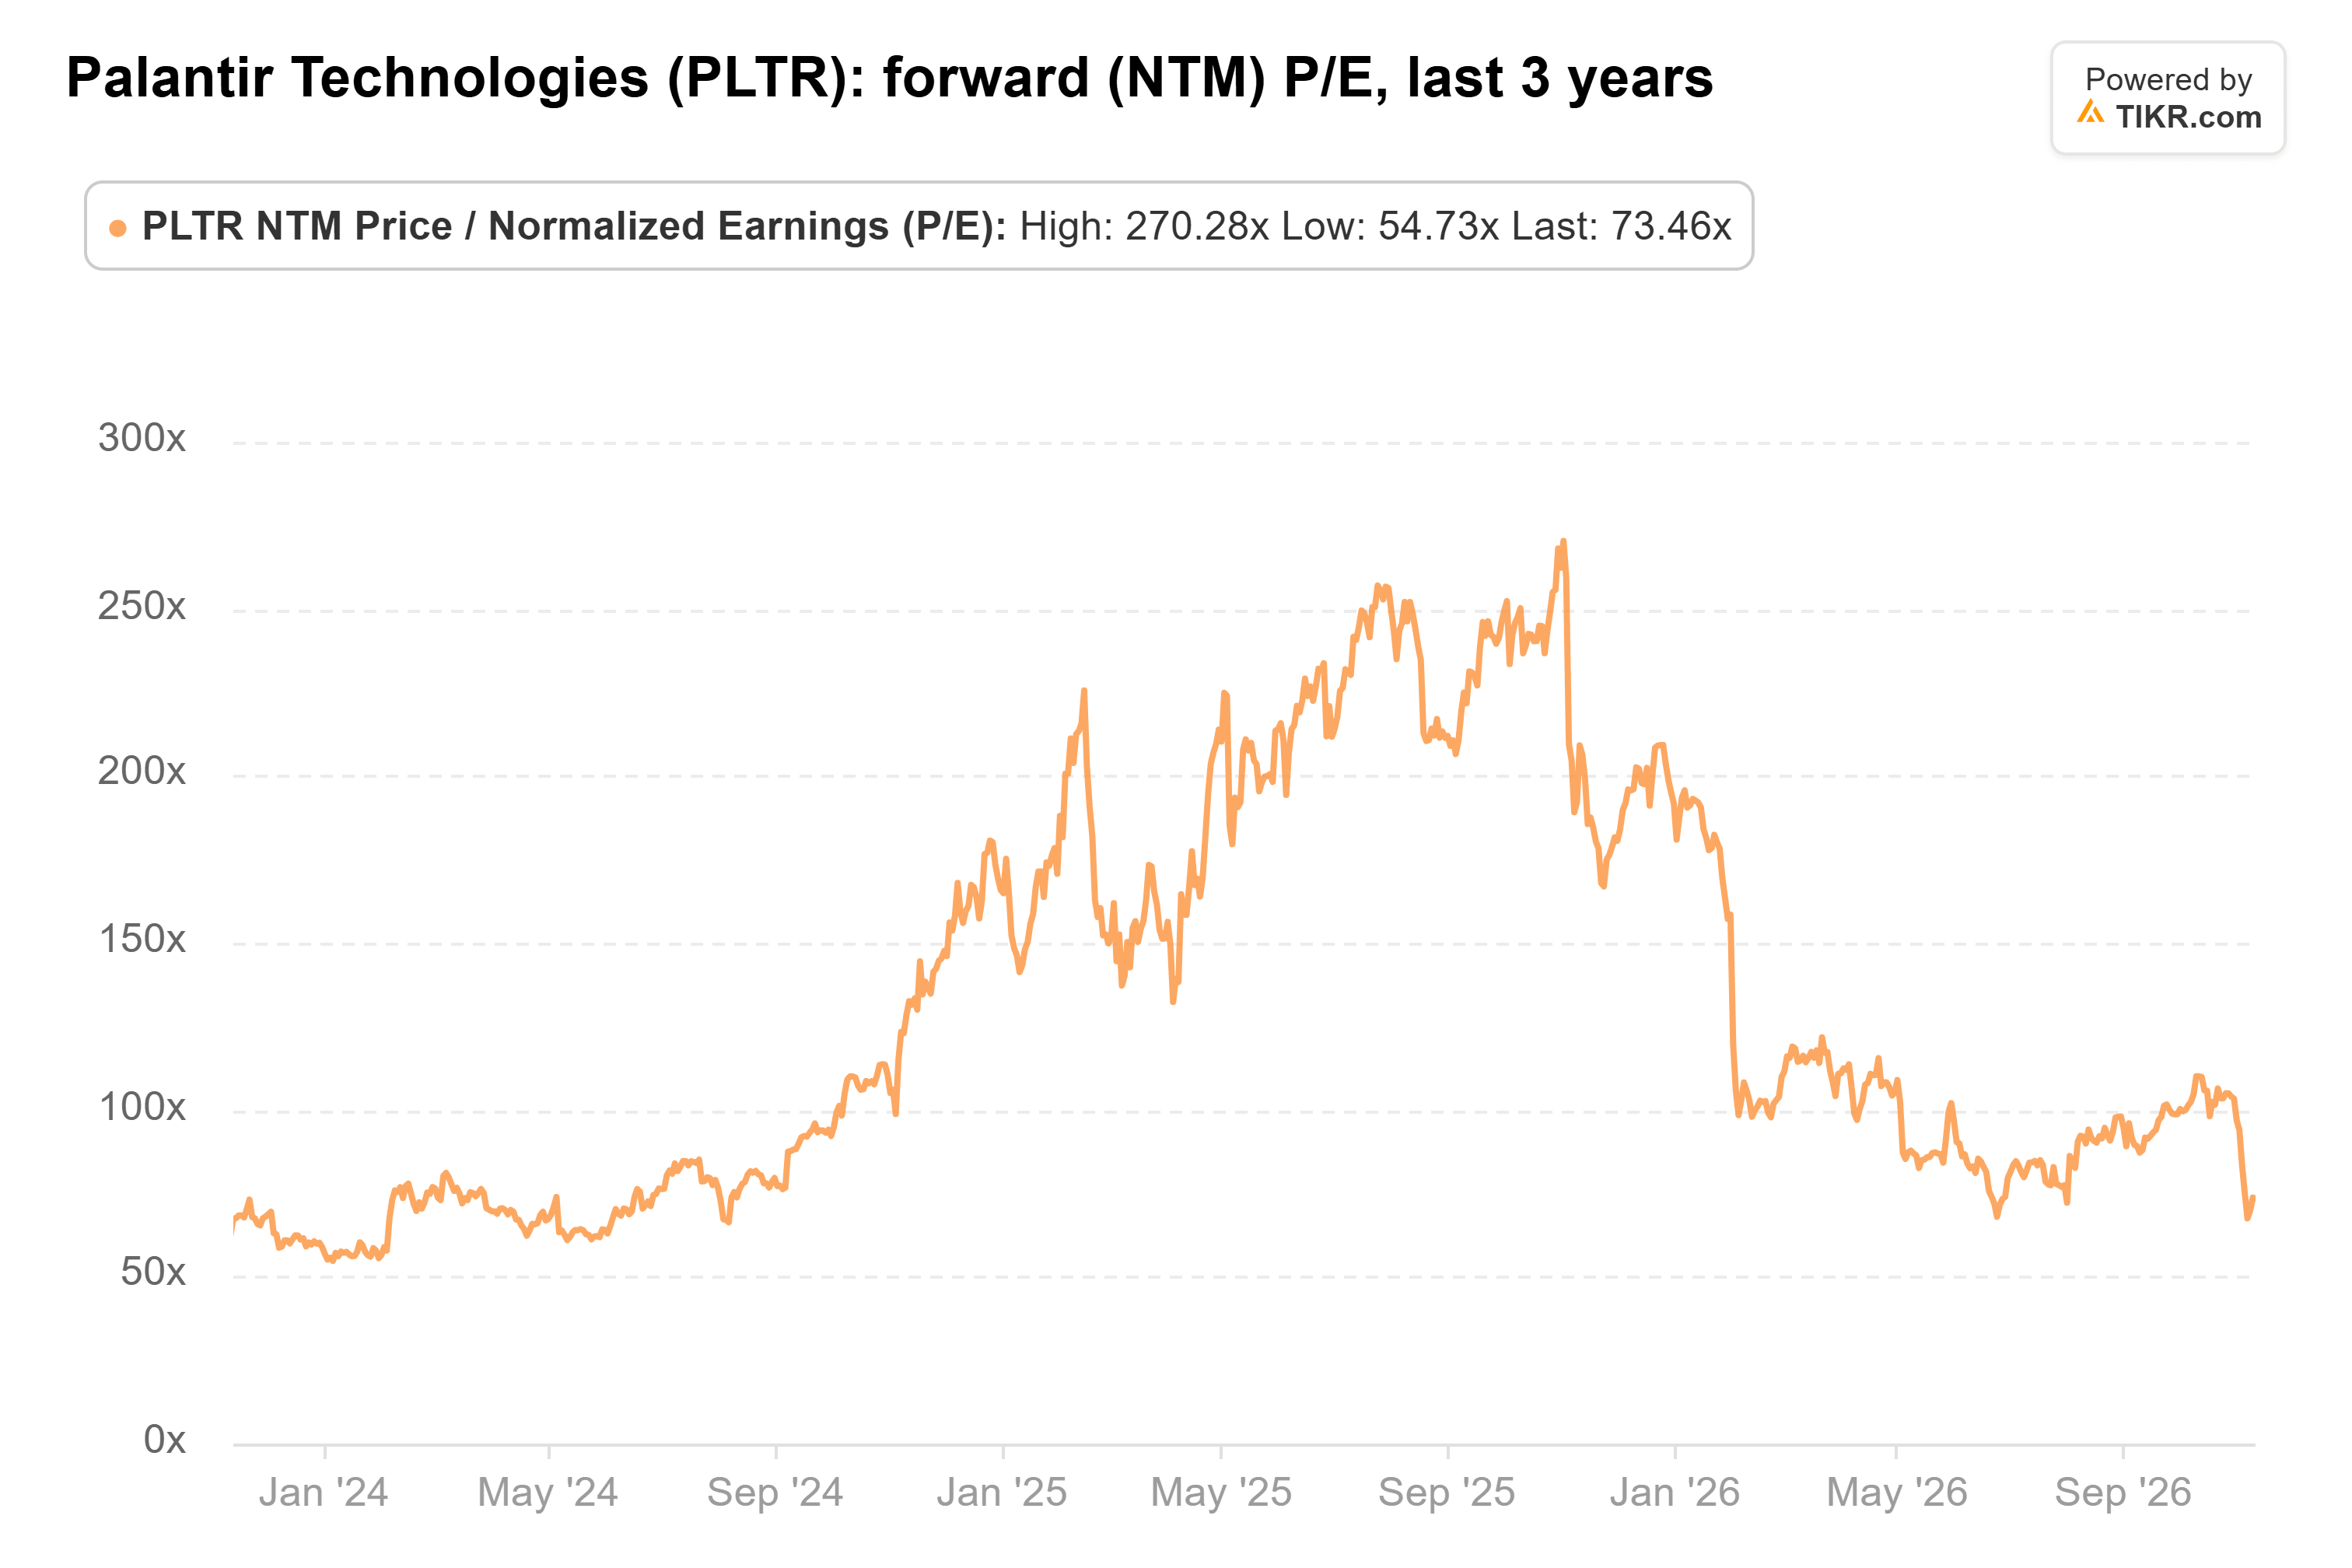
Palantir trades at 74x forward earnings. That’s below its three-year average of 130x and far from its 270x peak at the end of October 2025, but still well above its 55x low in January 2024. Analysts kept raising their earnings estimates while the multiple fell, so this is investors deciding what Palantir’s growth is worth. Anthropic gives them a faster-growing alternative at a lower sales multiple, and one more reason to pay less.
The way I see it, Palantir’s multiple has more room to fall than to recover until its growth can stand next to Anthropic’s. The next test is Palantir’s first 2027 revenue guidance, expected with its fourth-quarter report in early February, compared with the $13.1 billion of 2027 revenue analysts expect. Of course, Anthropic hasn’t priced yet, and a first trade well above $78 would push its sales multiple back up toward Palantir’s.
So what is Palantir stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palantir could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!