Key Takeaways
- Nu Holdings shares jumped 11% today on record third-quarter net income of $1.1 billion.
- Nu is deliberately taking on more credit risk, and its 32% return on equity pays for it.
- Nu’s loans grew far faster than Itaú Unibanco’s and Bradesco’s, and it now takes on MercadoLibre in Mexico.
- Before today’s jump, the stock traded at 4.4x tangible book value, about half its three-year average.
Nu Holdings (NU) stock is up 11% today after it reported record third-quarter net income of $1.1 billion, up 31% FX-neutral, after Thursday’s close. Founder and CEO David Vélez said the quarter included Nu’s “first steps beyond Latin America.”
At home, Nu’s credit portfolio grew 33% over the year to $41.6 billion, far faster than loans to individuals at Itaú Unibanco (ITUB), up 9.6%, and Banco Bradesco (BBD), up 7.4%. And in Mexico, where Nu just finished its first quarter as a full bank, it goes up against MercadoLibre (MELI).
TIKR tracks 23 analysts on Nu Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nu Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nu Holdings’ Analyst Ratings
More profit, and more risk by design
Return on equity hit 32%, but the 90+ day NPL ratio rose to 7.3% from 6.9% in the second quarter.
That’s on purpose. “We continue to expand our credit portfolio, deliberately taking some additional risk when the expected returns justify it,” CFO Rob Livingston said on the call. Excluding one-off items, Nu’s risk-adjusted net interest margin rose to 12.7% from 11.9% in the second quarter.
Itaú’s 90-day NPL ratio was 2.0%, barely above 1.9% a year earlier, so the rise in Nu’s bad loans looks like Nu’s own choice. And Nu’s ROE beats Itaú’s 23.6%.
Mexico is the next test, where Nu now has 16.6 million customers. MercadoLibre says it gained fintech share there in its own third quarter, but its operating income fell 6% as it reinvested. Can it keep pushing against a full-fledged Nu bank while already giving up margin?
Cheap for a bank growing this fast
Nu also cut its full-year efficiency-ratio forecast to 19%-19.5%, from about 20%.
Analysts expected Nu’s normalized EPS to keep climbing well before this report:
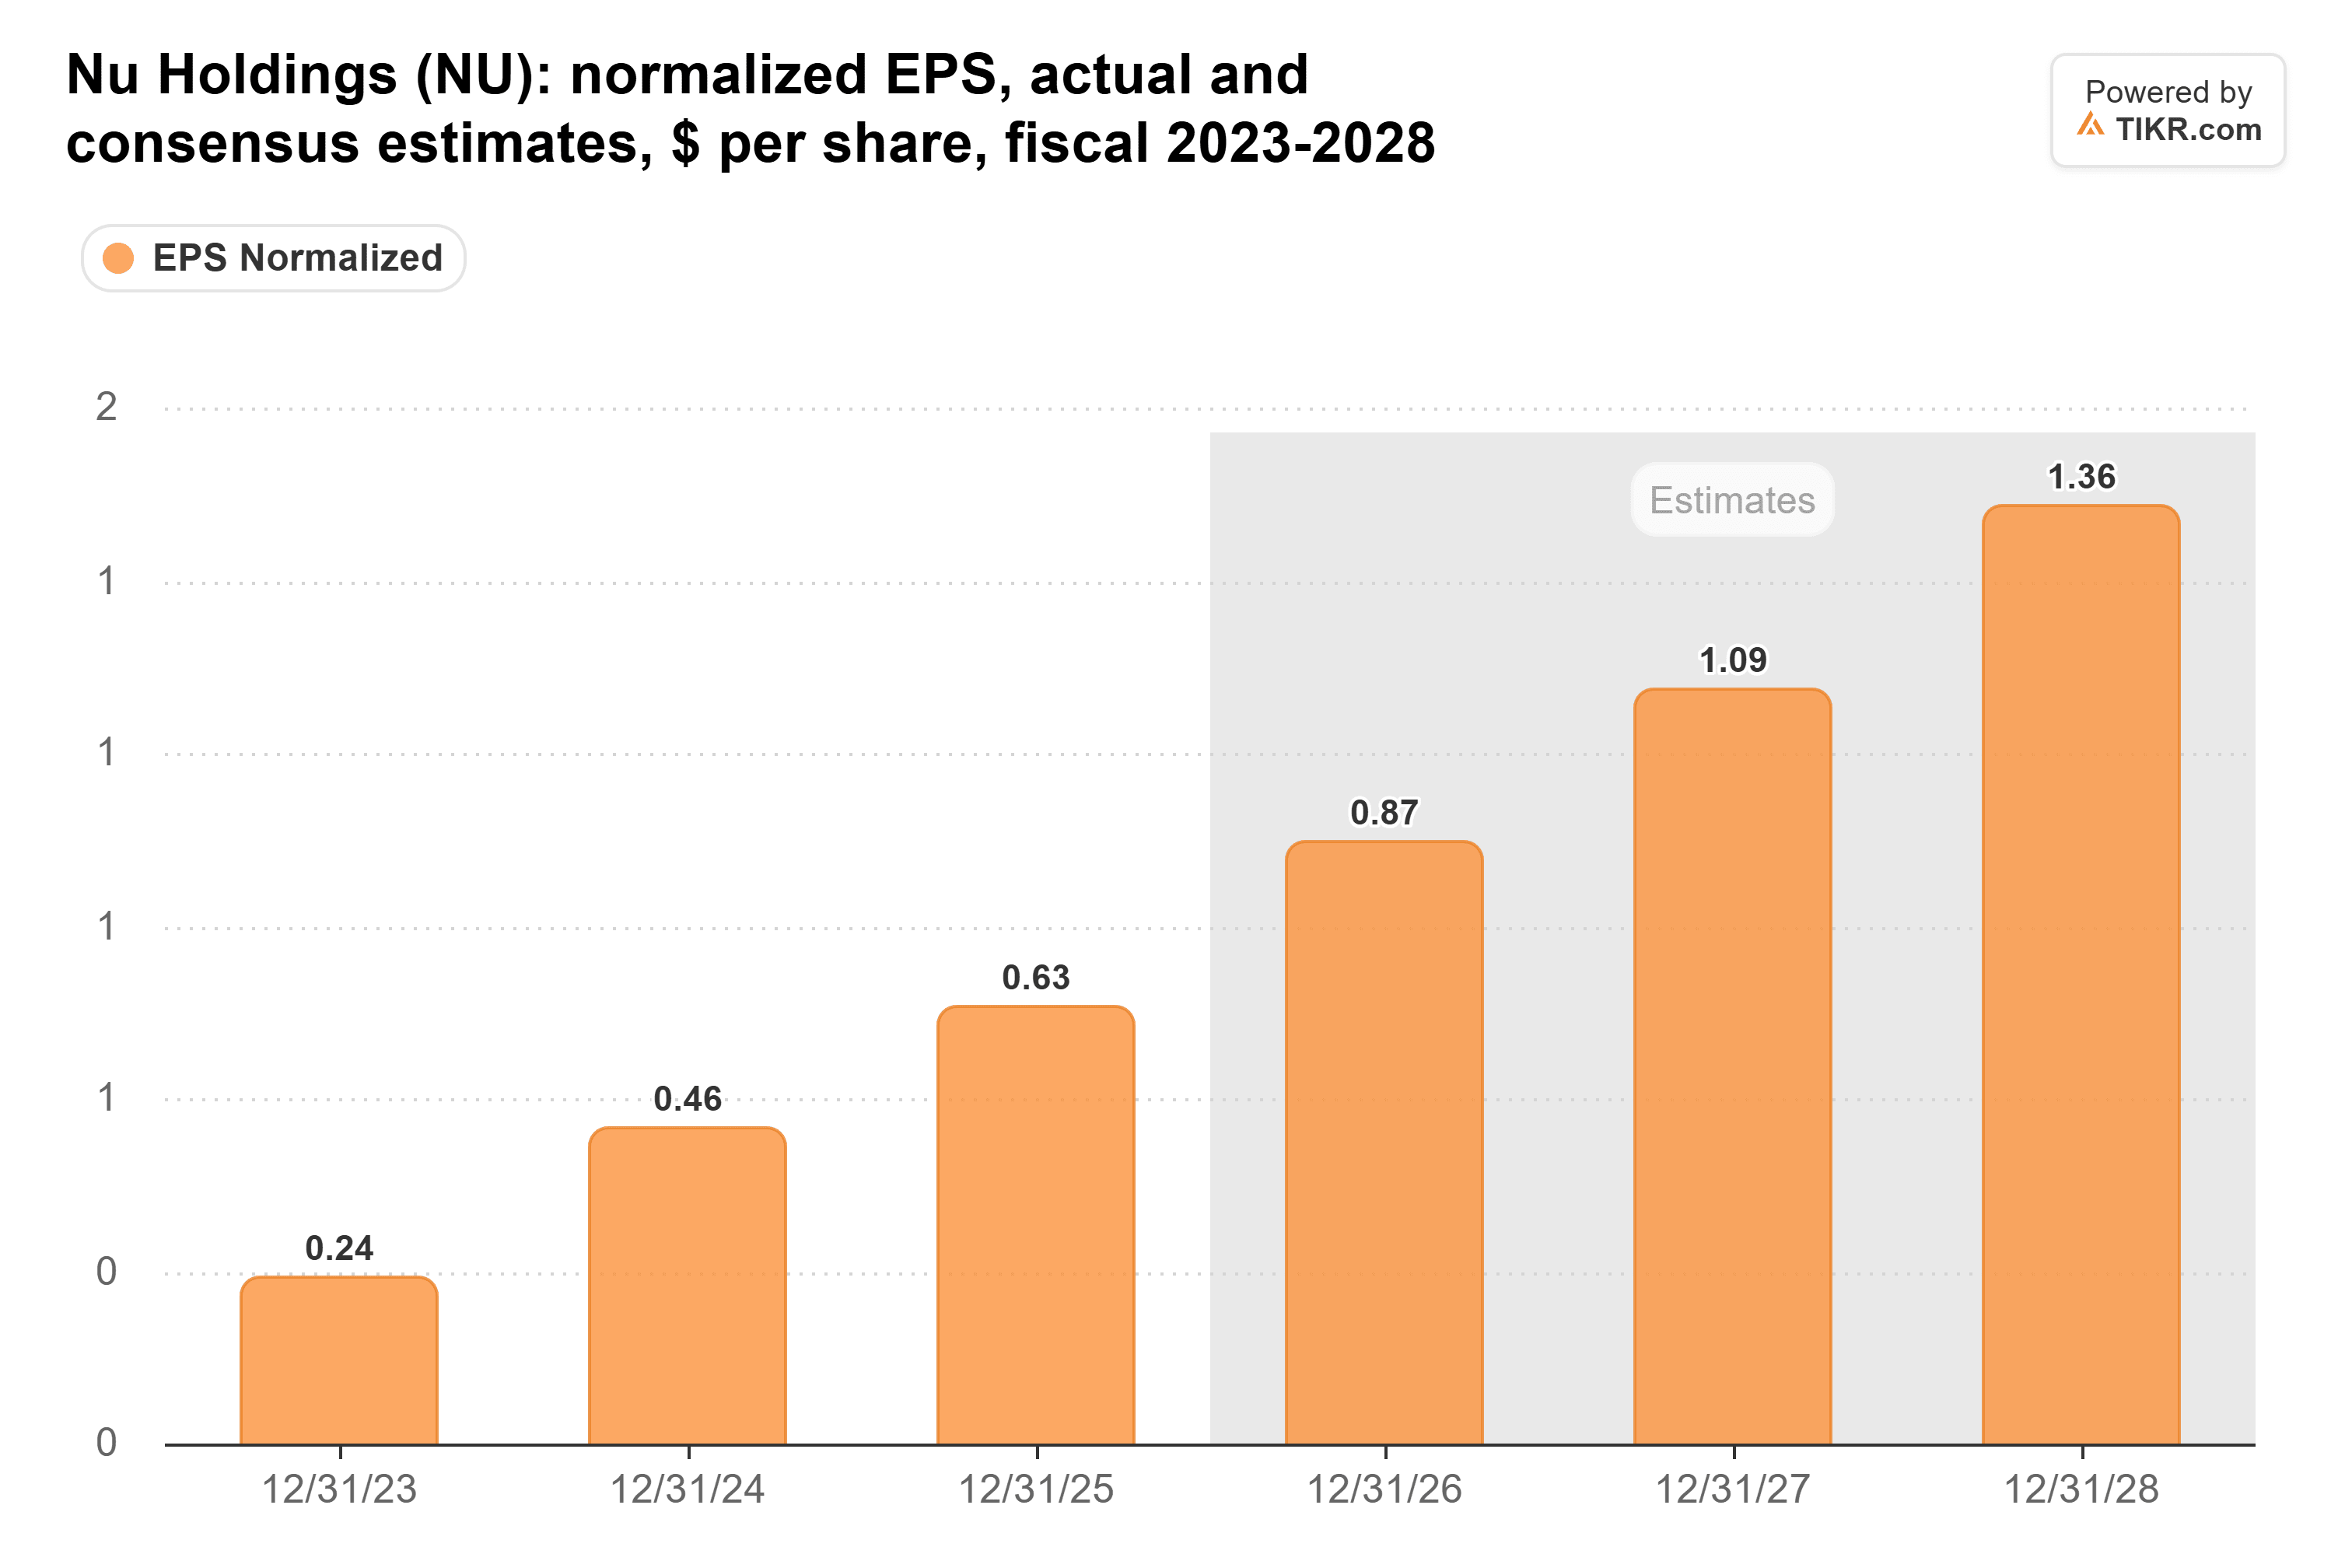
A record quarter and a lower expense forecast give analysts no reason to cut those numbers.
Still, the stock traded at 4.4x tangible book value at the last close. That’s the low of its last three years and about half its 8.2x average:
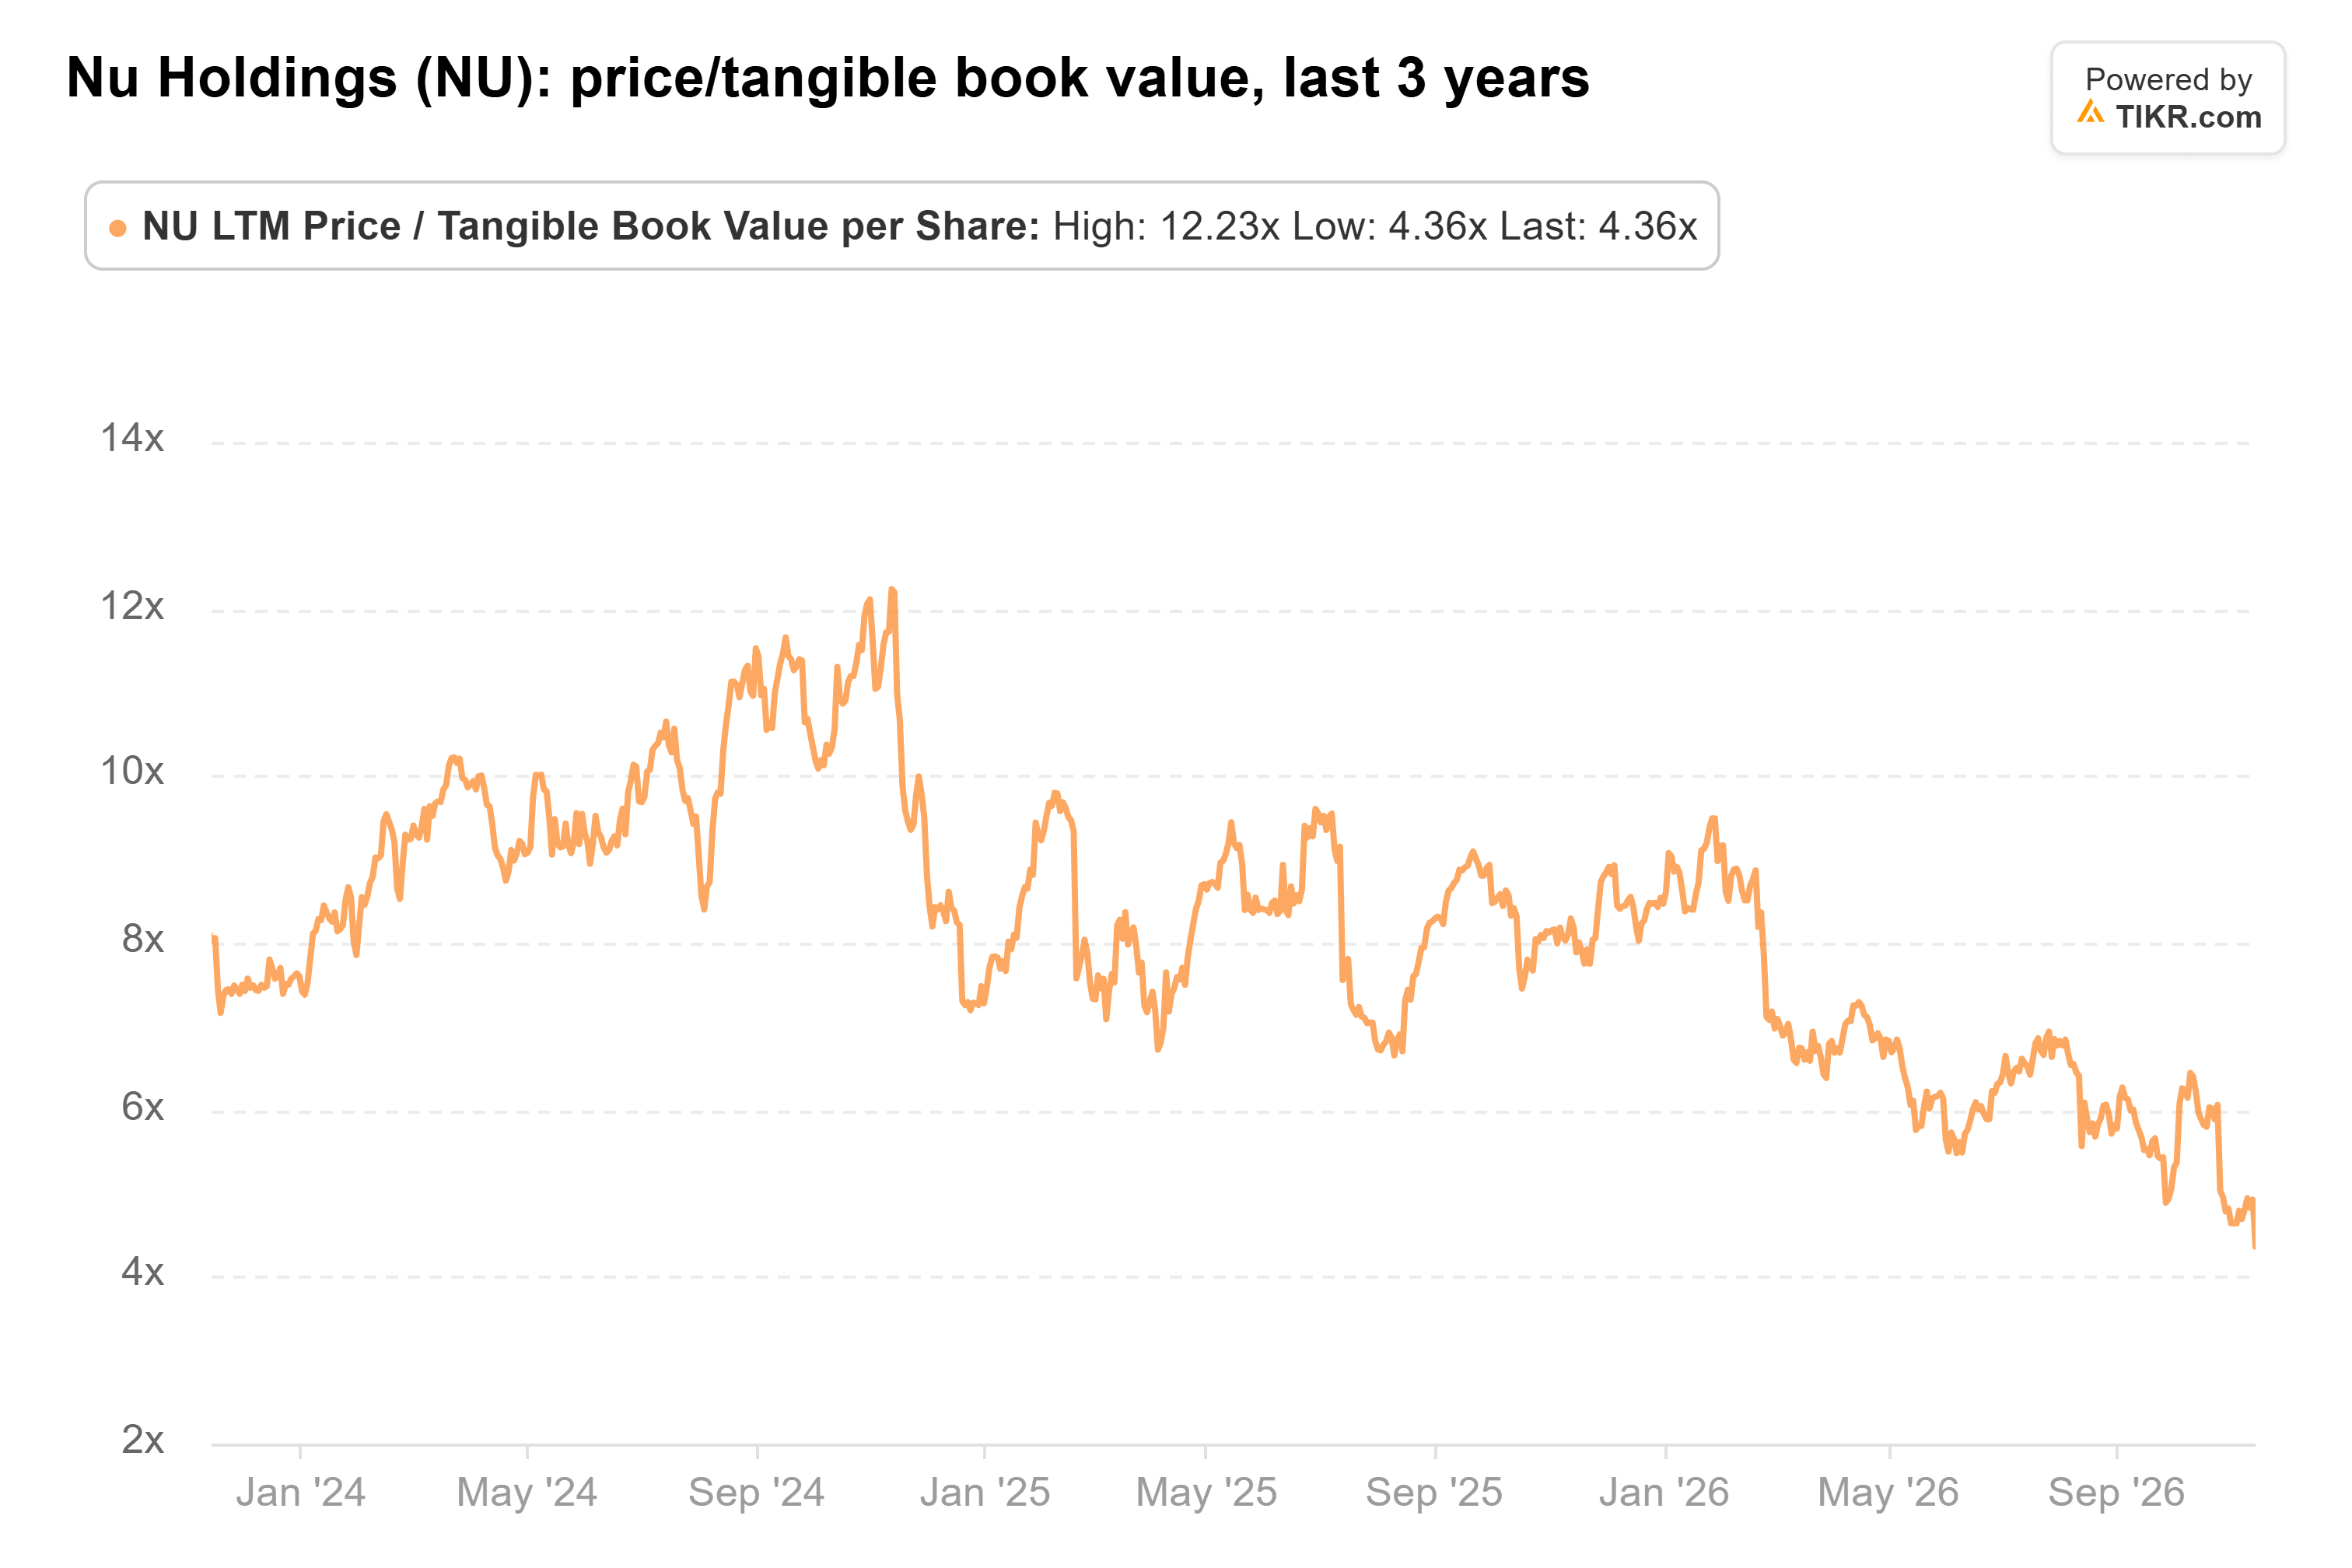
At today’s price it’s about 5x, still well below that average. The way I see it, that’s too cheap for a bank that grew its profit 31% while earning a 32% ROE.
The risk is the Brazilian consumer. Bradesco’s management says household debt is holding back spending, and a downturn would hit Nu’s riskier loans first. Nu’s fourth-quarter report early next year will show whether credit costs stay covered.
So what is Nu Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nu Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!