Key Takeaways
- AST SpaceMobile (ASTS) traded at $35.36 on November 11, approximately 73% below its May closing high, while Cantor Fitzgerald’s $90 price target implied roughly 155% upside.
- Cantor Fitzgerald reiterated its Overweight rating ahead of third-quarter earnings, citing telecommunications partnerships, growing government demand, and improving launch capacity.
- AST SpaceMobile reported $42.3 million in third-quarter revenue and pushed its target of approximately 45 BlueBird satellites in orbit to mid-2027, raising concerns about commercialization delays.
- The stock traded near 23x forward sales on November 10, below its five-year average of 60x, but lower revenue forecasts and rising capital requirements complicate the bullish case.
What Happened?
AST SpaceMobile (ASTS) has fallen sharply from its May highs, but Cantor Fitzgerald continues to see substantial upside in the satellite communications company.
On November 9, Cantor Fitzgerald analyst Colin Canfield reiterated his Overweight rating and $90 price target ahead of the company’s third-quarter earnings release.
Canfield remained “cautiously optimistic,” citing telecommunications partner support, accelerating government demand, and improving satellite launch supply chains.
However, the company’s latest results highlighted significant execution challenges.
AST SpaceMobile reported third-quarter revenue of $42.3 million, below the approximately $46 million analysts expected, while pushing its target of roughly 45 BlueBird satellites in orbit to mid-2027.
The milestone had already shifted from the end of 2026 to early 2027. BlueBird satellites 14, 15, and 16 were also awaiting confirmation of their SpaceX launch date.
Meanwhile, AST SpaceMobile entered an agreement valued at more than $1.3 billion with Firefly Aerospace for engines and support for its Blacklift rocket program, with initial launches targeted for late 2028.
During the earnings call, President Scott Wisniewski said the company expected “several hundred million dollars of incremental CapEx in 2027 associated with Blacklift.”
The company also completed a $1.15 billion convertible-note transaction in July, highlighting substantial financing requirements and potential shareholder dilution.
Despite these challenges, AST SpaceMobile ended September with approximately $3.2 billion in cash, cash equivalents, and restricted cash.
It also secured a U.S. Space Force contract representing approximately $100 million in revenue and announced roughly $1 billion in non-dilutive funding for a Japanese satellite initiative involving Rakuten.
Management maintained its 2026 revenue guidance of $150 million to $200 million, supporting its longer-term commercialization plans.
Is AST SpaceMobile Stock Undervalued or Overvalued?
AST SpaceMobile offers substantial upside potential, but its valuation remains demanding despite trading below its historical multiples.
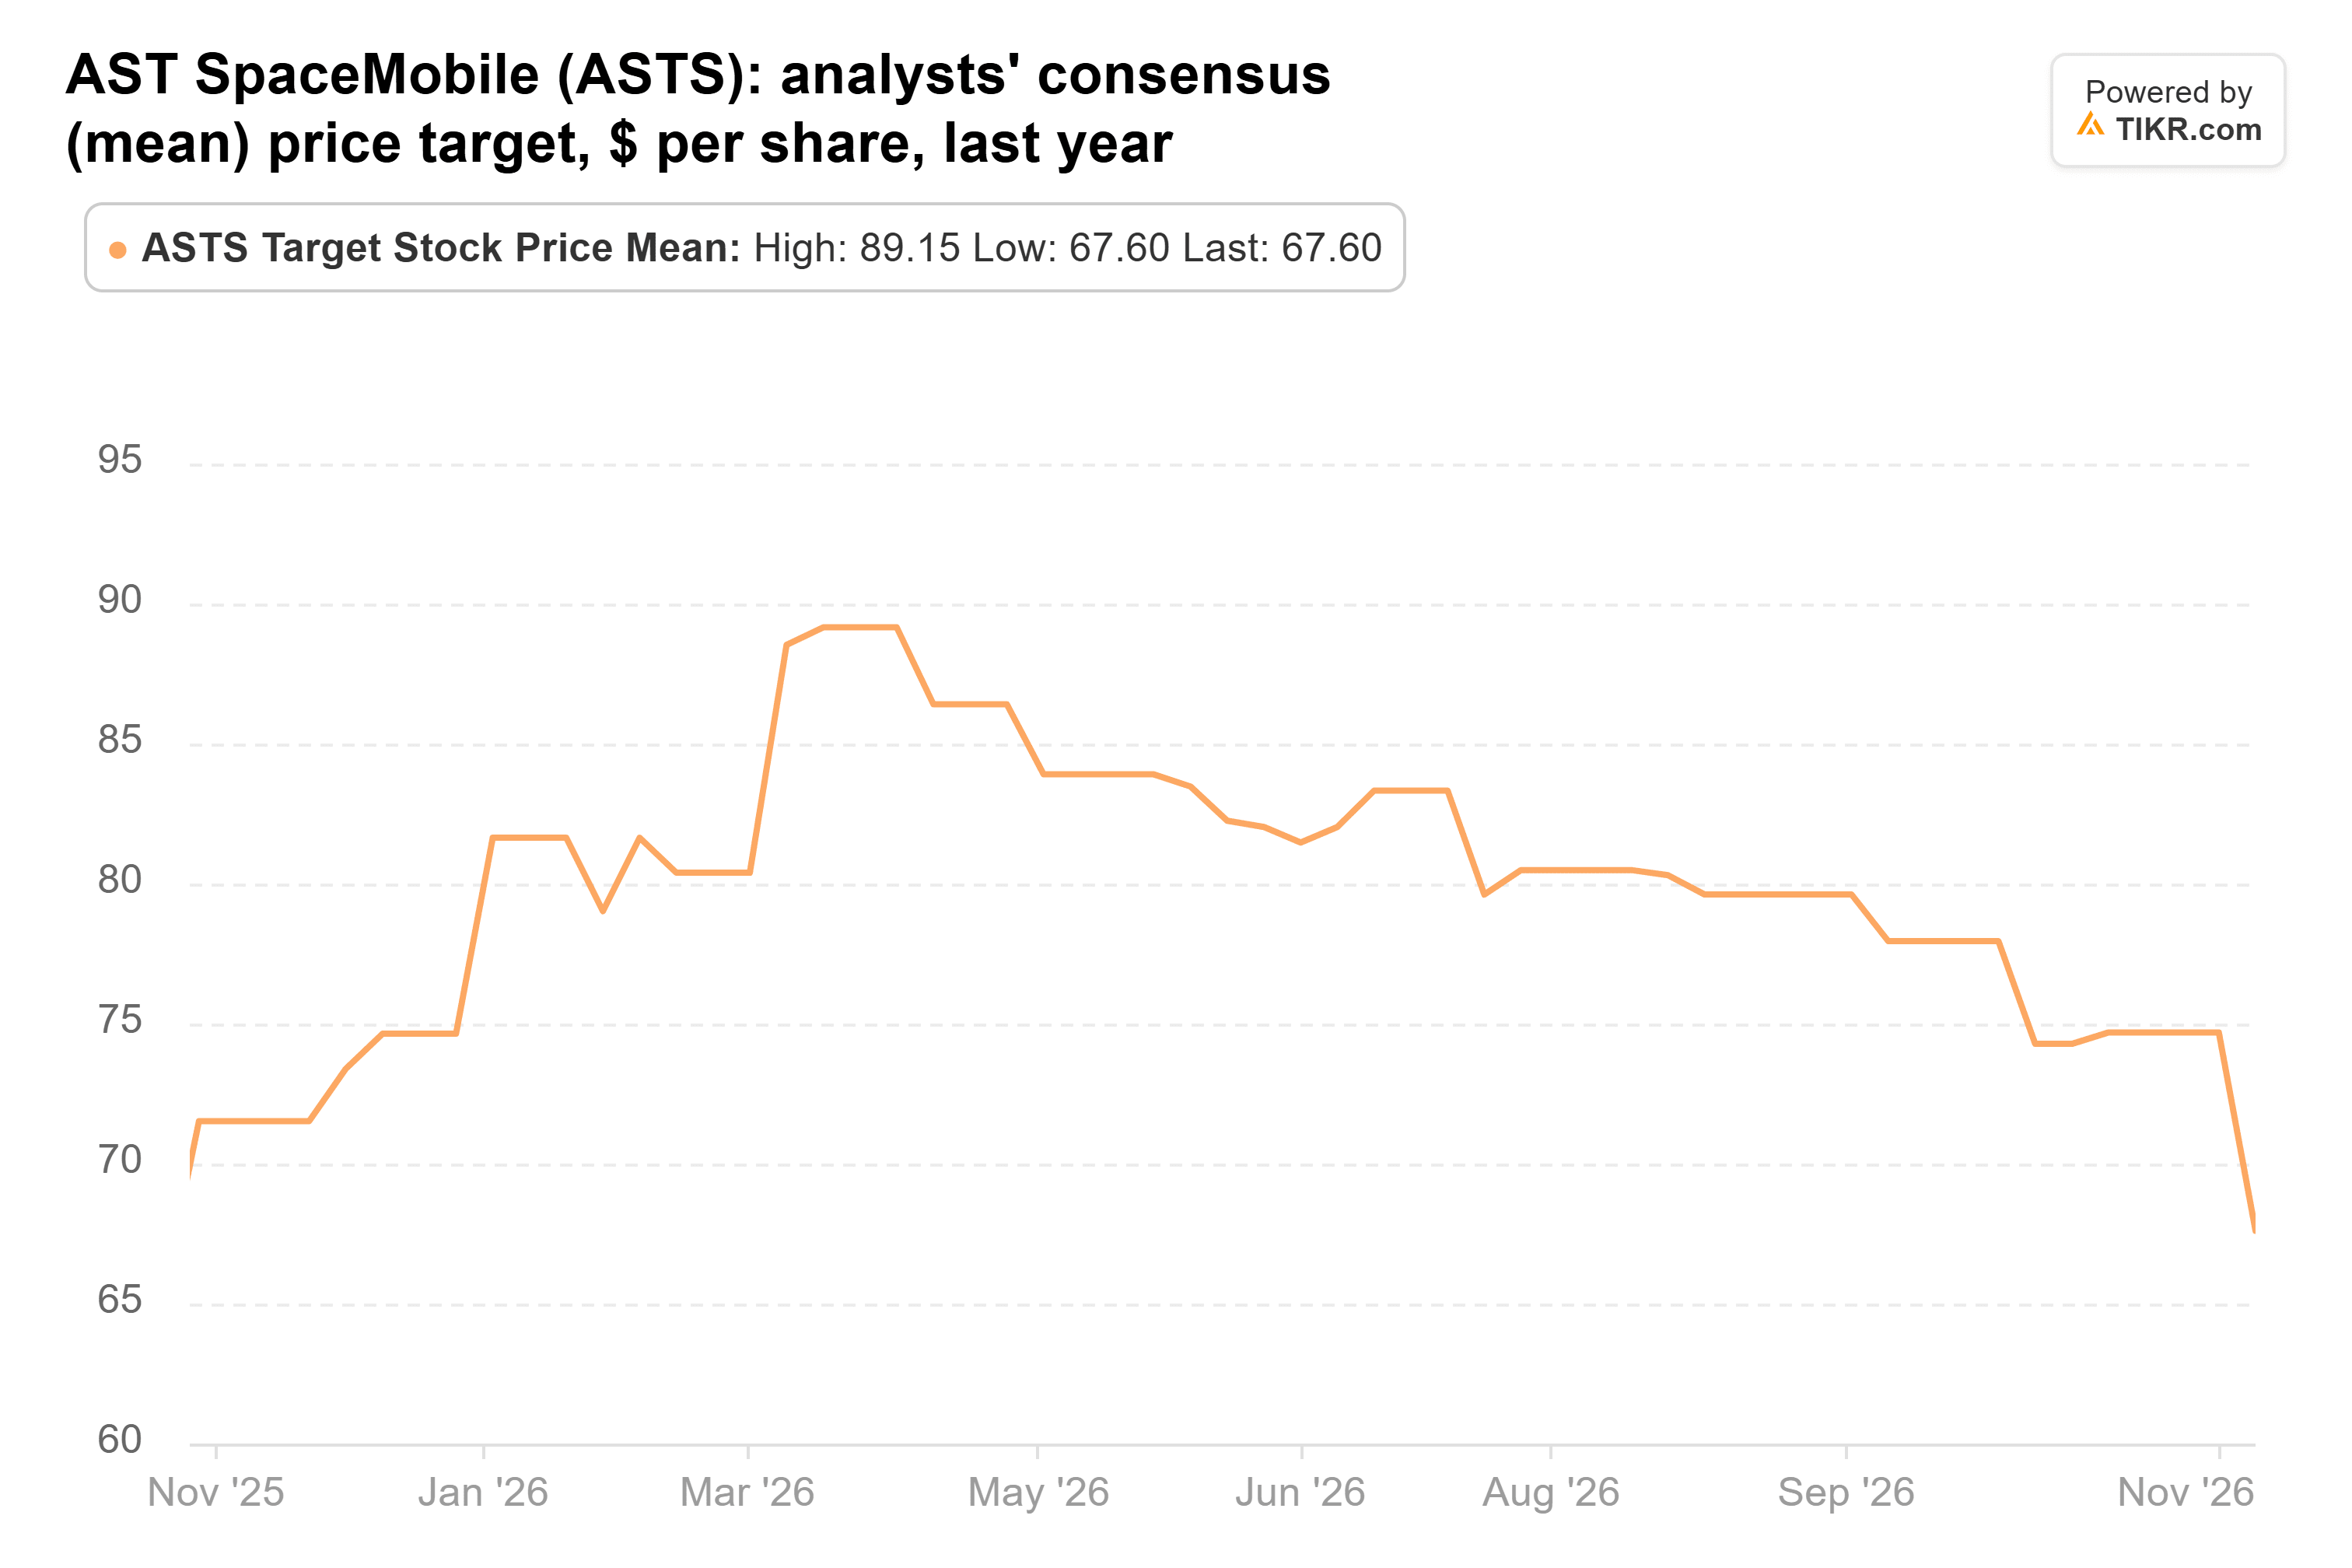
According to TIKR data from November 10, the average analyst price target stood near $68, down from approximately $89 in April. Cantor Fitzgerald’s $90 target was roughly 33% above consensus, while UBS, Bank of America, and B. Riley had lower targets ranging from $43 to $48 following earnings.
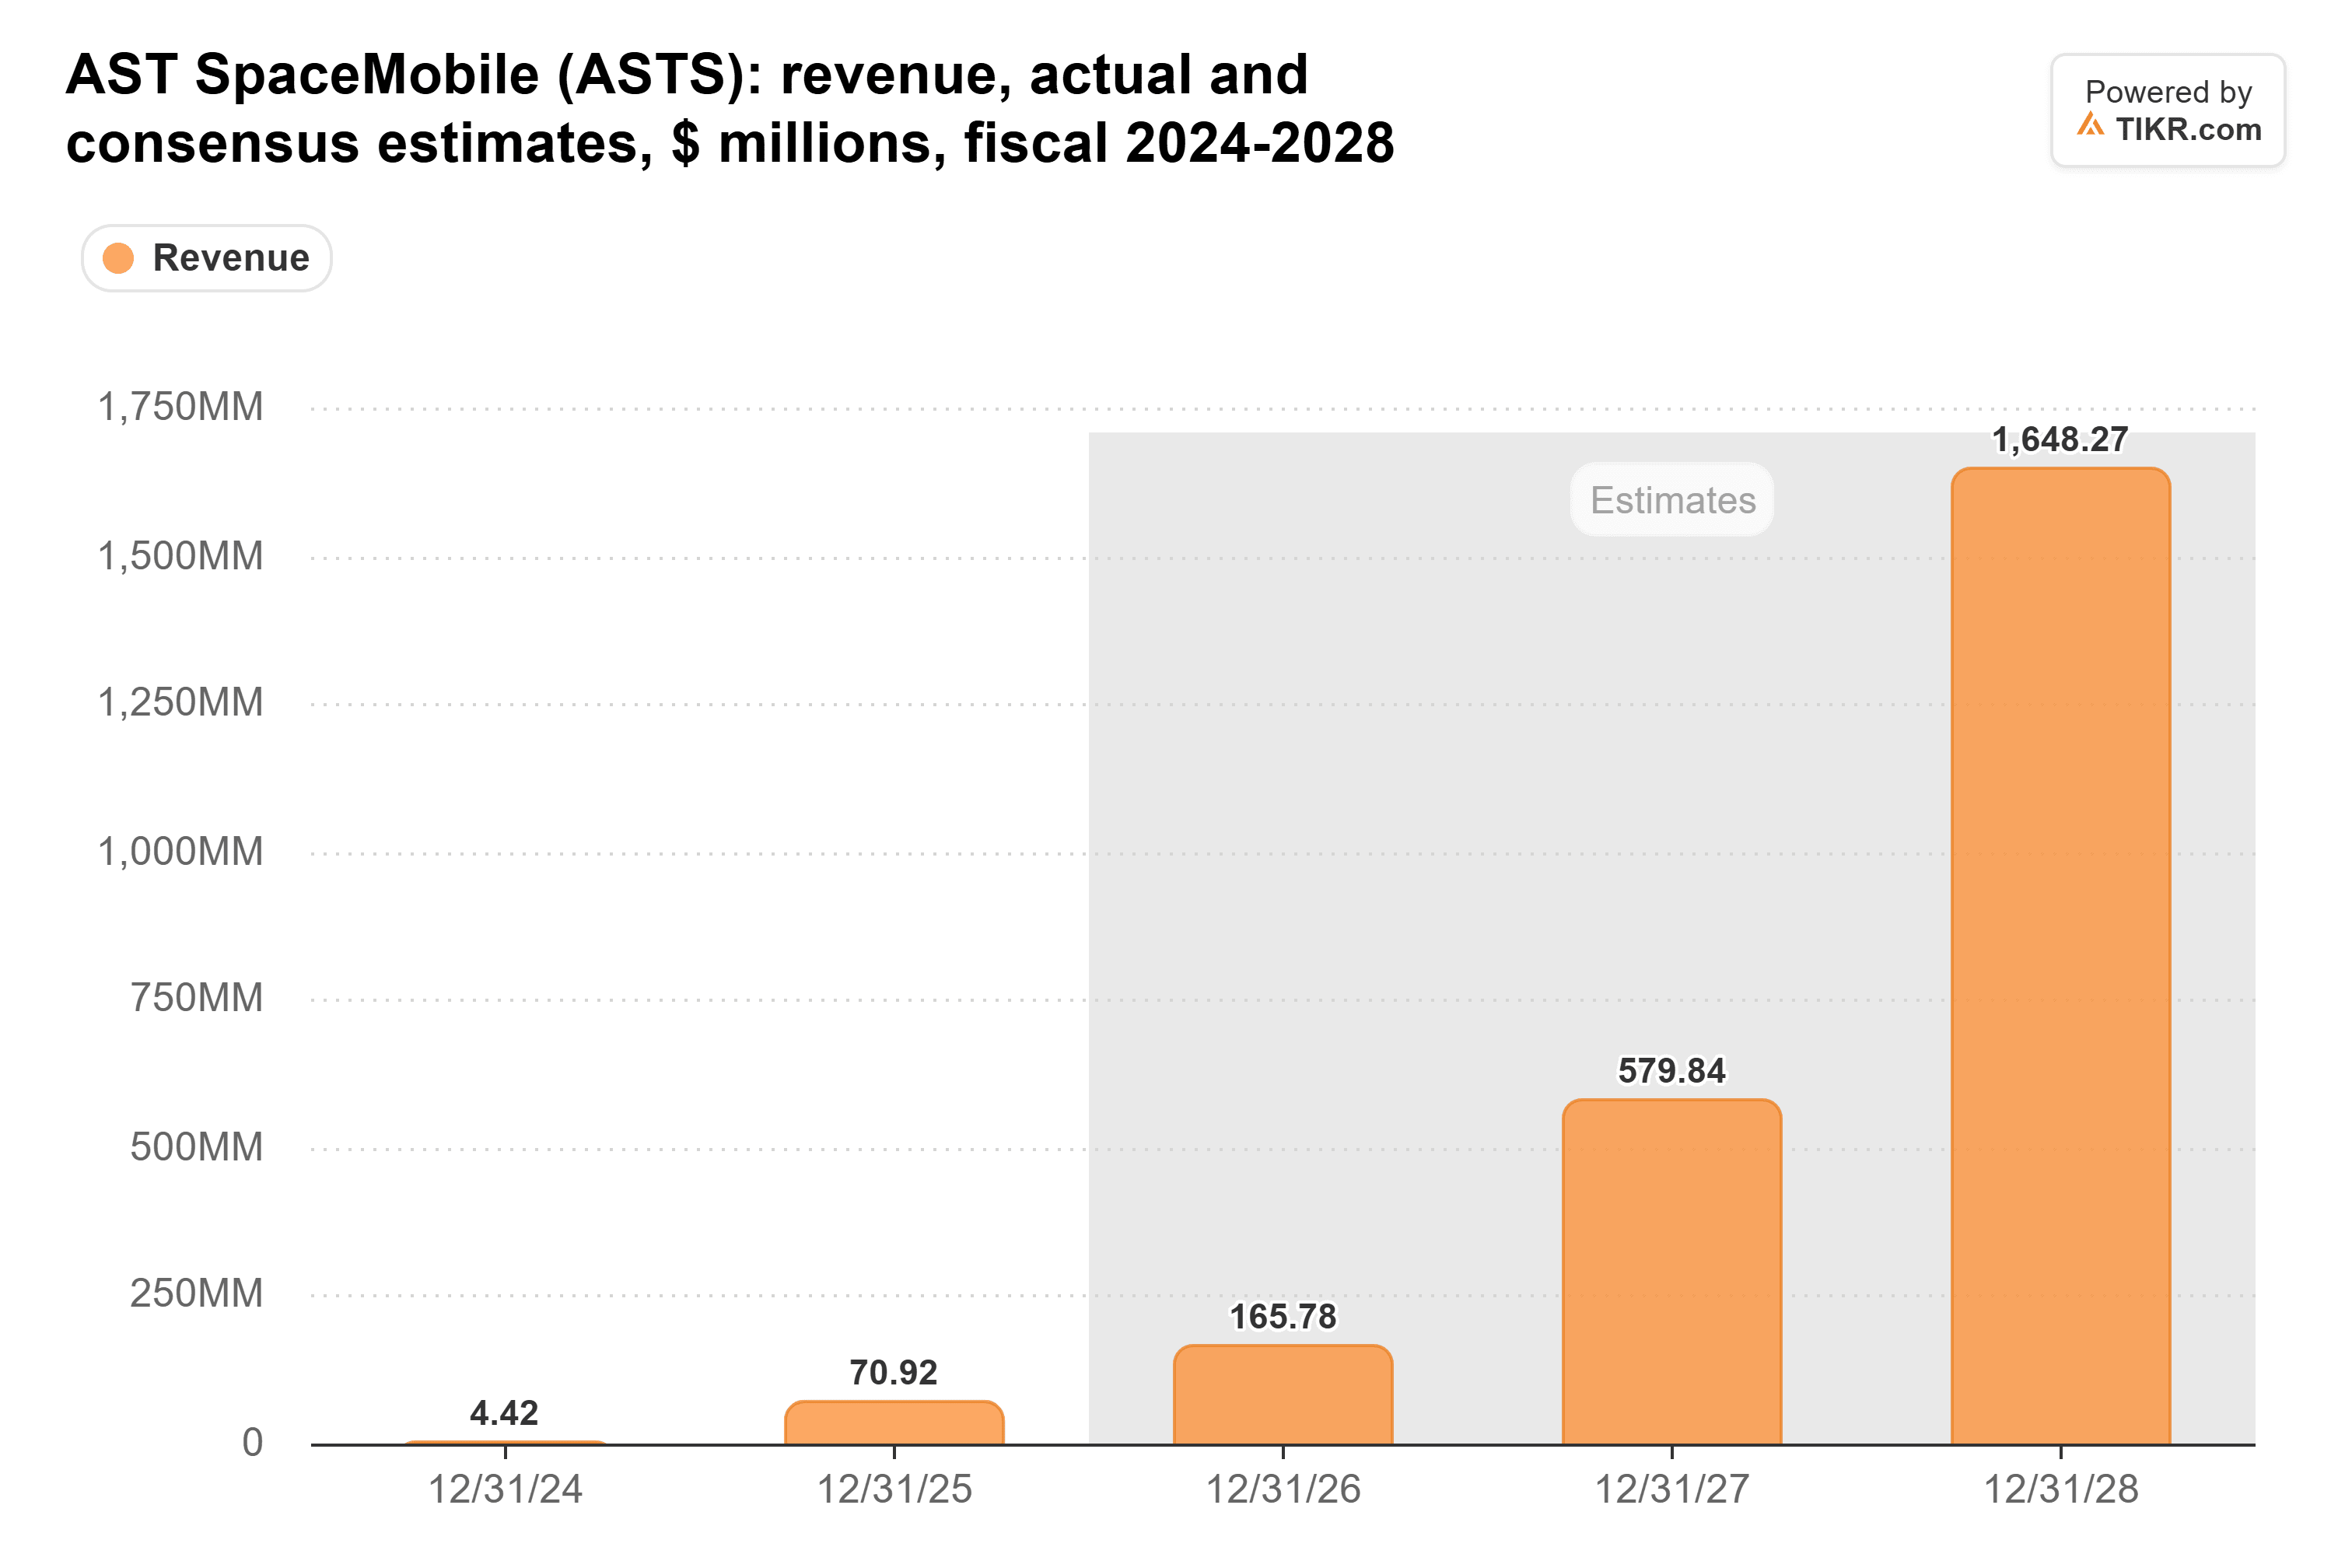
Analysts expected revenue to climb from approximately $166 million in 2026 to $580 million in 2027 and $1.65 billion in 2028, reflecting expectations for rapid commercialization.
However, the 2027 forecast had fallen from $748 million at the end of June, highlighting uncertainty surrounding satellite deployment timelines and the pace of commercial revenue growth.
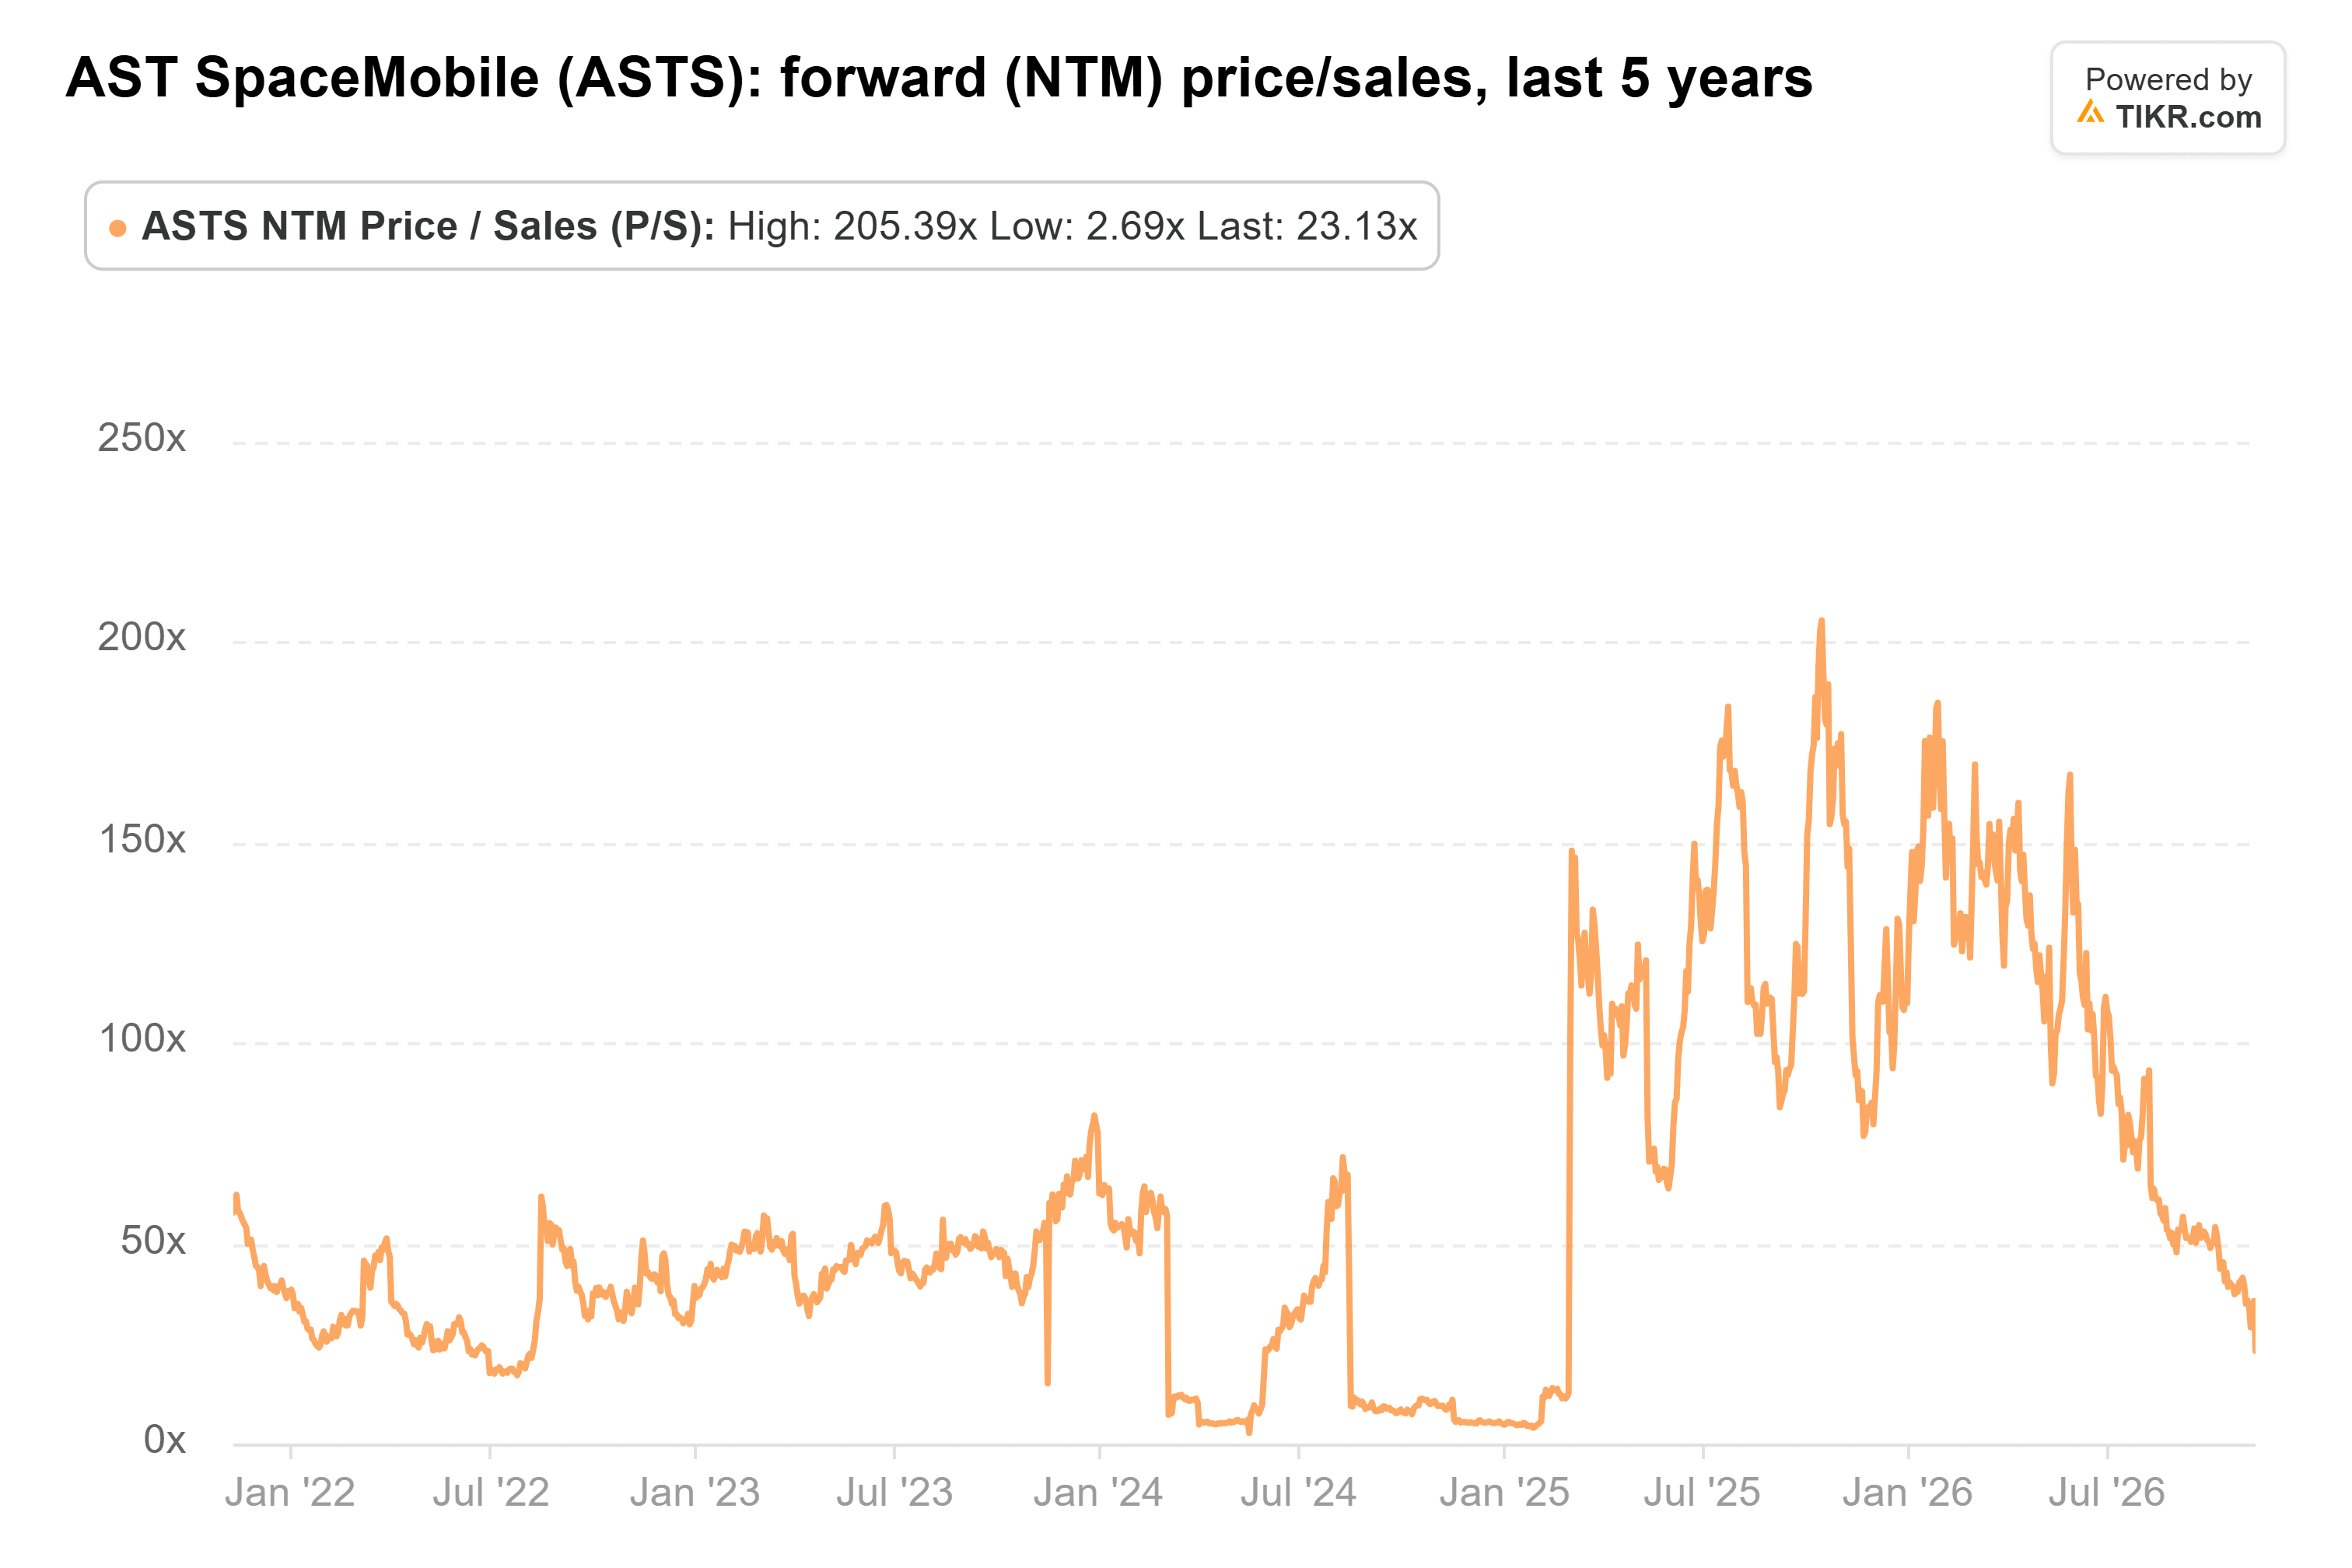
At approximately 23x forward sales on November 10, AST SpaceMobile traded below its five-year average of roughly 60x. Cantor Fitzgerald’s $90 target implied approximately 62x forward sales using the same revenue base, suggesting that the stock would need stronger sales growth or a return toward its historical valuation multiple to justify that price.
AST SpaceMobile’s valuation remains speculative despite trading below its historical sales multiple. Cantor Fitzgerald’s $90 target represents a bullish scenario that depends on successful satellite deployments, accelerating revenue growth, and sustained investor confidence.
Over the next 12 months, successful BlueBird launches and the activation of intermittent U.S. service could strengthen the investment case. However, additional delays, rising capital requirements, and weaker-than-expected revenue growth could limit the stock’s upside.
So what is AST SpaceMobile stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AST SpaceMobile could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value AST SpaceMobile for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!