Key Takeaways
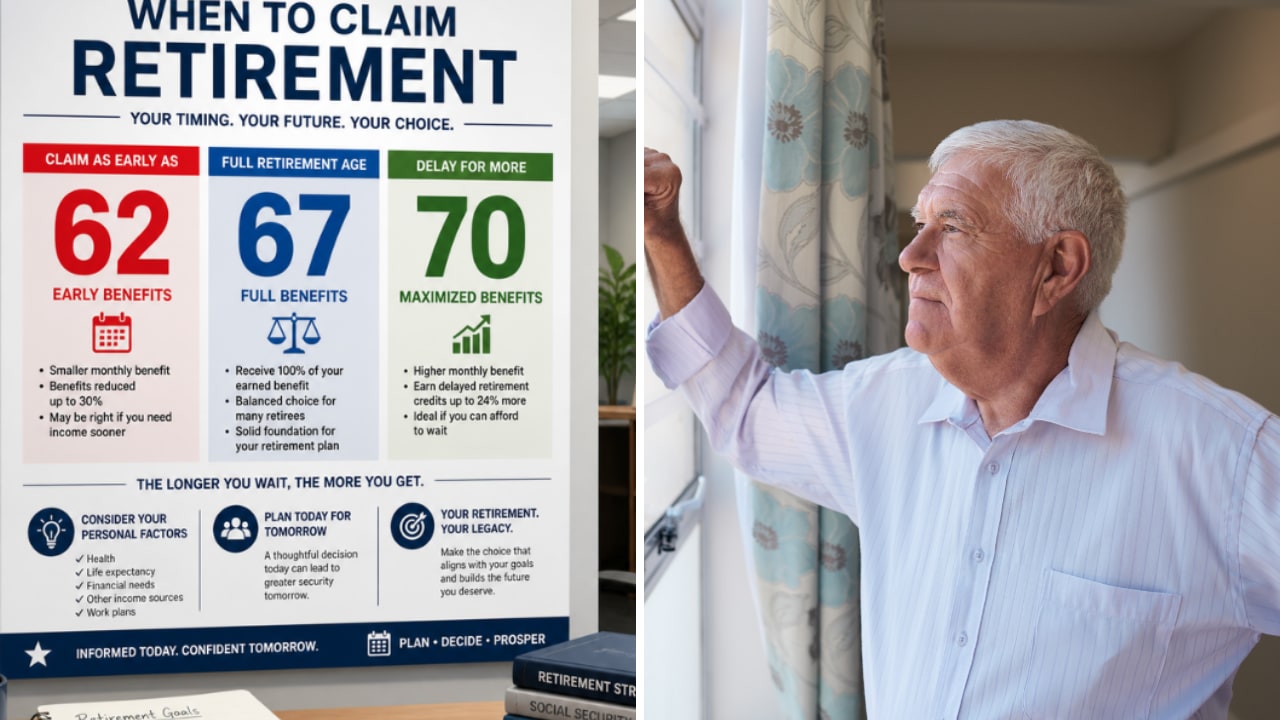
- A 58-year-old caller on Jill on Money who hopes to retire at 62 expects $2,400 a month from Social Security at his full retirement age of 67.
- Claiming at 62 would cut that check 30% for life, to $1,680 a month, or $8,640 less a year.
- Paying himself the full $2,400 from savings from 62 to 67 takes $144,000. His $280,000 in cash covers that nearly twice, so waiting is well within his reach.
- Waiting gives up $100,800 in early checks, which the bigger check earns back by about age 79. Working to 65 would shrink the bridge to $57,600.
If you want to stop working at 62 but hold out for your full Social Security check at 67, the five years in between have a price. The good news is that the price is easy to work out, and one caller on this week’s episode of Jill on Money may already have it saved.
A 58-year-old with his eye on 62
The caller is 58, married, and earns just over $200,000 a year. He has $750,000 in pre-tax 401(k)s and IRAs and $280,000 in cash he’s built up over the years. He also has $377,000 in a money market account from selling a Florida condo this past June. He puts the household’s spending at $5,000 to $6,000 a month.
He told Jill Schlesinger he’s always hoped to retire somewhere around 62, though he could see himself working to 65. She asked what Social Security would pay him at full retirement age. He said about $2,400 a month, based on the figure he last looked up early last year.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Claiming at 62 costs 30% for life
For anyone born in 1960 or later, full retirement age is 67, so his is 67. He can start his benefit as early as 62, but claiming then cuts it 30%, and the cut lasts for life. On his $2,400, that means a $1,680 check, or $720 a month less, which comes to $8,640 a year.
So if he quits at 62, he can either take the smaller check right away or wait for the full one and live on savings until it starts. Schlesinger told him the wait is the hard part: “The challenge that you have is that the years between 62 and full retirement age, you would be forced to be spending down some of your savings.”
Five years of full checks take $144,000
To pay himself the full $2,400 a month from 62 to 67, he’d need 60 monthly checks of his own, or $144,000. He’d set that aside as a bridge, in a separate pot, until Social Security takes over.
If he claimed at 62 instead, he’d get 60 checks of $1,680 over those same five years, or $100,800. That’s what he gives up by waiting. From 67 on, he gets it back $720 a month at a time. Divide $100,800 by $720 and it takes 140 months, just under 12 years, so he comes out ahead by waiting if he lives past about 79.
And the $144,000 only replaces the Social Security check. With spending of $5,000 to $6,000 a month, the rest of the budget comes out of his savings from 62 on, whichever way he claims.
His cash already covers the bridge
His $280,000 in cash covers the $144,000 nearly twice, without touching the condo money or his retirement accounts. Paying for the bridge from cash has another plus: that money has already been taxed, while the $750,000 in his 401(k)s and IRAs hasn’t, as Schlesinger pointed out.
If I were him, I’d wall off the $144,000 and wait for the full check. Living past 79 is a reasonable bet for a 58-year-old who calls himself healthy, and the extra $720 a month keeps coming for as long as he does.
Working to 65 shrinks the bridge to $57,600
Schlesinger’s own preference was for him to keep working a few more years: “if you really want to call it quits at 62, the plan is not quite as good as working till 65.” If he retires at 65 and claims at 67, the bridge shrinks to 24 checks of $2,400, or $57,600, and he gets three more years of saving on top. She also pointed out that 65 is when he’d get Medicare. Either way, his $2,400 is a figure he looked up early last year, so I’d get a fresh estimate from Social Security before setting aside a dollar.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!