Key Takeaways
- Netflix stock fell 15% in the past month after a soft fourth-quarter outlook and a cut to its 2026 ad revenue forecast, to about $2.7 billion from about $3 billion.
- Worries that members are watching less, and that their time is going to Alphabet’s YouTube, kept the pressure on, but churn improved in the third quarter.
- About half the drop matches the Nasdaq 100’s fall, and Evercore ISI put Spotify in Netflix’s place among its top large-cap picks while keeping its Buy on Netflix.
- At about half its five-year average multiple, Netflix looks like a buy unless January’s 2027 guidance shows members leaving.
Netflix (NFLX) stock is down 15% in the past month on a soft outlook, a smaller ad forecast and a run of reports that members are watching less. The worry is that much of that time is going to YouTube, owned by Alphabet (GOOG).
On the Nov. 2 episode of Prof G Markets, co-host Ed Elson put the fall in viewing time per member at 26% over three years. Then he turned on the stock: “I was looking at Netflix as a buy. I’m now thinking there’s more pain there.” On Nov. 17, Evercore ISI kept its Buy on Netflix but replaced it with Spotify (SPOT) as its third-ranked large-cap pick.
A soft guide and a smaller ad forecast
After the close on Oct. 20, Netflix reported third-quarter revenue up 12% to $12.9 billion, in line with its forecast. But it guided fourth-quarter revenue to $13.4 billion, below the $13.5 billion analysts expected. That forecast came with a 26.0% operating margin that includes about 120 basis points of layoff costs. The guide works out to 11.5% growth, down from 17.6% a year earlier.
Netflix also cut its 2026 ad revenue forecast to about $2.7 billion from about $3 billion, blaming a “slightly slower than expected rollout of some ad product capabilities.” Argus cut its target to $95 from $120, and Wolfe Research downgraded the stock to Hold on Oct. 22. Wells Fargo kept its Sell rating and $57 target.
TIKR tracks 51 analysts on Netflix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Netflix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Netflix’s Analyst Ratings
Members are paying more and watching less
Bloomberg reported on Oct. 25 that members open the app on fewer days a month, though there have been no mass cancellations. Pershing Square CEO Bill Ackman gave a reason on CNBC’s Squawk Pod on Nov. 3: hours have come down “because the mix of content is changing.” His verdict: “Netflix we think is an incredibly cheap stock.”
Netflix’s own figures back him up. Live programming takes just over 5% of this year’s content spending and about 1% of viewing hours. Yet live events accounted for six of Netflix’s 10 biggest sign-up days of the last five years. Churn also improved year over year in the third quarter, both globally and in the US, after US prices went up 8% to 13% in March.
Not all of it is Netflix’s problem
About half of Netflix’s drop matches the market’s: the Nasdaq 100 fell 7% over the same month. Alphabet fell further, 17%, even though its third-quarter revenue grew 25%. YouTube’s ad revenue rose 9% to $11.2 billion, slower than Netflix’s 12% (YouTube’s subscriptions aren’t in that figure), so YouTube isn’t pulling away on ad dollars. Meanwhile Spotify, Evercore’s new pick, grew revenue 16% last quarter and trades at 39x forward earnings, which shows investors will still pay up for faster growth.
Cheap, if January holds
Analysts still expect Netflix’s earnings to rise through 2028, though their 2027 estimate is down 4% in a year, to $3.77:
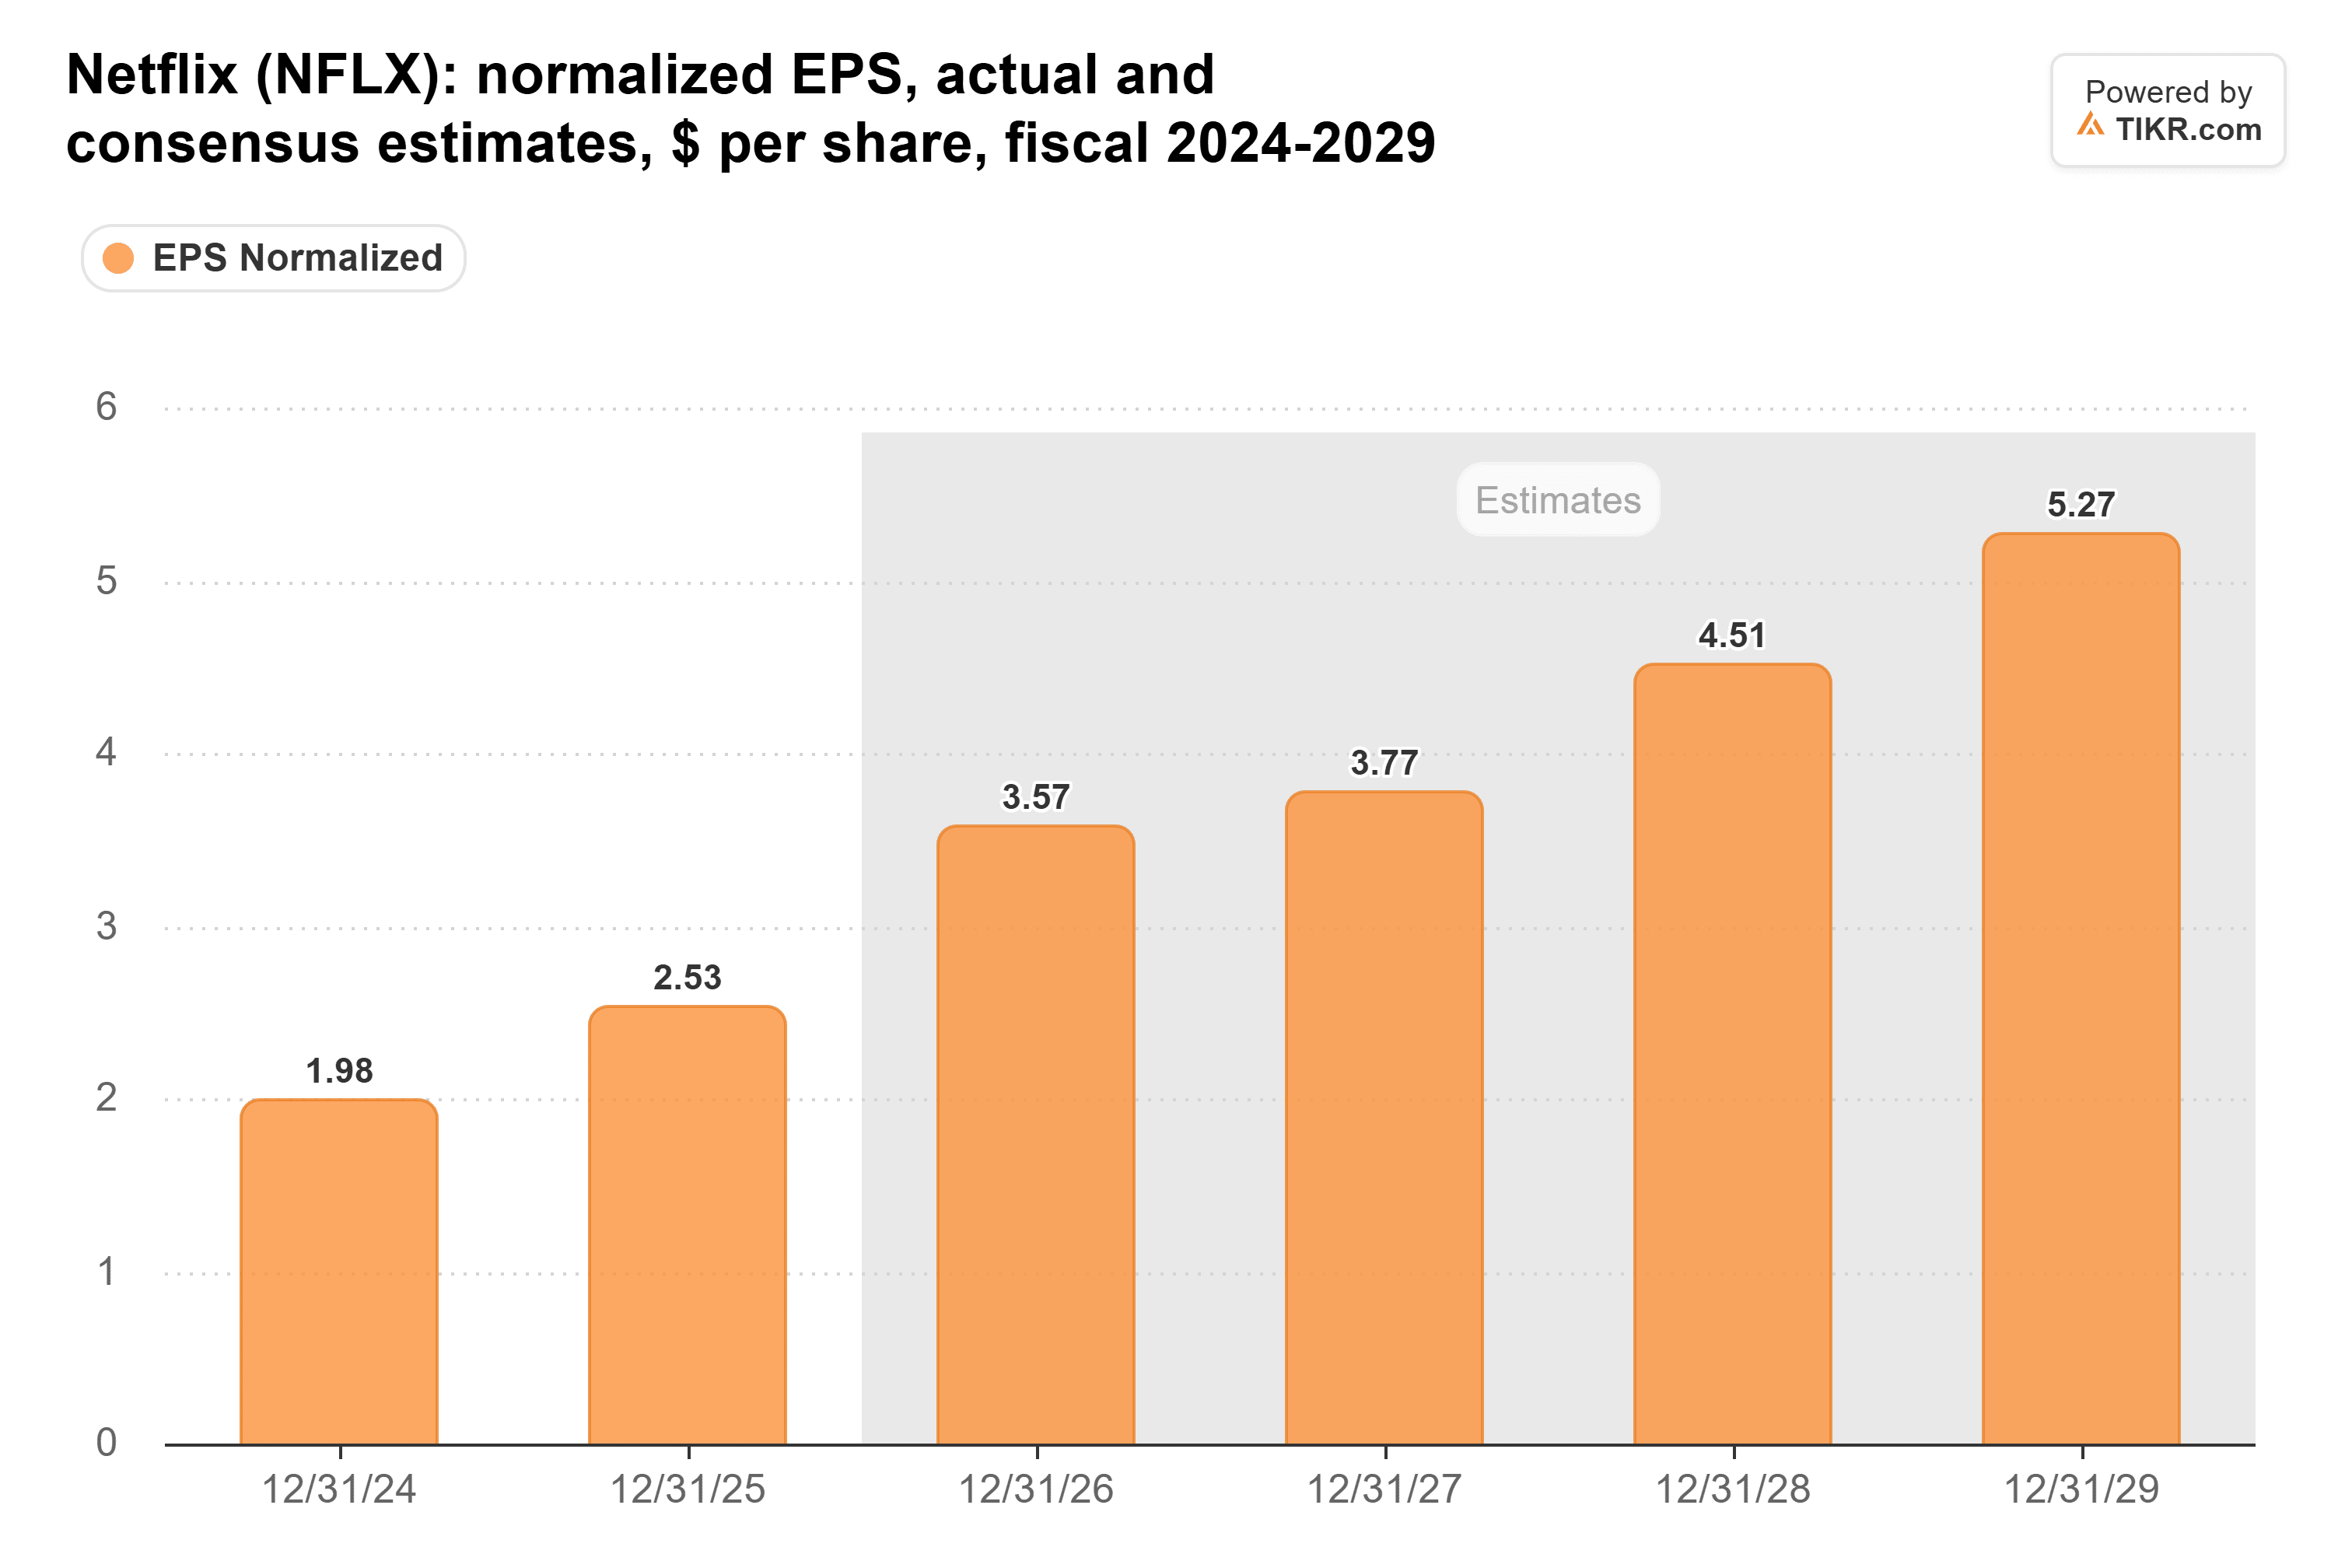
(2026 includes the $2.8 billion termination fee Netflix collected after it dropped its Warner Bros. Discovery bid.)
Yet the stock trades at 17x forward earnings, about half its five-year average of 32x:
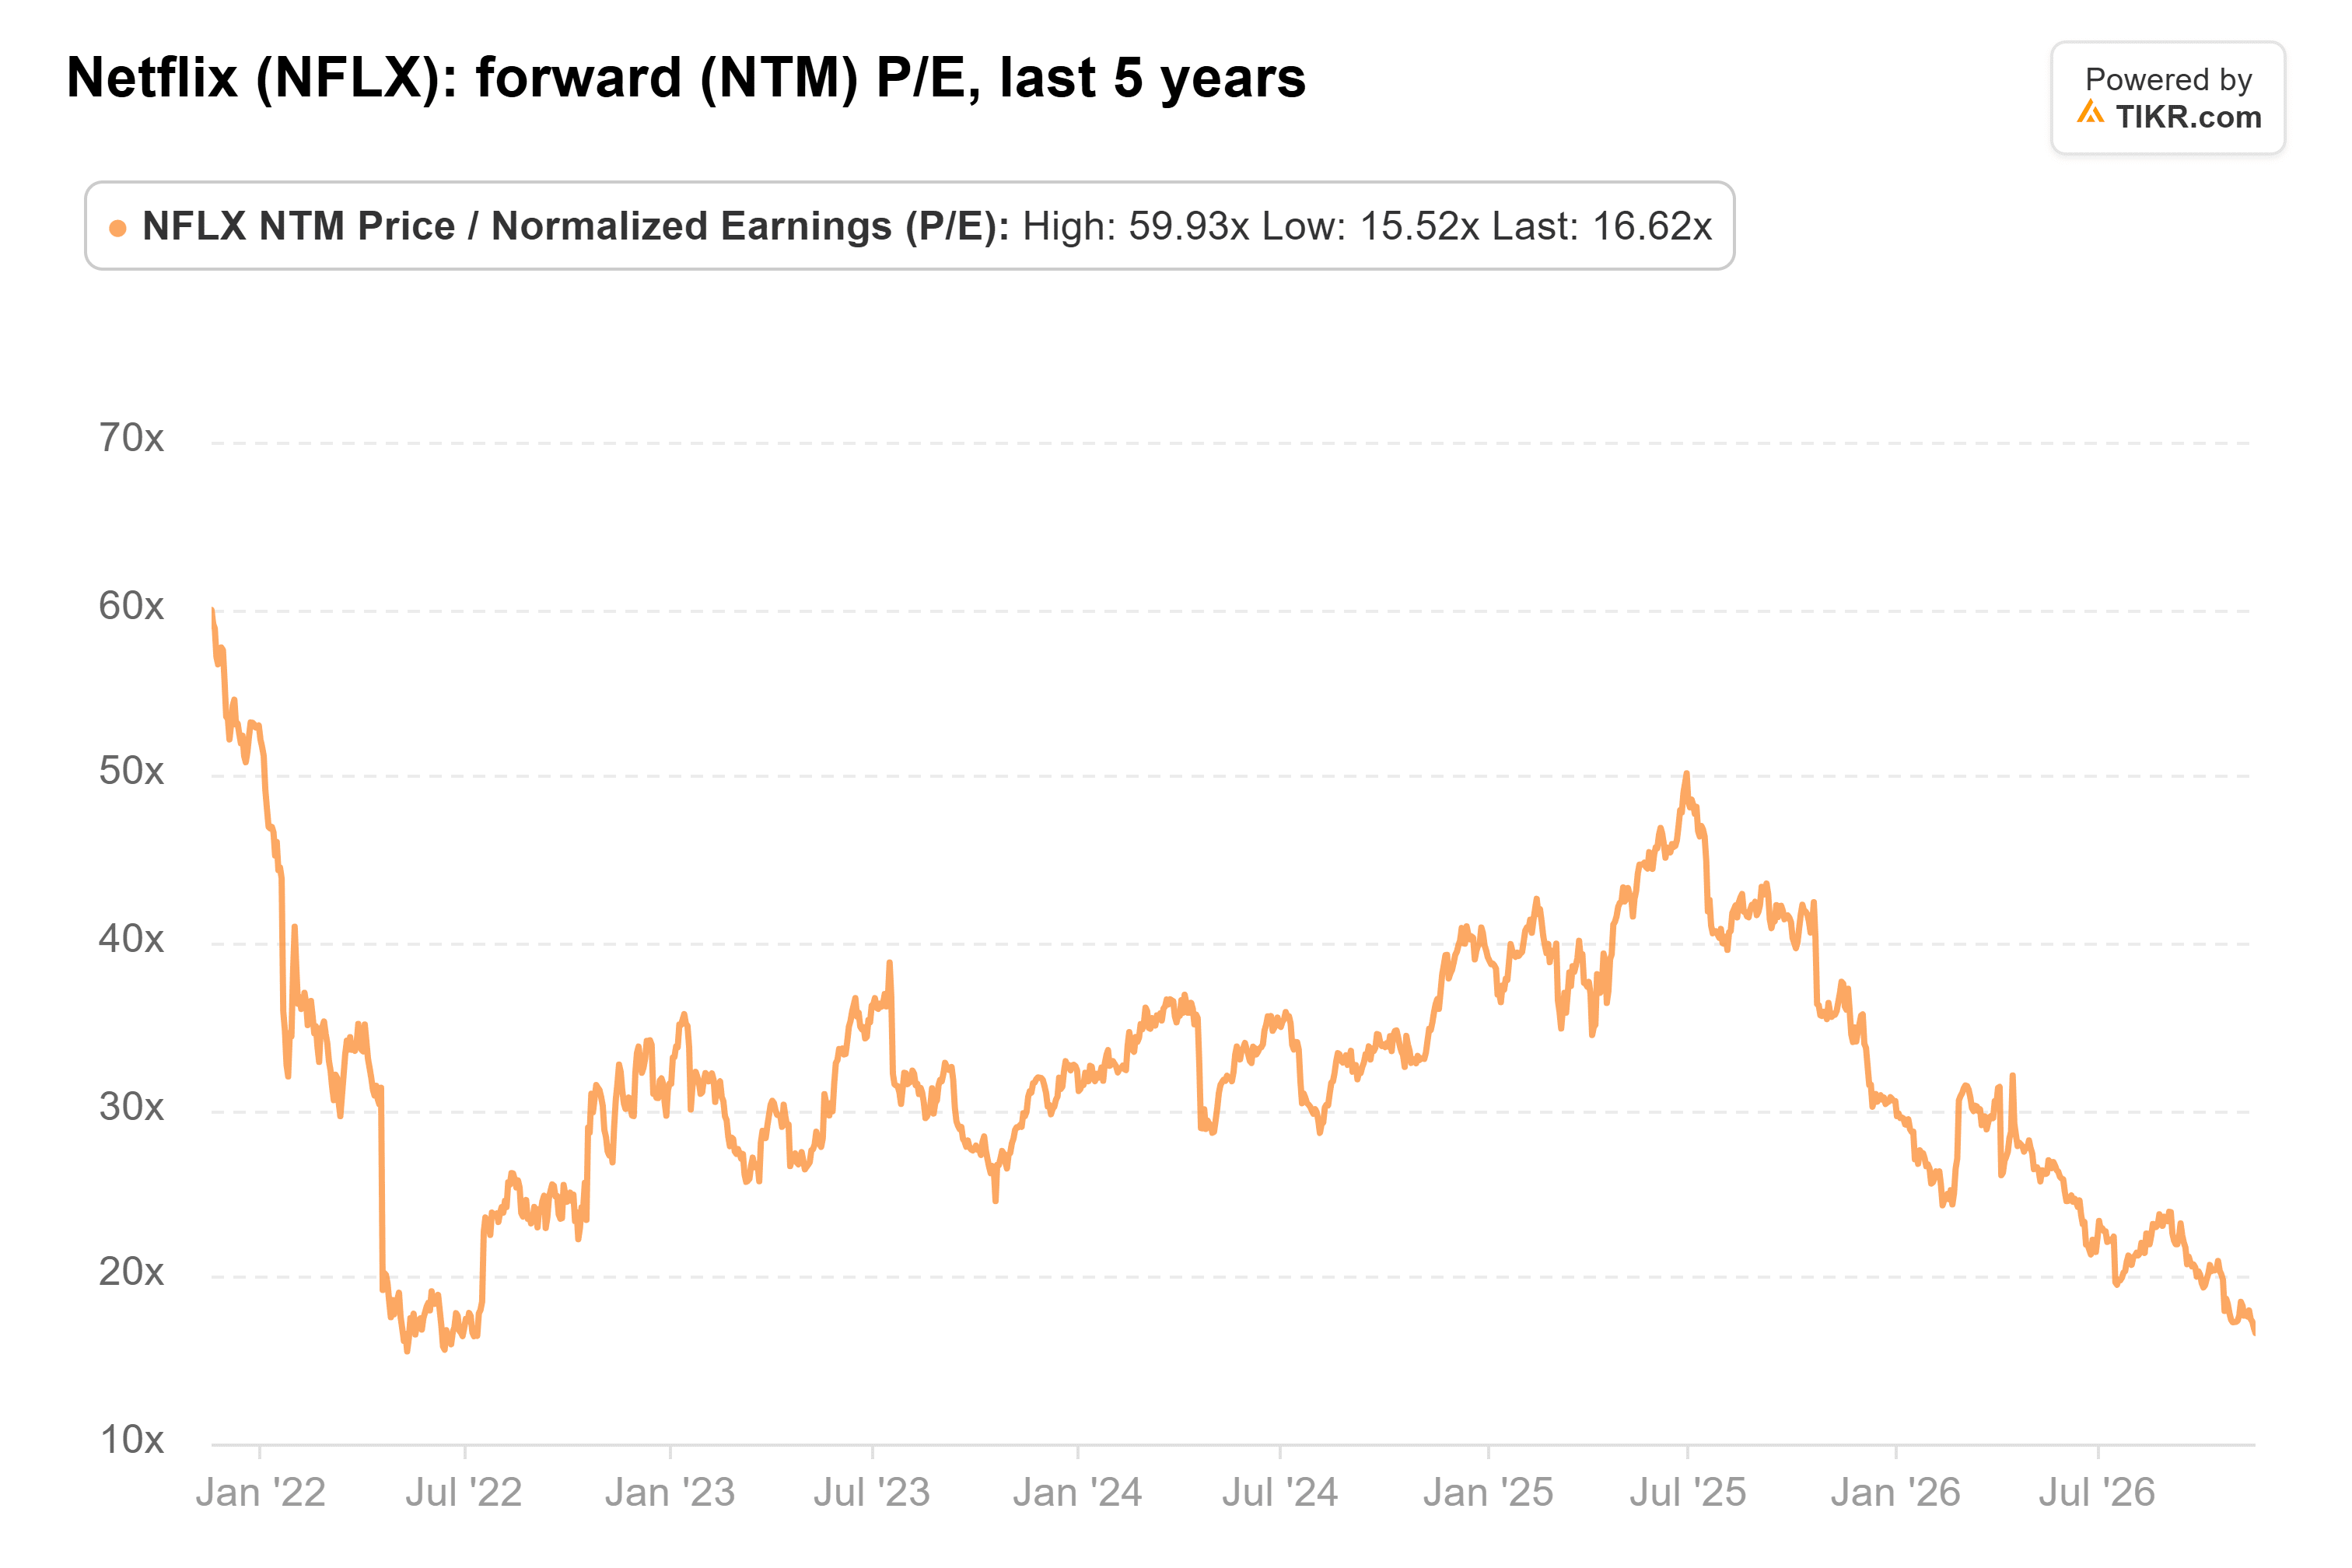
The $85 consensus target sits more than 40% above the last close.
Netflix’s fourth-quarter report in January will include 2027 guidance. Analysts expect 2027 revenue of $56.6 billion, up 10.8%, at a 33.3% operating margin. If the guide comes in at or above that and churn keeps improving, members are sticking around. Growth guided below 10% would mean the slowdown has further to run.
The way I see it, Netflix is priced as if members are heading for the exits, and they keep paying more. I’d load up at this price. Of course, if January’s guidance shows cancellations picking up, the low multiple will start to look deserved.
So what is Netflix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!