Key Takeaways
- Nebius shares fell about 16% after late third-party data centers pushed 2026 revenue to the low end of its $3.0 billion to $3.4 billion range.
- Third-quarter revenue rose 571% to $980.8 million, but about $325 million of it was one-time revenue from the asset-light partner model.
- Capex guidance jumped to about $27 billion for 2026 and $40 billion to $45 billion for 2027, which revived financing and dilution worries.
- The February report should show whether Microsoft’s New Jersey capacity arrived and whether ARR is on track to top $7 billion.
Nebius Group (NBIS) beat on revenue last Thursday and still lost about 16% of its value that session.
The outlook did the damage. Data centers that landlords are building for Nebius are running late, so some 2026 revenue now lands next year. Full-year sales should come in at the low end of the $3.0 billion to $3.4 billion range.
The timing stung. CoreWeave (CRWV) raised its 2026 revenue forecast to $13.0 billion to $13.3 billion on November 10. Nebius stock then jumped 15% the next day, right before its own report.
The biggest delay is in Vineland, New Jersey, at a third-party site serving Nebius’ contract with Microsoft (MSFT). Nebius now expects to deliver more than half of that capacity by year-end. The rest slips to the second quarter of 2027.
A beat with an asterisk
Third-quarter revenue hit $980.8 million, up 571% from $146.1 million a year earlier and 68% from the second quarter. That beat the $907.5 million consensus.
The headline needs one adjustment, though:
- About $325 million was one-time revenue from the first phase of its asset-light partner model.
- Operating income reached $50.4 million, against a $130.2 million loss a year earlier.
- The net loss from continuing operations narrowed to $37.5 million, or $0.13 per share.
Strip out the one-time piece and revenue was about $656 million. That’s still roughly 12% above the second quarter…
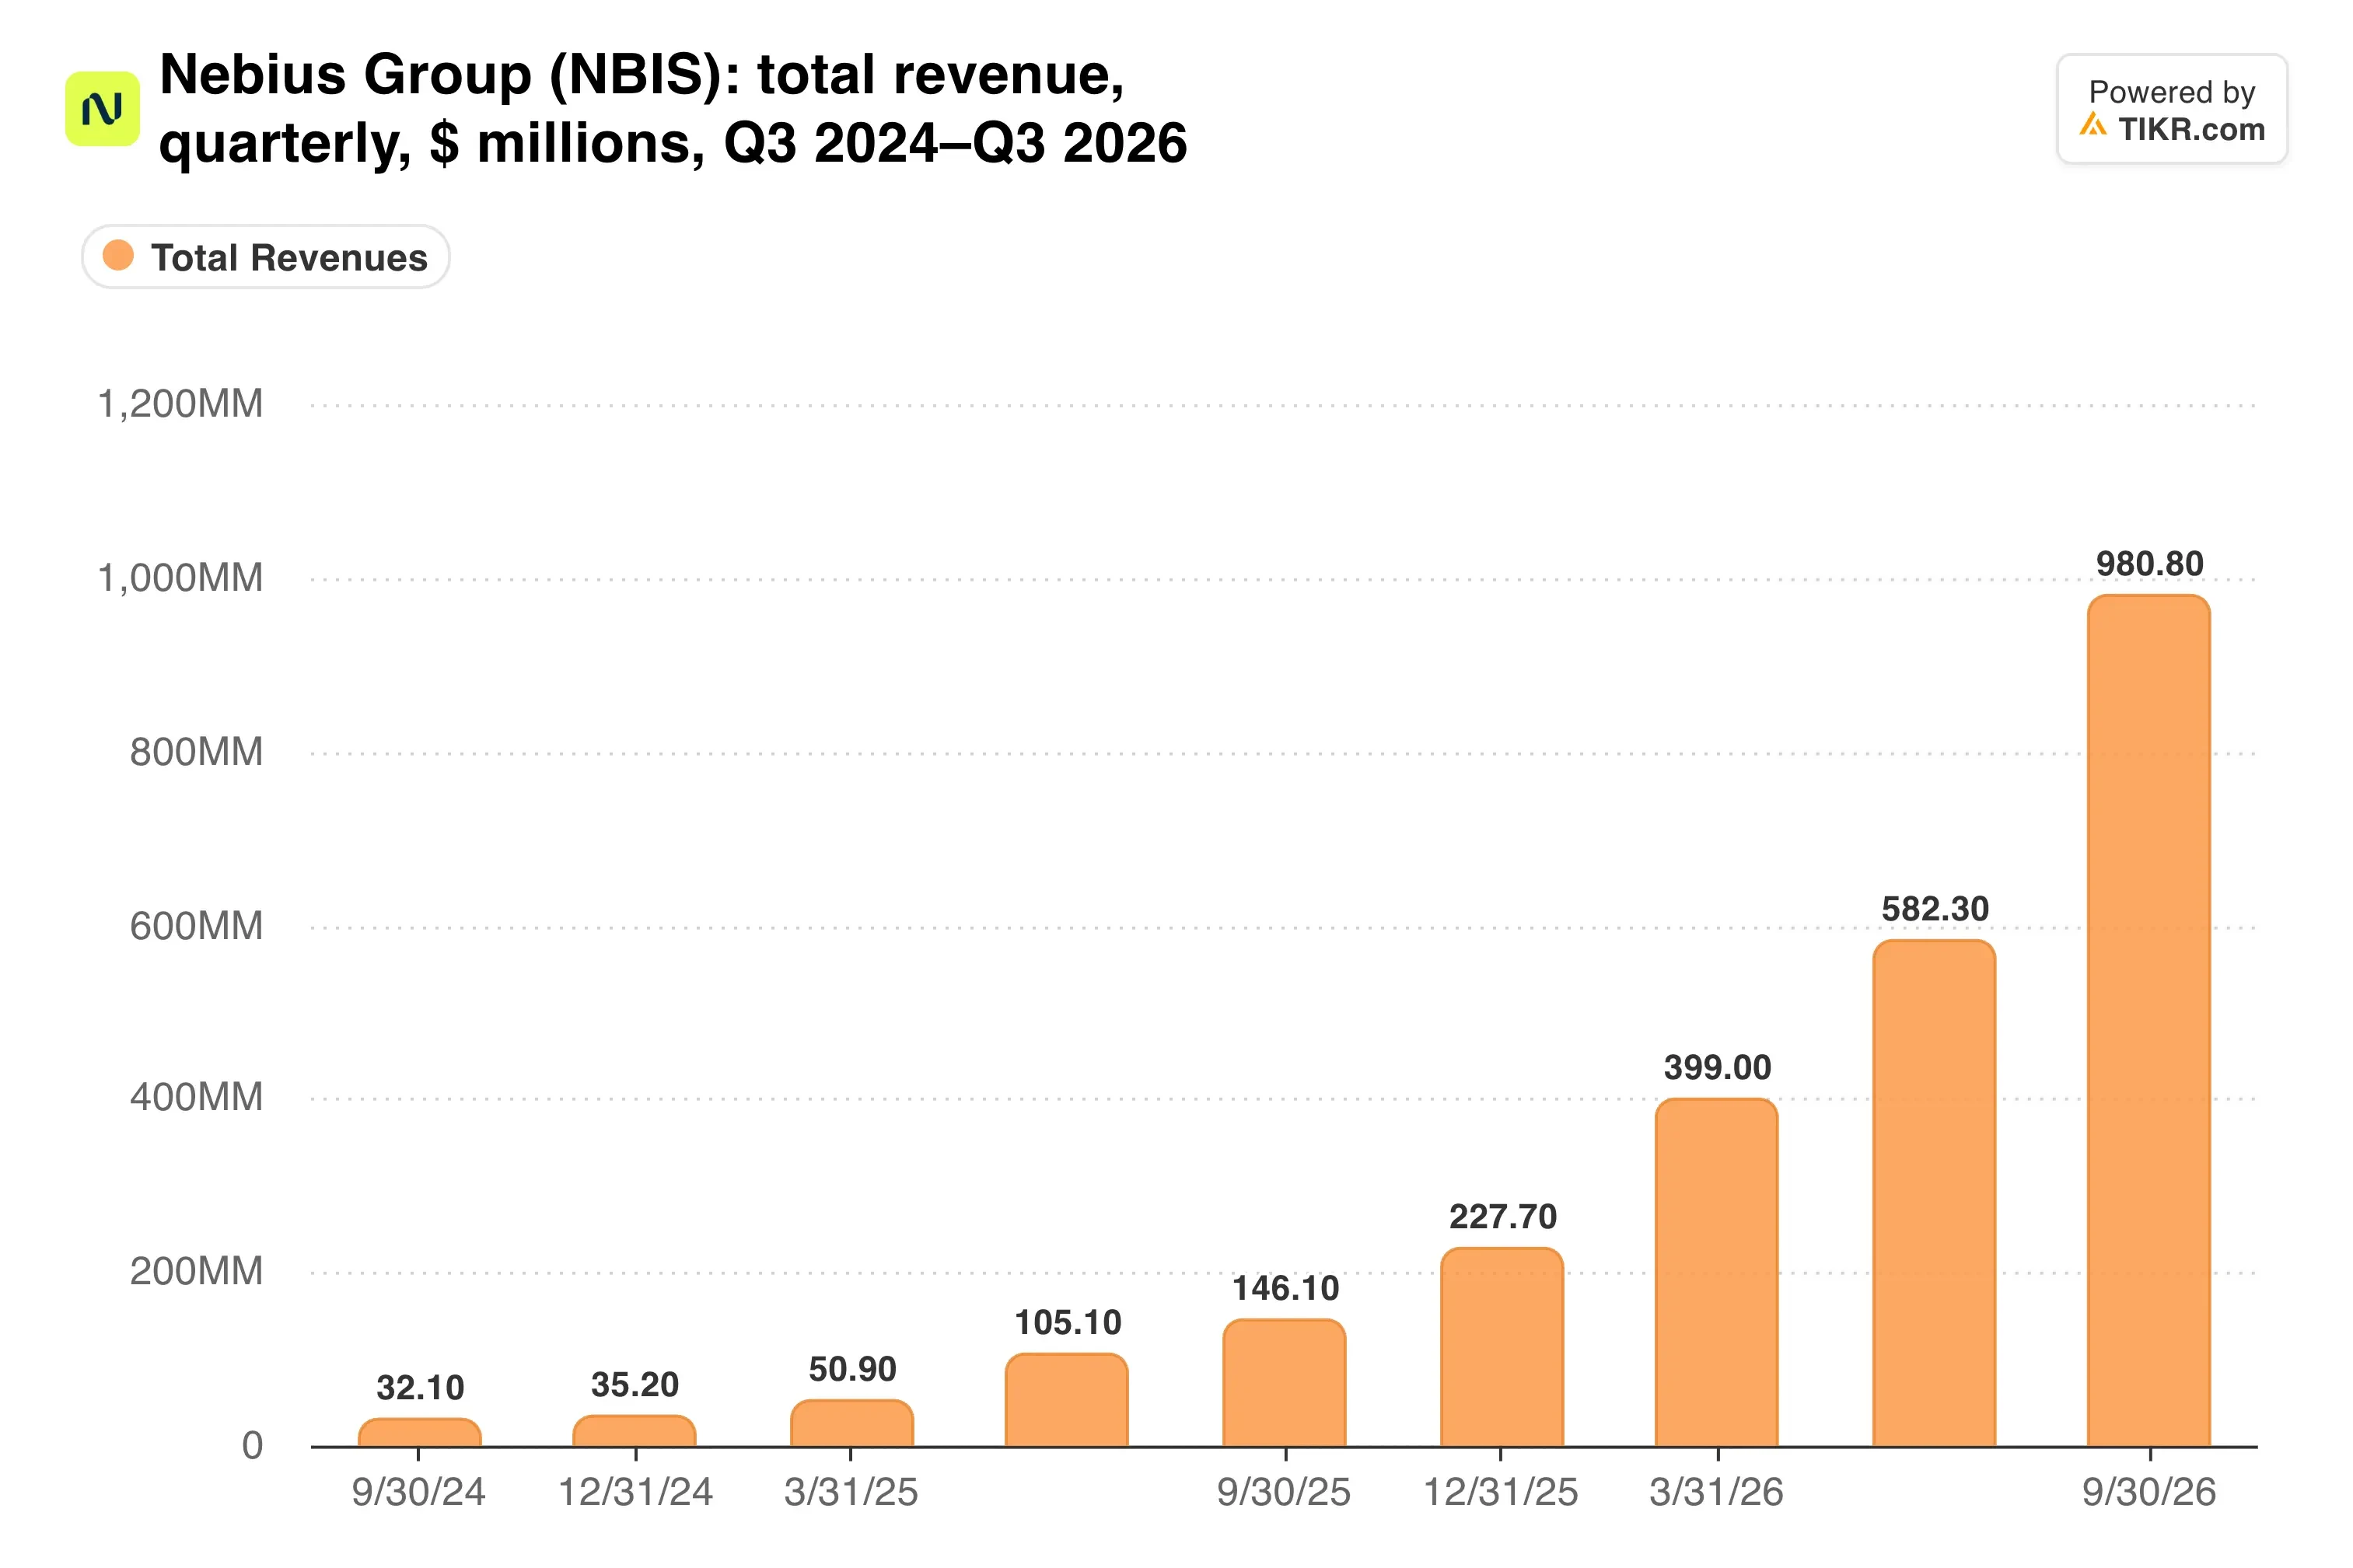
The underlying trend held up. From here, though, the pace depends mostly on when buildings get power.
Customers are paying up front
This is the part bulls should focus on. Prices on third-quarter deals rose more than 20% per GPU-hour from the second quarter, and customers committed over $12 billion in contract value since the quarter began.
Prepayments are the bigger shift. On deals signed in the quarter, they covered more than 100% of the related capex, up from 50% to 60% in the second quarter. So customers are now funding much of the build themselves.
Pricing like that should show up in profitability. Does it?
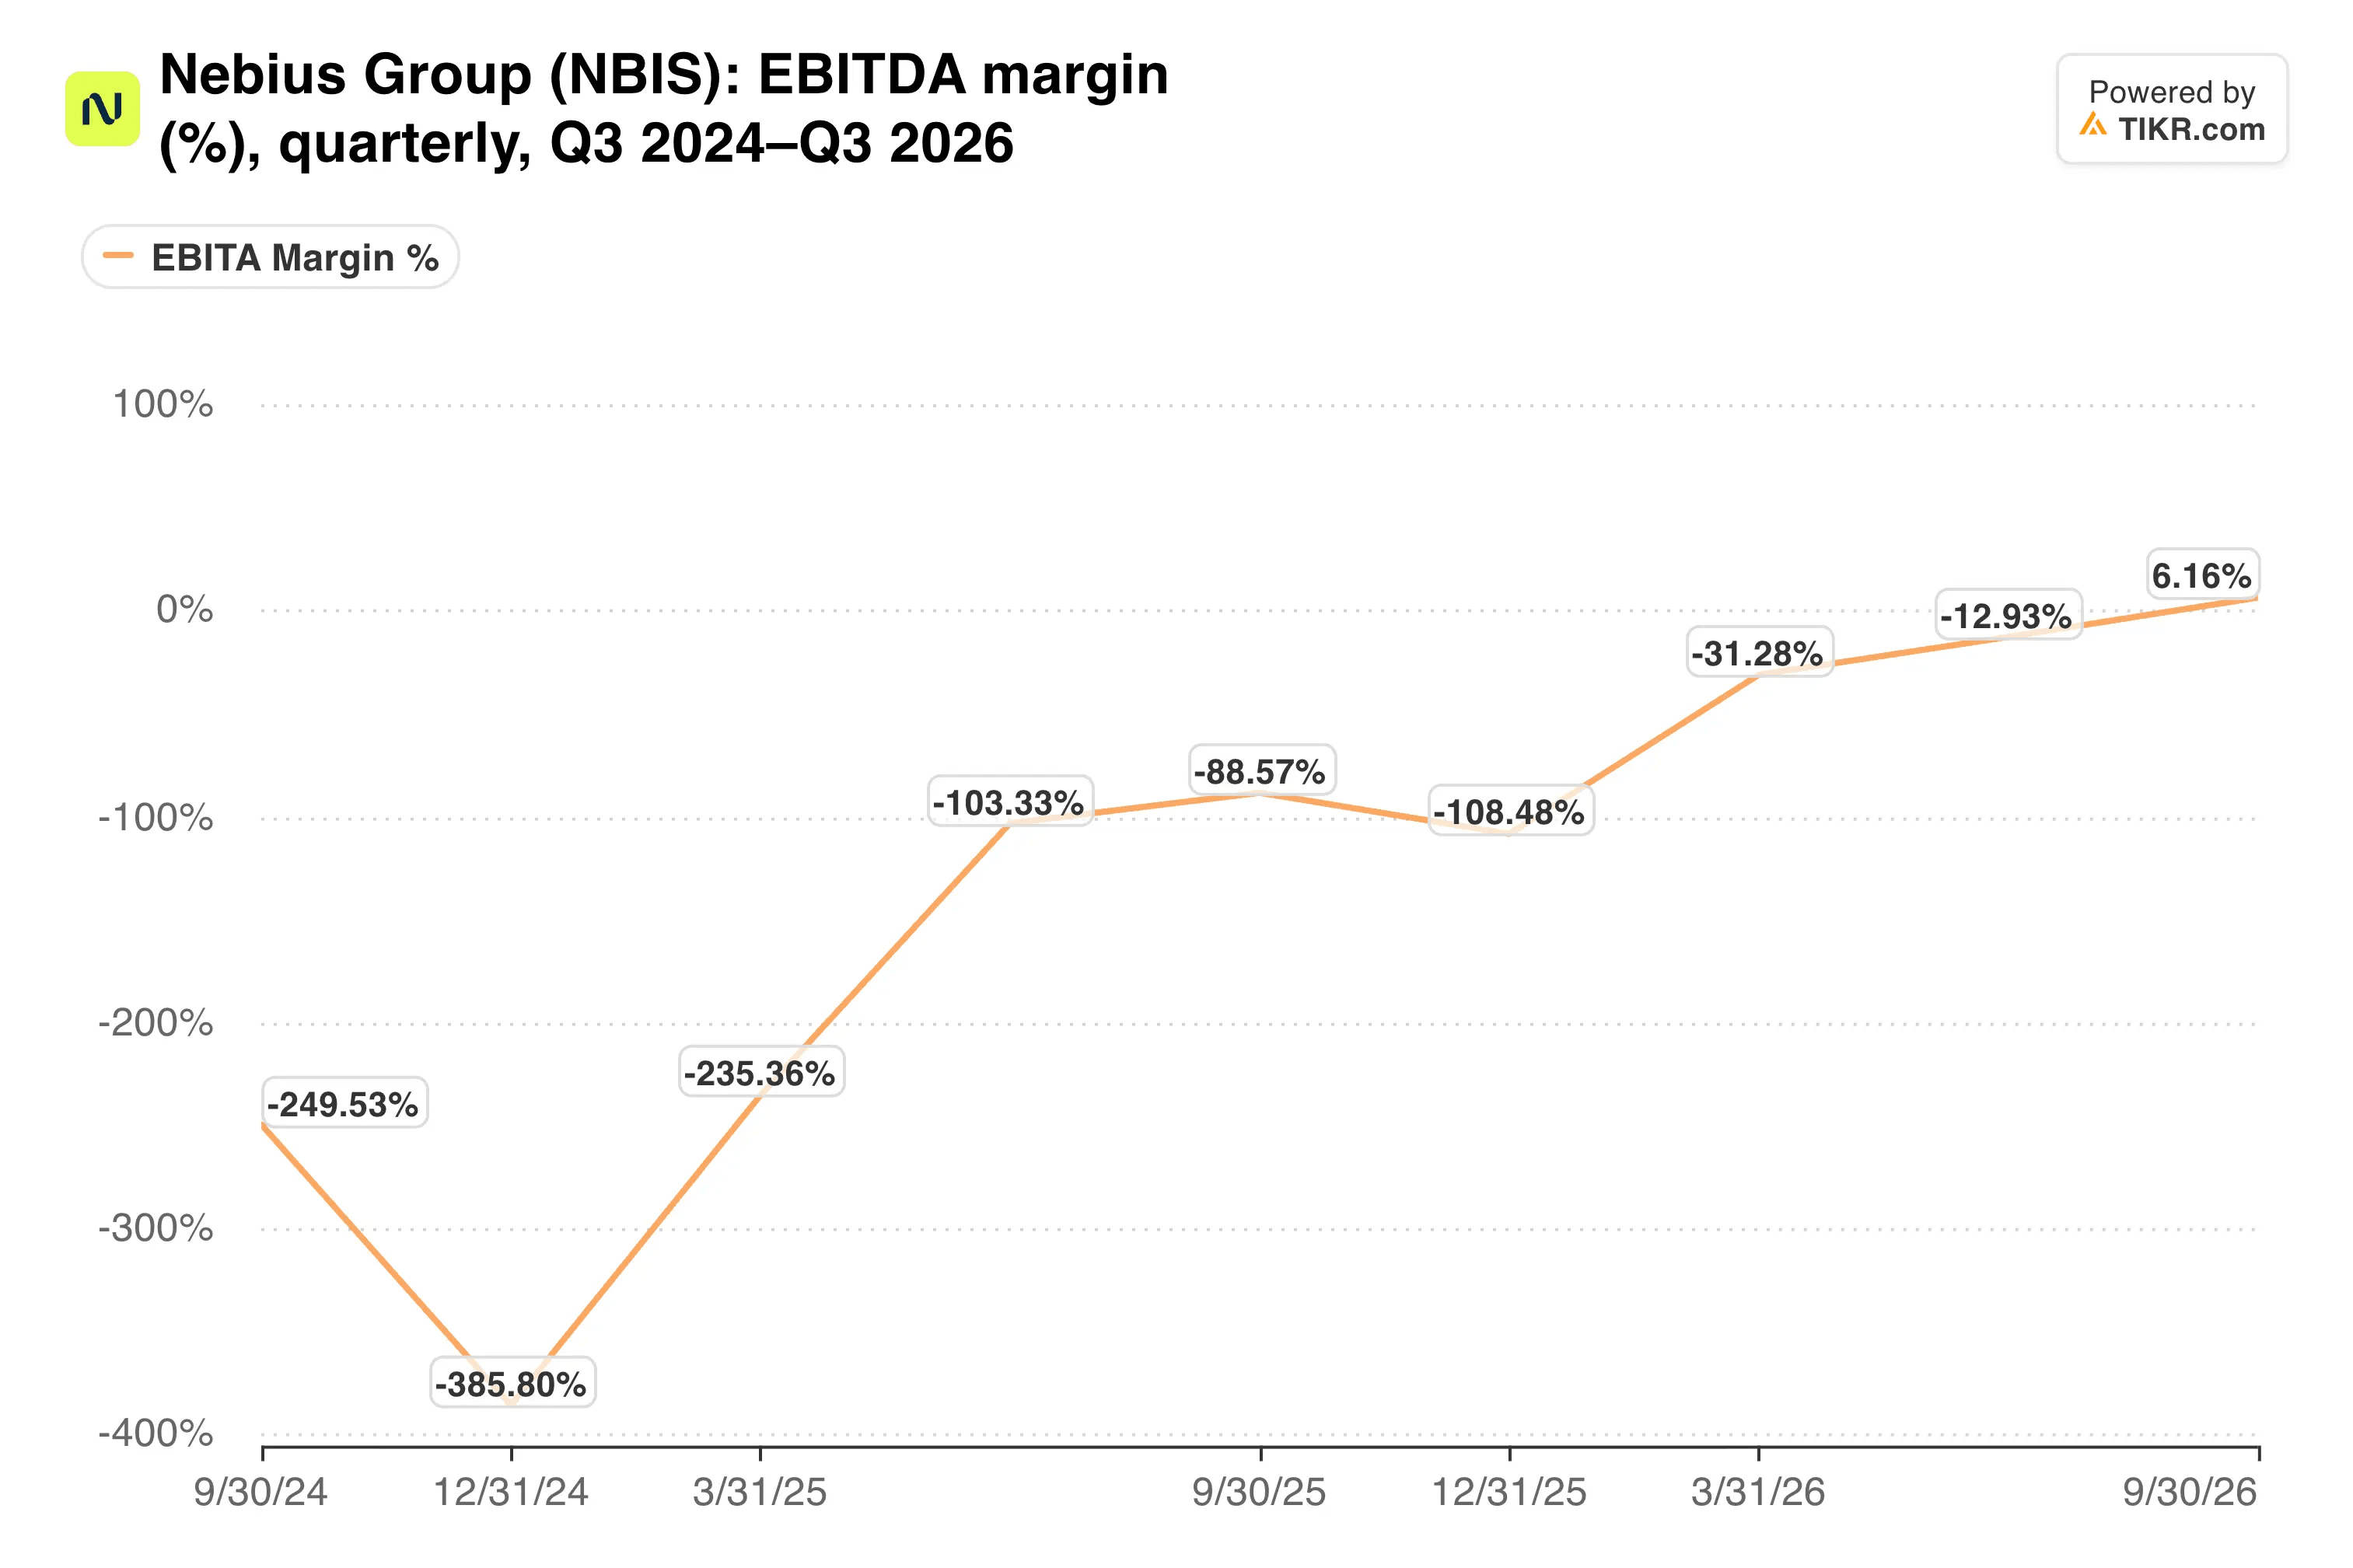
The AI cloud business posted a 53.2% adjusted EBITDA margin. For scale, CoreWeave’s third-quarter revenue rose 168% to $3.66 billion, still more than three times Nebius’ total. Nebius is growing faster from a smaller base, and it guided 2027 revenue to $12 billion to $13 billion, about four times this year.
TIKR tracks 23 analysts on Nebius. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nebius, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nebius’ Analyst Ratings
The spending bill keeps growing
Spending is where the selloff makes sense. Nebius raised 2026 capex to about $27 billion from $20 billion to $25 billion. It also guided $40 billion to $45 billion for 2027, and both figures topped analyst expectations.
Third-quarter capex alone came to about $7.3 billion, and the climb has been steep.
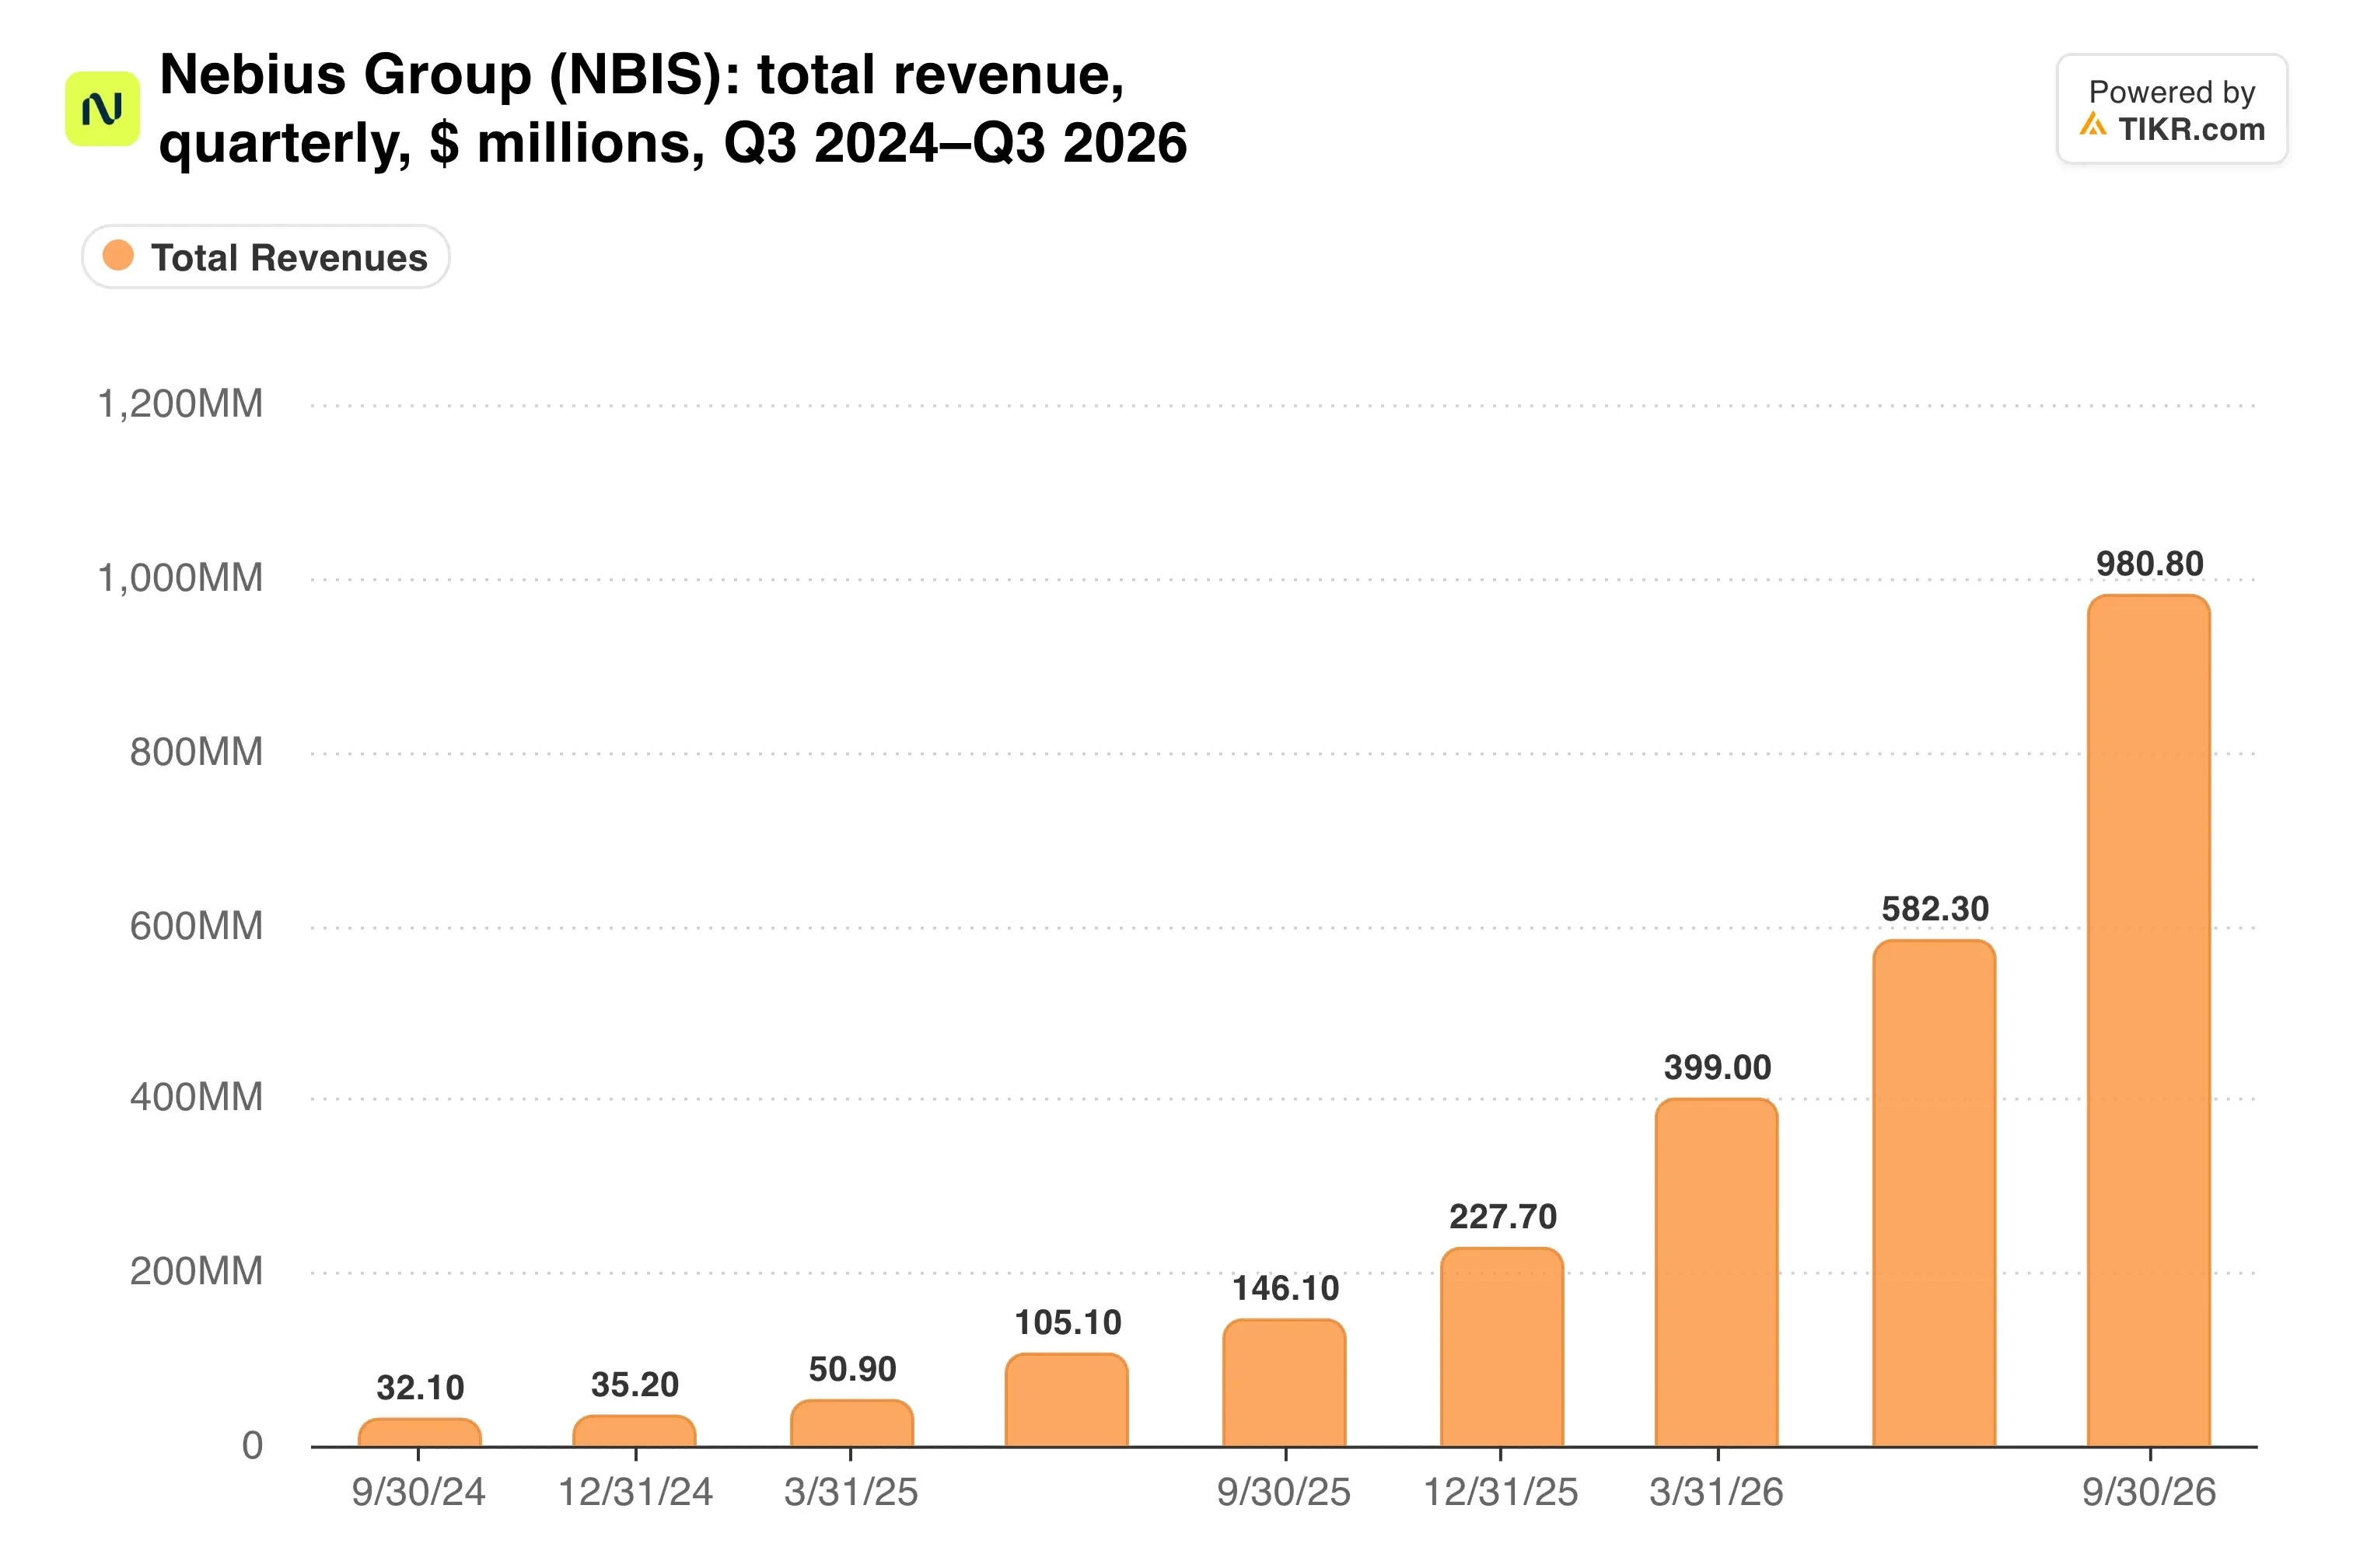
Operating cash flow was a $273 million outflow, so outside money filled the gap. That included $5.75 billion of convertible notes in August and about $1.0 billion of stock sales.
CEO Arkady Volozh was blunt on the earnings call: “Building at this scale is hard, and delays are part of our industry right now. We are not immune.”
Nebius expects prepayments and asset-backed loans to cover 75% to 85% of 2027 capex. It also targets pre-tax breakeven in the fourth quarter of 2027.
My take: The demand side of this report was better than the stock’s reaction suggests. Yet the delays sit with landlords Nebius doesn’t control, and more share sales remain possible until owned sites carry the load. I’d wait for proof of delivery before buying the dip.
The next checkpoint is the fourth-quarter report, expected in February. That report should show whether more than half of Microsoft’s New Jersey capacity arrived on schedule. Watch, too, whether ARR looks set to top $7 billion that month.
So what is Nebius Group stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nebius Group could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!