Key Takeaways
- Navitas Semiconductor shares jumped 6% after third-quarter revenue of $14.0 million beat estimates.
- Navitas expects AI infrastructure to top 40% of fourth-quarter sales.
- onsemi’s AI data center sales jumped 175%, and NVIDIA’s Nov. 17 report is the next read on 800-volt timing.
- Navitas’s pivot has the revenue behind it now, but investors are already paying for next year’s growth.
Navitas Semiconductor (NVTS) stock is up 6% today after its third quarter and fourth-quarter guide beat Wall Street’s estimates.
A day earlier, onsemi (ON) said its AI data center revenue grew 175% from a year earlier. And Navitas worked with NVIDIA (NVDA) on a power board for 800-volt AI racks.
Growth is back
- Revenue: $14.0 million, up 38% from a year earlier (consensus: $13.17 million)
- Fourth-quarter guide: $16.0 million at the midpoint (consensus: $15.12 million)
CEO Chris Allexandre called power AI’s biggest bottleneck: “Realizing this increased capacity requires breaking the power wall with new technologies, including 800 V architectures as well as integrated voltage regulation (IVR).”
Mobile chips, most of last year’s revenue, should be essentially gone by year-end, and Navitas expects AI infrastructure to top 40% of fourth-quarter sales.
Going into the report, analysts expected 2026 to be the bottom for revenue:

Navitas now guides 2026 to $49.1 million, above the $47.7 million consensus, and expects AI infrastructure revenue to grow about 3x in 2027. I don’t see anything here that should push estimates lower.
TIKR tracks 7 analysts on Navitas Semiconductor. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Navitas Semiconductor, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Navitas Semiconductor’s Analyst Ratings
Navitas has company
onsemi is buying Ferric to deliver power right at the AI processor, the job Navitas bought Claros to do. That’s good news for the shift Navitas is betting on, but it puts Navitas up against a rival that made $489 million of free cash flow last quarter.
NVIDIA matters even more. For its biggest gallium nitride sales, Navitas needs 800-volt power inside the server tray. In July, management said that move would pick up in late 2027 and early 2028. Whatever NVIDIA says about 800-volt racks on Nov. 17 is the next read on that timeline.
Still small, and not cheap
With Claros, Navitas would need over $60 million of quarterly revenue to break even, nearly four times the guide. It had $531.5 million of cash on Sept. 30, so it has time.
Navitas traded at 34x forward sales at Tuesday’s close, above its three-year average of 31x:
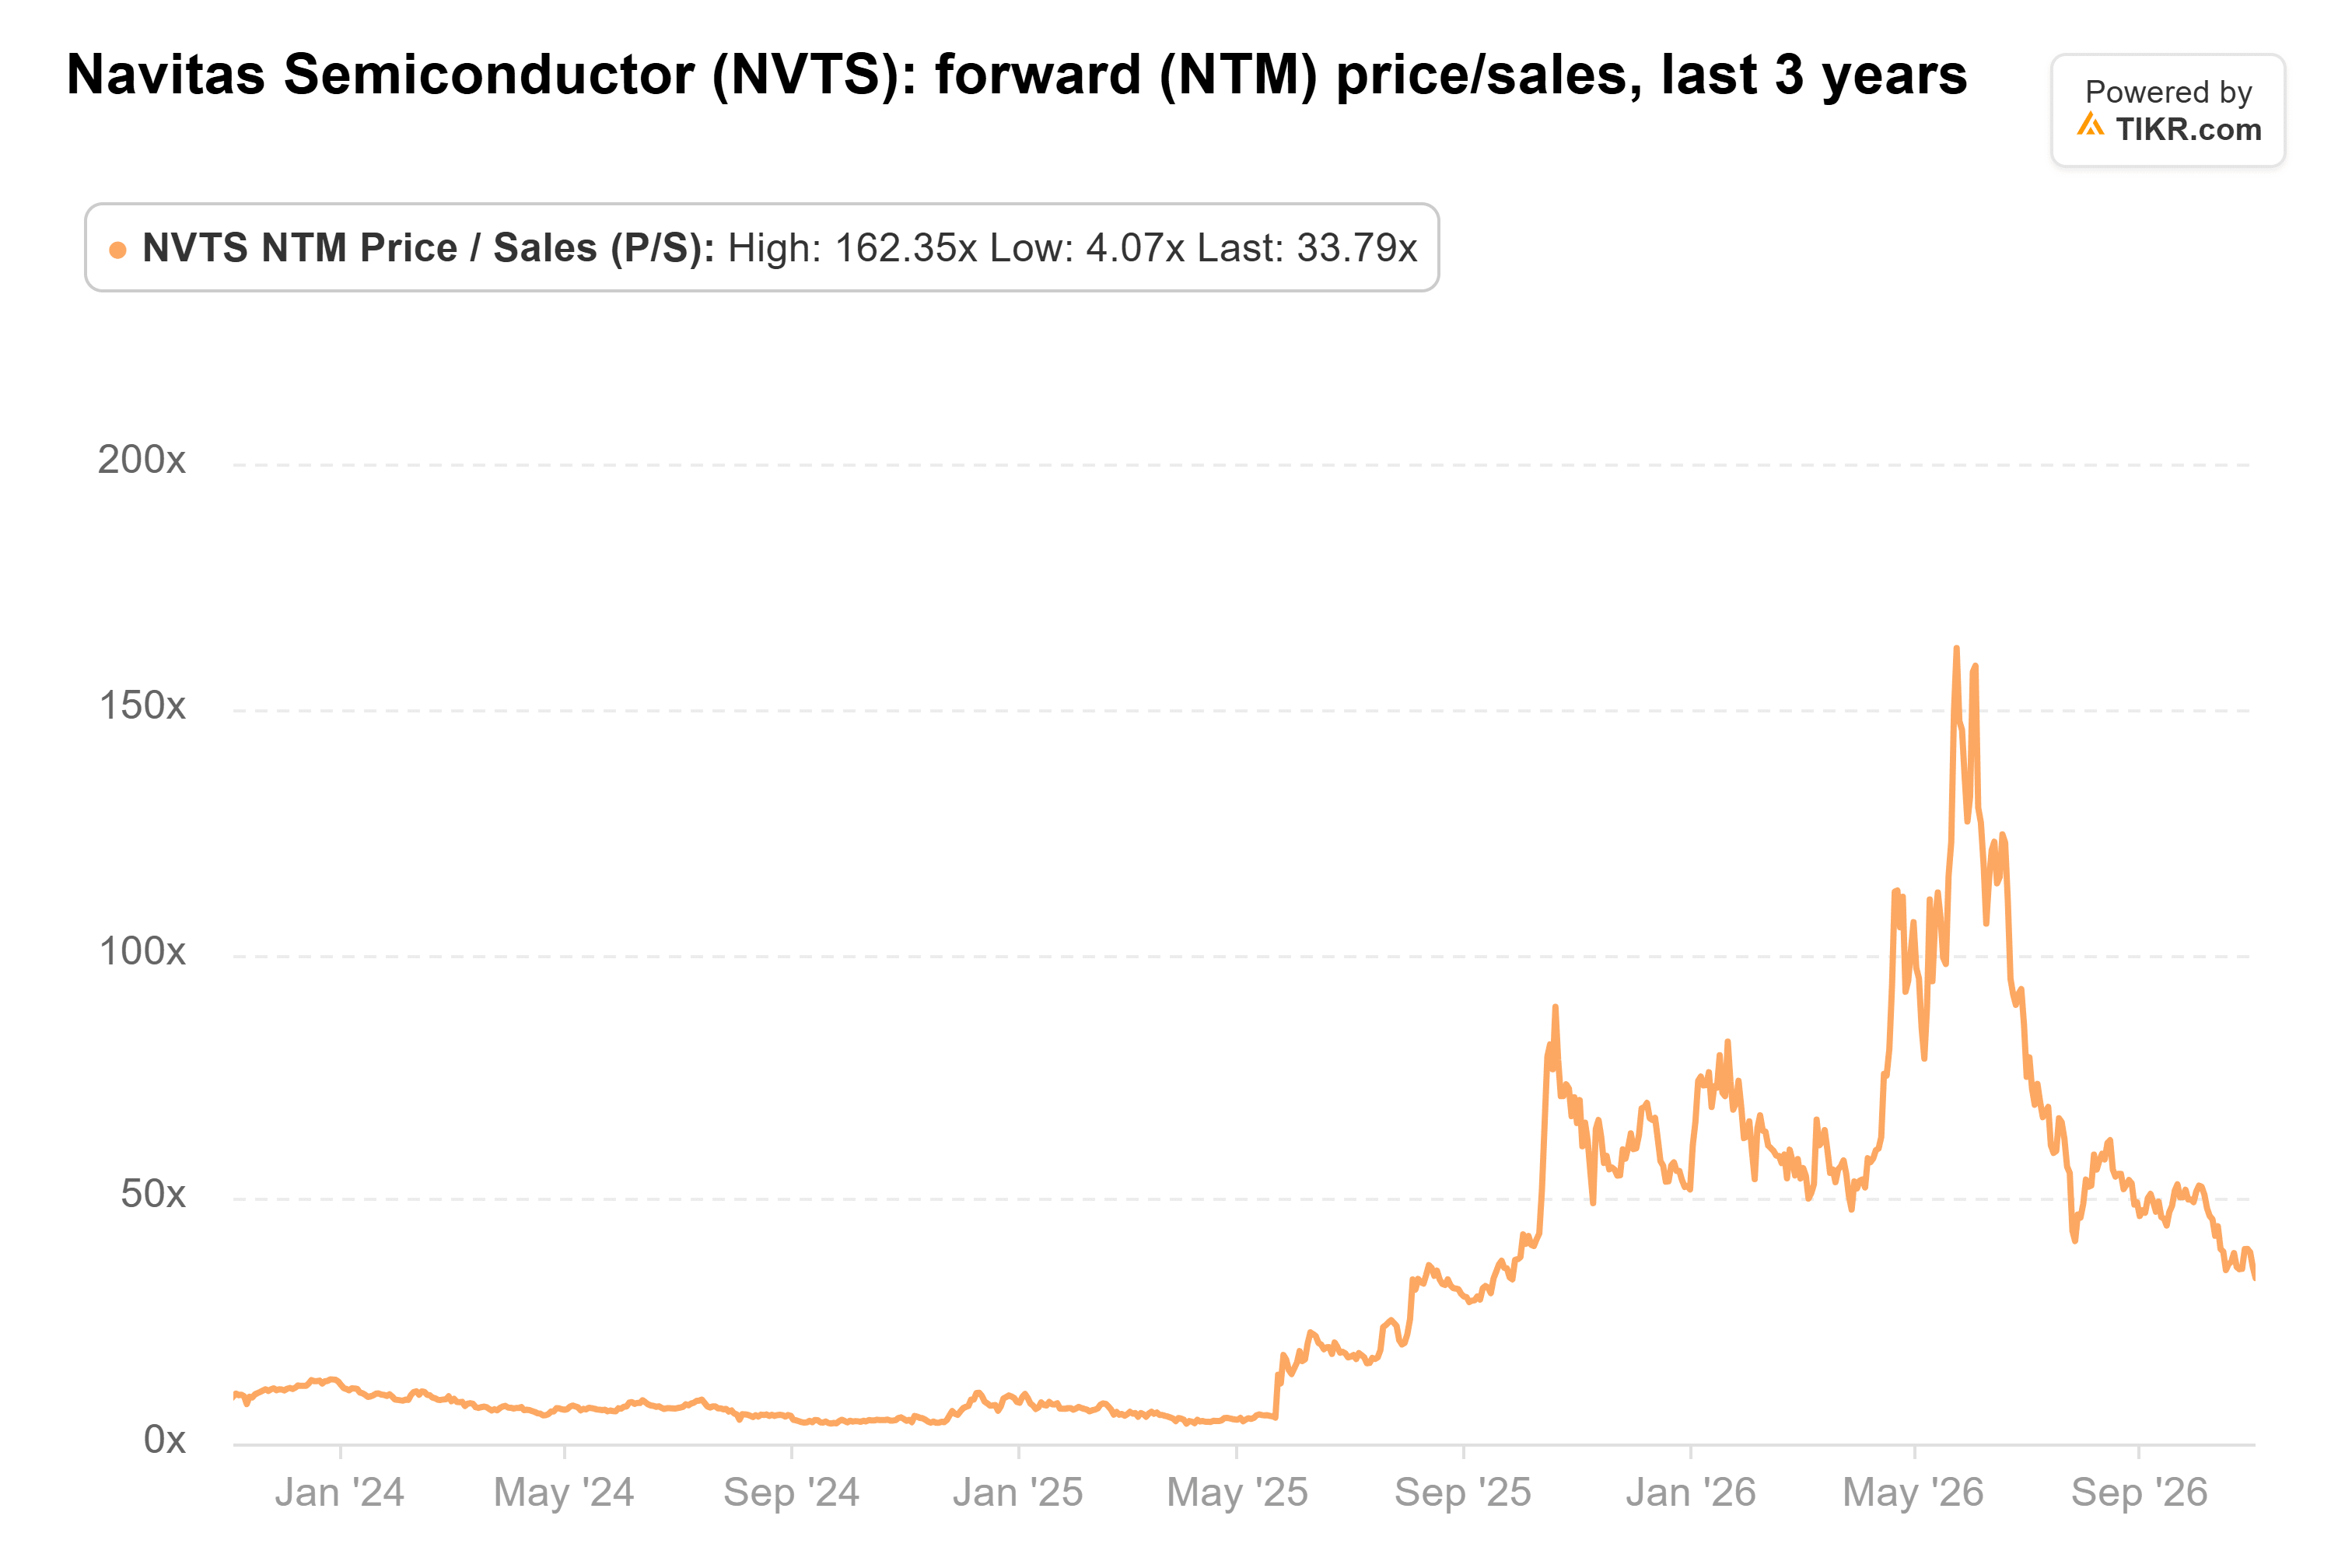
At today’s price, it’s even higher.
The way I see it, Navitas finally has the revenue behind its pivot, but investors are already paying for the 2027 ramp. Of course, with backlog running into mid-2027, that wait could be shorter than I think.
So what is Navitas stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Navitas could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!