

Key Takeaways
- Datadog stock fell 17% in a week after a roughly flat fourth-quarter revenue guide outweighed 35% third-quarter growth.
- The guide counts its largest customer, an AI company that cut its usage, only at its contract minimum.
- Cloudflare’s fourth-quarter guide keeps climbing, a sign the slowdown may be confined to one Datadog account.
- At about 60x forward earnings, far below its usual multiple, Datadog looks like a buy ahead of February’s 2027 outlook.
Datadog (DDOG) stock fell 17% in the week through Nov. 9, and most of it traces back to one customer.
Citi analyst Fatima Boolani says the selloff is “likely missing forest-for-the-trees.” Cloudflare (NET) backs her up: its own outlook, out a day after Datadog’s, keeps climbing.
Great quarter, flat outlook
Datadog reported before the open on Nov. 4. Revenue rose 35% to $1.20 billion, $52 million above the top of its own range, and adjusted EPS of $0.81 beat the $0.64 consensus. But fourth-quarter revenue is guided to 1.19-1.20 billion, roughly flat with the quarter it just reported, or 25% to 26% growth from a year earlier. Shares fell 14% that day and slid further on Thursday, Nov. 5, as the Nasdaq Composite dropped 5.5%.
Outside one customer, growth is speeding up
CFO David Obstler said on the third-quarter call that the largest customer cut its usage, though it still spent above its minimum commitment, and the guide counts it only at that minimum. Strip it out, and fourth-quarter growth comes to the low to mid 30s, even as some big customers, AI accounts included, renewed early for bigger commitments at better volume pricing. Growth outside AI customers sped up for a fifth straight quarter, to the high 20s, and Datadog now has more than 850 AI customers.
Cloudflare’s third-quarter revenue rose 39% to $782.5 million, and it guided the fourth quarter to 845-846 million, another step up. Its shares jumped 9.9% on Nov. 6. A broad pullback in cloud spending would likely have shown up there too.
TIKR tracks 48 analysts on Datadog. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Datadog, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Datadog’s Analyst Ratings
Far cheaper than usual
The new 2026 EPS guide of $2.73-$2.75 topped the $2.53 analysts expected, and estimates further out have climbed too:
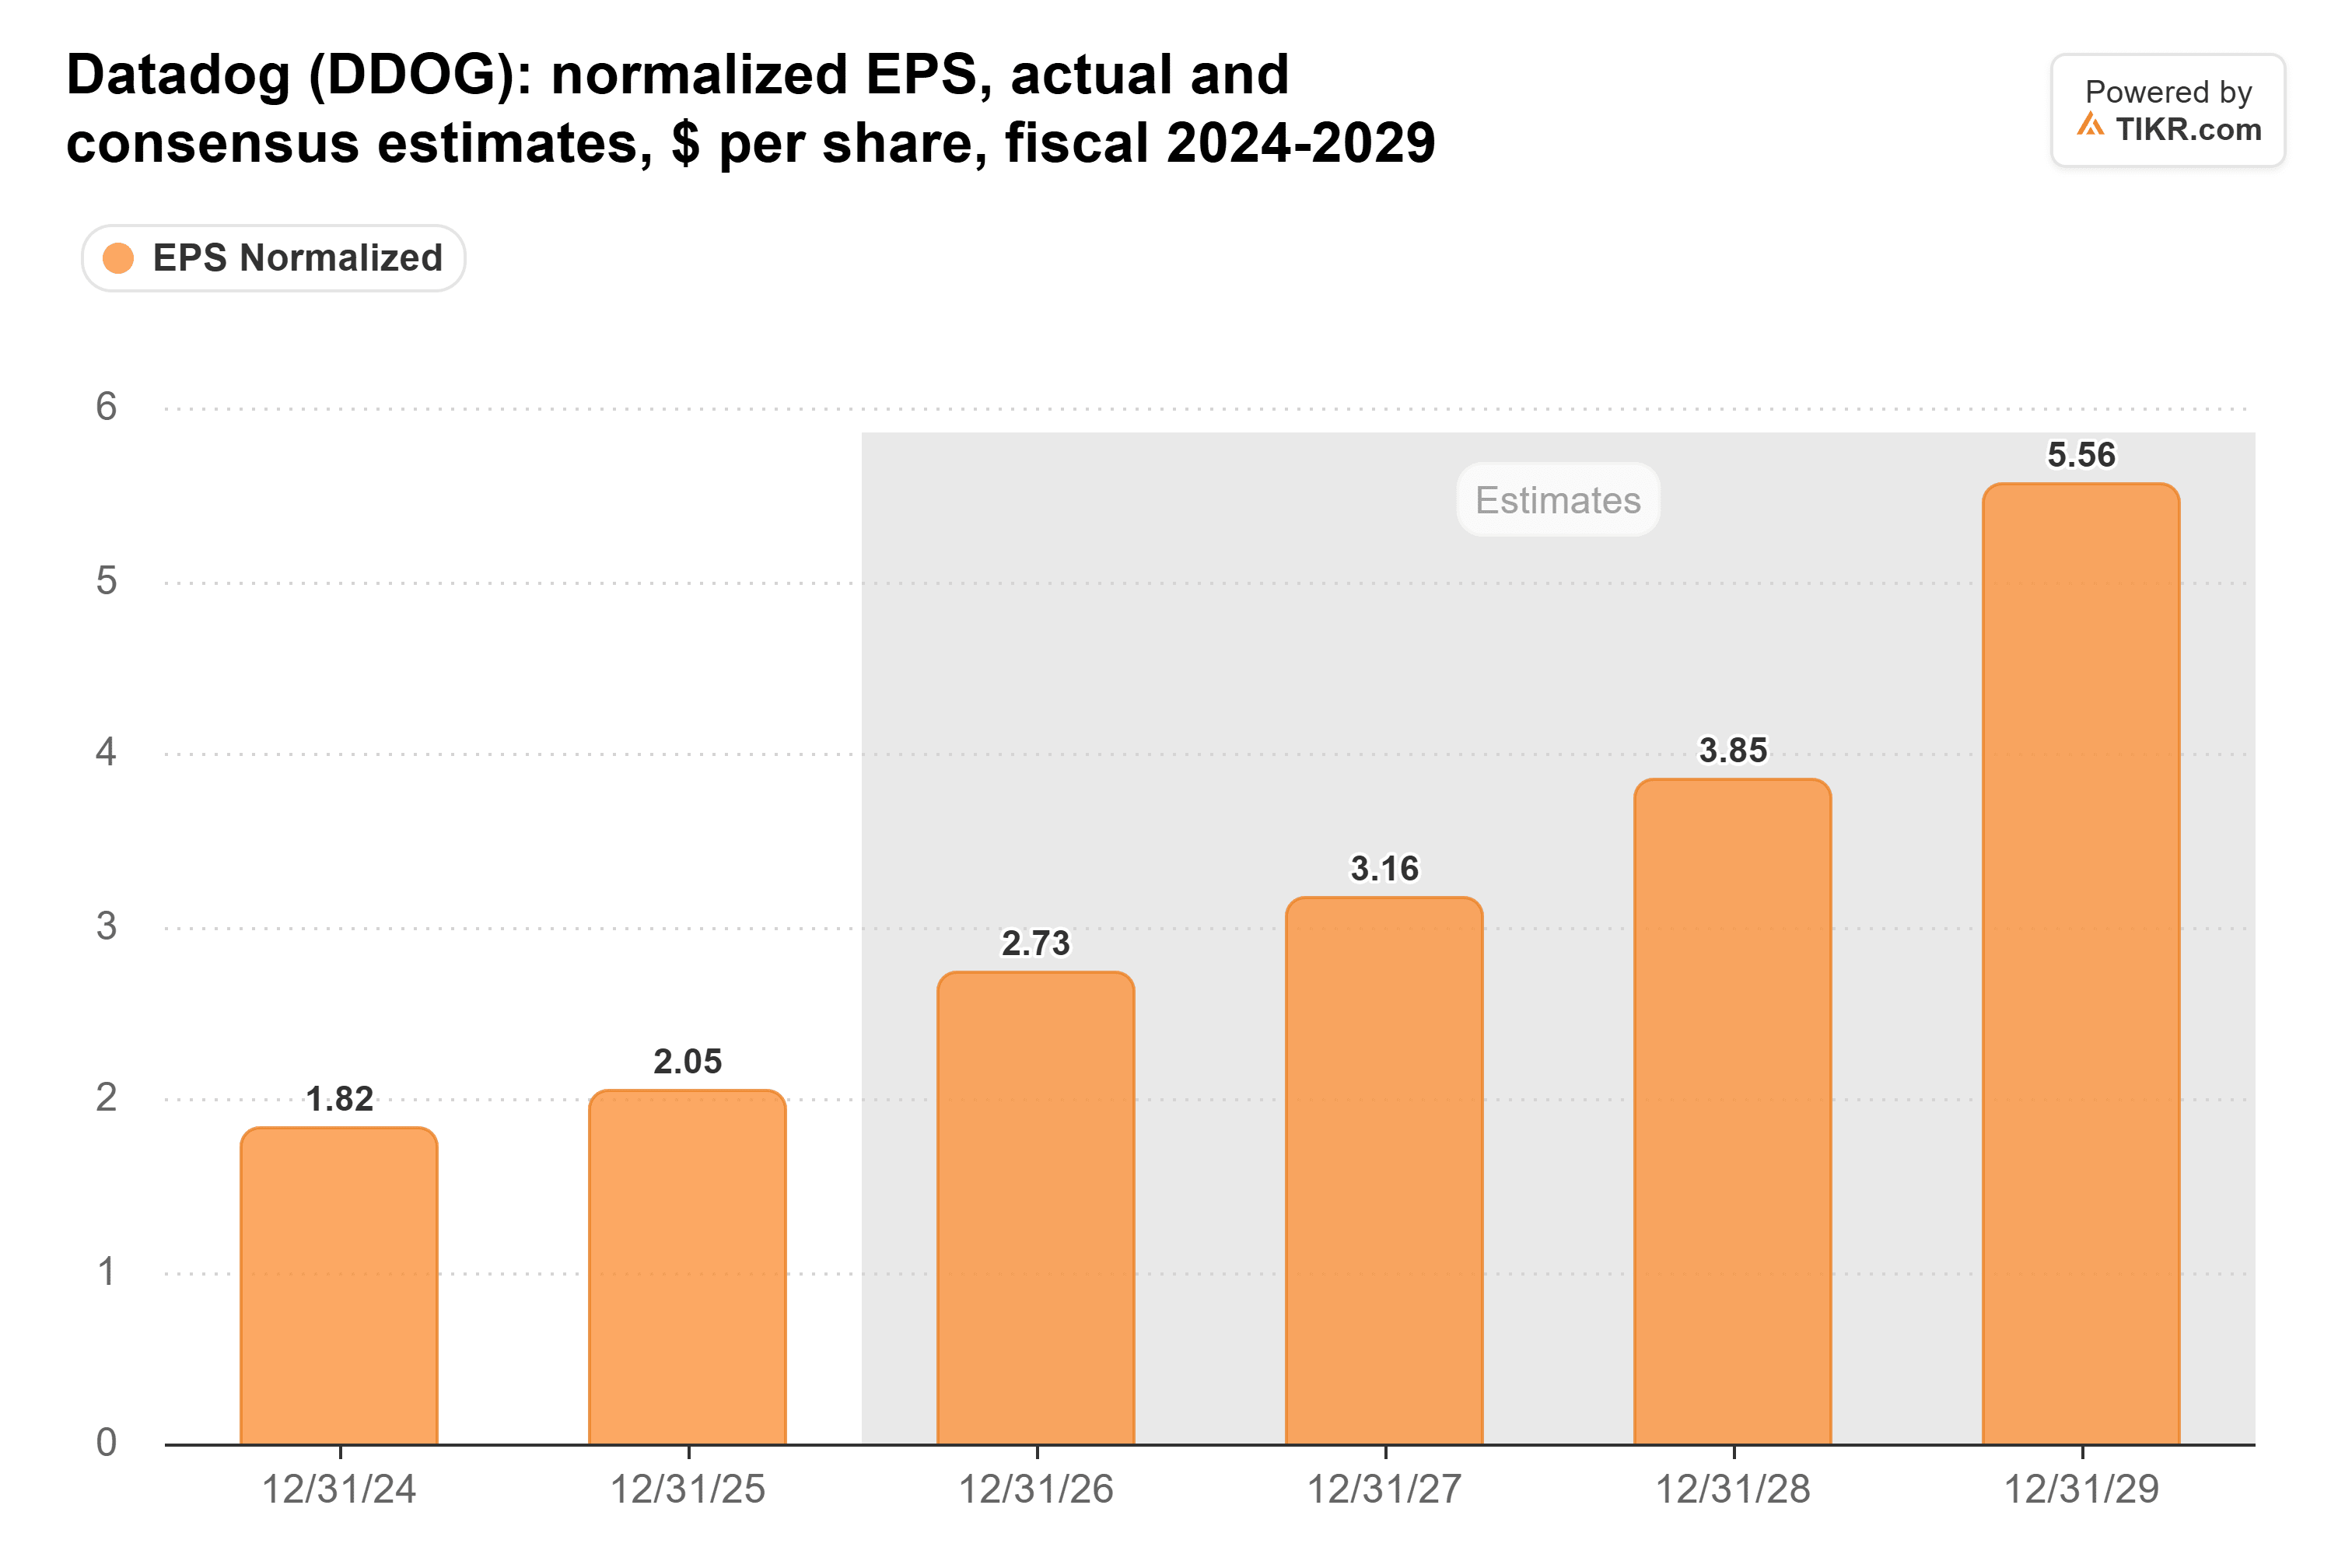
The 2027 estimate is now $3.16, up from $2.98 before the report. The stock went the other way, so its forward P/E is down to about 60x:
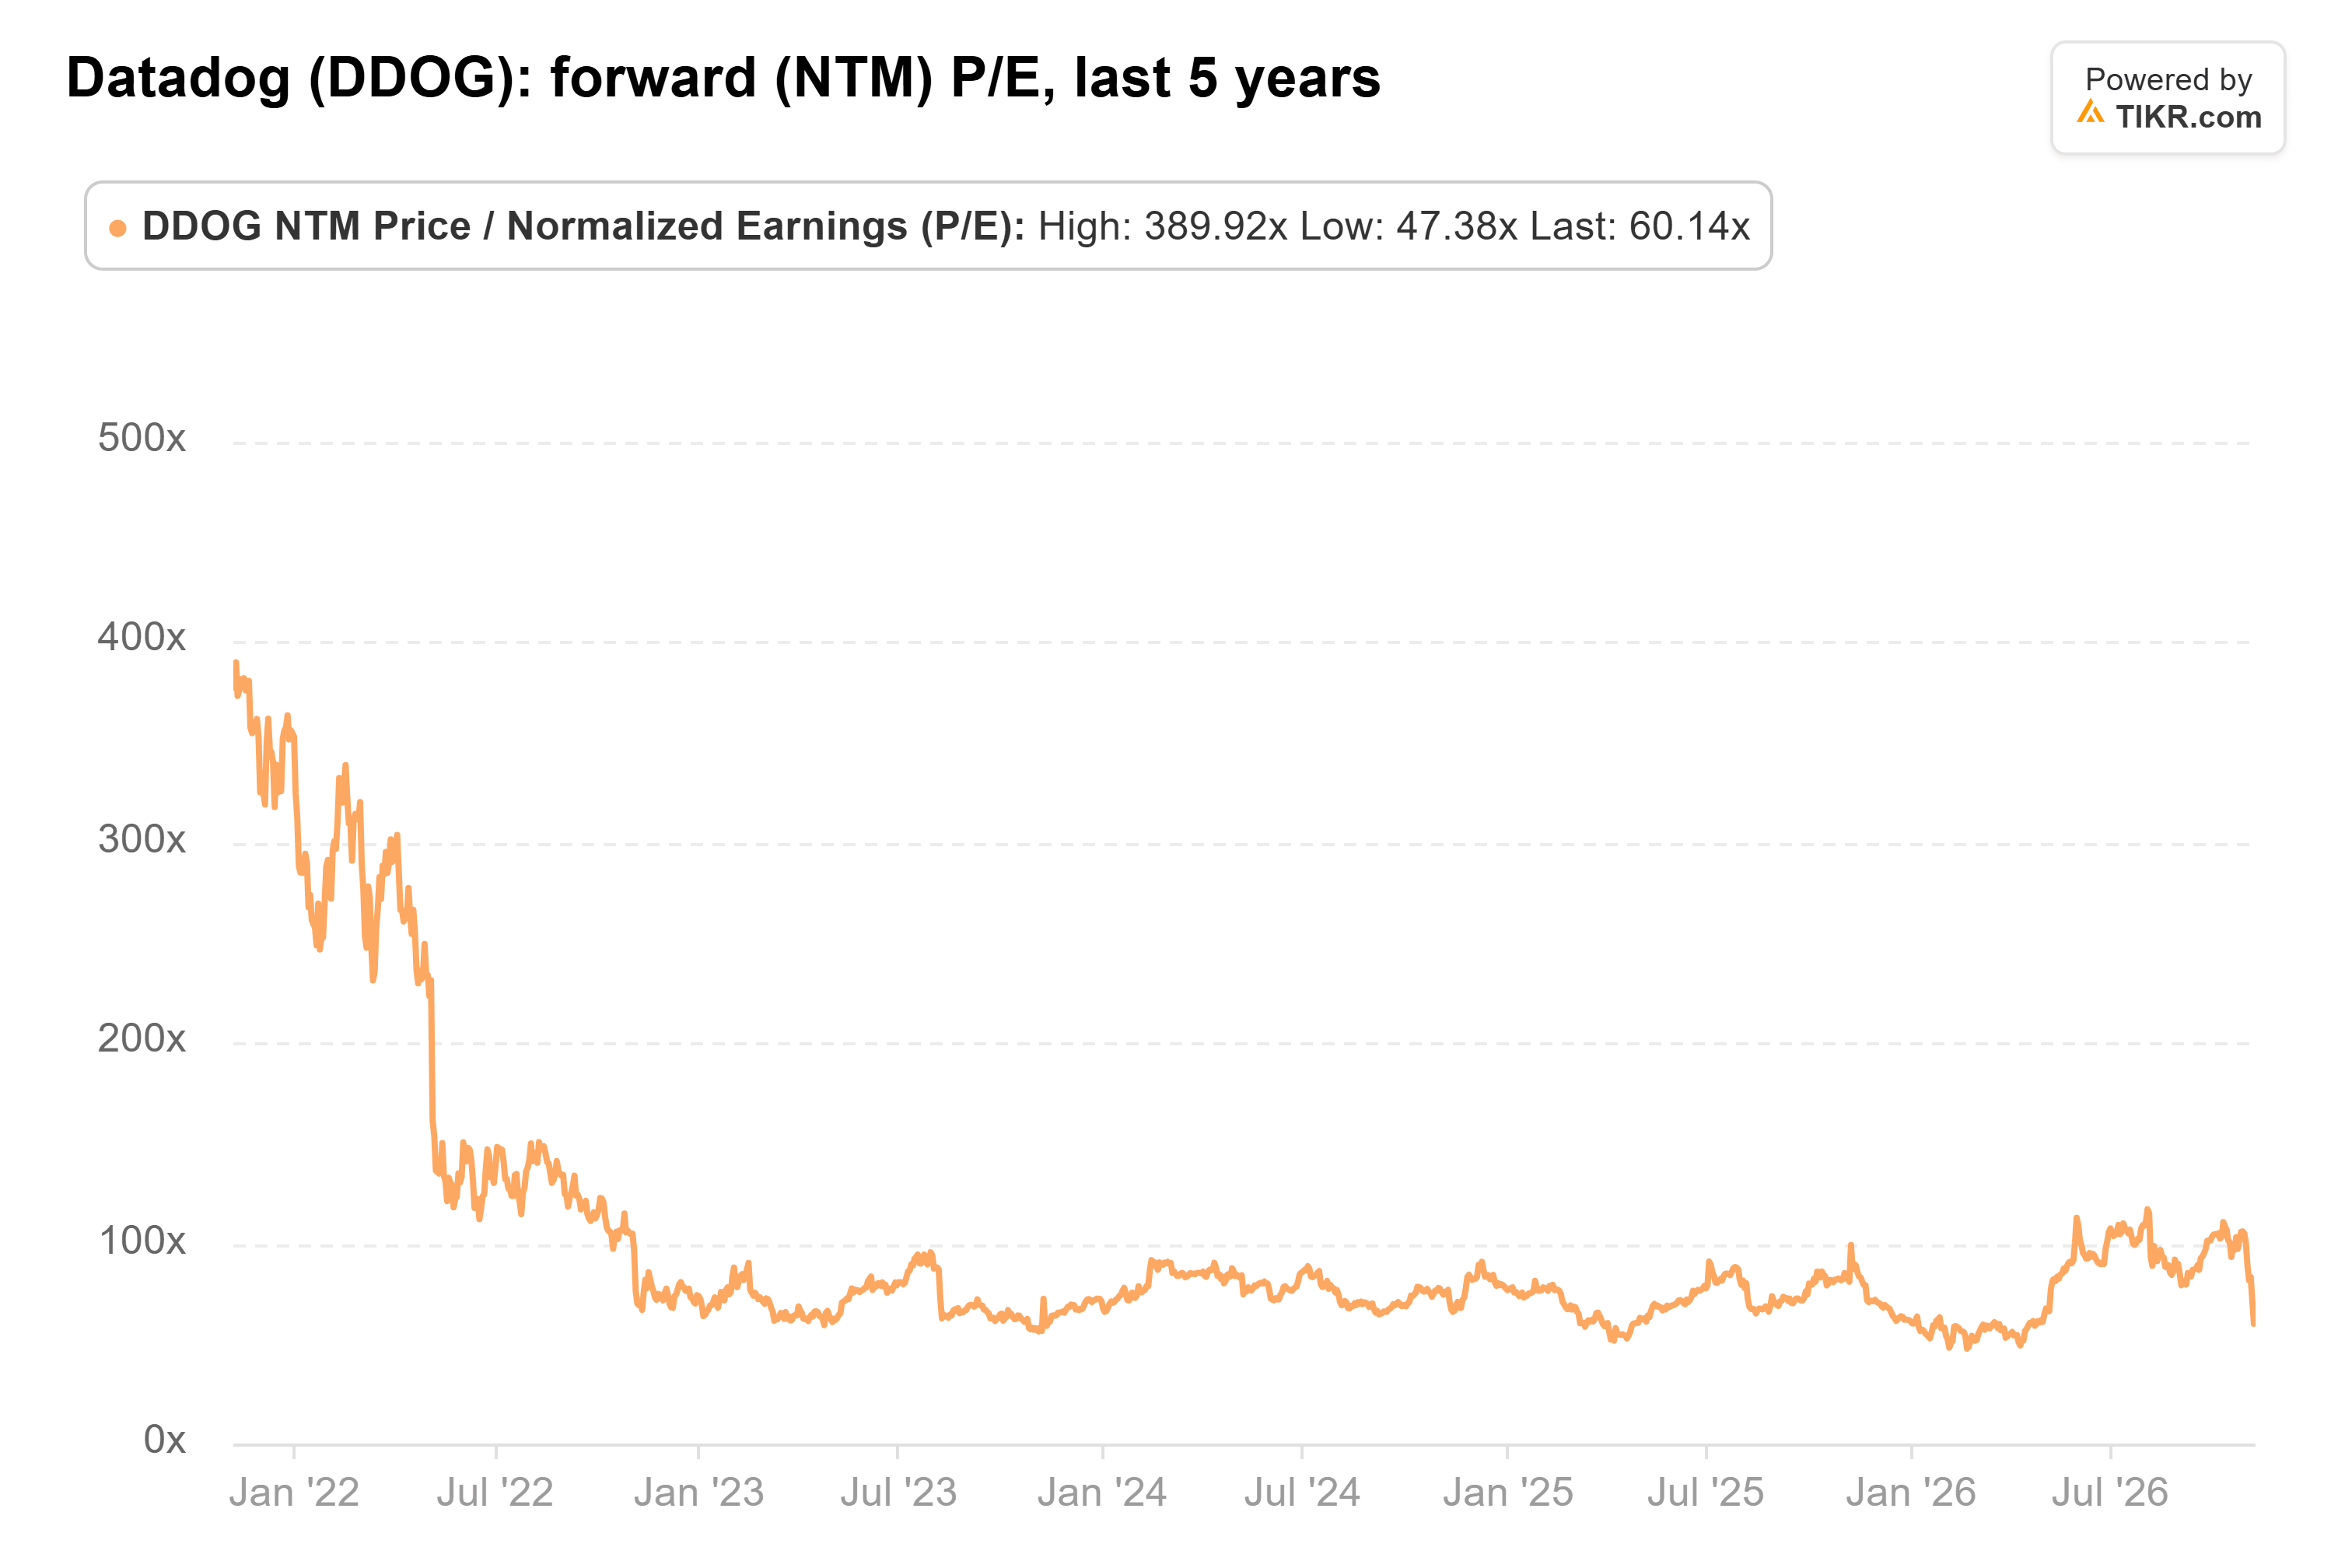
That’s well below its five-year average of 102x and the 76x it has averaged at quarter-ends since late 2022. Even after a round of target cuts on Nov. 5, the $272 consensus target sits about 51% above Monday’s $179.62 close.
The selloff prices Datadog as if one customer’s cut will spread, while the rest of the business accelerates. At this multiple, that looks like a buying opportunity. Not everyone agrees: Goldman Sachs rates the stock Sell with a $171 target, and if one big AI customer can cut back, another can too. February’s report is the checkpoint, with Datadog’s first 2027 outlook against the roughly 23% revenue growth analysts expected going in.
So what is Datadog stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Datadog could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


