Key Takeaways
- Microsoft shares fell 2% after Anthropic added Claude Sheets, Claude Whiteboards and Claude Data to its paid Claude plans at no extra charge.
- The threat to Office looks smaller than the selloff suggests, since Alphabet has offered free Office rivals for years and Microsoft 365 commercial cloud revenue grew 17% last quarter.
- Microsoft 365 brought in $111.2 billion in fiscal 2026, about a third of Microsoft’s revenue, and the segment that includes Office earned more than half of its operating income.
- Microsoft trades at 26x forward earnings, below its 29x five-year average, and Anthropic’s next products will show how far it plans to push into Microsoft’s bundle.
Anthropic just took its most direct shot yet at the Office franchise of Microsoft (MSFT).
On Tuesday, the AI lab started rolling out Claude Sheets, Claude Whiteboards and Claude Data, all included in its paid plans. It did it on the same day it began marketing its IPO. Microsoft shares fell 2%. Alphabet (GOOG) sells Google Sheets and Docs for the same kind of work, and its shares slipped on the news too.
Angel investor and All-In podcast co-host Jason Calacanis reacted on X:
“MICROSOFT is no longer the bundler — they are now the bundled.”
Bold words, given how much money Office makes.
TIKR tracks 58 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
Office is still the profit engine
One investor on Reddit’s r/ValueInvesting puts Microsoft 365 at $111.2 billion of revenue in fiscal 2026 (the year ended June), or 33.5% of the company’s total. That’s right. Microsoft’s annual report shows $102.0 billion from Microsoft 365 commercial products and cloud services and $9.2 billion from the consumer side, out of $331.8 billion of total revenue.
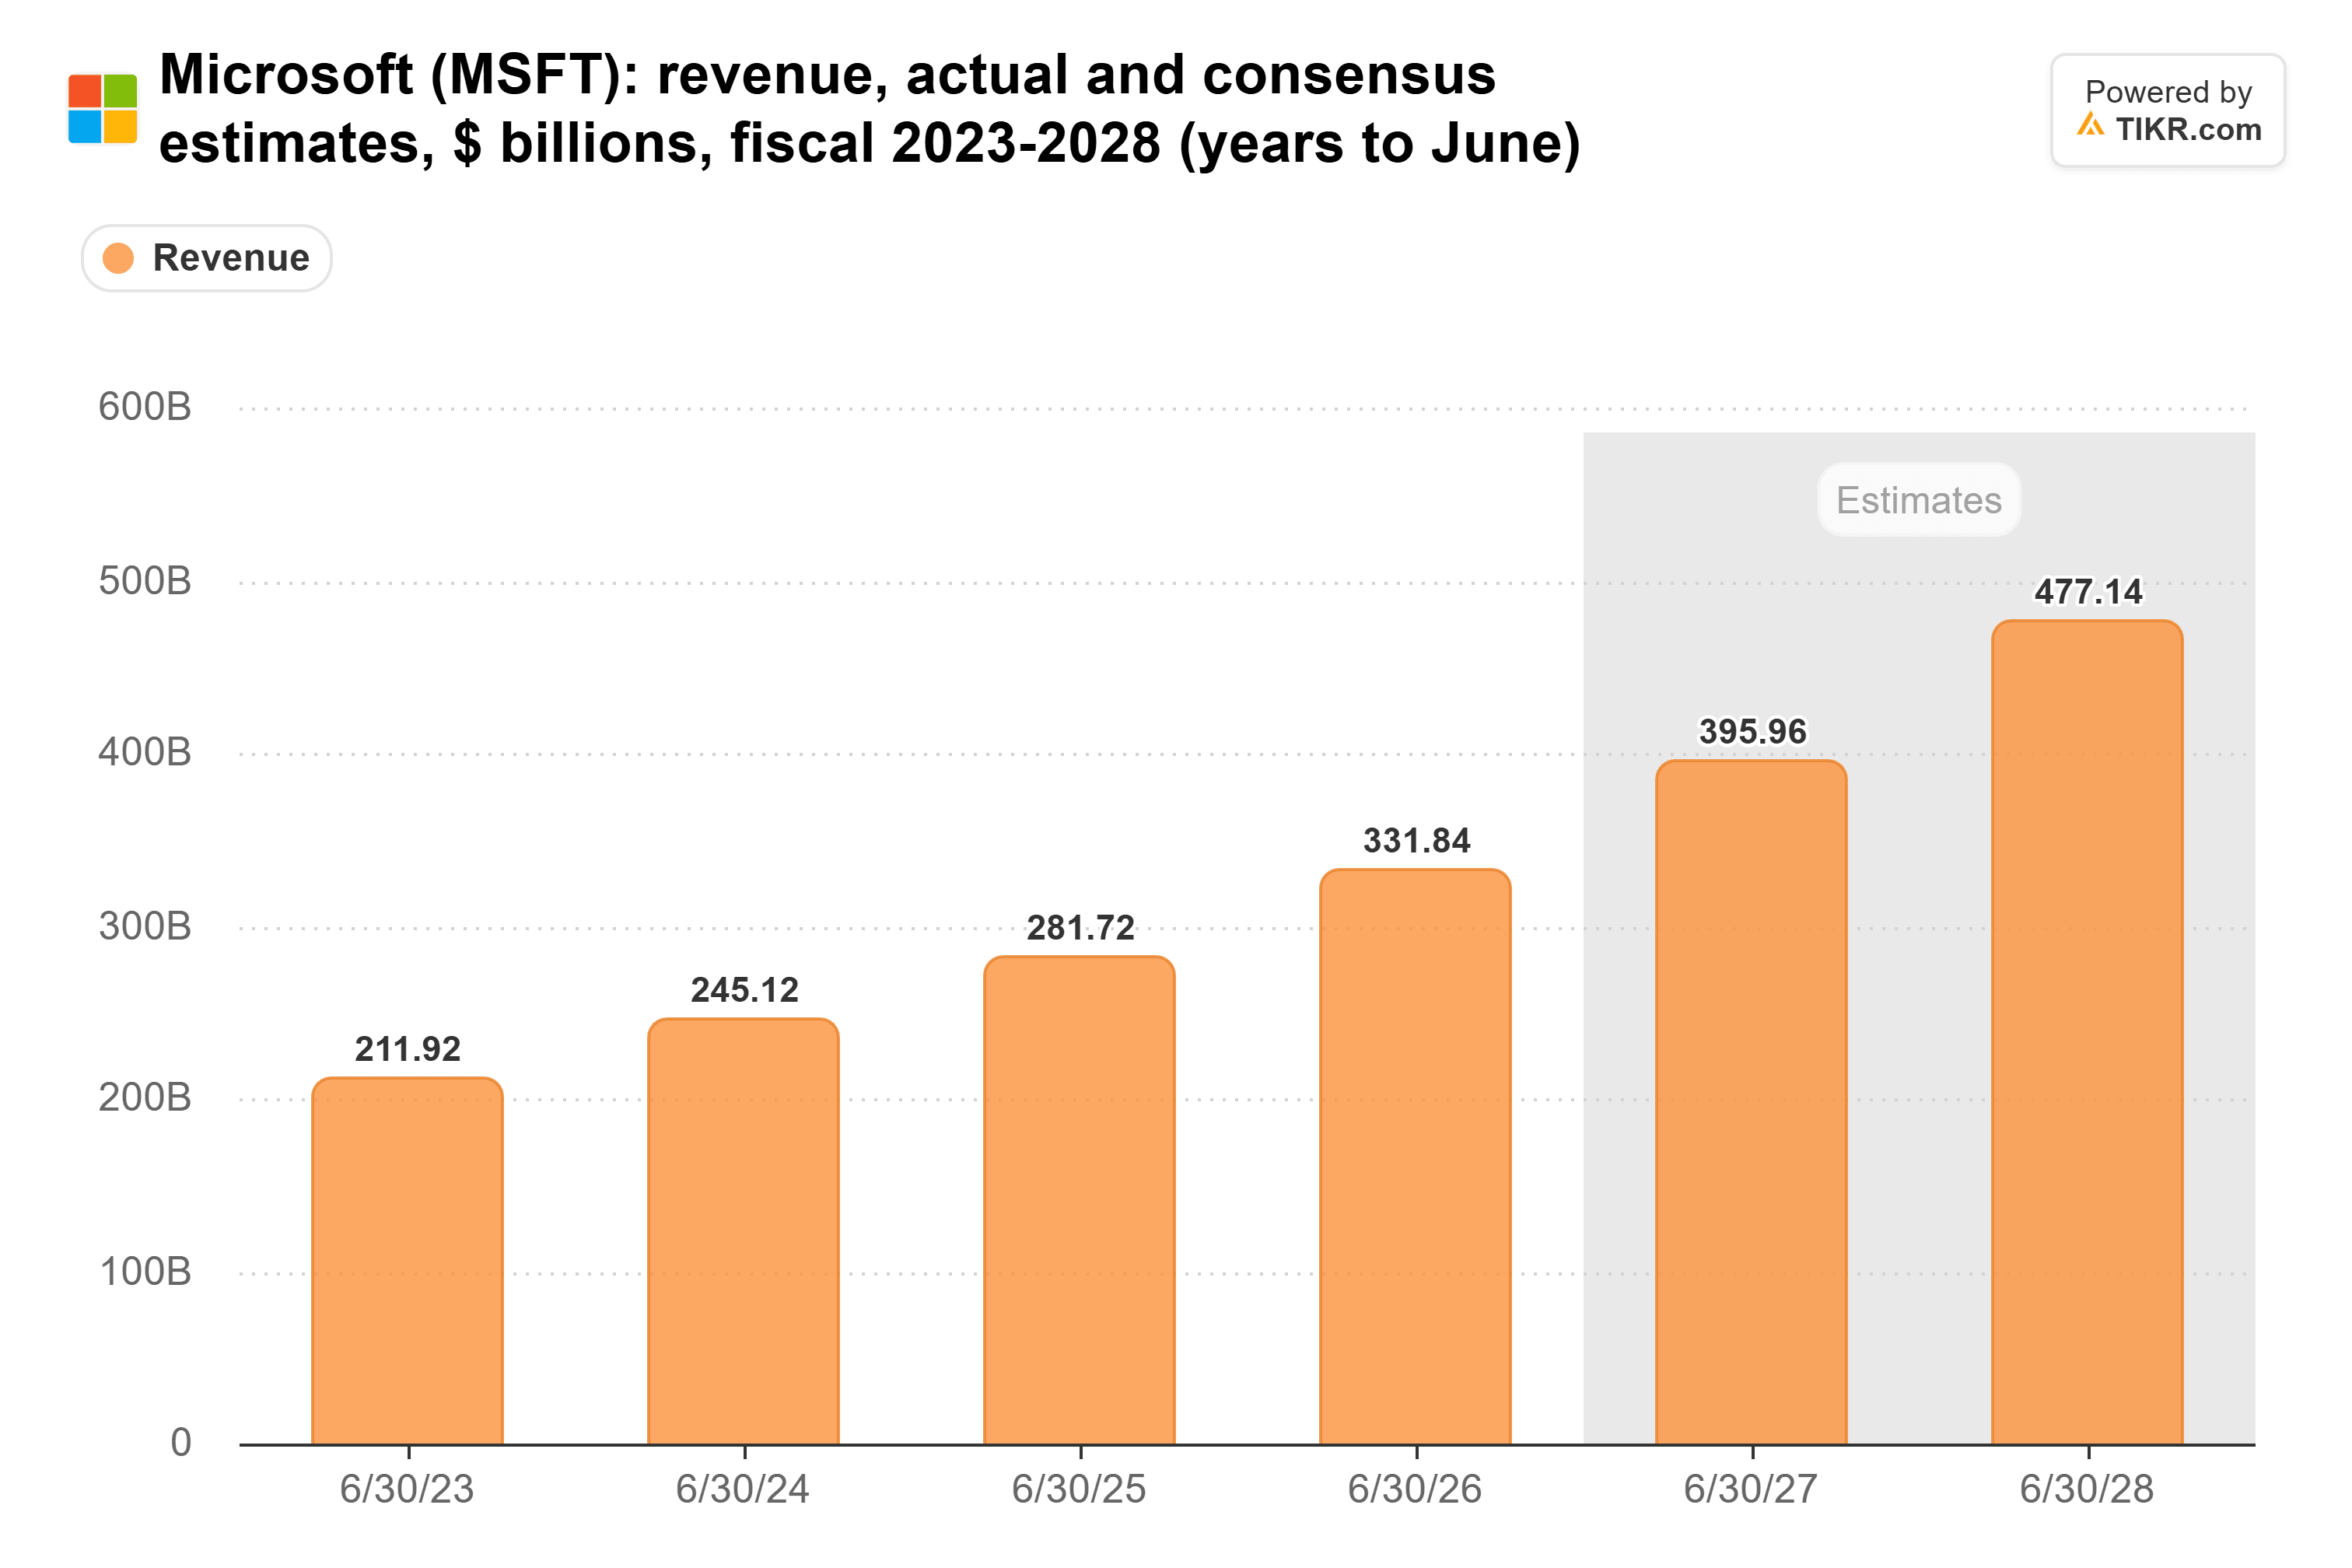
Analysts expect Microsoft’s total revenue to grow from $332 billion in fiscal 2026 to $477 billion in fiscal 2028.
A spreadsheet app still in beta shouldn’t move those estimates much. Microsoft 365 commercial cloud revenue grew 17% in the quarter ended Sept. 30, up from 14% in the June quarter, Microsoft said in its first-quarter release.
Office matters even more for profit. The segment that includes it, along with LinkedIn and Dynamics, earned 54.0% of Microsoft’s fiscal 2026 operating income at a 59.9% margin. Pricing power in franchises like Office helps explain how Microsoft’s operating margin climbed from 42.1% in fiscal 2022 to 46.8% in fiscal 2026.
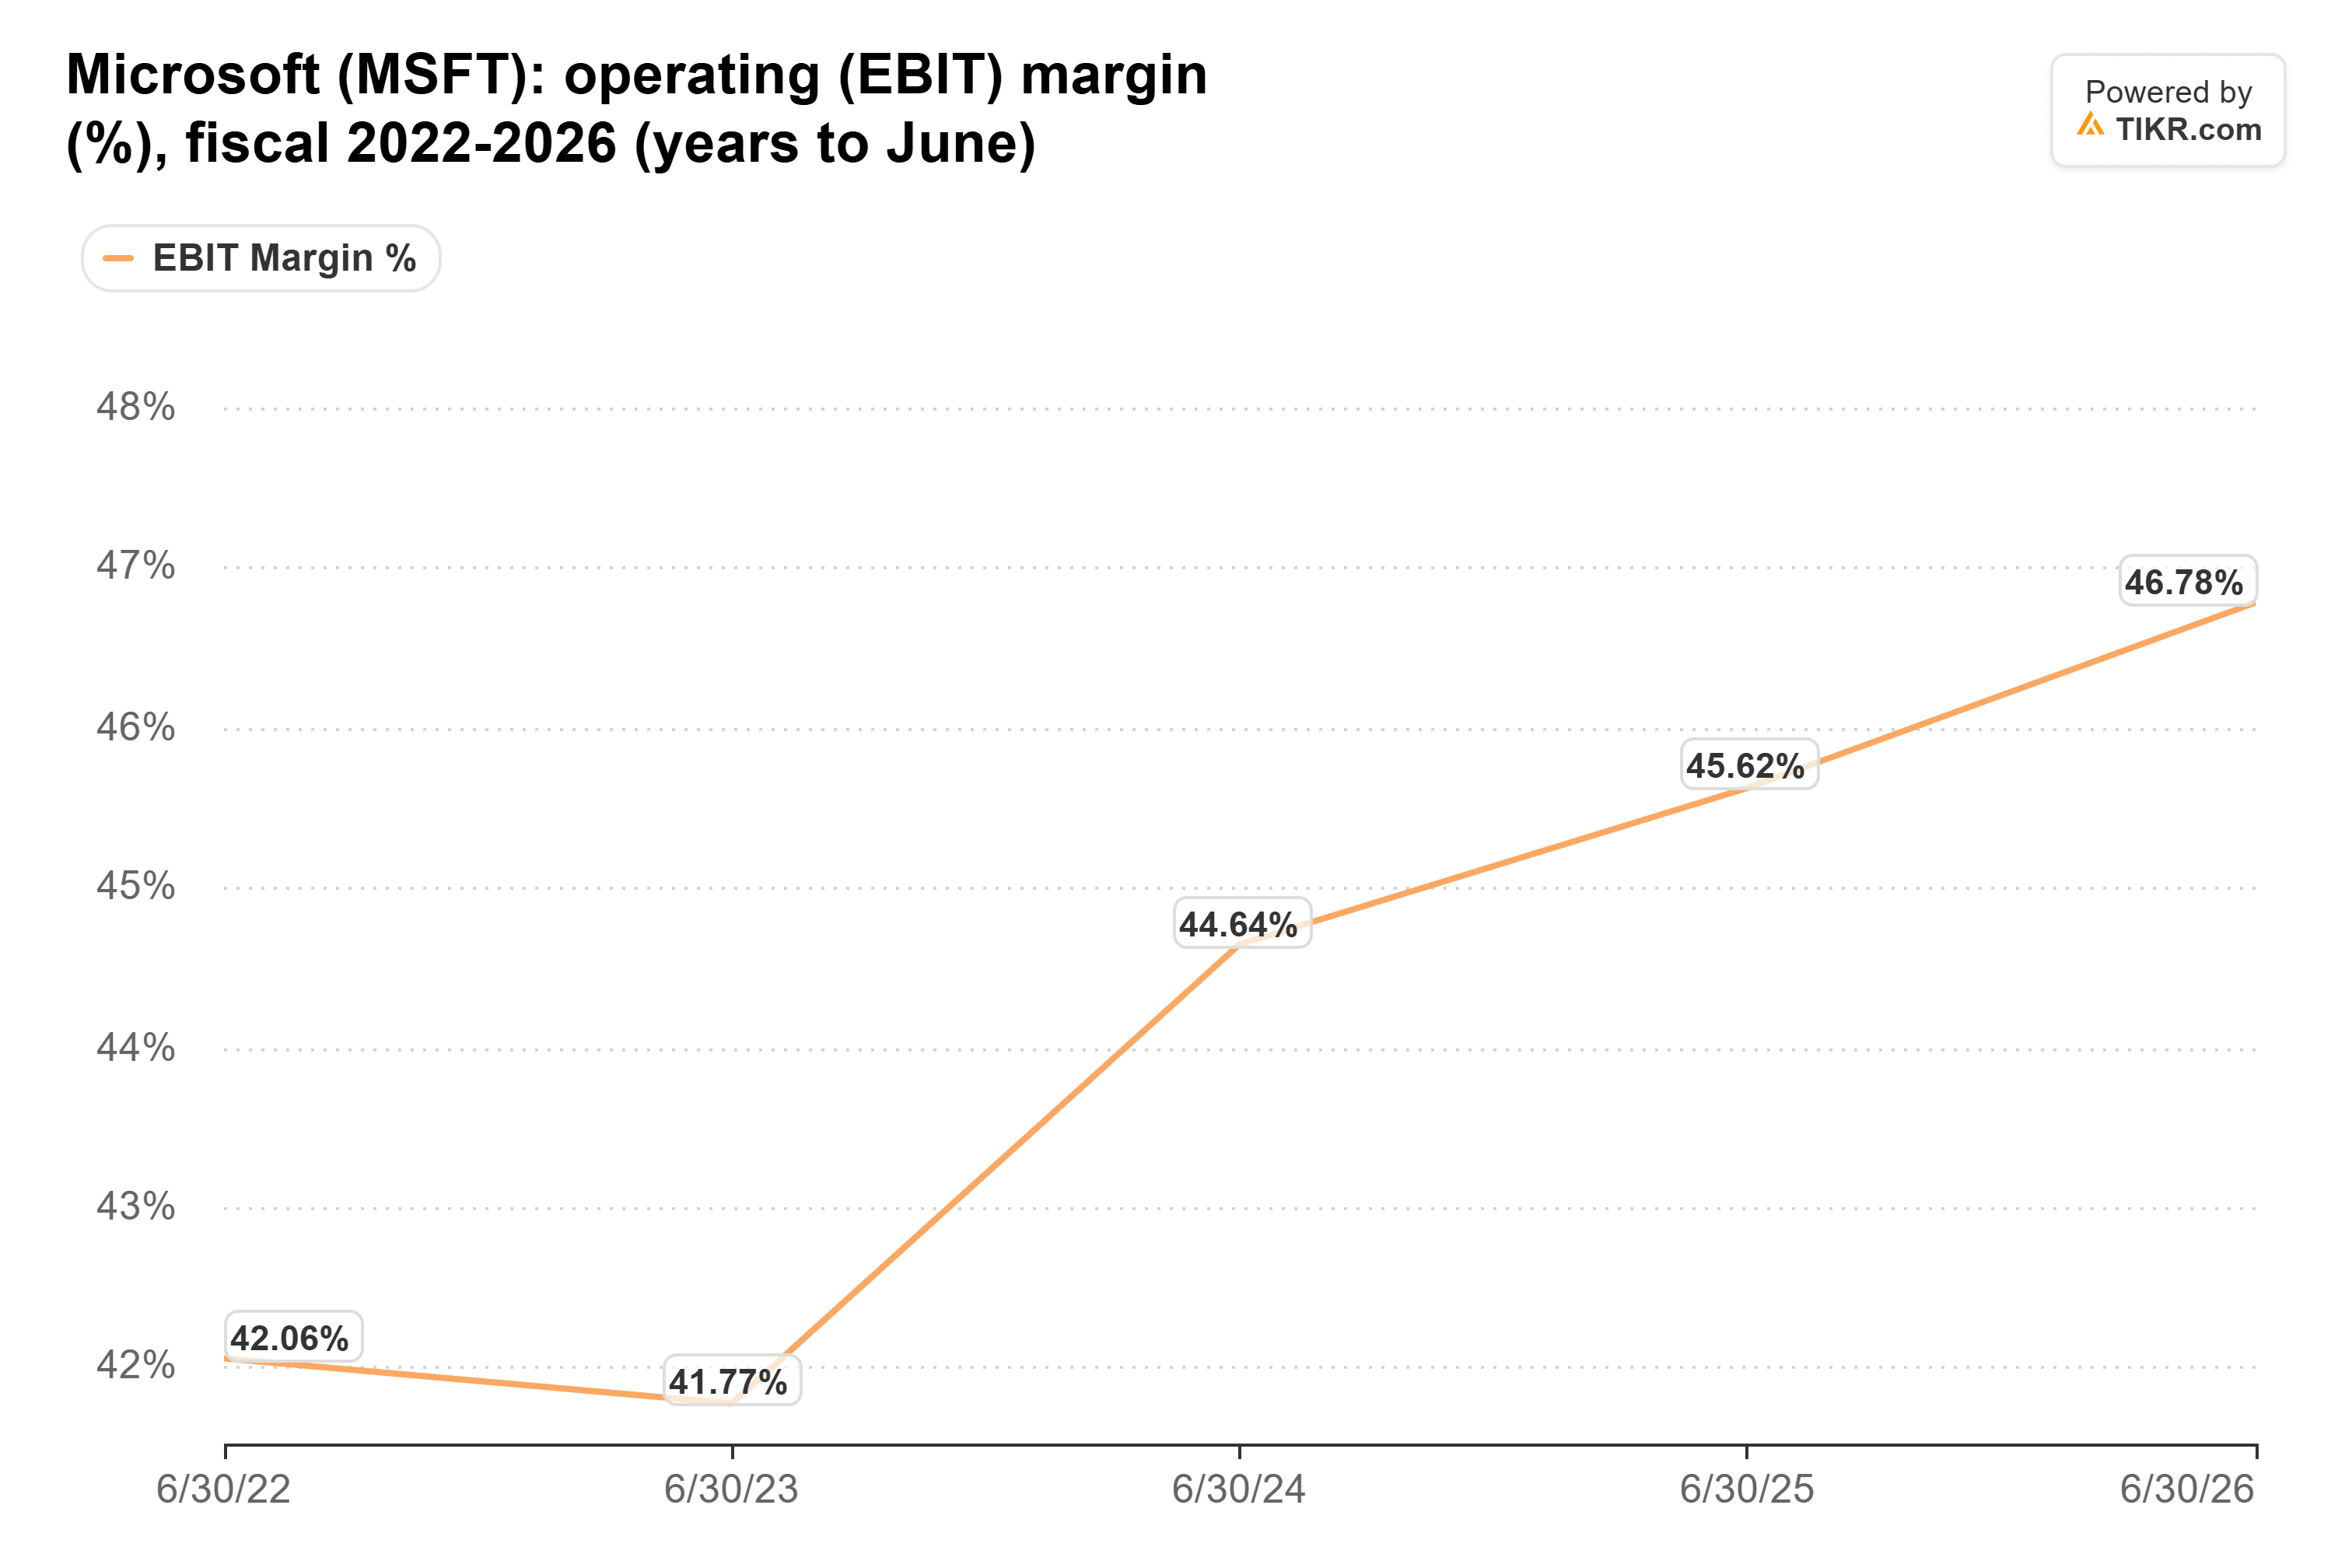
That margin is what Calacanis thinks Anthropic can chip away at. If Claude subscribers get a spreadsheet and a whiteboard thrown in, it gets harder for Microsoft to raise what it charges per seat.
Google has given this stuff away for years
Free rivals to Office aren’t new. Alphabet has offered Google Sheets and Docs at no charge for years, and Microsoft 365 kept growing anyway: in fiscal 2026, commercial revenue grew 16% and consumer revenue grew 24%.
Big companies also pay Microsoft for far more than the apps. Stifel analyst Brad Reback told clients he doesn’t “expect these products to have any meaningful impact on M365 growth rates for the foreseeable future.” He pointed to how deeply Microsoft is built into its enterprise customers and to its security and governance tools. A Claude subscription doesn’t replace the identity, compliance and admin controls that IT departments have spent years building around Microsoft.
Microsoft wins when Anthropic grows, too
Microsoft has a stake in Anthropic’s success. In November 2025, Microsoft agreed to invest up to $5 billion in Anthropic, and Anthropic committed to buy $30 billion of computing capacity on Azure. Microsoft booked a $3.2 billion gain on that stake in its June quarter, and Anthropic is now marketing its shares at a valuation of up to about $1.4 trillion.
So Calacanis is right that Microsoft is part of someone else’s bundle now: Anthropic’s compute bill.
The stock already trades at a discount
After the drop, Microsoft trades at 26x forward earnings. That’s below its five-year average of 29x and well off its 37x peak in July 2024.
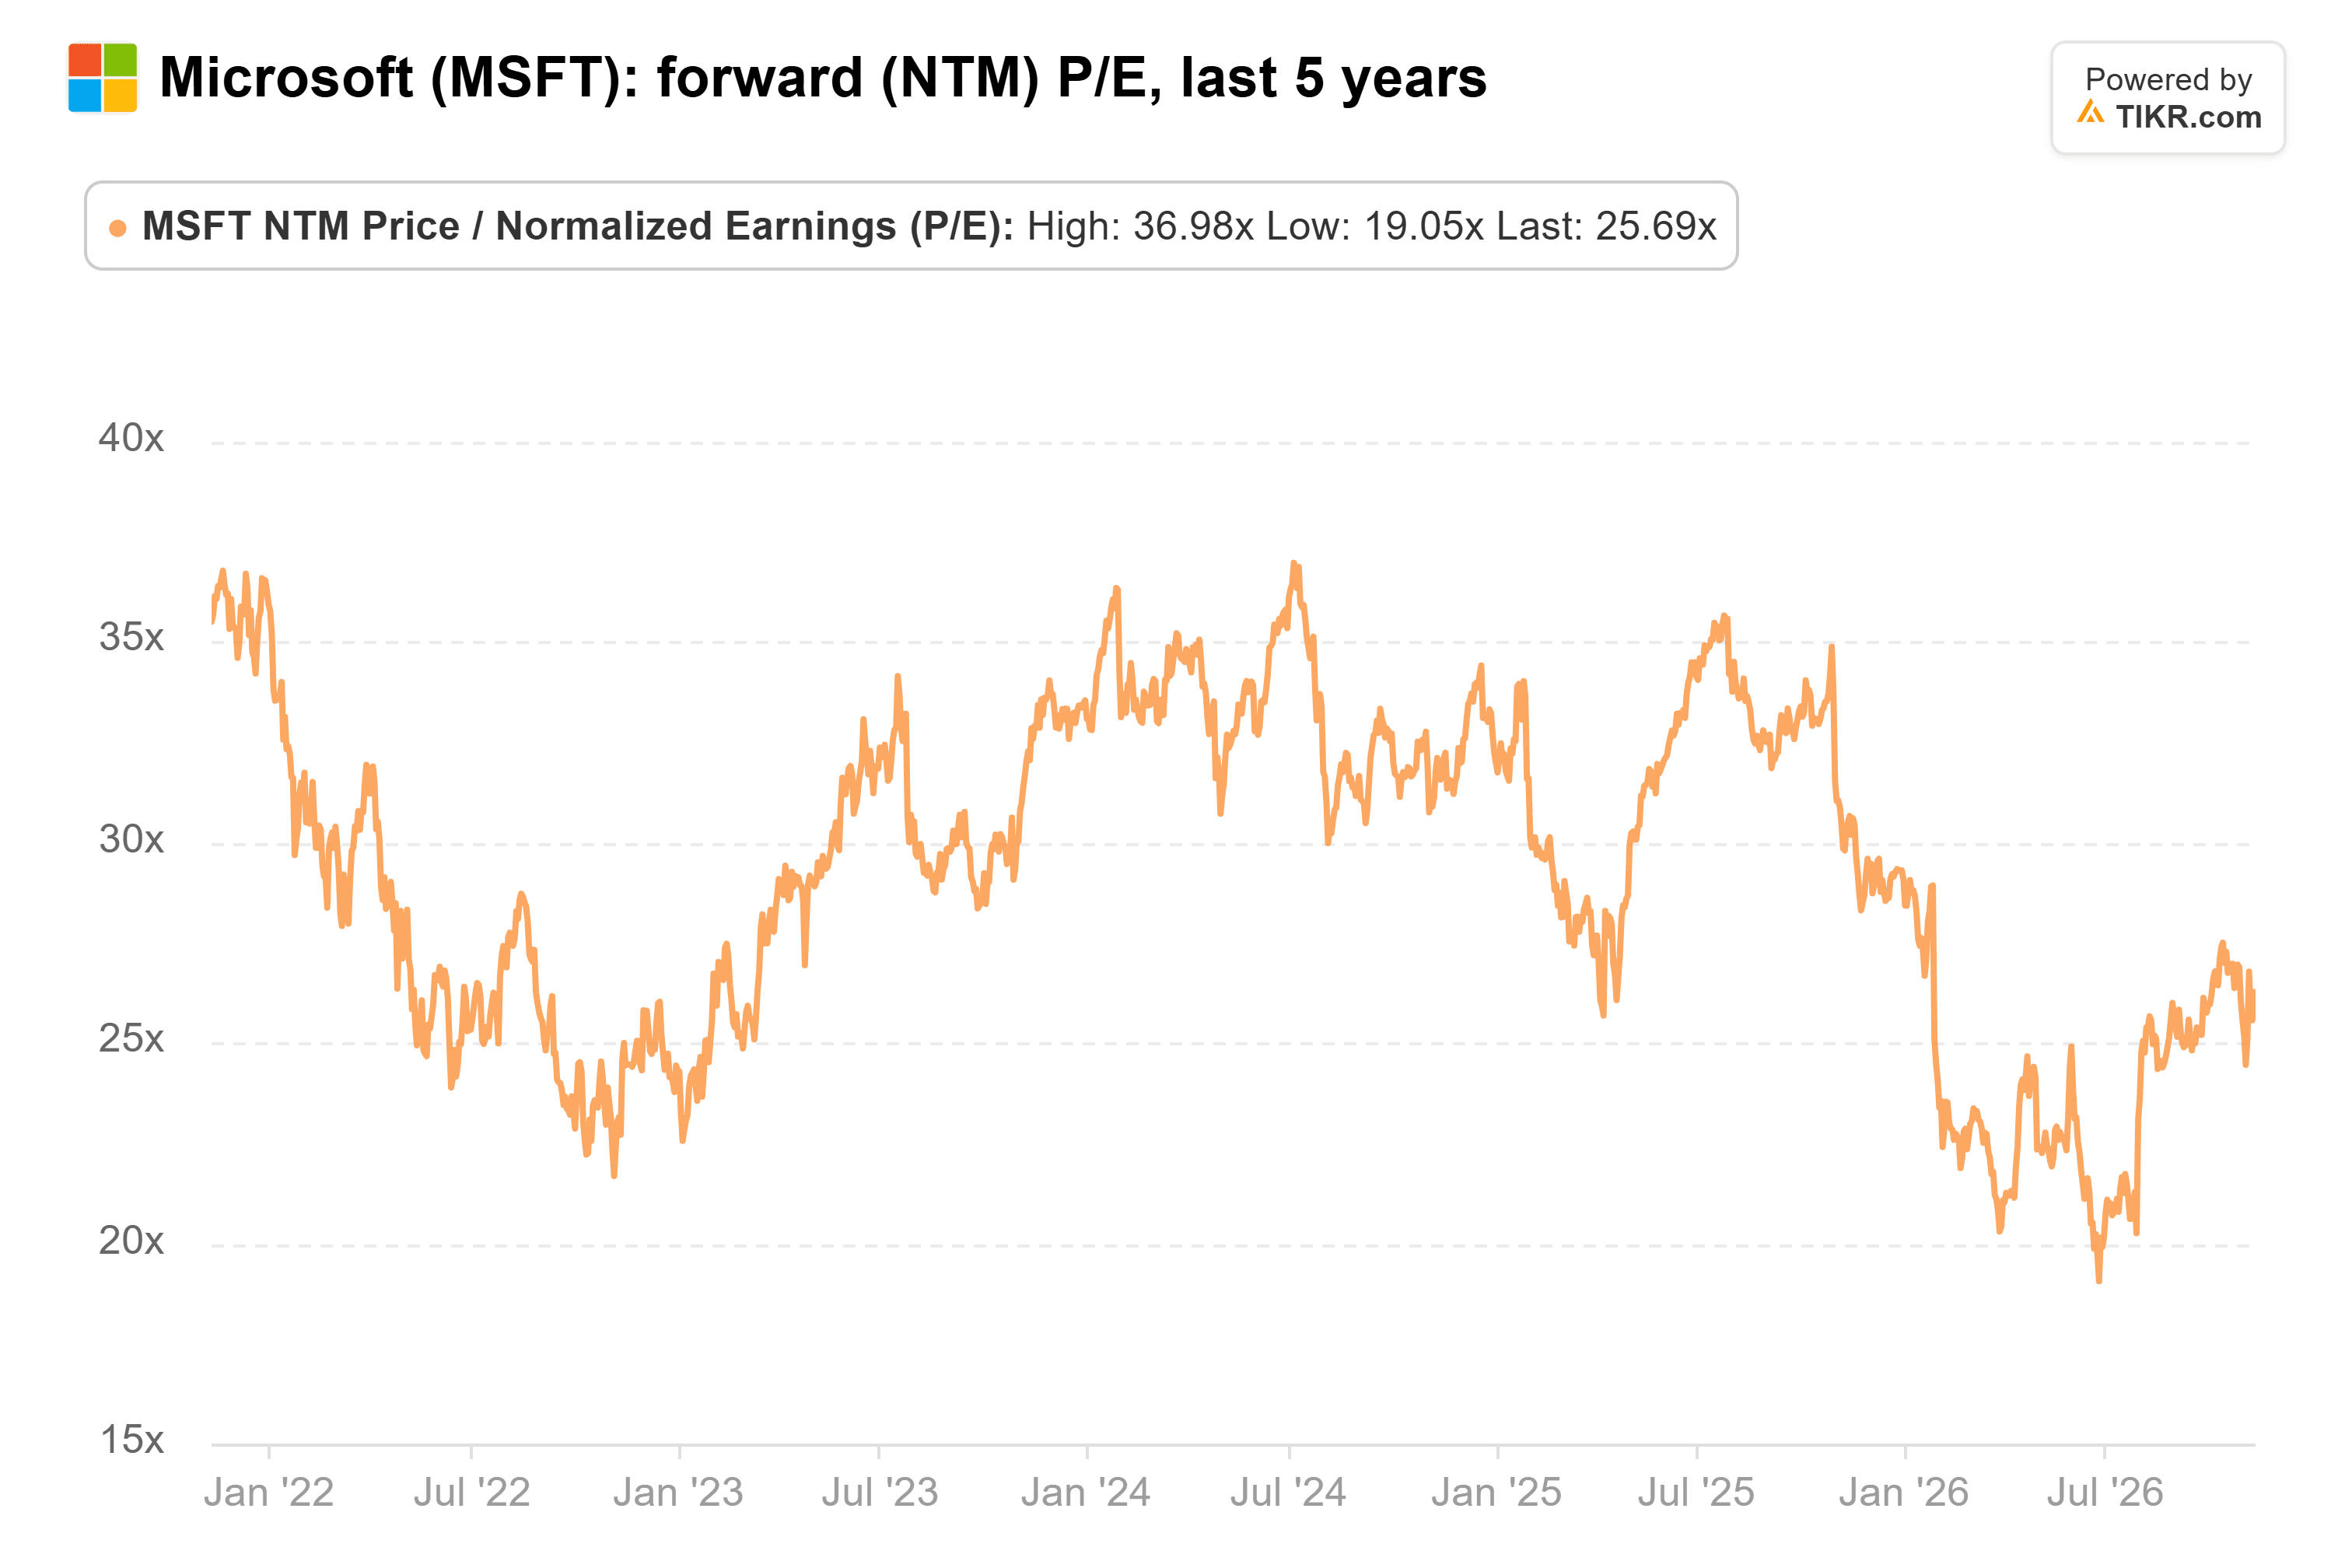
The way I see it, the market is overreacting. Microsoft 365’s growth just sped up, Microsoft’s margins are still rising, and the stock already trades below its usual multiple. The bigger long-term risk is AI agents doing more of the work, so companies need fewer Office seats. That would hurt, since Microsoft charges by the user.
Of course, Anthropic is just getting started. It has marked Claude Meetings as coming soon, and Calacanis is already betting that an Outlook rival comes next (“CLAUDE MAIL coming.”). If Anthropic goes after Outlook and Teams, the heart of Microsoft’s enterprise bundle, I’d take his warning a lot more seriously.
So what is Microsoft stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Microsoft could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!