Key Takeaways
- Micron president Scott DeBoer says Micron is targeting designs in half the time, and twice as many with the same staff.
- Micron lifted R&D 49% to $5.65 billion and still can’t serve every customer.
- Faster design won’t add wafers, but it could help Micron take on more custom work now and limit the R&D cost of each design in a downturn.
- Marvell reports Dec. 1 and Synopsys Dec. 8, ahead of Micron on Dec. 17.
Micron Technology (MU) is selling all the memory it can make. Now its president says AI lets it design that memory faster.
Scott DeBoer, Micron’s president, told TBPN on Nov. 18 that AI is “pervasive” in “all aspects of our product development right now.” Micron is “targeting to get designs done in half the time that we got done before. And able to do twice as many designs with the same number of people.”
Marvell Technology (MRVL) named Micron as a partner on custom high-bandwidth memory (HBM) for its AI chips in December 2024. Synopsys (SNPS) sells the software chipmakers use to verify designs, and verification is where DeBoer said AI was “just impactful right off the bat.”
Micron Still Can’t Say Yes to Everyone
DeBoer said Micron has “massively increased” R&D to “support more of the yes answer” for its big customers, co-designing memory for products three or four years out. Even so, “at times, we can’t support every customer.” Twice the designs per engineer would mean more yeses without matching hiring, and Marvell’s Dec. 1 report is the next read on custom HBM demand.
Micron’s R&D Is Up, but Revenue Is Up Far More
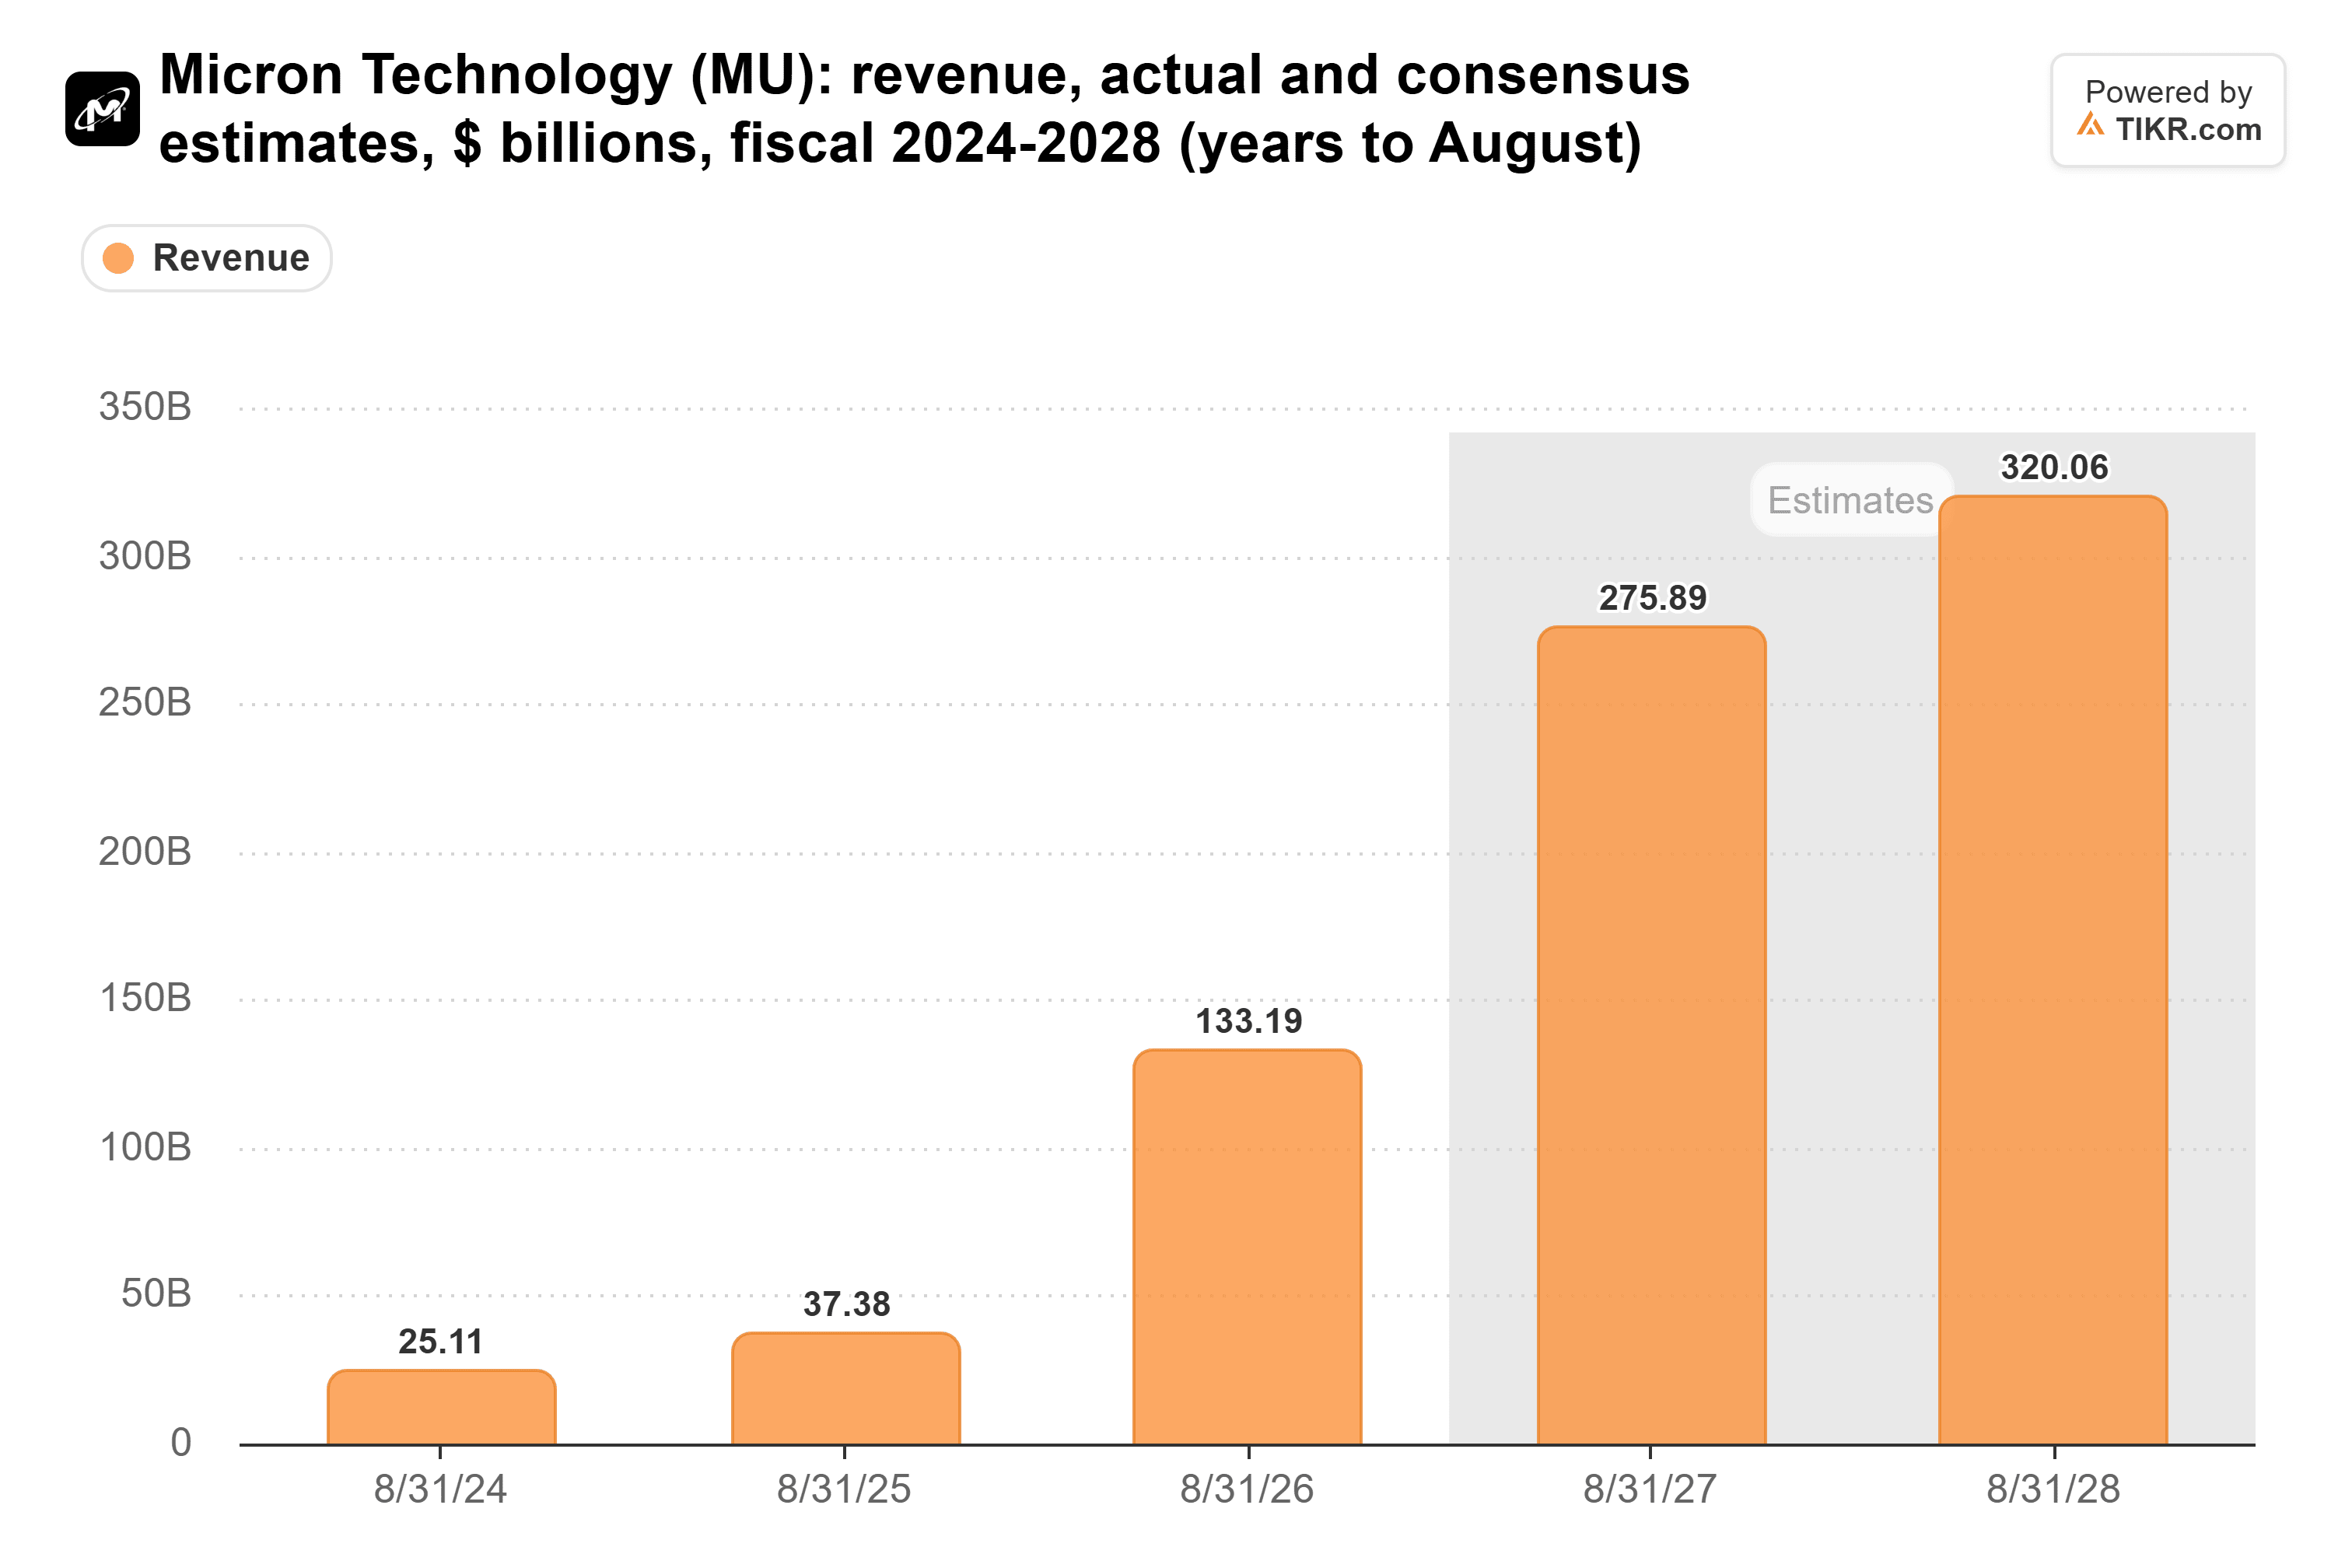
Revenue rose to $133.2 billion in fiscal 2026 from $37.4 billion, and analysts expect it to more than double again this fiscal year.
GAAP R&D expense climbed 49% to $5.65 billion in fiscal 2026, and Micron expects non-GAAP operating expenses to rise about $2.5 billion in fiscal 2027, primarily from higher R&D and incentive pay.
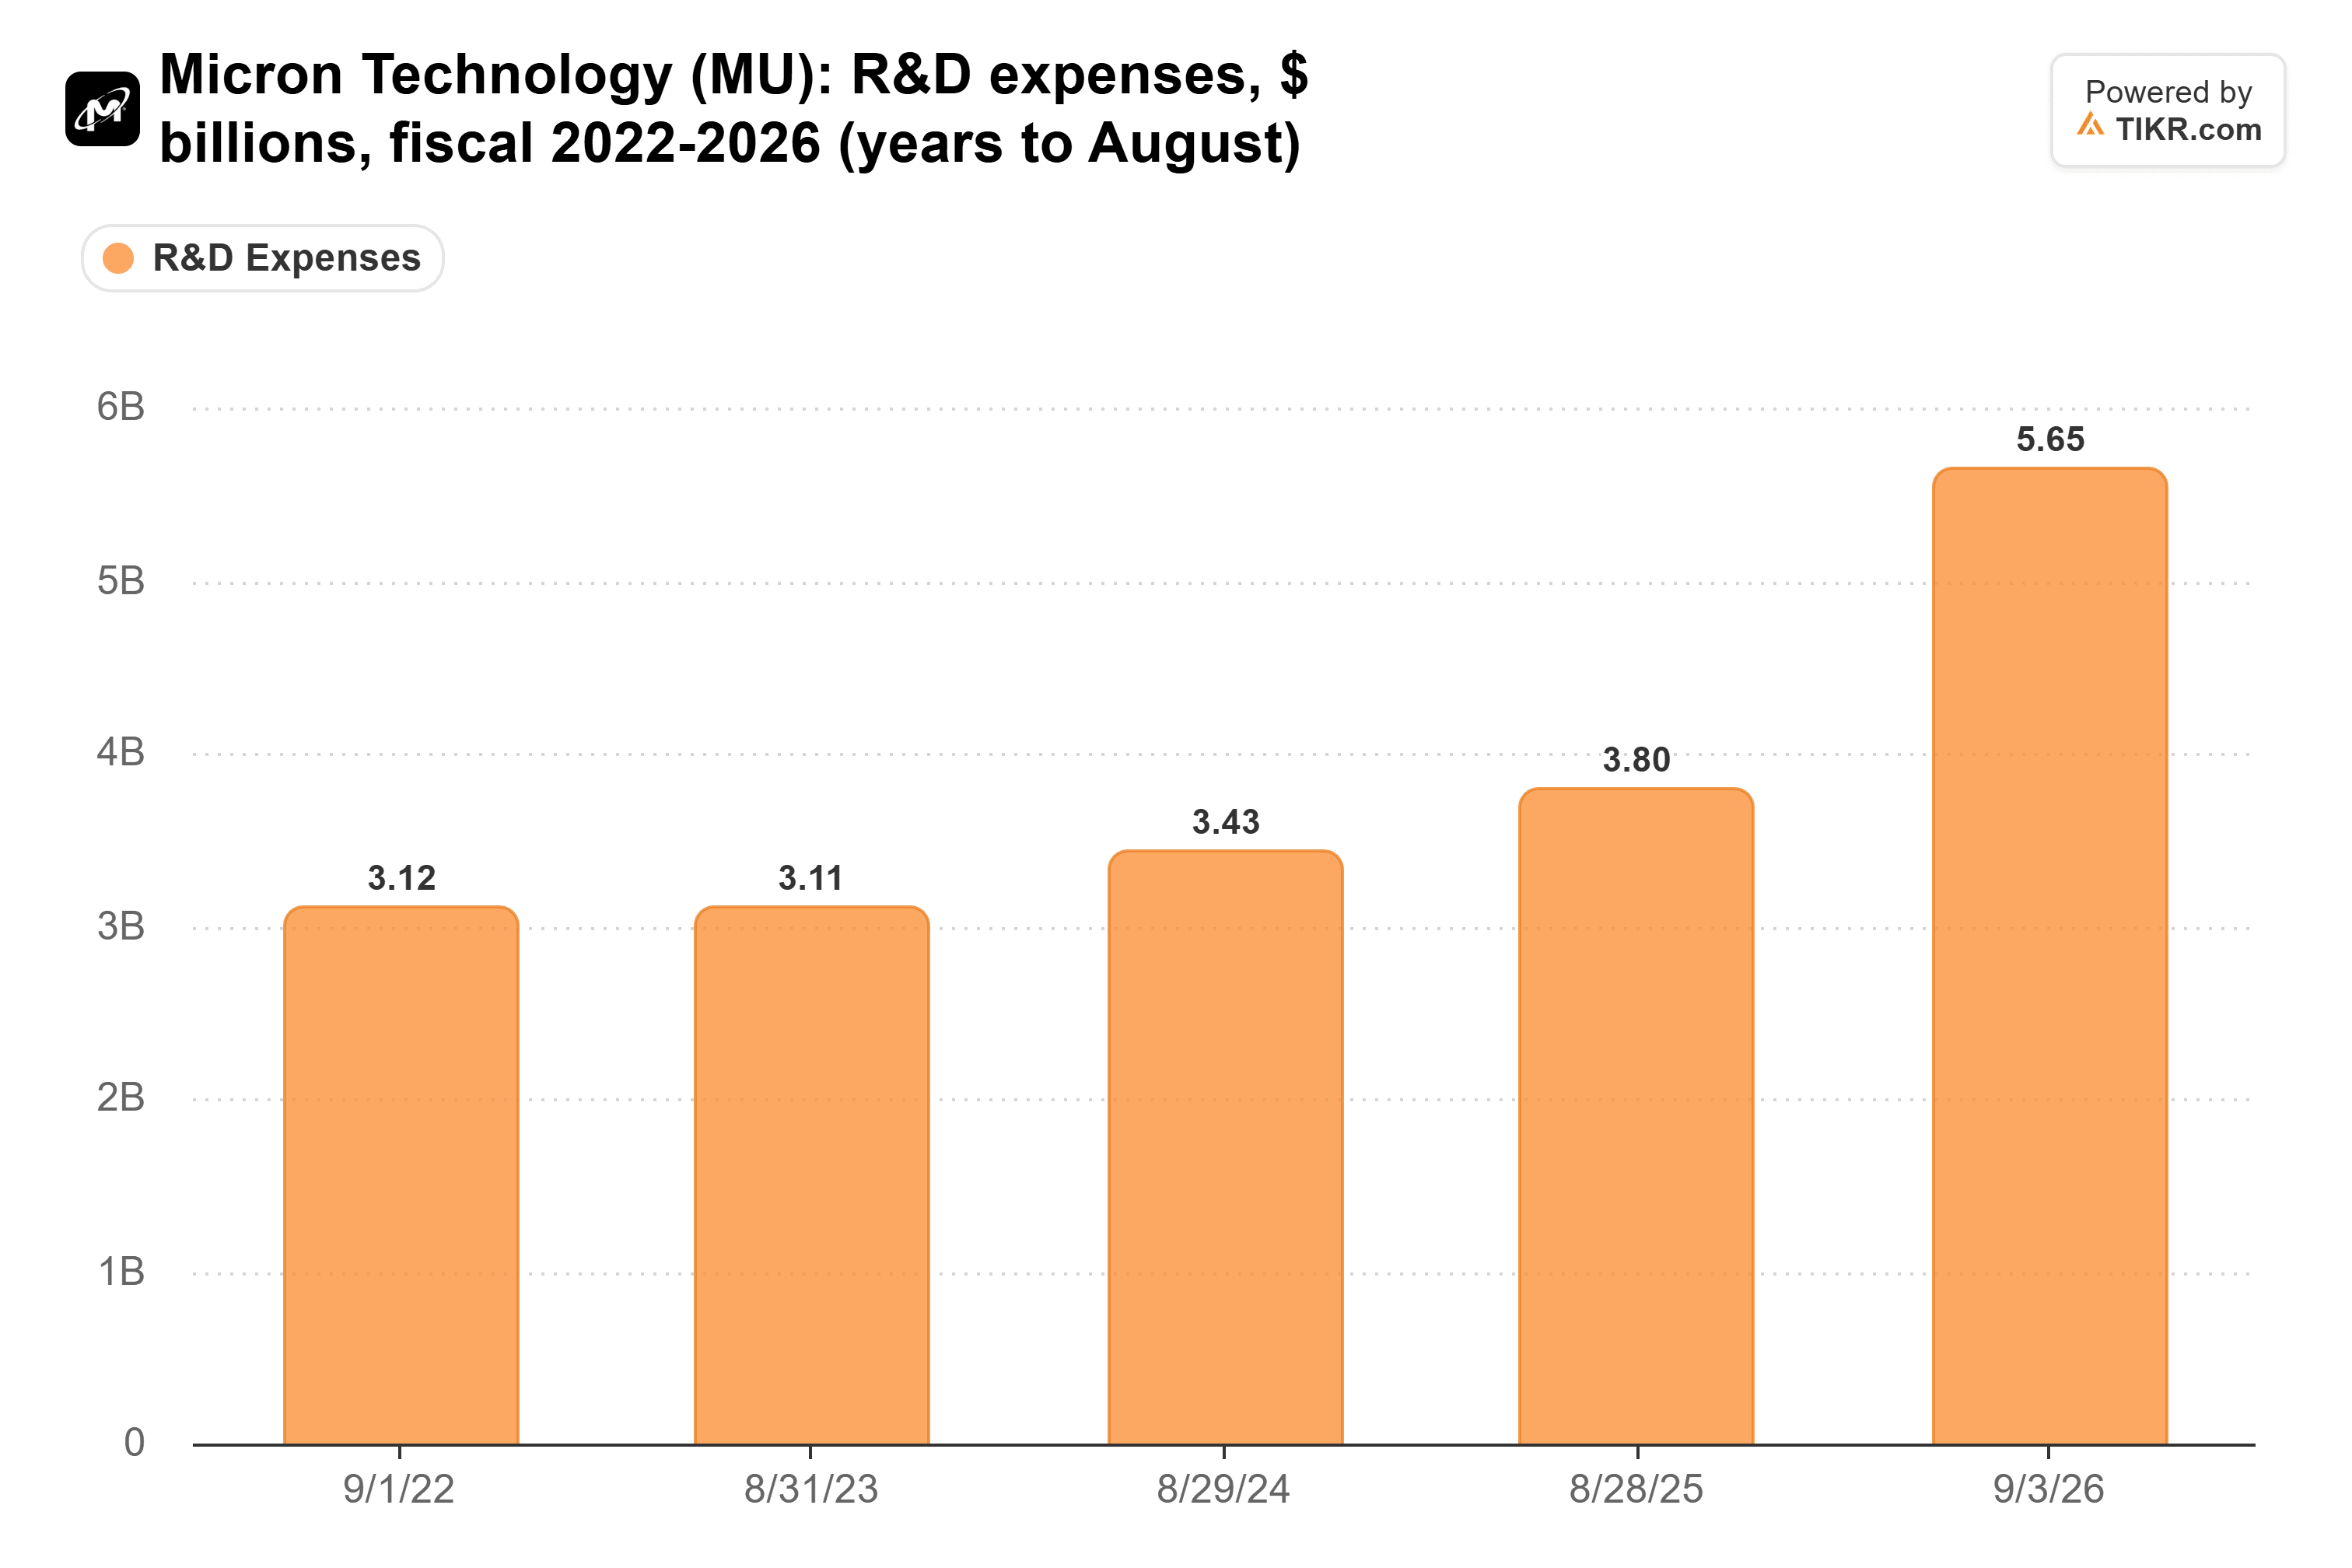
That’s only about 4% of revenue, down from about 10%, and Micron’s GAAP operating margin reached 74.6%.
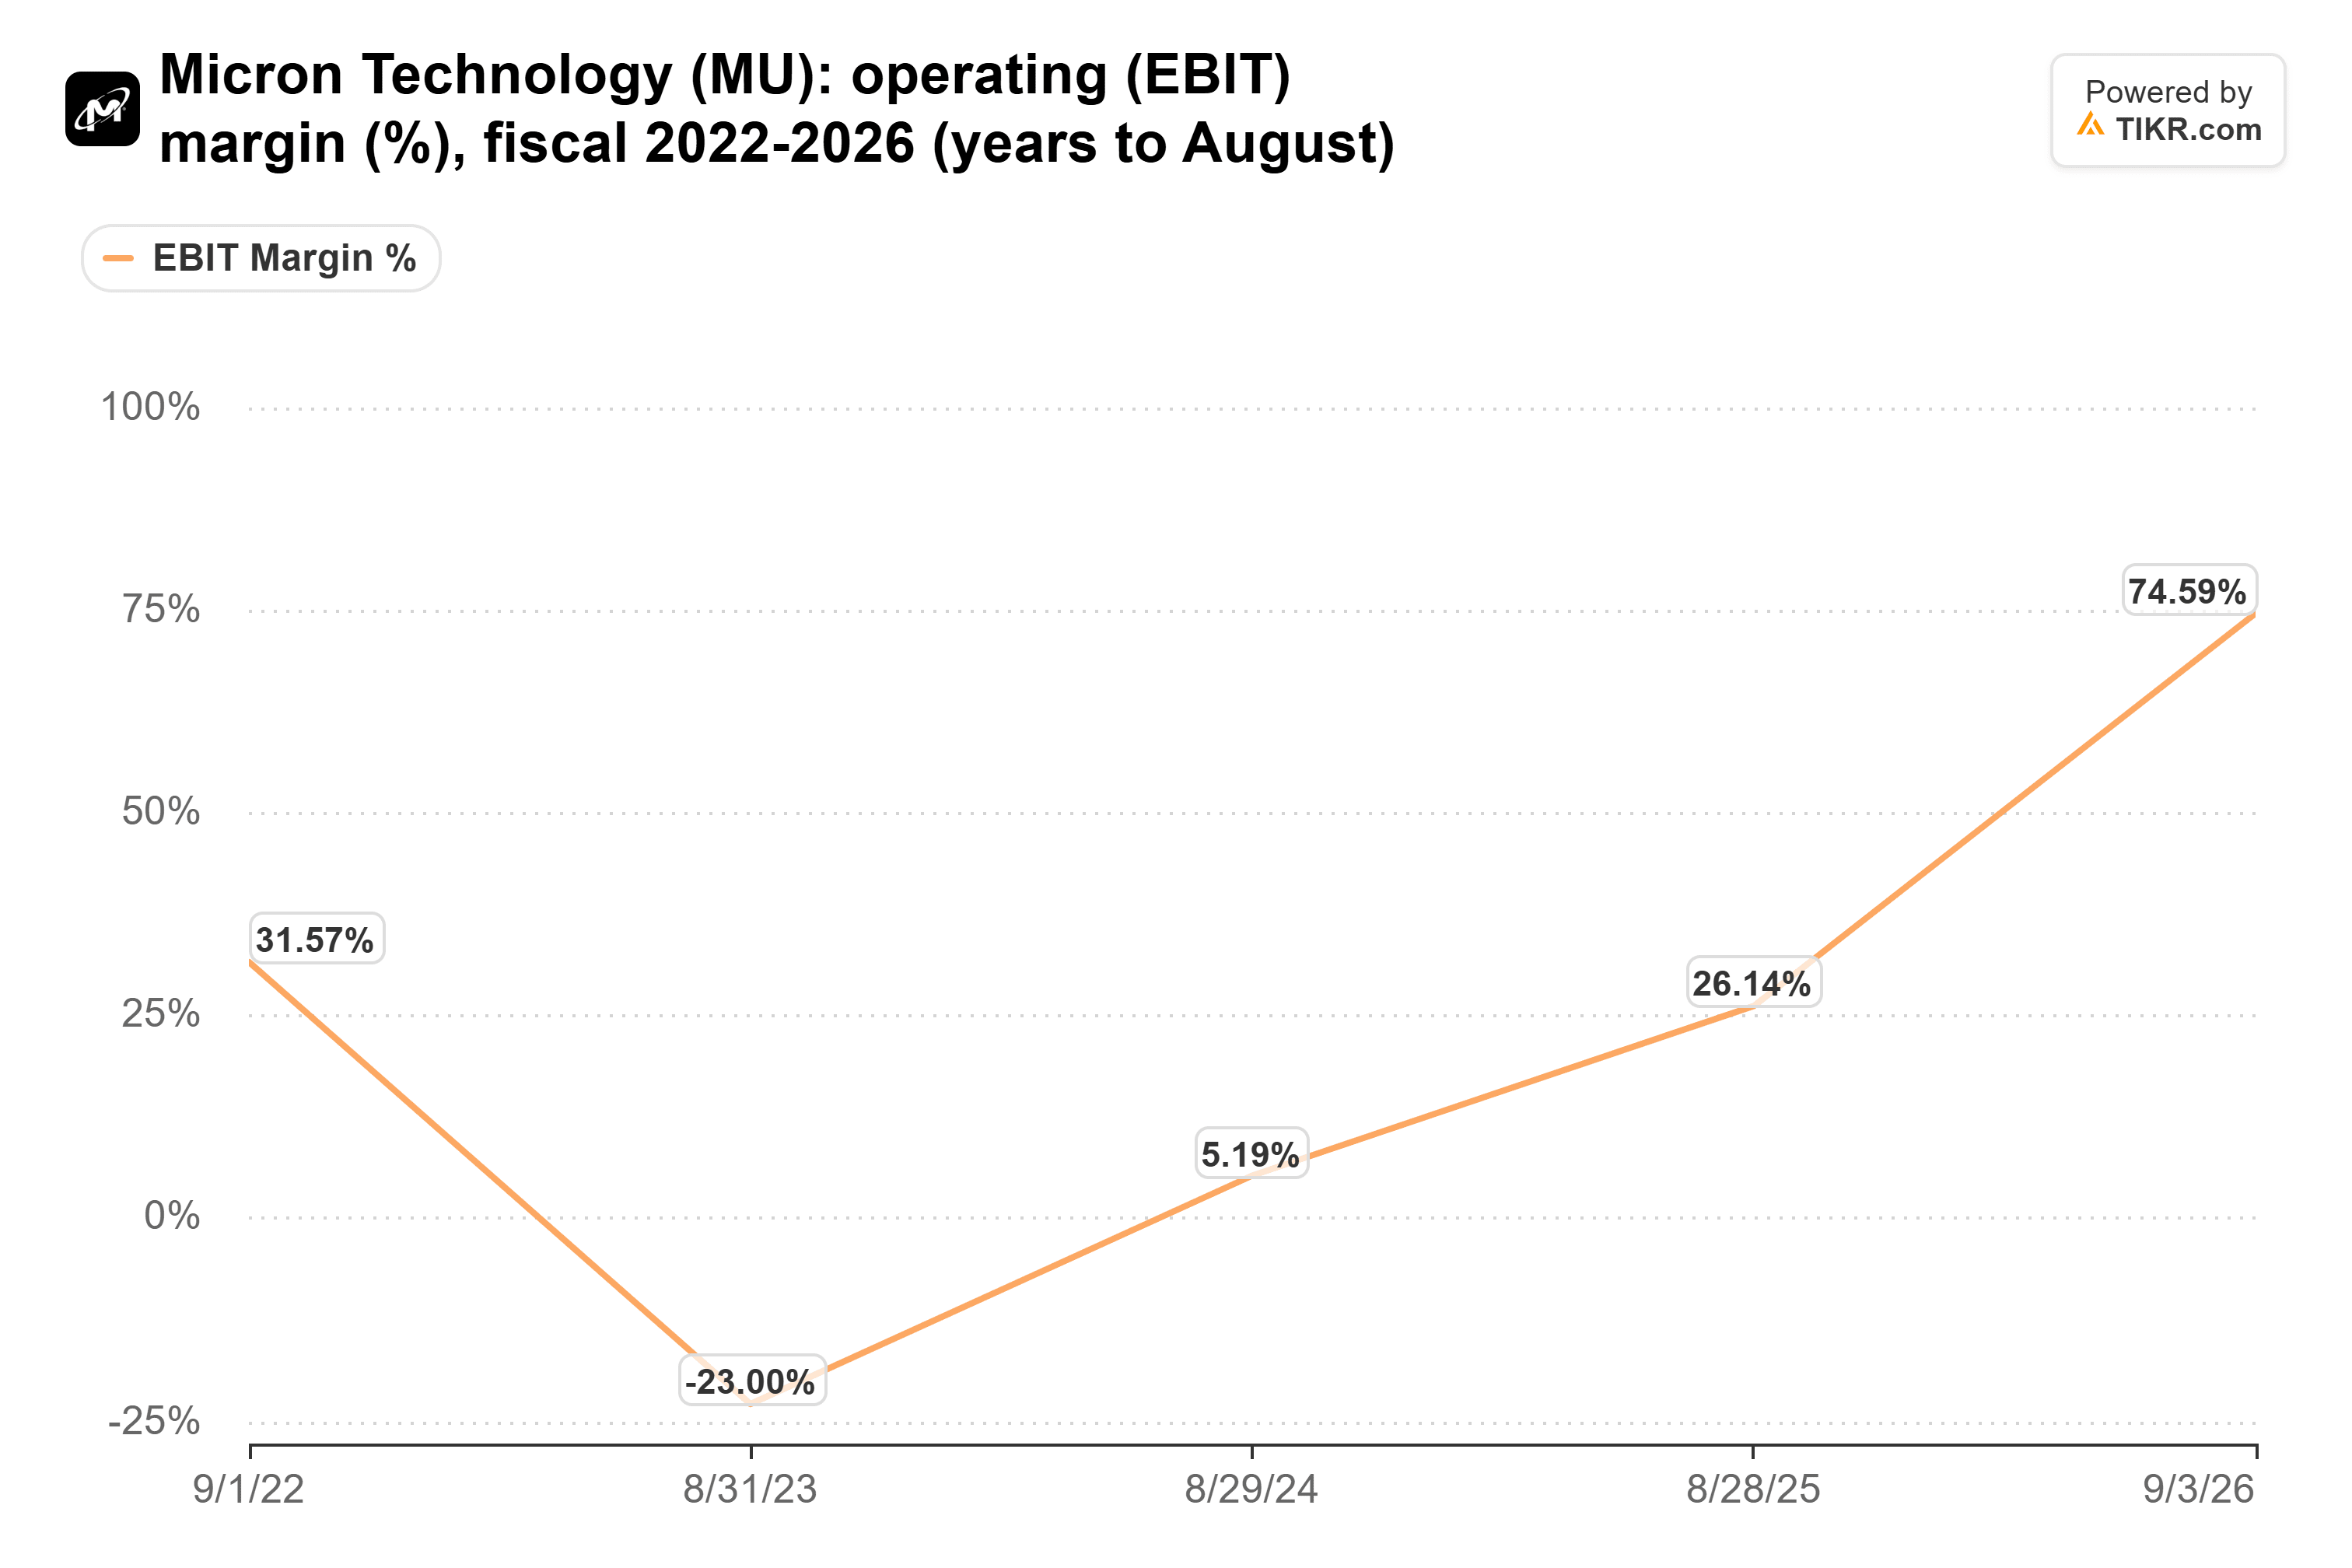
Spending isn’t a margin problem today.
TIKR Tracks 49 Analysts on Micron. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
Faster Designs Won’t Build More Fabs
DeBoer said “targeting,” with no date. Headcount is still growing: “even though we’re becoming more and more efficient, we’re also expanding our company in terms of people because it is a very labor intensive thing.” Faster design also doesn’t add wafers, the real limit on supply. DeBoer’s answer to “the tightness of memory across really multiple years now” is new fabs, and the first new Boise fab isn’t due to turn out wafers until mid-2027.
For Synopsys, the question is whether it gets paid for the designs or for the engineers. Its Dec. 8 report may tell.
Twice the Designs Pays Off in Micron’s Next Downturn
If Micron hits that target, it’s a real edge, and it matters most when memory prices fall. In fiscal 2023, revenue dropped to $15.5 billion, yet Micron still spent $3.11 billion on R&D (about a fifth of sales) and posted an operating loss of more than $5.7 billion. A team that does twice the custom work without twice the people could keep customers through the next slump without R&D eating the margin.
At 4.0x forward earnings on Nov. 19, against a five-year average of about 14x, the market is pricing the end of the cycle. That’s why Micron could out-earn Apple last quarter yet be worth 1/6 as much. Micron reports fiscal first-quarter results on Dec. 17. The proof would be shorter design cycles or more completed designs per engineer, and Micron hasn’t disclosed either number yet.
So What Is Micron Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!