Key Takeaways
- MercadoLibre reports third-quarter results after the close on Nov. 4, and analysts expect revenue to grow about 44% but EPS only 13%.
- The bull case depends on profit growth coming back, with consensus calling for normalized EPS to jump 46% in 2027 after a small dip this year.
- The operating margin fell to 6.7% in the second quarter from 12.2% a year earlier, and management has said it doesn’t expect that level to change much in the near term.
- The report has to show the margin has stopped falling, because investors paying 41x forward earnings are already paying for much of the 2027 rebound.
MercadoLibre (MELI) reports third-quarter results after the close today, Wednesday, Nov. 4. Its bulls need one thing from the report: proof that all that sales growth is turning back into profit.
The stock fell 10% in the week after Lula’s surprise win in Brazil’s Oct. 25 runoff. With the election settled, investors are left with one question: can earnings grow fast enough to carry the stock?
The bull case is a 2027 story
Analysts expect normalized EPS to slip to $38.26 this year from $39.40 in 2025. After that they expect it to jump to $55.89 in 2027 and $78.56 in 2028, nearly double last year’s figure:

Analysts have been moving the other way, though. Between September 2025 and October 2026, they cut their 2026 EPS estimate by 42% while raising their 2026 revenue estimate by 17%. MercadoLibre has delivered the sales analysts hoped for, and less of the profit.
TIKR tracks 26 analysts on MercadoLibre. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
The margin is still sliding
The bull case needs the operating margin to turn. Instead, it has fallen by more than half since mid-2024, from 14.3% to 6.7%:

Second-quarter revenue rose 50% to $10.2 billion, the fastest growth in four years, while operating income fell 17% to $683 million. Across MercadoLibre’s four country segments, profit before corporate costs was $2,948 million in the first half of 2026. A year earlier it was $2,950 million, on 49% less revenue.
All that extra scale went straight back into the business.
Most of the spending has gone into three things:
- Free shipping in Brazil, where MercadoLibre lowered its free-shipping threshold to R$19 from R$79 in June 2025.
- The Mercado Pago credit card, which still lost money after funding costs and loan losses in the second quarter.
- Keeping Amazon and Shopee from taking market share.
Management isn’t promising a quick turn. In May it said it didn’t expect the margin to change materially in the near term. On the second-quarter call, it said the company’s strong cash generation and profitability “give us the confidence to keep investing at the pace we are.”
What earnings tonight have to show
The bar is a good bit lower than you might think. Consensus expects about $10.7 billion of revenue, up about 44% from $7.4 billion a year ago, and EPS of $9.41, up 13% from $8.32. Analysts can only get 13% EPS growth out of 44% revenue growth if they expect a margin well below the 9.8% of the third quarter of 2025. Their full-year numbers imply about 7% for the second half.
So the test is whether the margin holds at or above the second quarter’s 6.7%. Around 7% or better says the slide has stopped. Below 6.7% would mean costs are still rising faster than revenue, and 2027 estimates would likely come down. Brazil’s segment margin, which improved to 9.9% in the second quarter from 8.1% in the first, is the other number to check.
A surprise in loan losses, or a weaker real after Lula’s win, could move the stock more than a point of margin. MercadoLibre’s fintech chief said he isn’t seeing deterioration in Brazil credit, and the report will show whether that held up.
41x earnings? Give me margins
After the drop, the forward P/E is well below its five-year average:
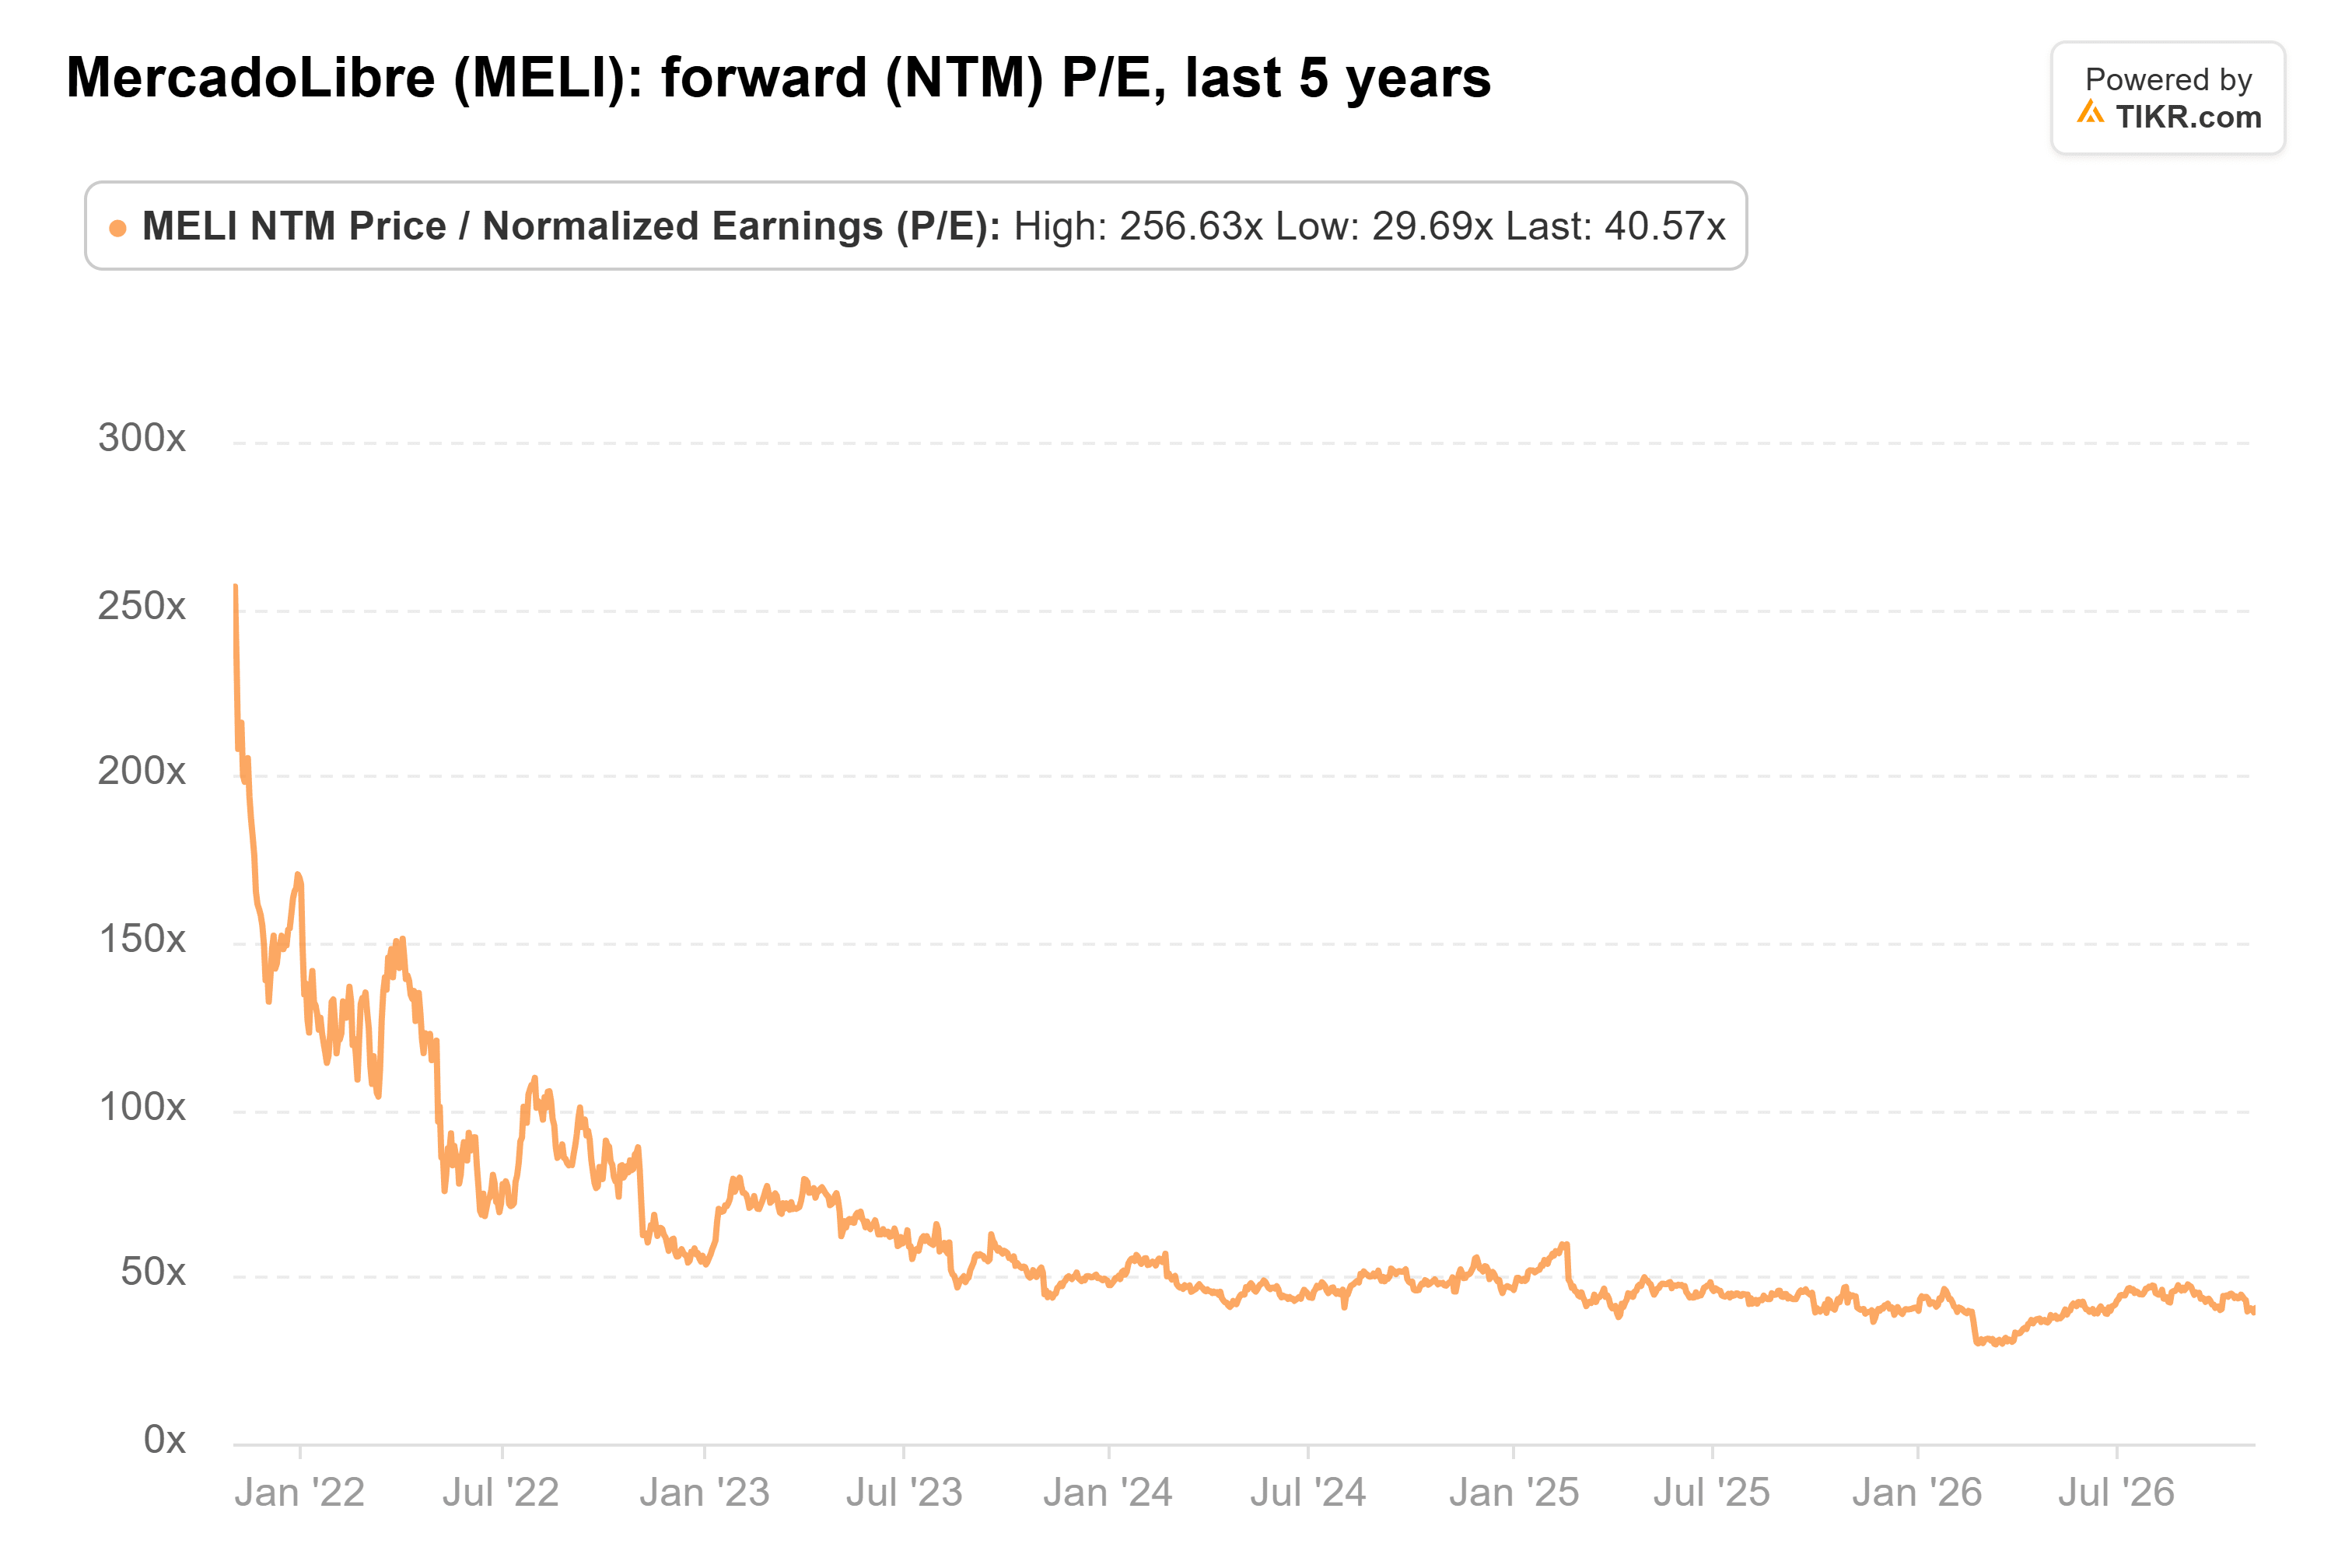
It’s at 41x, against a 63x average that includes 2021’s 257x peak, and it got as low as 30x in March. Next-twelve-months earnings now come mostly from 2027’s estimate, so investors paying 41x are already paying for much of that 46% jump. If the report pushes 2027 estimates down, the stock gets more expensive at the same price.
Here’s where I land: I’d want to see the margin stop falling before paying 41x for a rebound that management itself says isn’t coming soon. If the margin comes in around 7% or better on Nov. 4, the 2027 estimates look reachable. Below 6.7%, I’d expect them to come down.
Even after a good quarter, investors won’t have the whole answer. MercadoLibre doesn’t give guidance, so the fourth-quarter letter early next year will show how hard it plans to invest in 2027.
So what is MercadoLibre stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!