Key Takeaways
- Micron’s president says memory is no longer a commodity, yet the stock trades at about 3.4x fiscal 2027 consensus earnings.
- Analysts expect earnings per share to more than double in fiscal 2027.
- The bear case rests on past busts and a NAND glut next year, which hits Sandisk hardest.
- I think the stock is too cheap, and the December report is the next test.
Micron Technology (MU) booked $85.0 billion of GAAP net income in fiscal 2026. Its stock still fell 13.89% on Friday, November 20, to $594.51, less than half its June 25 record close of $1,213.56 and about 3.4 times fiscal 2027 consensus earnings.
AMD (AMD), which pairs high-bandwidth memory (HBM) with its AI accelerators, fell 13.25% the same day, even after its Data Center revenue jumped 97% last quarter. NAND specialist Sandisk (SNDK) faces a bigger threat: a glut next year.
Micron’s president, Scott DeBoer, says the business has changed. “When memory was a commodity even five years ago, but certainly through history, memory had a very different role,” he said on TBPN on November 18. “And we’re just at the beginning of AI.”
Somebody’s wrong.
The Estimates Keep Climbing
Consensus normalized EPS more than doubles from $75.52 in fiscal 2026 to $176.50 in fiscal 2027, then reaches $207.76 in fiscal 2028.
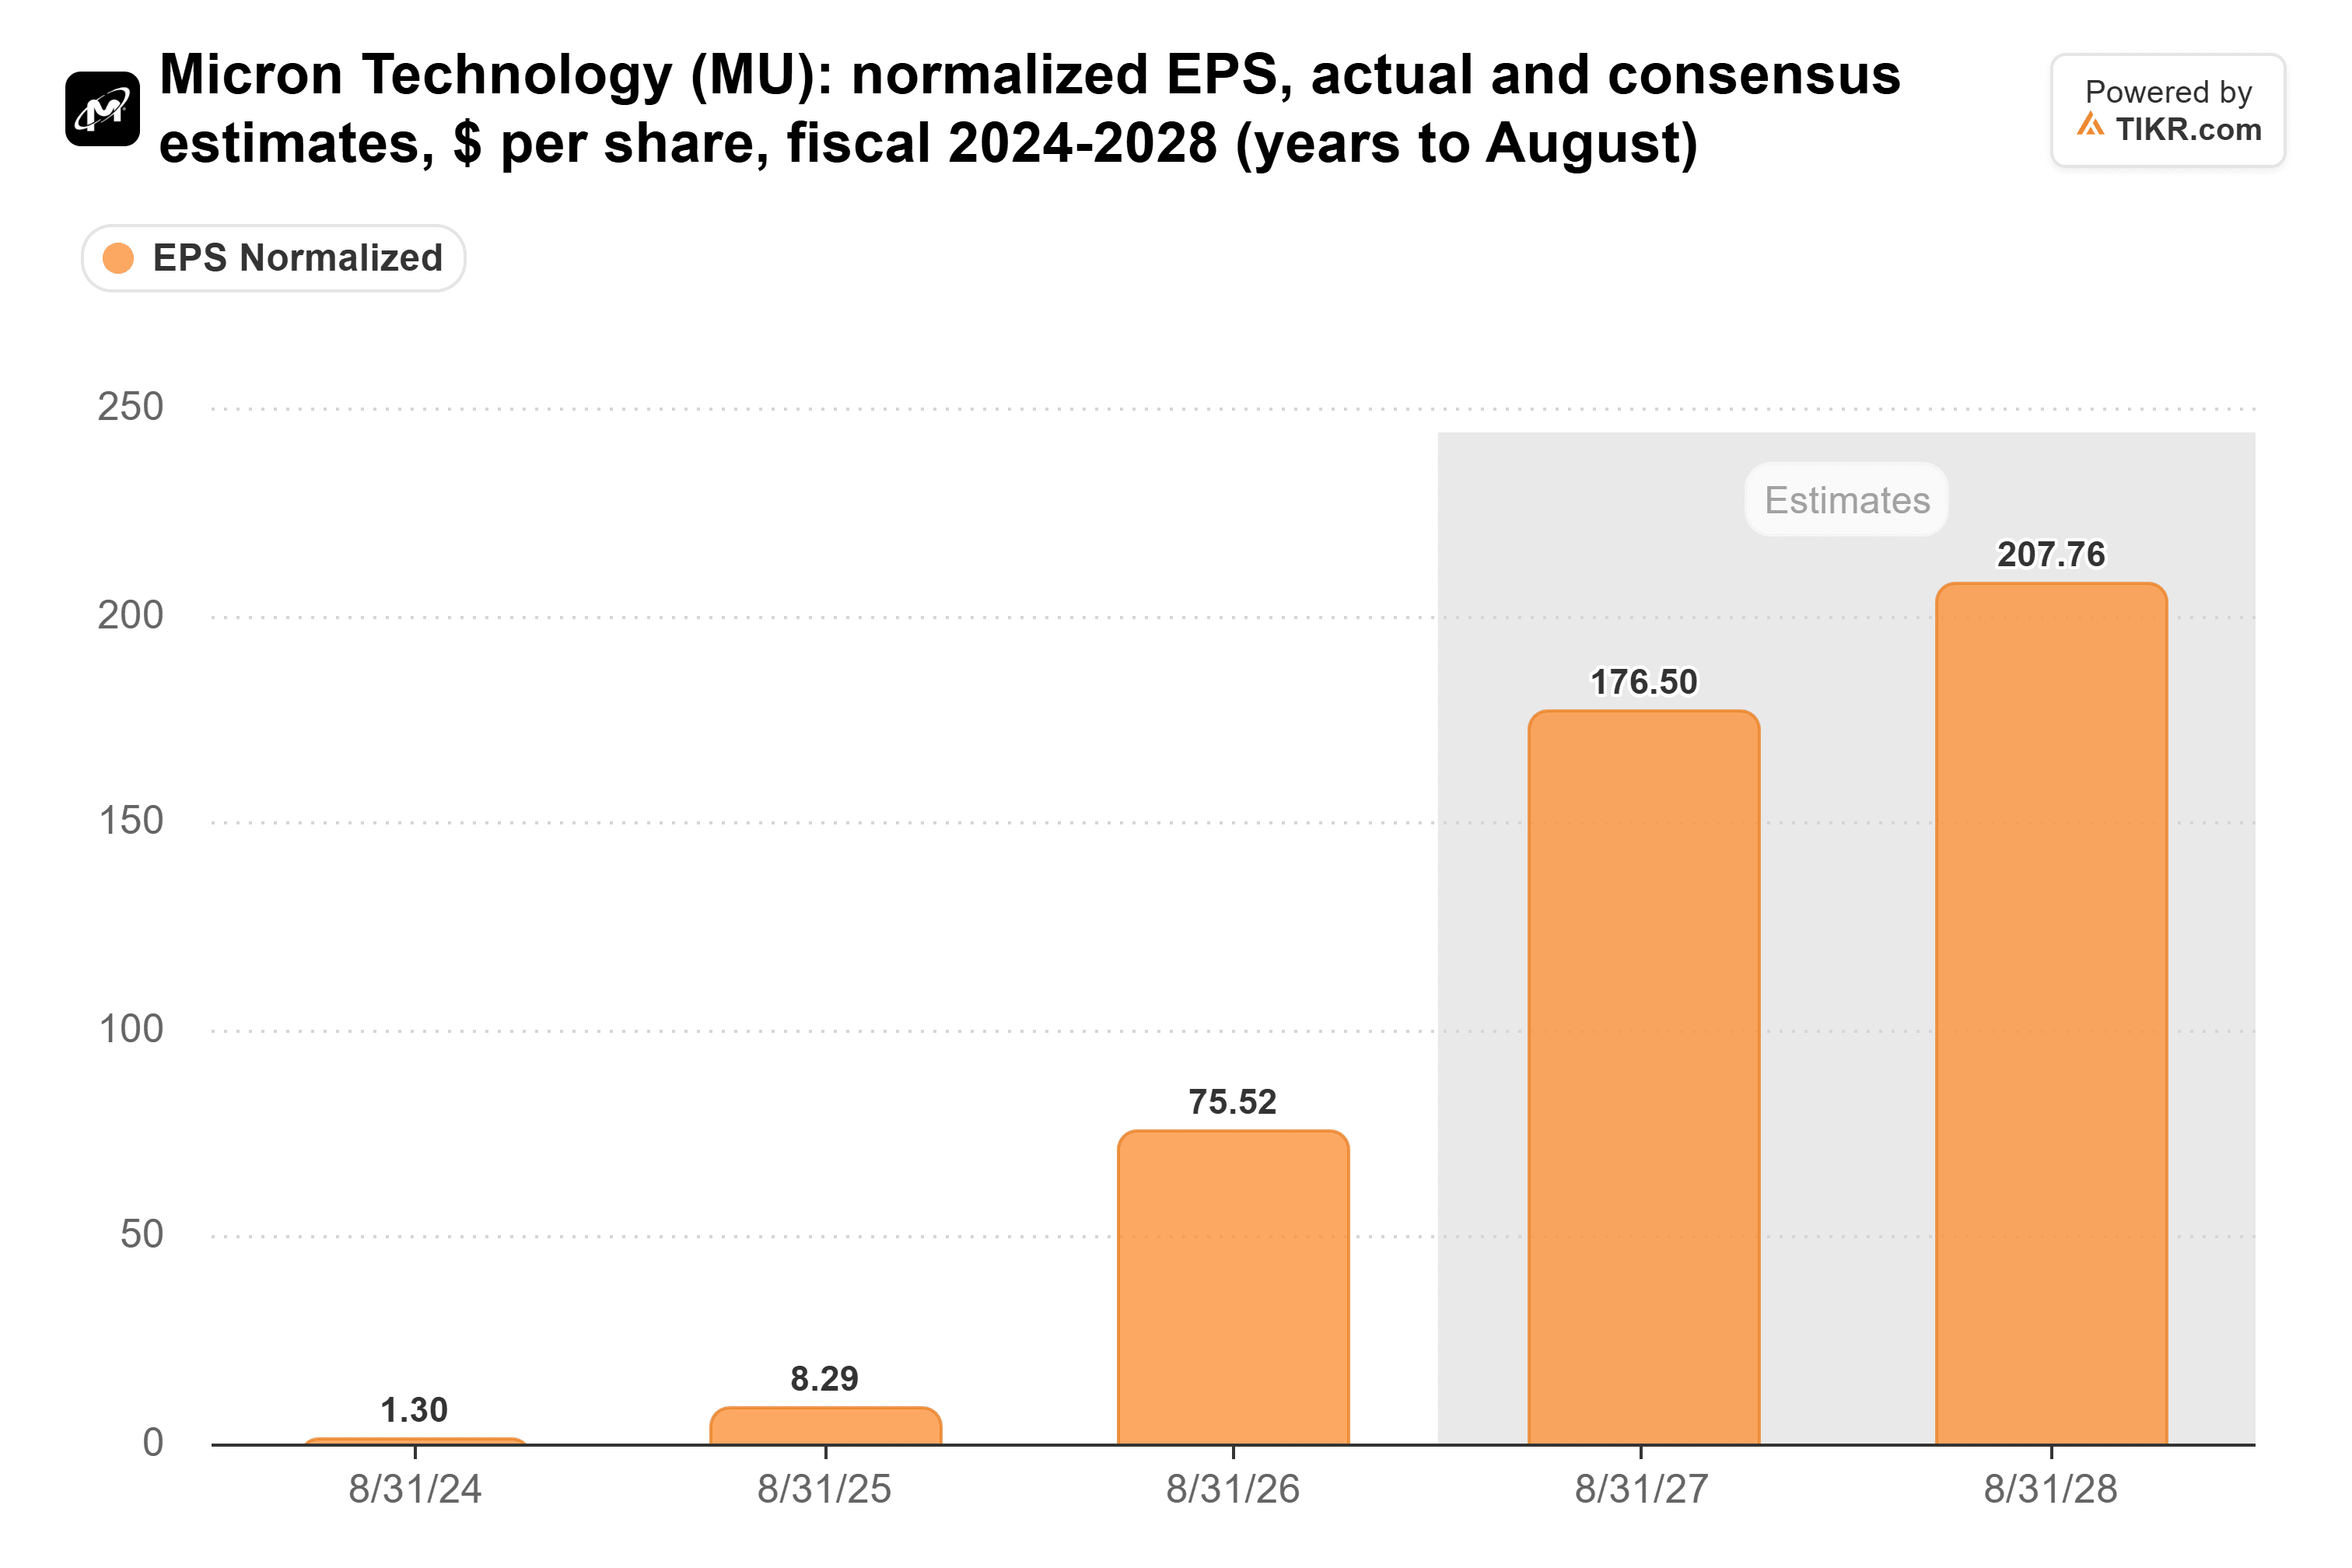
Add the next two years together, and Micron would earn about $384 a share, nearly two-thirds of Friday’s close. The market is betting those estimates won’t hold.
Micron’s Last Busts Still Haunt the Stock
Micron’s GAAP gross margin fell from 45.2% in fiscal 2022 to negative 9.1% in fiscal 2023. Even without the net effect of inventory write-downs, it would have been negative 2.8%.
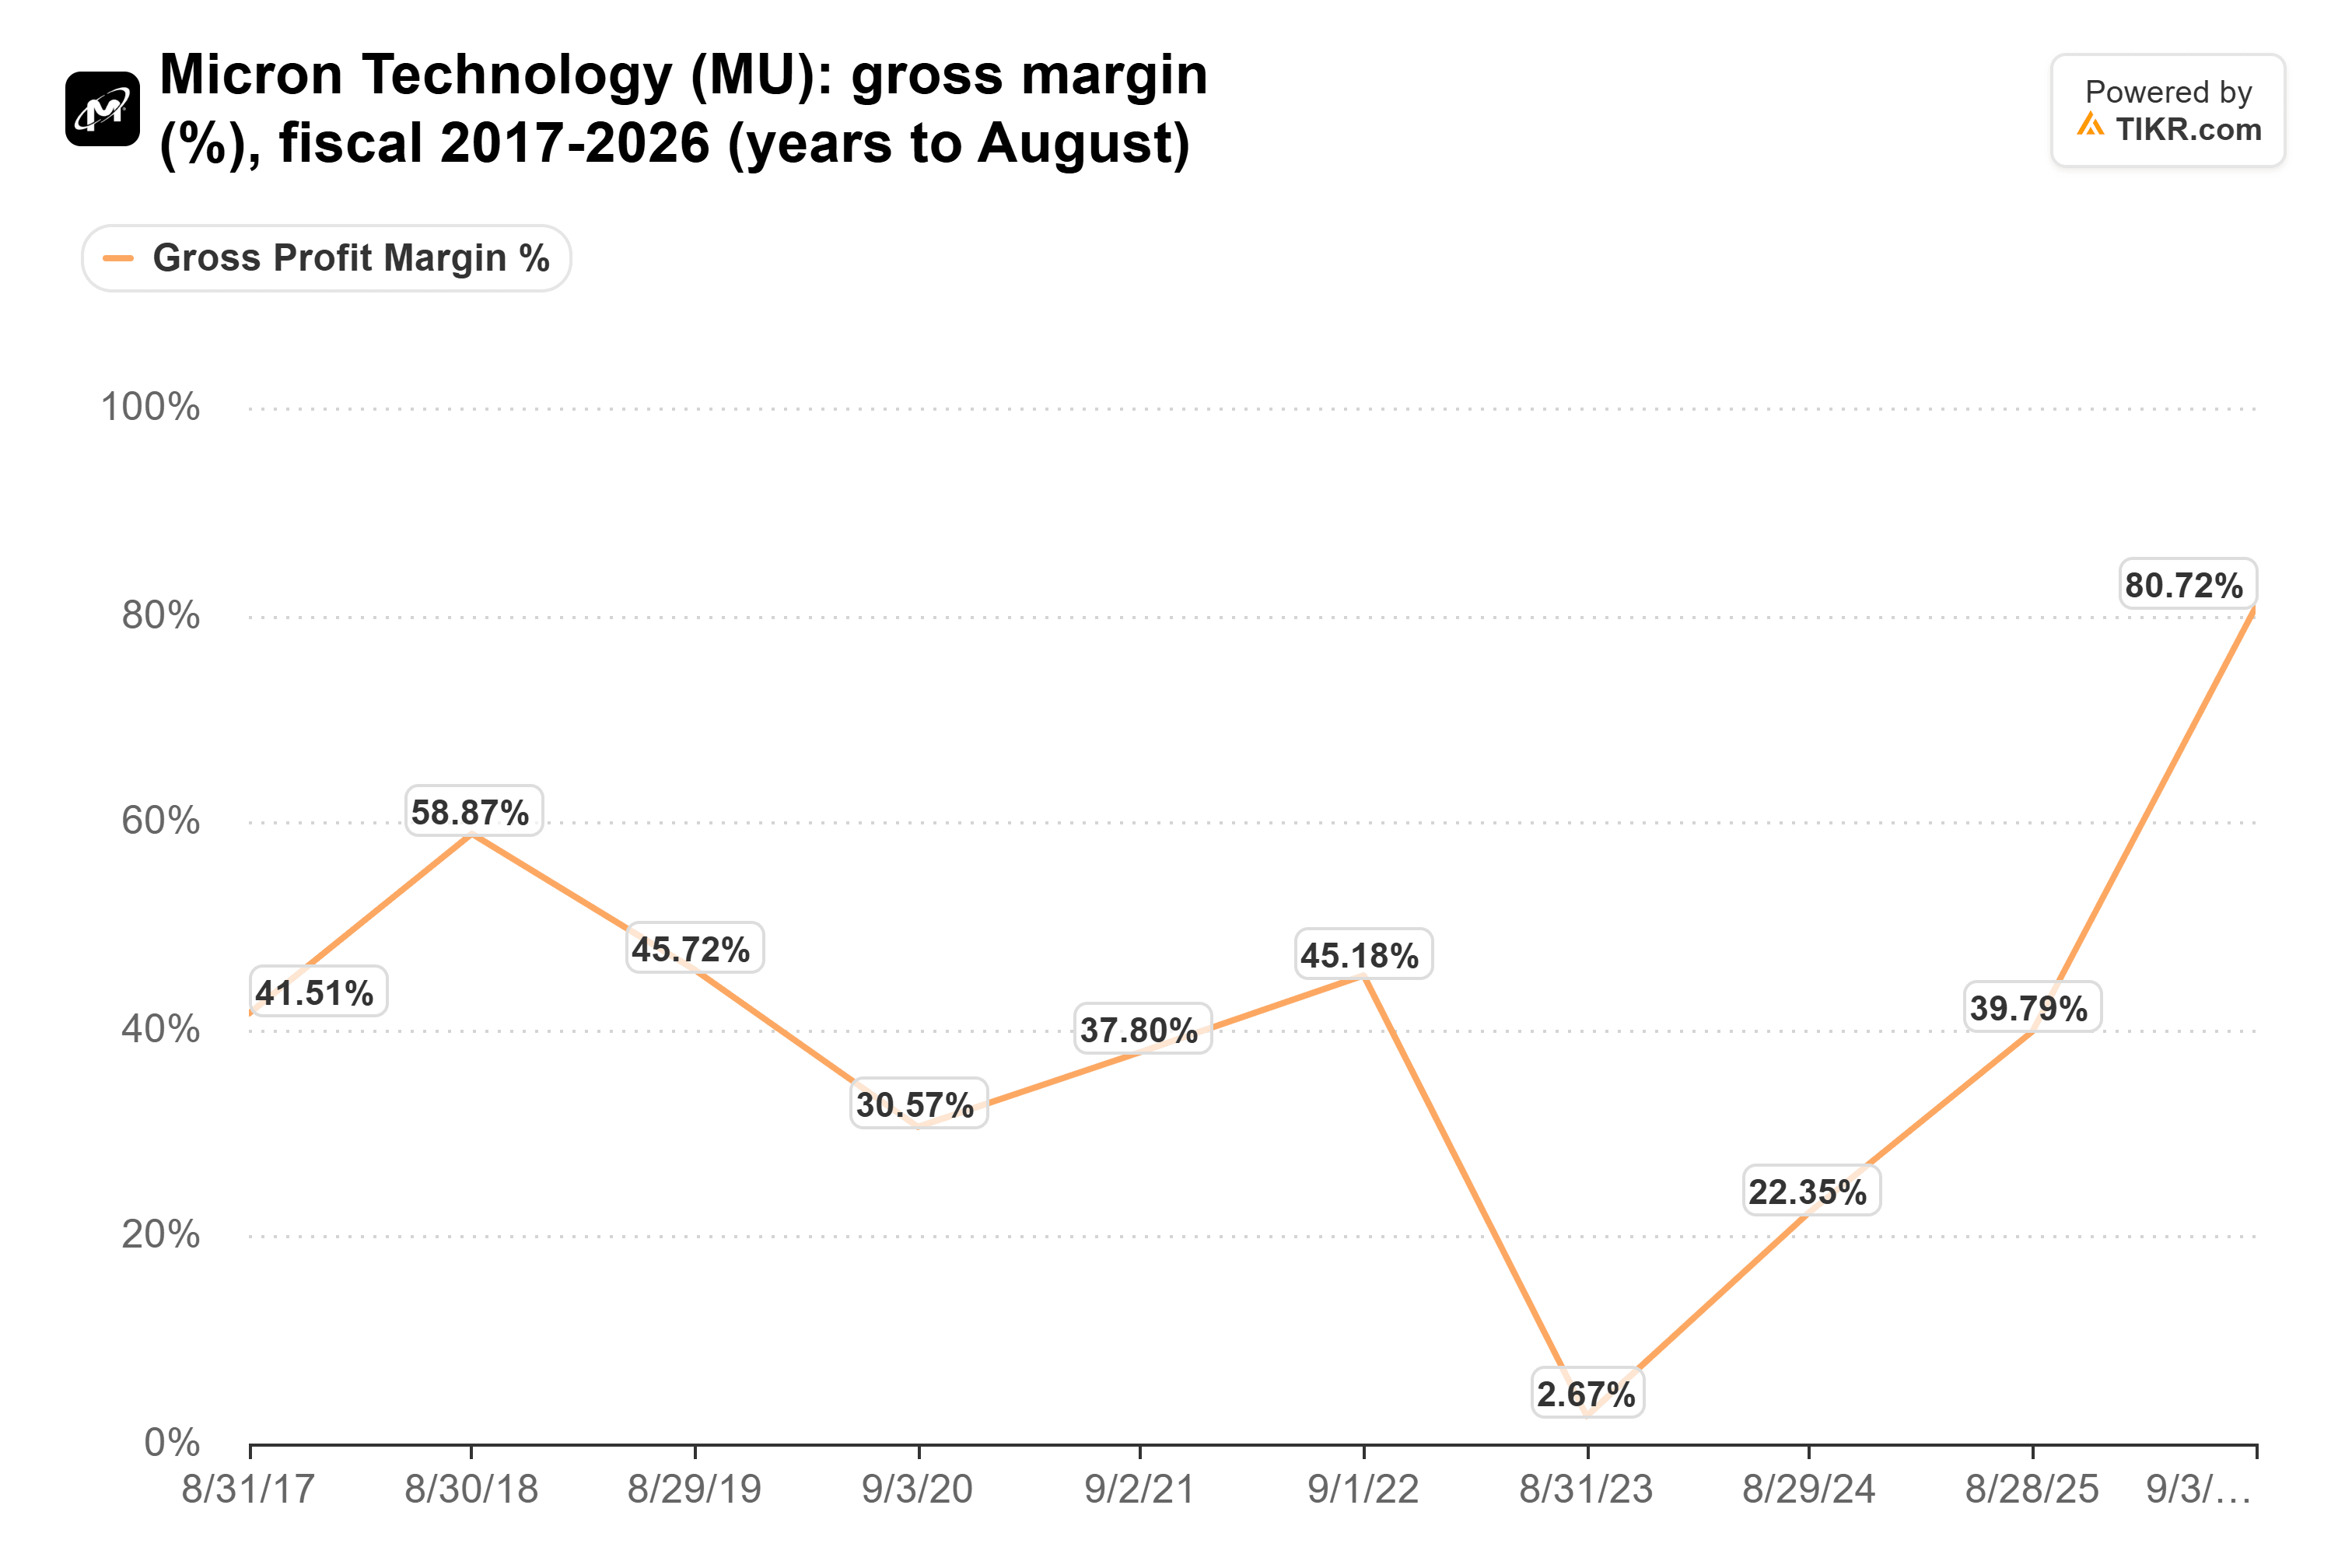
Cheap multiples haven’t saved it before: Micron traded at 3.7x to 5.3x forward earnings in 2017 and 2018. GAAP EPS then fell 79%, from $11.51 in fiscal 2018 to $2.37 in fiscal 2020.
DRAM gains are slowing, too: TrendForce expects conventional DRAM contract prices to rise a more moderate 10% to 15% this quarter.
TIKR Tracks 49 Analysts on Micron. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
NAND Still Acts Like a Commodity
DeBoer’s case is strongest in DRAM. In NAND, TrendForce now expects oversupply next year, with contract prices falling a quarter sooner as Chinese cloud providers cut orders. That clashes with Micron’s September earnings call, where CEO Sanjay Mehrotra said NAND would stay supply-constrained in 2027 and 2028.
GF Securities warned of a NAND glut in 2027 and named Sandisk as the most exposed, with Micron better protected by DRAM and HBM. Micron isn’t immune, though: NAND brought in $31.8 billion of fiscal 2026 revenue, nearly a quarter of the total.
The Contracts Are DeBoer’s Best Evidence
Micron has signed 26 multi-year agreements that management estimates cover more than 35% of revenue through 2030. Most of its calendar 2027 HBM supply is already sold at significantly higher prices.
DeBoer told TBPN that Micron now works with customers on products for “three or four years from now,” and that “at times, we can’t support every customer.” Micron says more of its demand involves customer-specific memory.
Micron Stock Is Too Cheap at 3.4x
DeBoer is right about Micron’s DRAM and HBM business, and the market is pricing the whole company like it’s 2018. Even at half the fiscal 2028 estimate, the stock would trade under 6x earnings. The risk is that none of these contracts has been tested by falling prices.
Micron reports its fiscal first quarter in mid-to-late December, guided to an adjusted gross margin of about 86.25%. Hit it with contract coverage still climbing, and DeBoer’s case holds. Miss it, and the bears have their answer.
So What Is Micron Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!