Key Takeaways
- JPMorgan cut its IREN price target to $55 from $65 on Monday and kept its Overweight rating, leaving 148% upside after a 68% drop in a year.
- IREN pushed its $4 billion revenue run-rate target into early 2027 after Microsoft asked for a network upgrade, and $6 billion of this fiscal year’s build still needs funding.
- JPMorgan’s $55 implies 6.5x forward sales, above IREN’s 3-year average of 5.2x, while next year’s revenue estimates held through the delay.
- The target looks reachable within a year if IREN funds the gap with loans against its data centers, and too high if it sells more stock at these prices.
IREN (IREN) has lost 68% of its value in a year, and JPMorgan still sees $55. Analyst Richard Choe cut his target from $65 on Monday and kept his Overweight rating, leaving it 148% above the $22.20 share price.
A Microsoft delay and $6 billion still to raise
On Nov. 5, IREN moved its target of more than $4 billion of annualized run-rate revenue from year-end to January, possibly the end of February. Microsoft (MSFT) had asked for a network upgrade in its halls, and supplier timing slipped. IREN also put the rest of this fiscal year’s capex at $15 billion, with $9 billion covered and $6 billion still to raise.
“Capital markets have become more selective in the last few weeks,” co-CEO Daniel Roberts said on the call.
JPMorgan still likes the pricing
Choe’s cut follows the delay and the smaller spending plan. But when he upgraded the stock two notches in mid-September, he pointed to rising contract prices, and they’re still going up. IREN’s pricing rose 11% on three-year deals and 12% on five-year deals in the September quarter, as AI cloud revenue nearly tripled to $200 million. Since then, it has also recontracted older H100s at double their original price.
TIKR tracks 20 analysts on IREN. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on IREN, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See IREN’s Analyst Ratings
Does $55 add up?
The consensus target has fallen far less than the stock, to $70 from $76 a year ago:
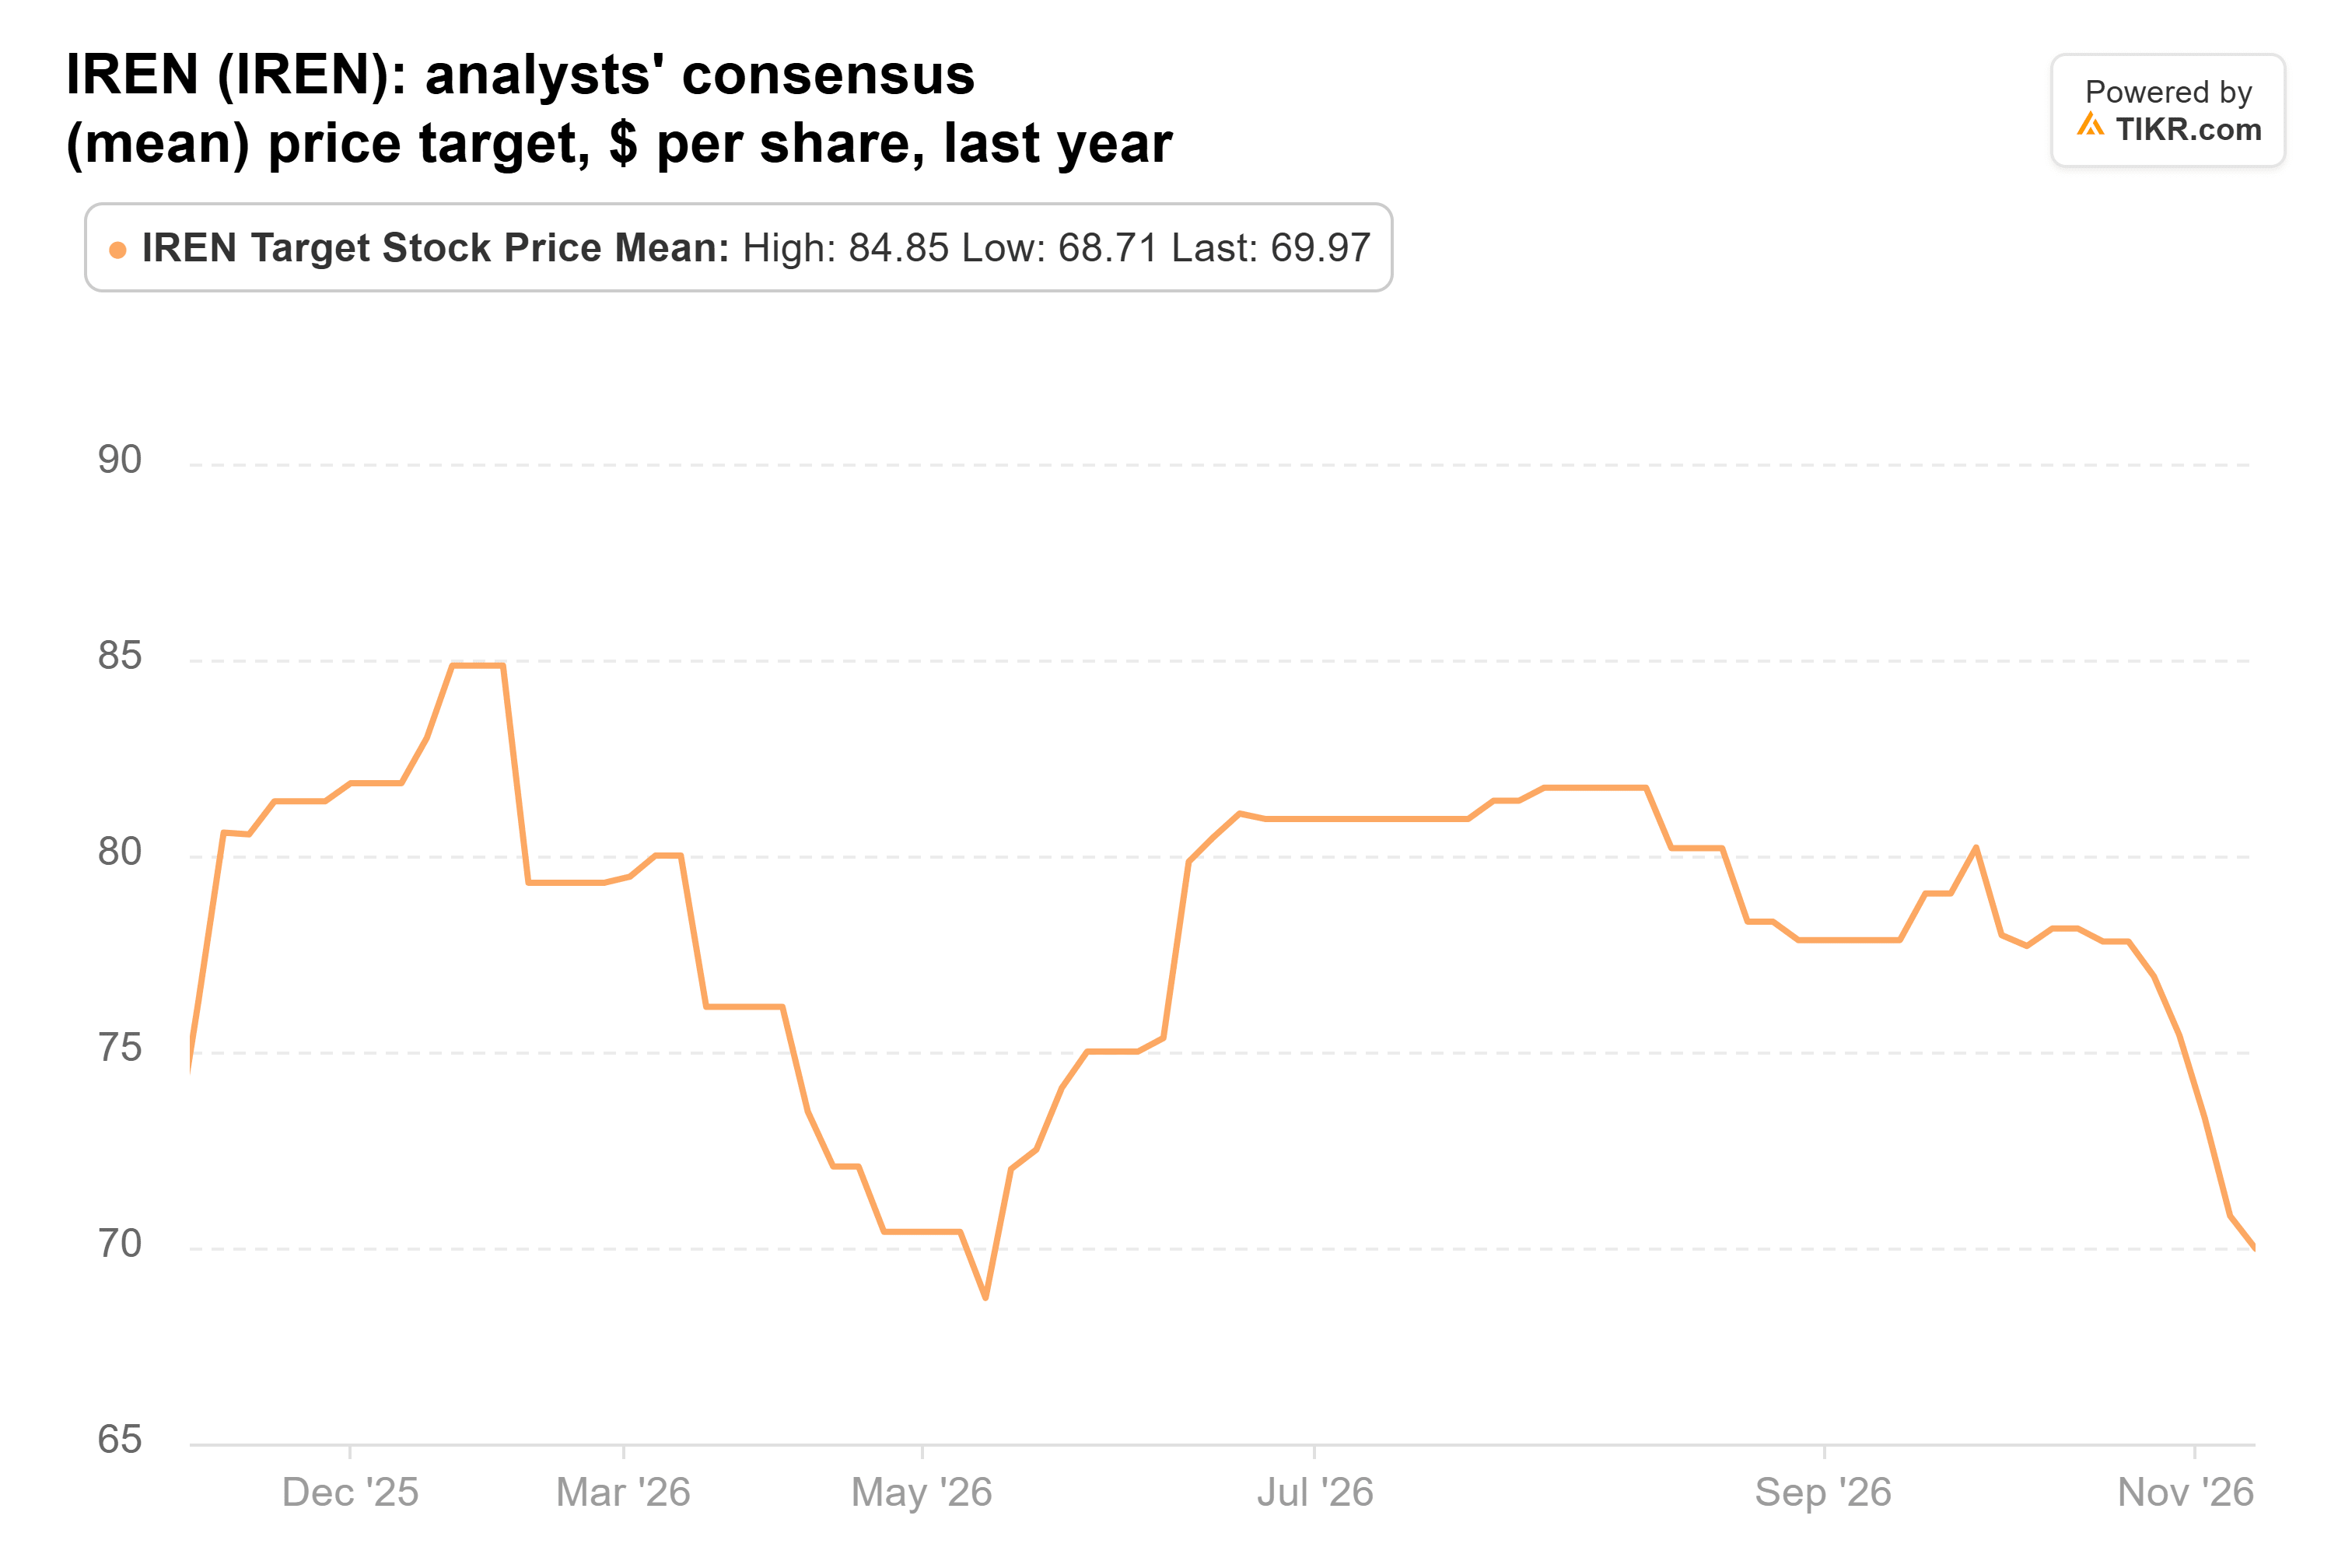
Twenty analysts cover IREN, with targets from $30 to $139, so JPMorgan’s $55 sits 21% below the average.
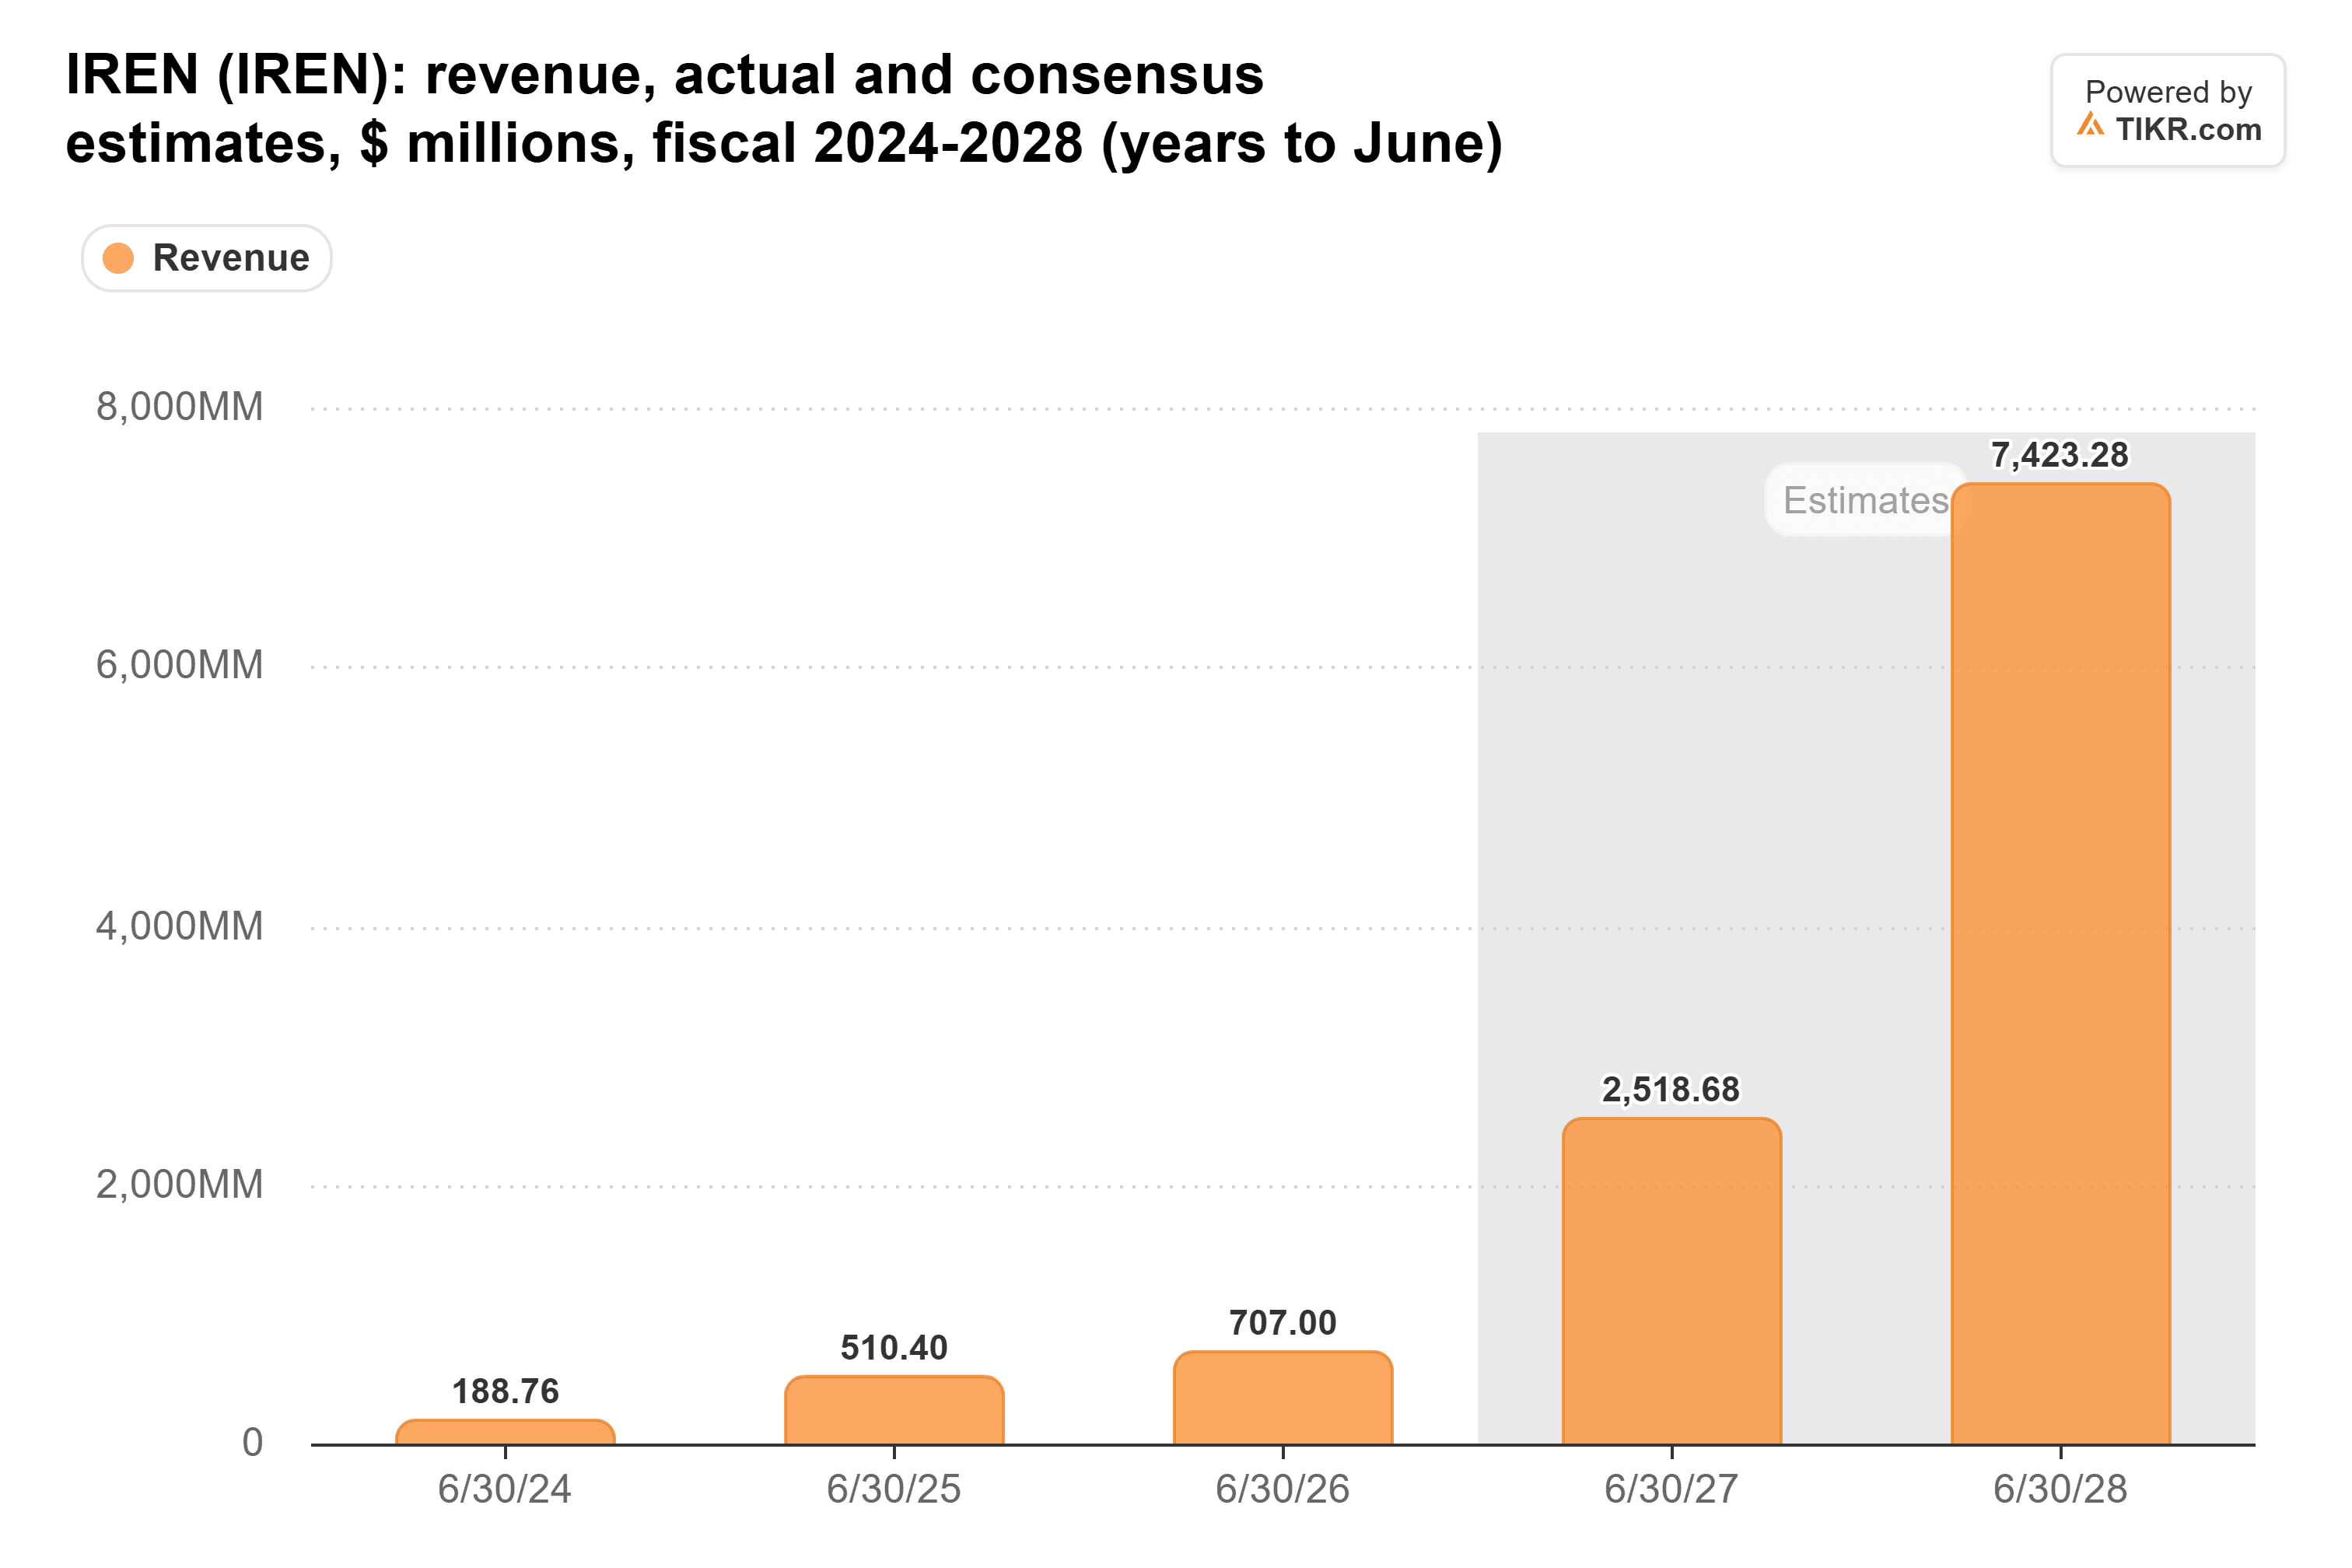
Analysts now expect $2.52 billion of revenue for the year to June 2027, down from $2.81 billion in late October, while next year’s $7.42 billion has barely moved:
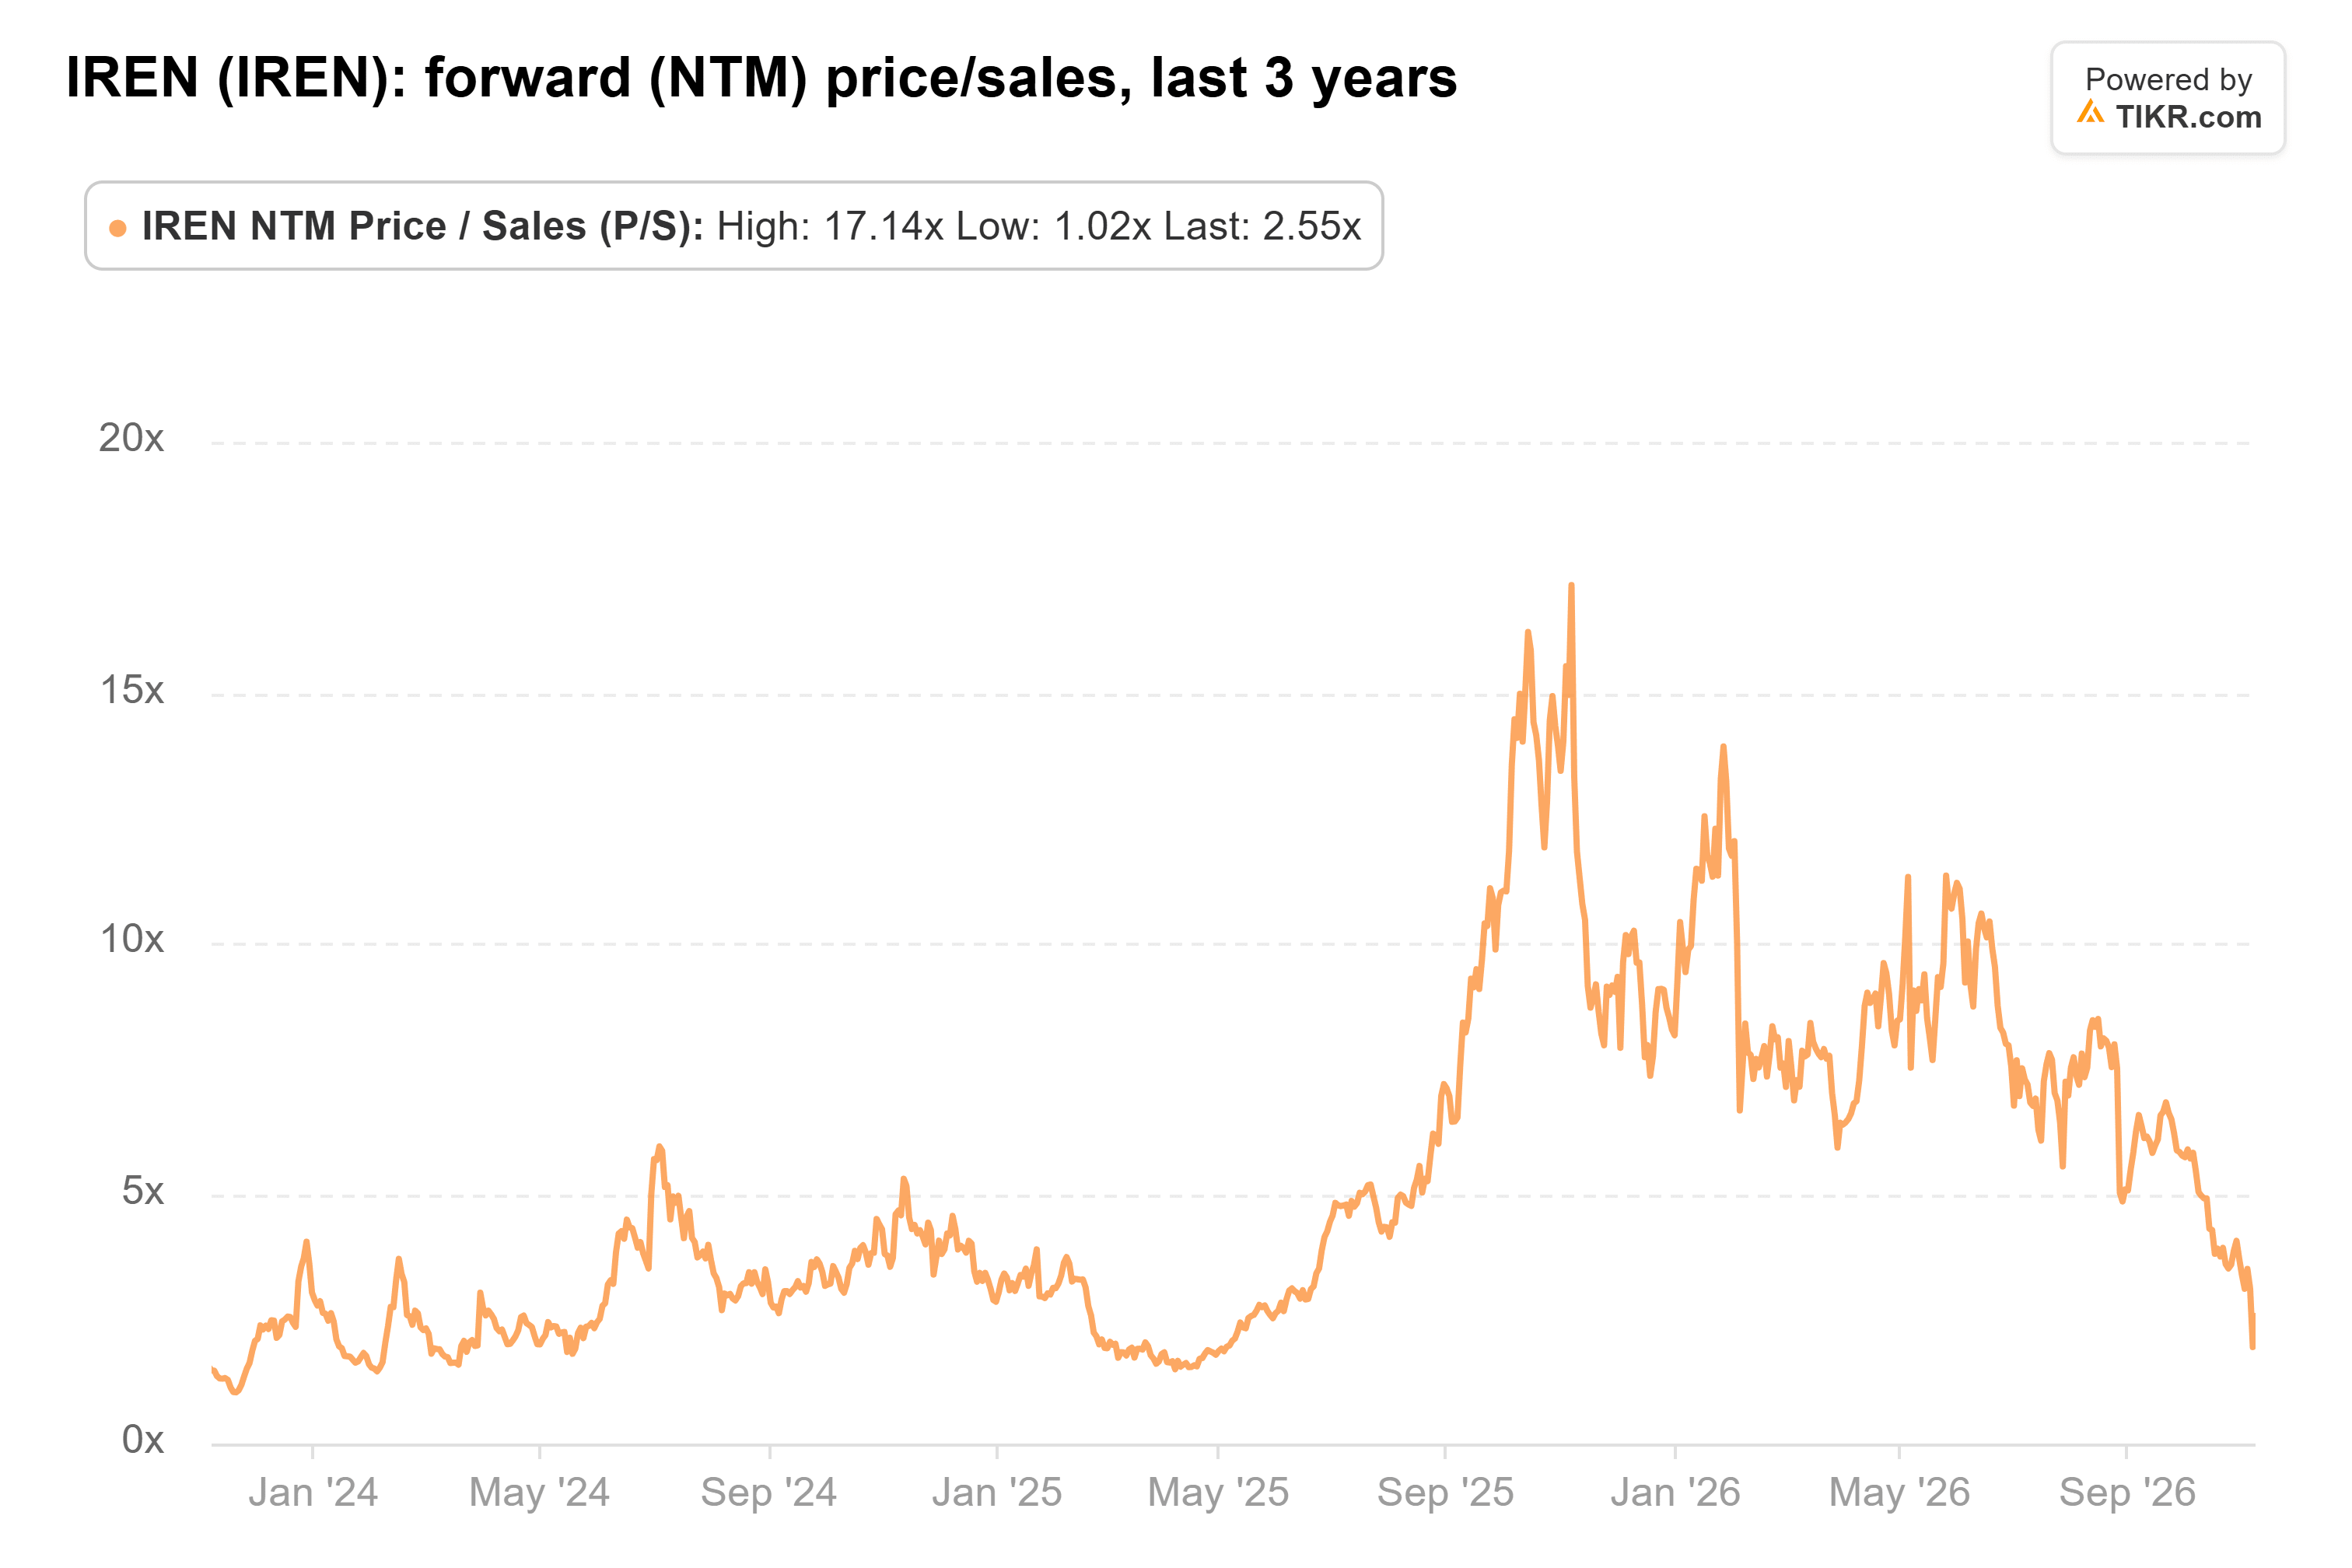
JPMorgan’s $55 works out to 6.5x the sales analysts expect over the next twelve months. That compares with 2.6x at Friday’s close and a 3-year average of 5.2x:
Watch how IREN raises the next $6 billion
Management sees $12 billion to $15 billion of loan and prepayment options for that $6 billion, before convertibles or stock. Each share sold near today’s price shrinks the sales per share behind JPMorgan’s $55.
Here’s where I land: 6.5x is a fair ask, since next year’s revenue estimates held through the delay. If IREN raises the money with loans against its debt-free data centers, $55 looks reachable within a year. If it leans on new stock at these prices, $55 is too much to ask.
The tests come early next year: the $4 billion run rate going live, Microsoft accepting the remaining halls, and a first data center loan for the Microsoft halls.
So what is IREN stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what IREN could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!