Key Takeaways
- Josh Brown said on The Compound and Friends that Alphabet stock “could go down 50%” if Google’s search share slips just 2%, and that he’d buy at $213 to $215.
- A 2% slip in Search would cost Alphabet about 1% of its revenue, so a 50% drop would have to come from investors paying a much lower multiple for its earnings.
- Search & other revenue growth slowed to 12% in the third quarter from 19% in the first, as Google’s AI Mode earns less per query, even with query growth at a five-year high.
- Brown’s buy price works out to about 15x forward earnings, below Alphabet’s five-year low, and the stock already trades at about 20x against a 22x five-year average.
Alphabet (GOOGL) shares fell 13% the day after its Oct. 28 third-quarter report, when Search revenue came in light.
Then OpenAI piled on. ChatGPT consumer product lead Adam Fry told Big Technology’s Alex Kantrowitz on Nov. 2 that ChatGPT now handles roughly a fifth as many search-like queries as Google.
On a recent episode of The Compound and Friends, Ritholtz Wealth Management CEO Josh Brown brought up Fry’s figure. He argued that Google’s dominance won’t protect the stock once its search share starts to slip:
“That number could fall 2% and the stock could go down 50%.”
That’s a lot of downside from a very small number.
TIKR tracks 58 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Plenty of people are still Googling
Search & other revenue grew 19% in the first quarter, 17% in the second and 12% in the third, when it reached $63.4 billion. Query growth was the fastest in five years, but AI Mode monetizes at a lower rate than traditional search.
The one-fifth figure is OpenAI’s own count, and Fry gave no Google figure to measure it against. In February, Ahrefs estimated that ChatGPT handled about 12% of Google’s traditional search volume.
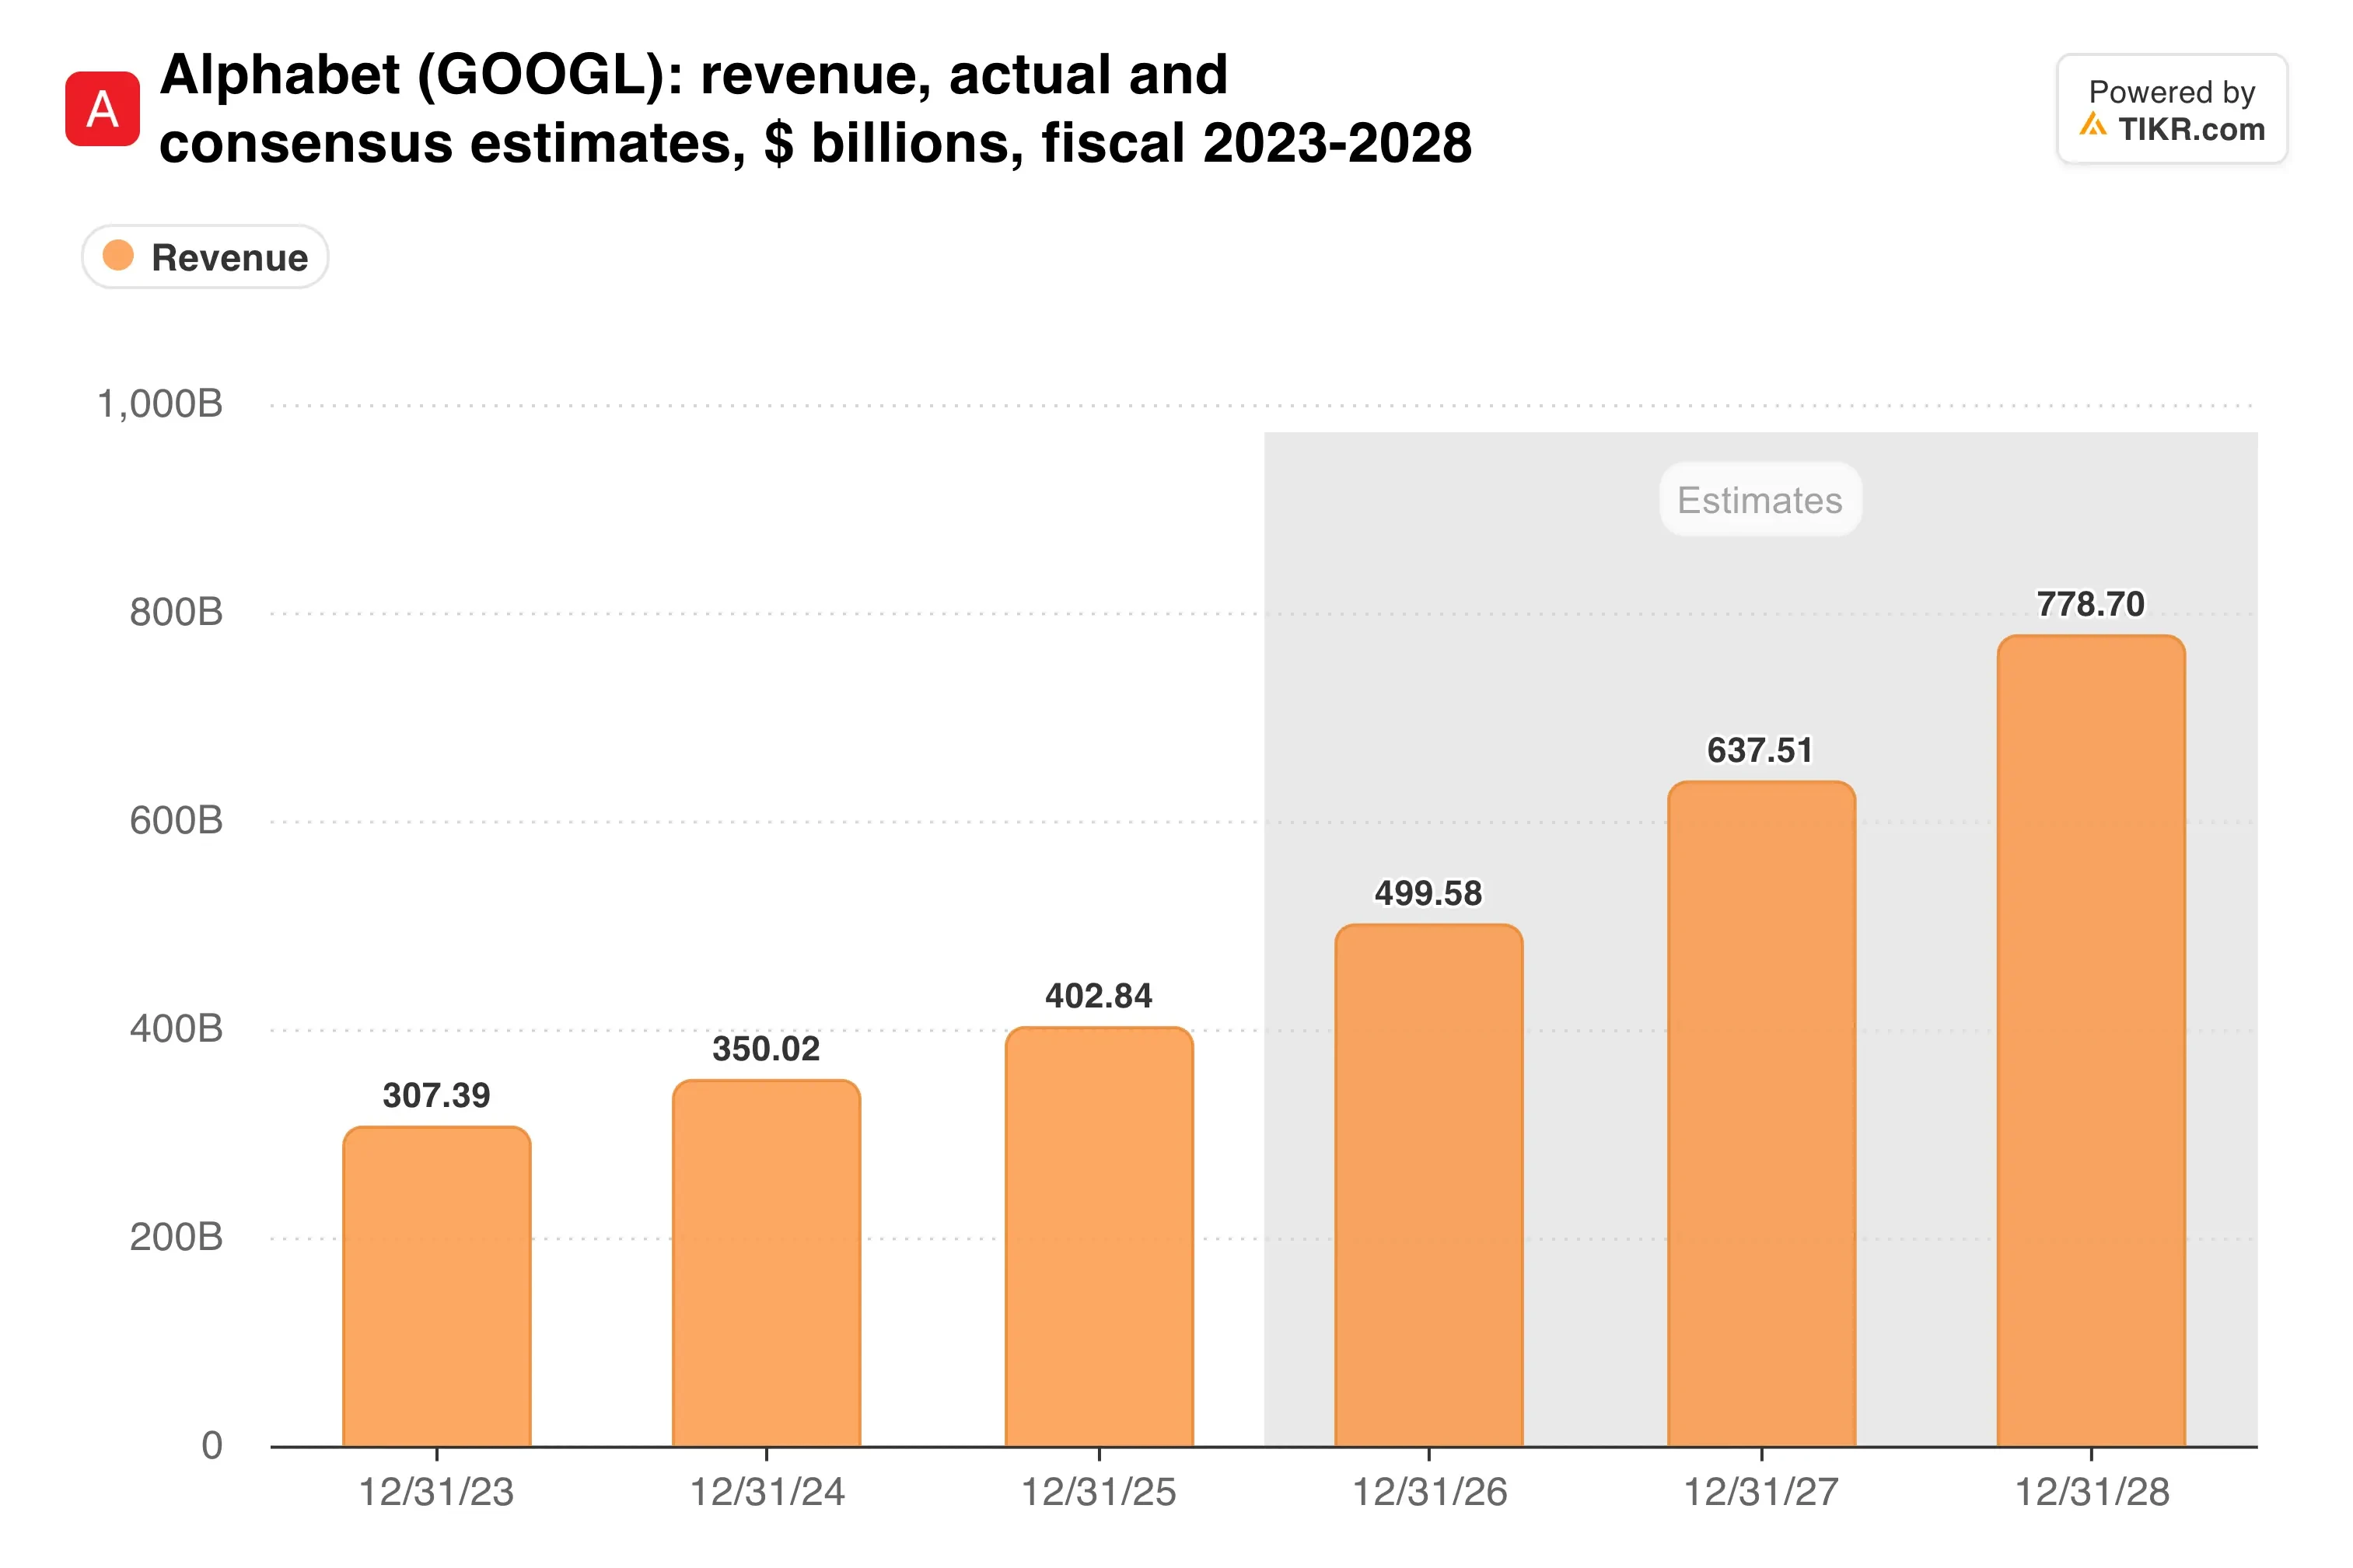
And analysts still expect Alphabet’s total revenue to climb from $403 billion in 2025 to $638 billion in 2027:
Where a 50% drop would have to come from
Search pays the bills. In 2025, Search & other brought in $224.5 billion, 55.7% of Alphabet’s revenue. Google Services earned $139.4 billion of operating income that year, more than Alphabet’s $129.0 billion total.
Those profits are a big reason Alphabet’s operating margin has stayed between 26.5% and 32.1% over the past five years:
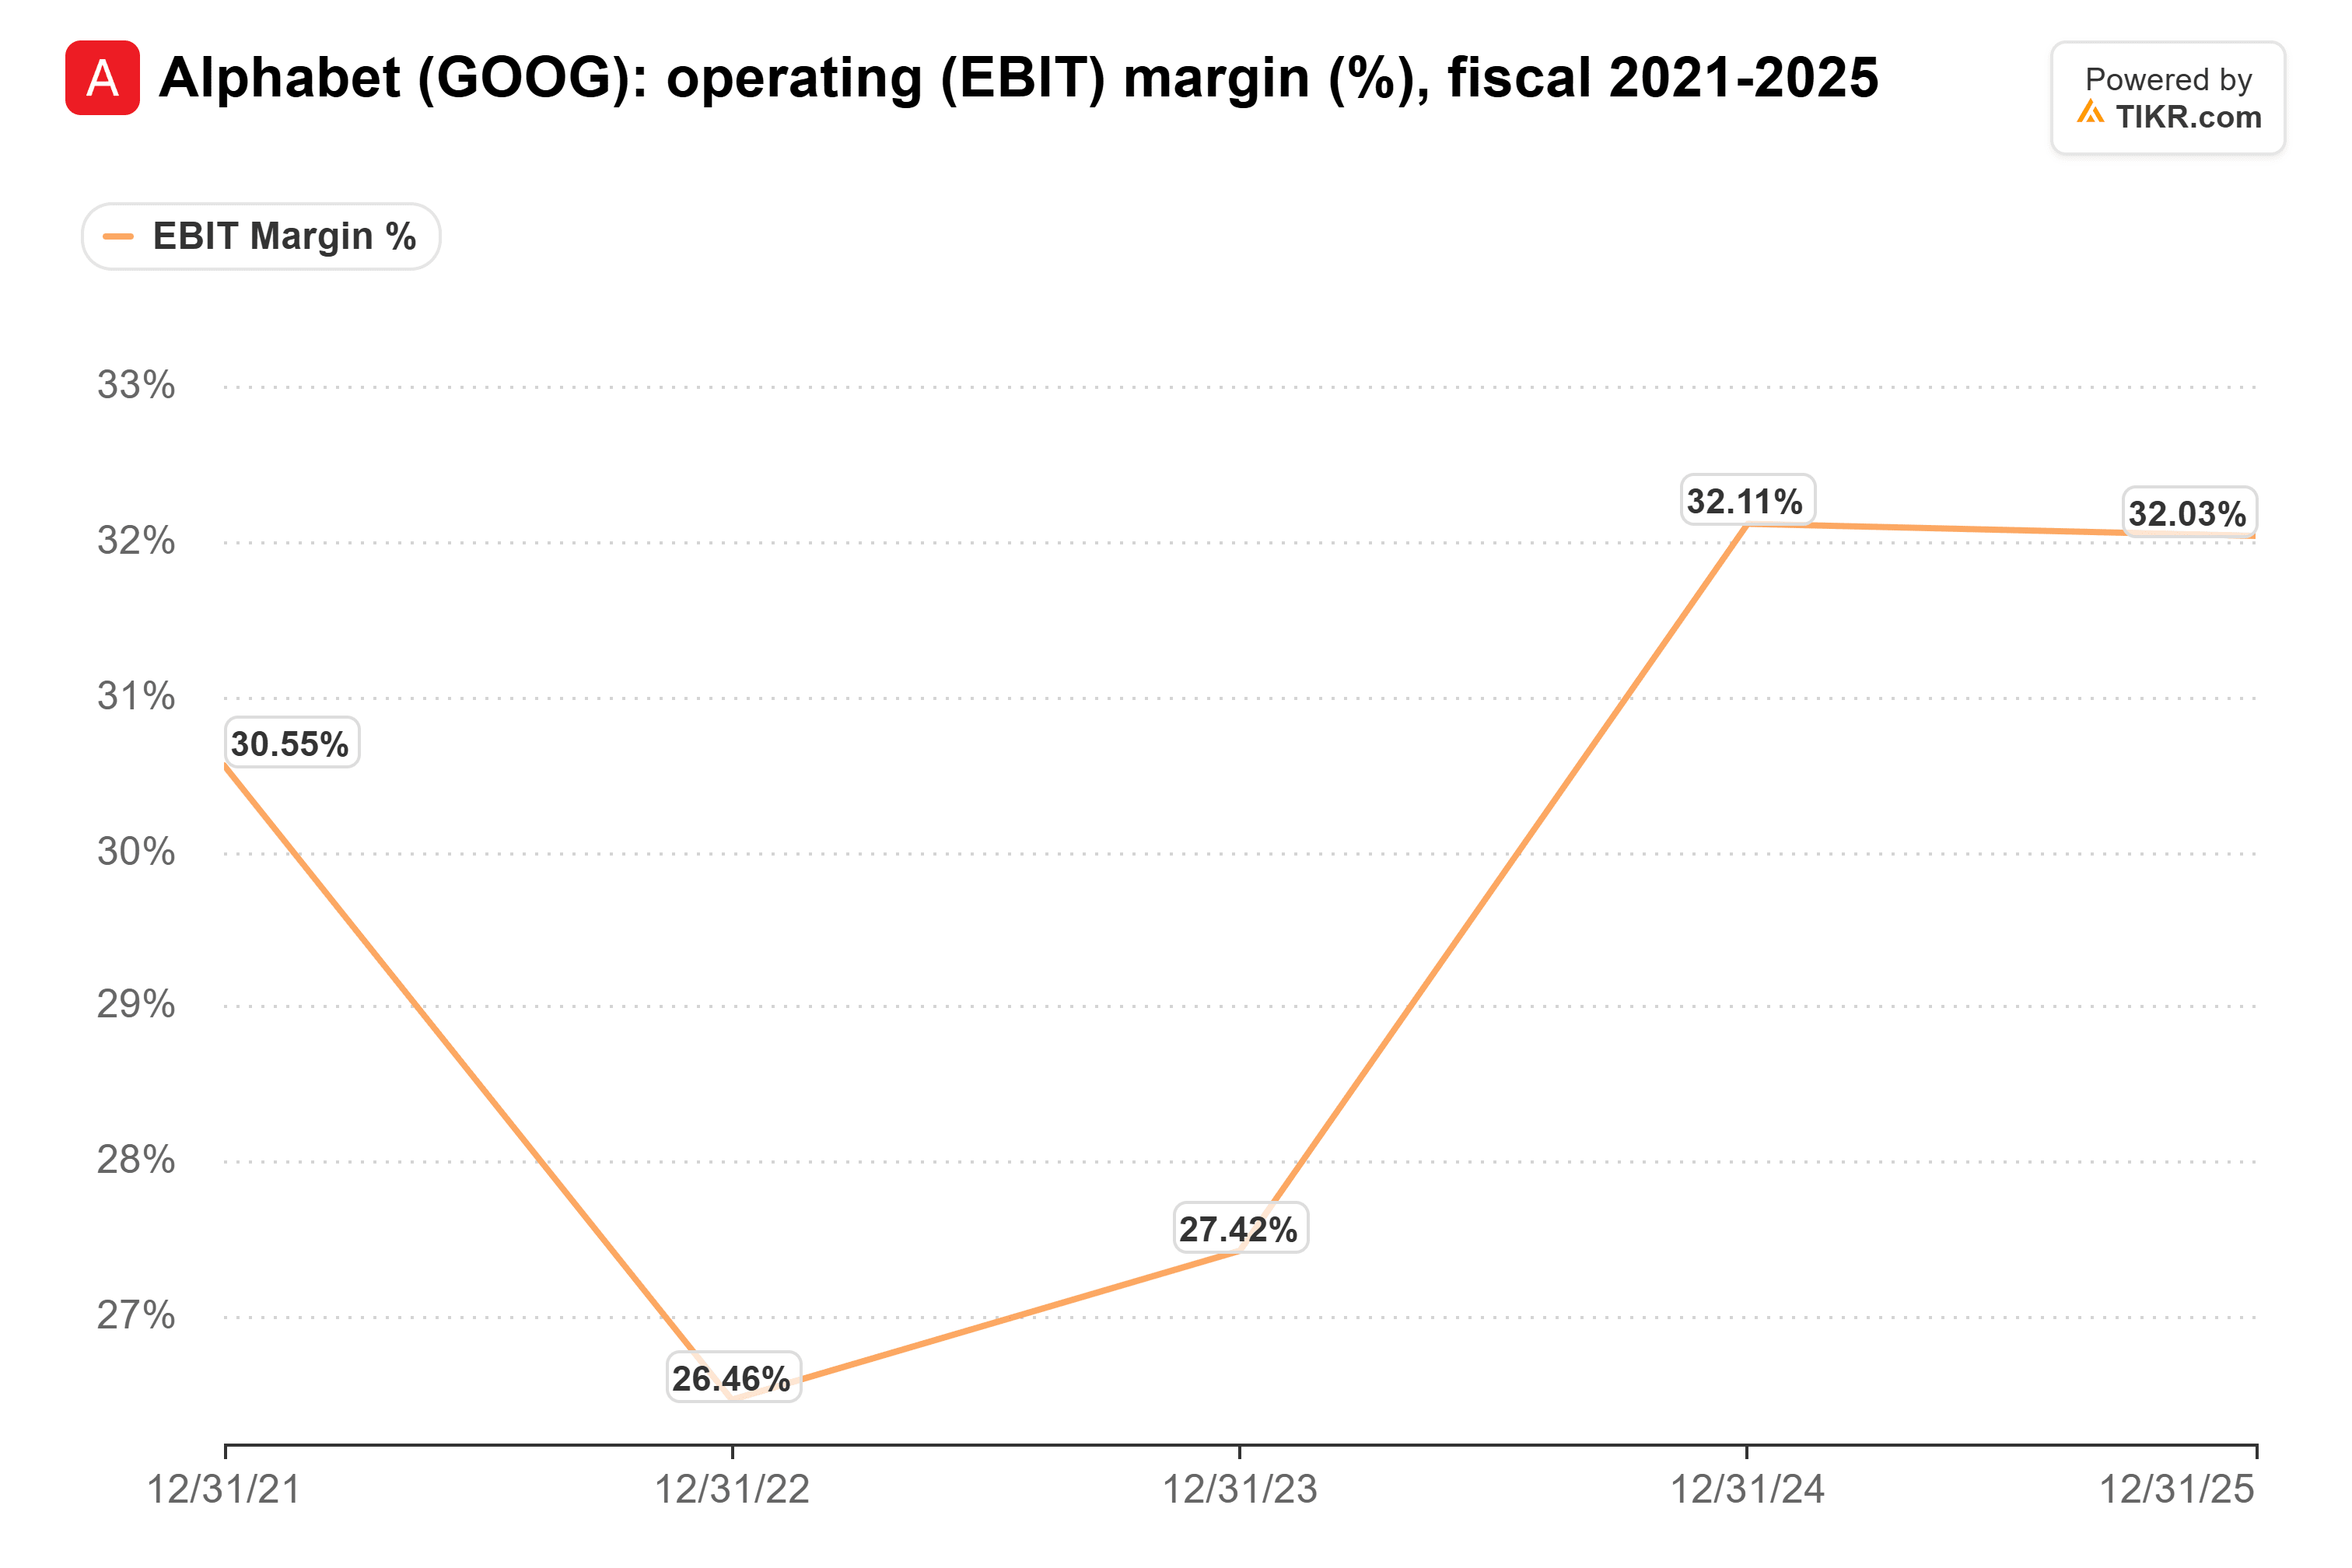
But if you run Brown’s 2% through those numbers, you don’t get anywhere near 50%. A 2% hit to Search & other’s 2025 revenue is about $4.5 billion, roughly 1% of Alphabet’s sales.
So the 50% would have to come from the multiple. If earnings held up, the stock would have to fall from about 20x forward earnings to about 10x, far below its five-year low of 16x.
That’s how I read Brown’s warning. Investors pay up for a franchise they think will keep growing. Once they think it’s shrinking, they stop paying up, even if it’s still dominant.
Alphabet has a second engine now
Plus: Alphabet relies a little less on search every quarter. Google Cloud’s revenue grew 103% in the third quarter. Its backlog reached $560.8 billion at Sept. 30, and just over 55% of Alphabet’s total backlog should turn into revenue within 24 months.
None of that depends on whether someone asks Google or ChatGPT where to get dinner.
Of course, all that capacity costs money. Capital spending was $51.4 billion in the third quarter, and free cash flow was negative $9.1 billion.
Brown’s price would be Alphabet’s cheapest in five years
Asked where he’d buy, Brown named the level where the stock gapped up in September 2025: “I would buy it on the truck if it got to 213 or 215.”
That’s about 25% below Friday’s $285 close. Alphabet already trades at about 20x forward earnings, below its five-year average of 22x:
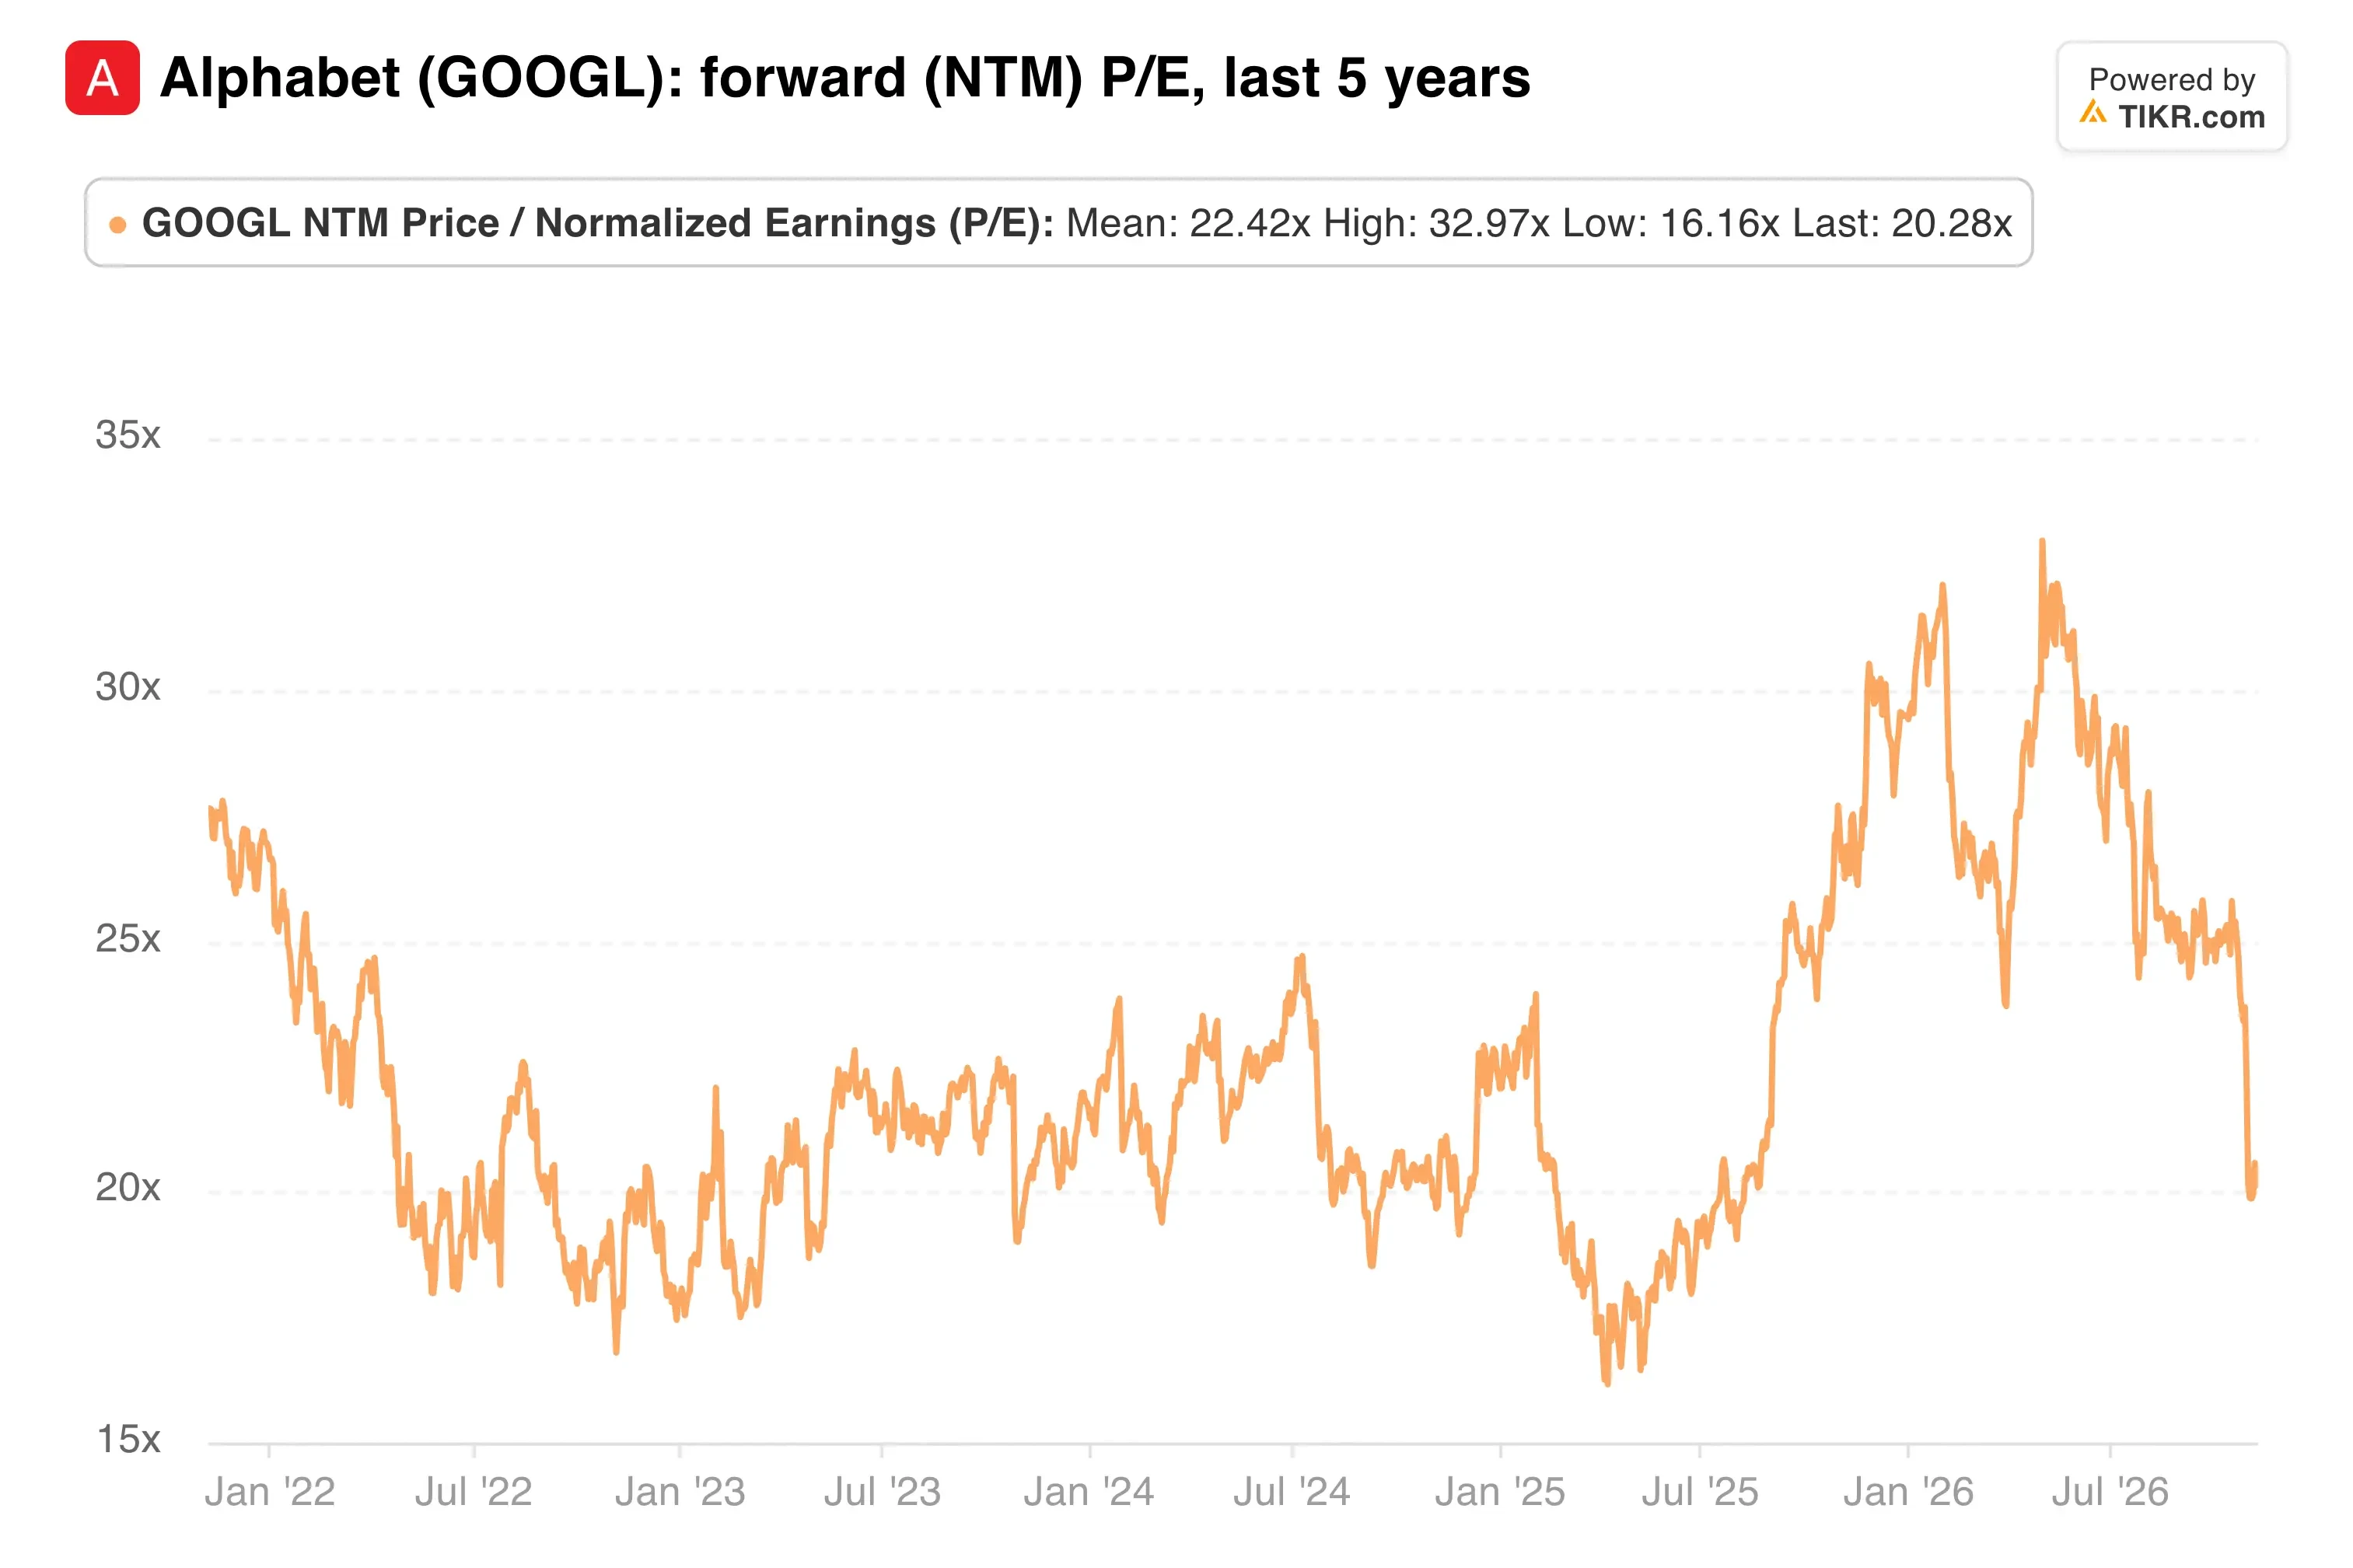
On the same estimates, $215 would mean about 15x. That’s below the 16x low the stock hit during the April 2025 tariff selloff.
Brown is right that Alphabet’s valuation depends on how much investors trust Search, and October shook that trust. But at 20x, investors already doubt Search more than its numbers do. Waiting for 15x means waiting for a selloff worse than the tariff panic. I wouldn’t hold out for $215.
One more quarter like the third would change my mind, though. If Search & other growth drops into single digits when Alphabet reports in early February, it’ll look like more than a trade of revenue per query for usage, and I’d take Brown’s 50% a lot more seriously.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!