Key Takeaways
- Celestica shares fell 22% last week, as did Dell’s, as AI hardware stocks sold off after the Democrats swept the Nov. 3 midterms.
- Celestica had no bad news of its own, and it just guided to $40 billion of revenue and $21.50 of adjusted EPS for 2027.
- The main risk is that a Texas moratorium or other new rules slow its customers’ data-center builds.
- The stock trades far below its usual multiple and looks like a buy as long as those builds keep coming.
Celestica (CLS) fell 22% last week, and Dell Technologies (DELL) dropped 22% too. Neither company had bad news of its own. Most of the selling came after the Democrats swept the Nov. 3 midterms.
The election hit the AI builders
Democrat Gina Hinojosa beat Gov. Greg Abbott in Texas after promising a pause on new data centers. “When I am governor, I will issue a moratorium, a ban, on all data center approvals until laws can be passed by the legislature to protect Texans,” she said in a video on X in late October.
That’s a big deal, since Texas holds about 27% of the data center capacity planned in the US, according to Wells Fargo. The AI hardware selloff deepened on Nov. 5.
Yet Dell’s AI server backlog hit a record $95 billion in July. So both companies face the same question. Does a moratorium cancel orders, or just push them into other states?
Celestica just raised its outlook
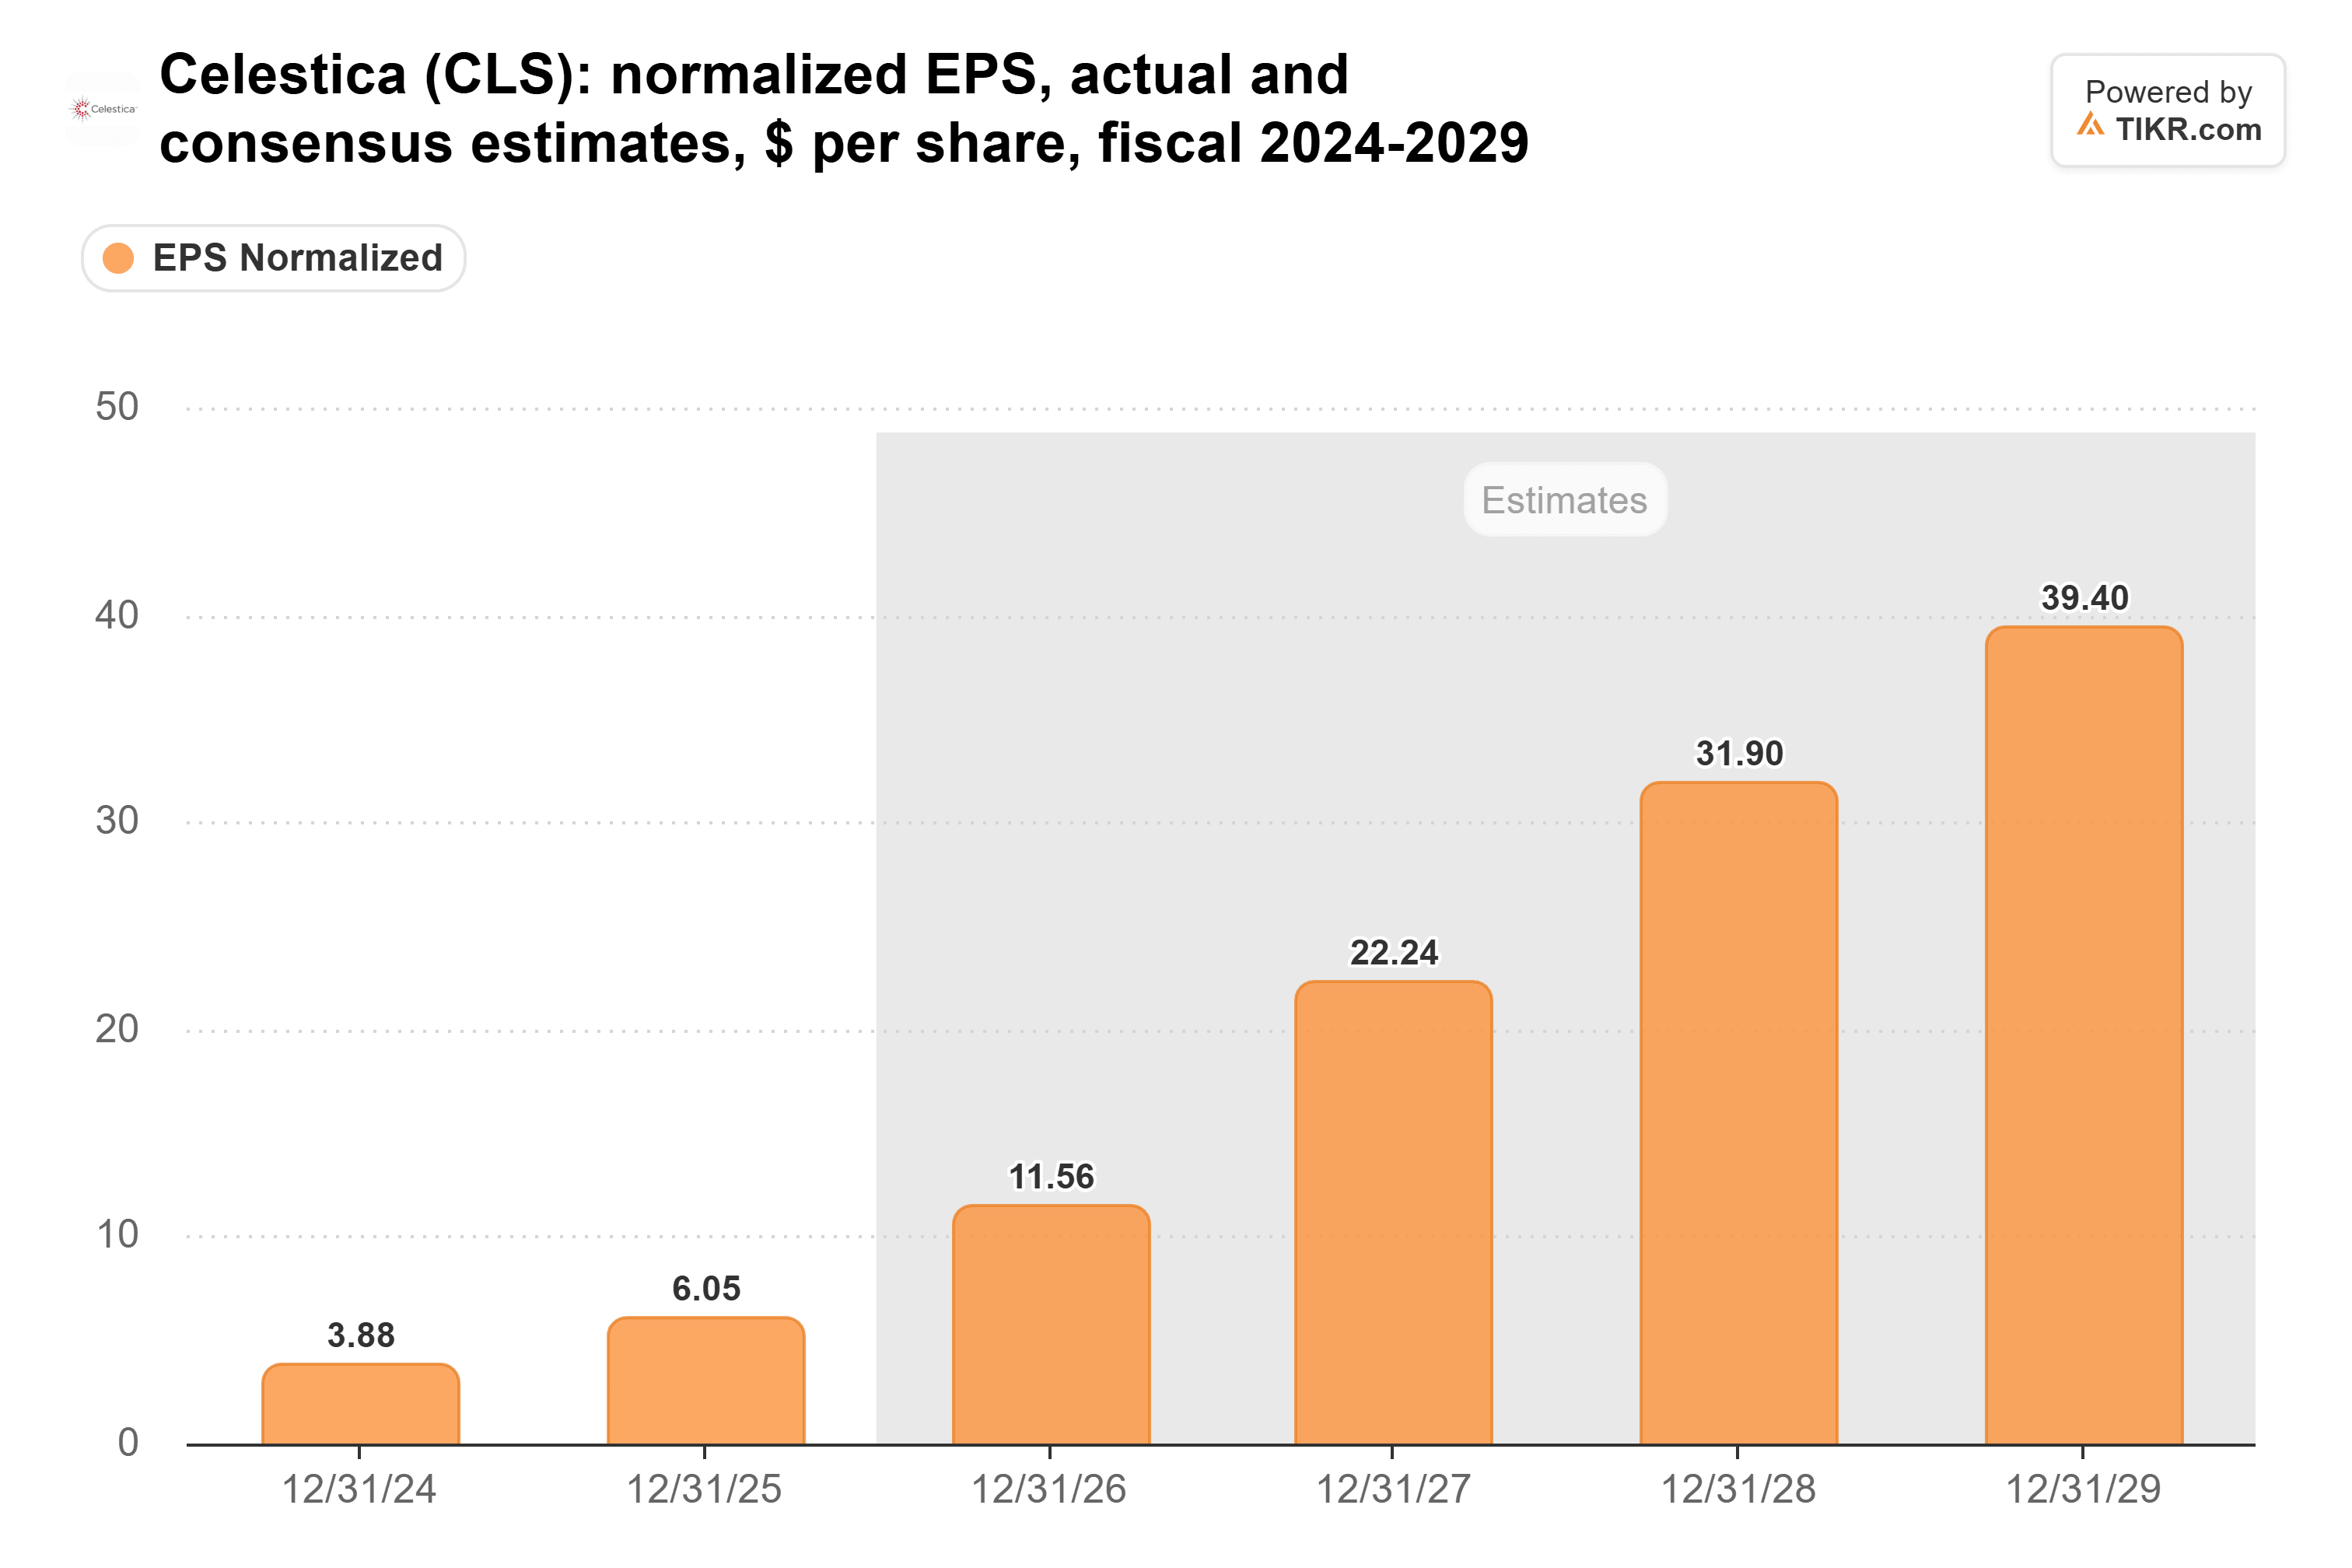
On Oct. 26, Celestica beat its third-quarter guidance, with revenue up 83% to $5.83 billion. It raised its 2026 outlook to $21.0 billion of revenue and $11.55 of adjusted EPS, and guided to $40.0 billion and $21.50 for 2027. Chair and CEO Rob Mionis said customers want even more after that:
“The demand environment continues to be very robust, supporting our 2027 revenue outlook, with customer demand forecasts meaningfully higher for 2028.”
TIKR tracks 21 analysts on Celestica. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Celestica, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Celestica’s Analyst Ratings
Analysts expect adjusted EPS to nearly double this year, then nearly double again in 2027.
The one sore spot was cash. Celestica cut its 2026 free cash flow outlook to $460 million from $600 million to build working capital for 2027. It also expects $1.5 billion to $2 billion of capex next year.
Cheap, if the builds keep coming
Celestica trades at 11x forward earnings, well below its five-year average of 18x.
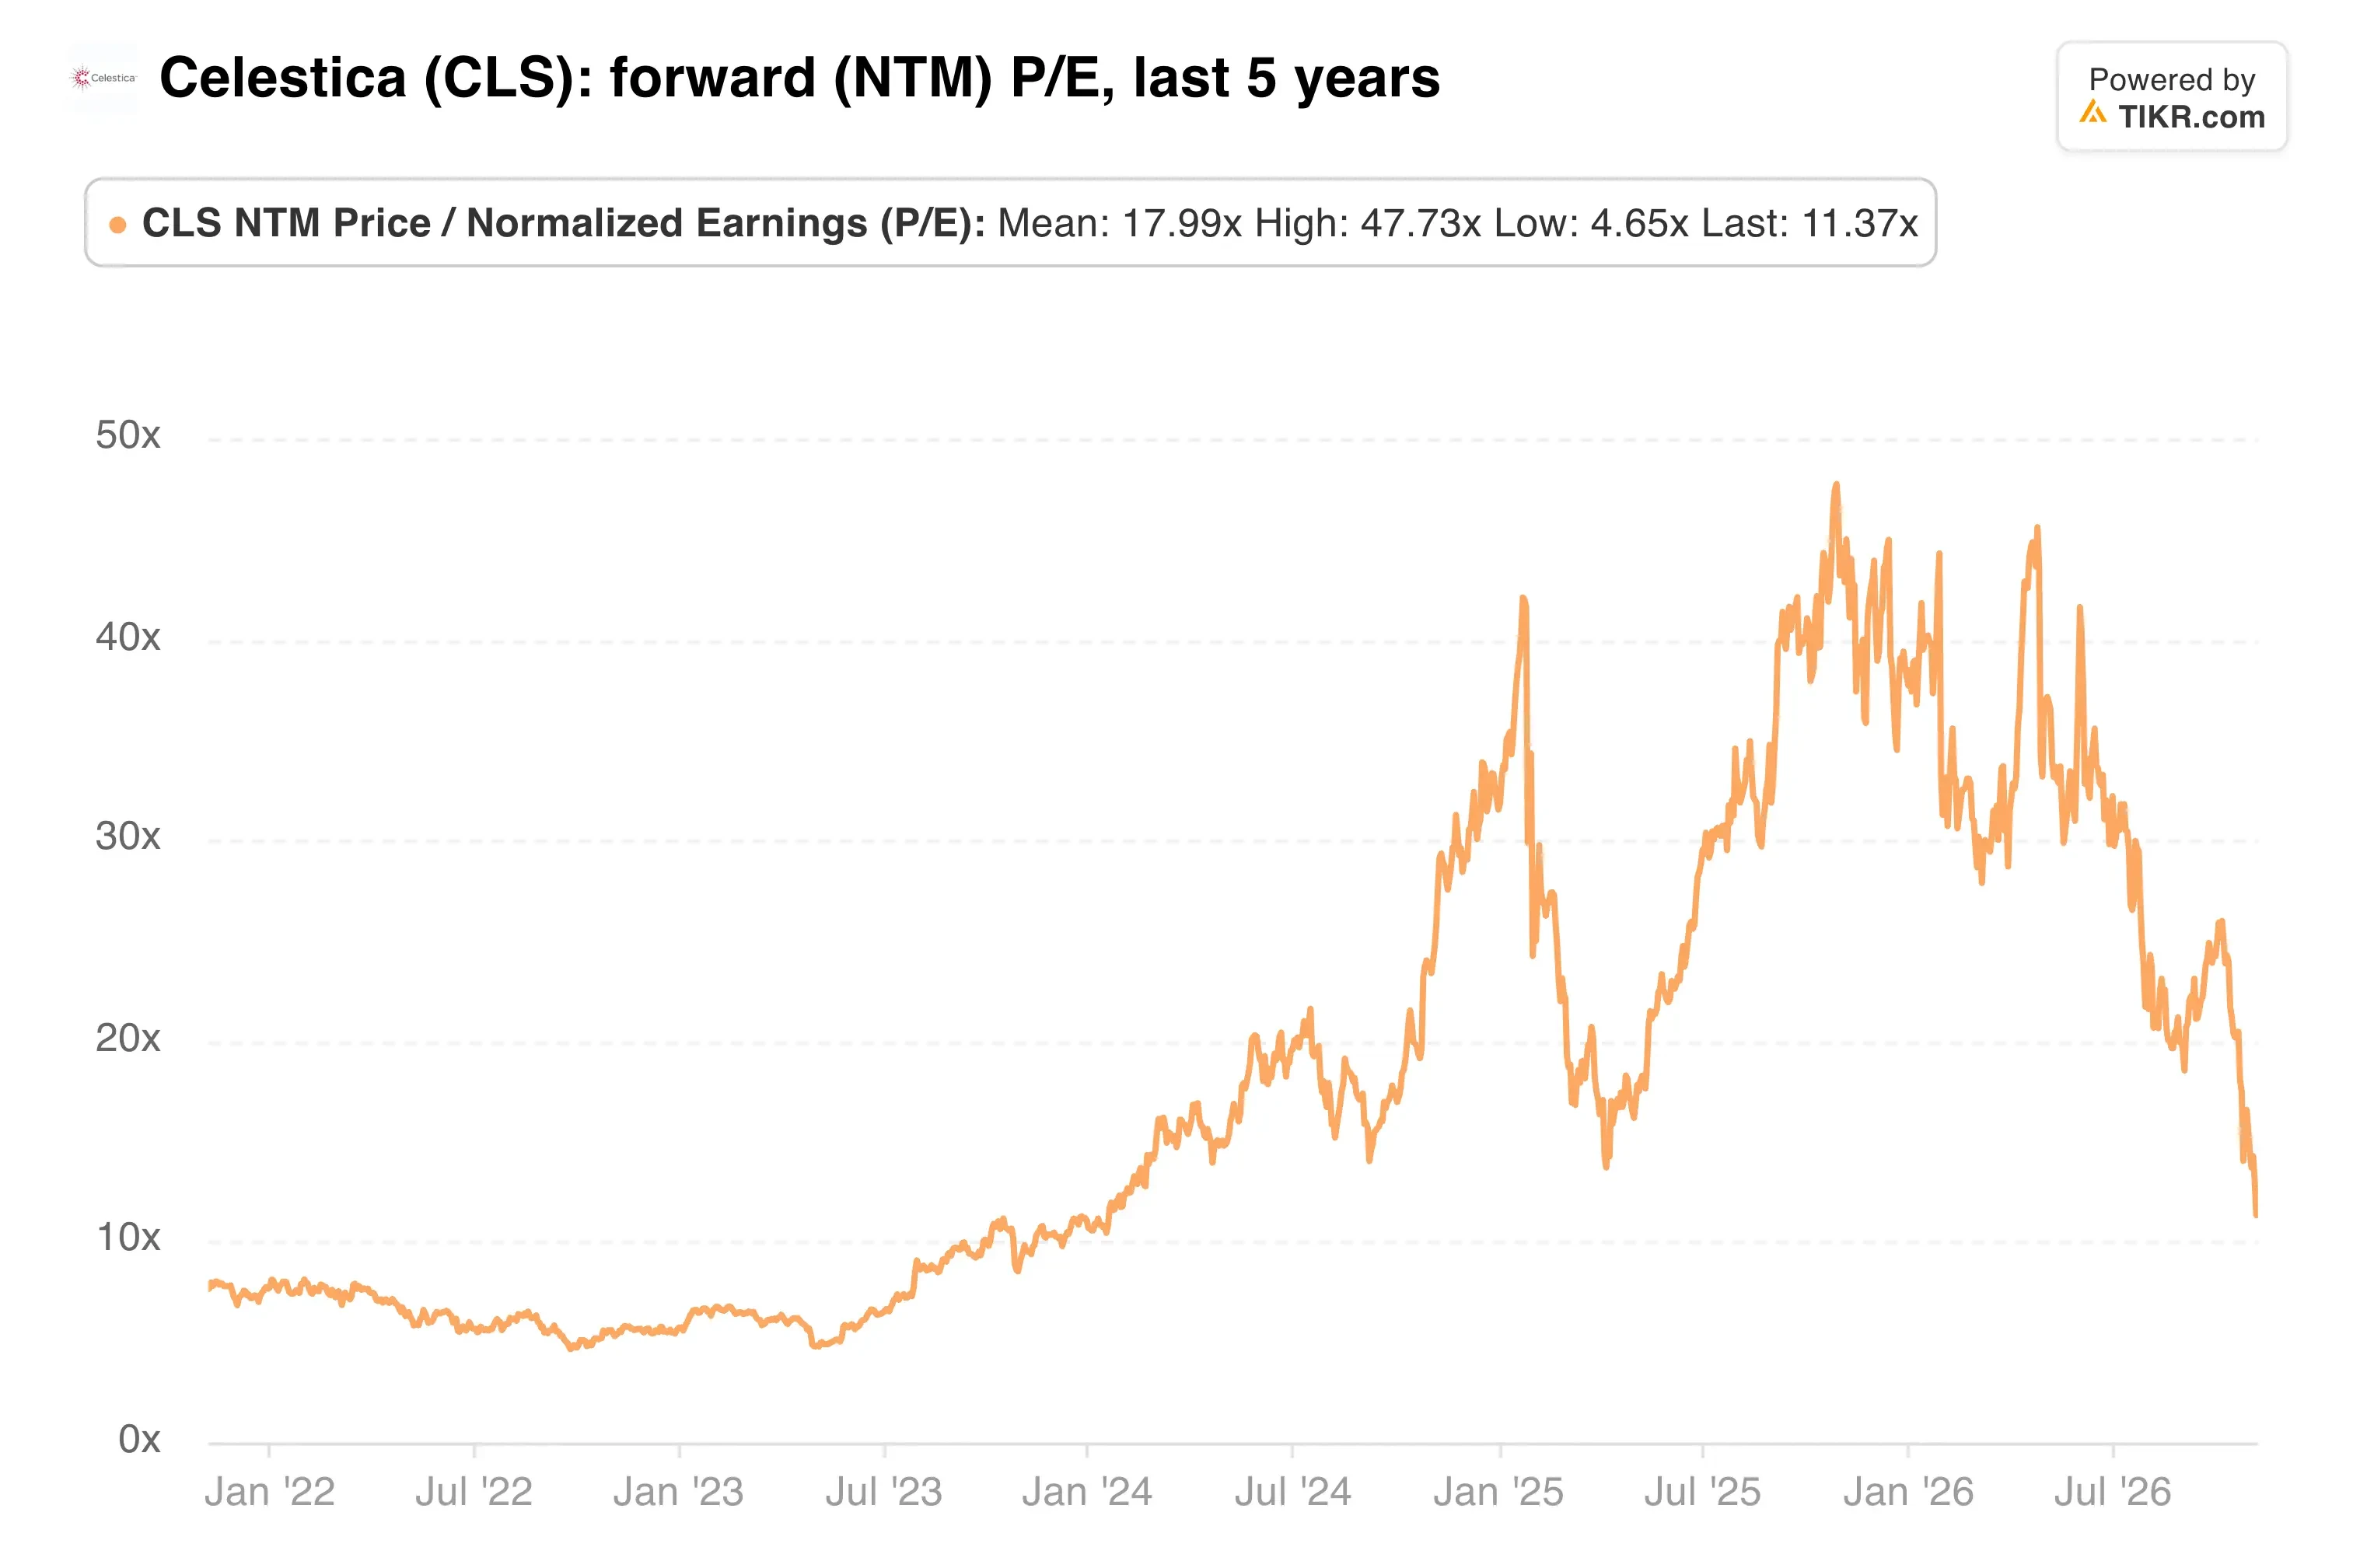
At Friday’s close, it’s under 10x its 2027 guide, and the consensus price target is more than double that price.
The way I see it, the market is pricing in a slowdown that Celestica’s customers haven’t announced. A Texas moratorium would hurt, but I suspect the hyperscalers would build that capacity in other states. At these prices, I’d load up.
Of course, we’ll know more once Hinojosa takes office in January and Celestica updates its 2027 outlook with its fourth-quarter report early next year.
So what is Celestica stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Celestica could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!