Key Stats for Johnson & Johnson Stock
- Current Price: $273.20
- Target Price (Mid): ~$342
- Street Target: ~$279
- Potential Total Return: ~25%
- Annualized IRR: ~5.5% / year
What Happened?
Johnson & Johnson (JNJ) used the TCT cardiology meeting in San Diego to post two heart-device results on November 1. Its investigational Javelin catheter met both primary goals in a 158-patient pivotal study. Three Impella heart pump analyses also reported lower death rates than CHIP-BCIS3, the randomized trial J&J has tied to slower Impella sales. Neither result moves the quarter much. Abiomed, the Impella business, posted $412 million of third-quarter sales, about 1.6% of J&J’s $25.4 billion. What the data tests is whether Impella, the part of J&J’s cardiovascular unit that shrank last quarter, can recover.
Javelin Cleared Its Pivotal Bar. FDA Review Comes Next
Javelin sends acoustic pressure waves forward from its tip to crack calcium in narrowed arteries that are hard to cross with balloon-based devices. In FORWARD CAD, J&J reported 93.6% technical success and 93.4% freedom from major cardiac events through 30 days, both above pre-set performance goals. Of the treated lesions, 96% were moderately or severely calcified, and serious complications appeared in 1.3% of patients.
The study had no comparison arm, and Javelin is still investigational in the U.S., so a filing and FDA review come before any U.S. sales. It would join Shockwave, which grew 17.2% operationally in the third quarter against 2.5% for MedTech overall.

Impella’s Comeback Case Rests on Registries Until 2027
CHIP-BCIS3, presented at the American College of Cardiology meeting in March, found no benefit from Impella in 300 high-risk PCI patients. Over a median of 22 months, cardiovascular deaths ran 26.7% with the pump versus 14.5% without it. A second Impella trial at the meeting, STEMI-DTU, did not reduce heart damage in heart attack patients. Abiomed sales fell 1.5% operationally in the third quarter on lower patient volume. On the October 13 call, Tim Schmid, Worldwide Chairman of MedTech, called it “a short-term headwind.” He also said J&J believes the study’s methodology “did not follow well-established practices.”
The TCT analyses are J&J’s reply:
- PROTECT III cohort: in 578 patients who met CHIP-BCIS3’s entry criteria, in-hospital mortality was 4.7%. J&J compares that with an estimated ~8% in CHIP-BCIS3.
- European registry: 279 patients showed 6.1% all-cause mortality at 30 days.
These are observational comparisons presented by paid J&J MedTech consultants. Navin Kapur, M.D., chief medical and scientific officer of J&J’s Heart Recovery business, said outcomes “depend not only on the device but how and when it is used.” That point cuts both ways: registries, where doctors choose the patients, can’t separate the device from the selection.
CFO Joe Wolk said PROTECT IV, a 1,252-patient randomized trial four times CHIP-BCIS3’s size, should report in 2027. Until then, he described heart recovery as “now a stable business” that J&J wants to “catalyze back to double-digit growth.”
TIKR tracks 23 analysts on Johnson & Johnson. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Johnson & Johnson, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Johnson & Johnson’s Analyst Ratings
TIKR Advanced Model Analysis
- Current Price: $273.20
- Target Price (Mid): ~$342
- Potential Total Return: ~25%
- Annualized IRR: ~5.5% / year

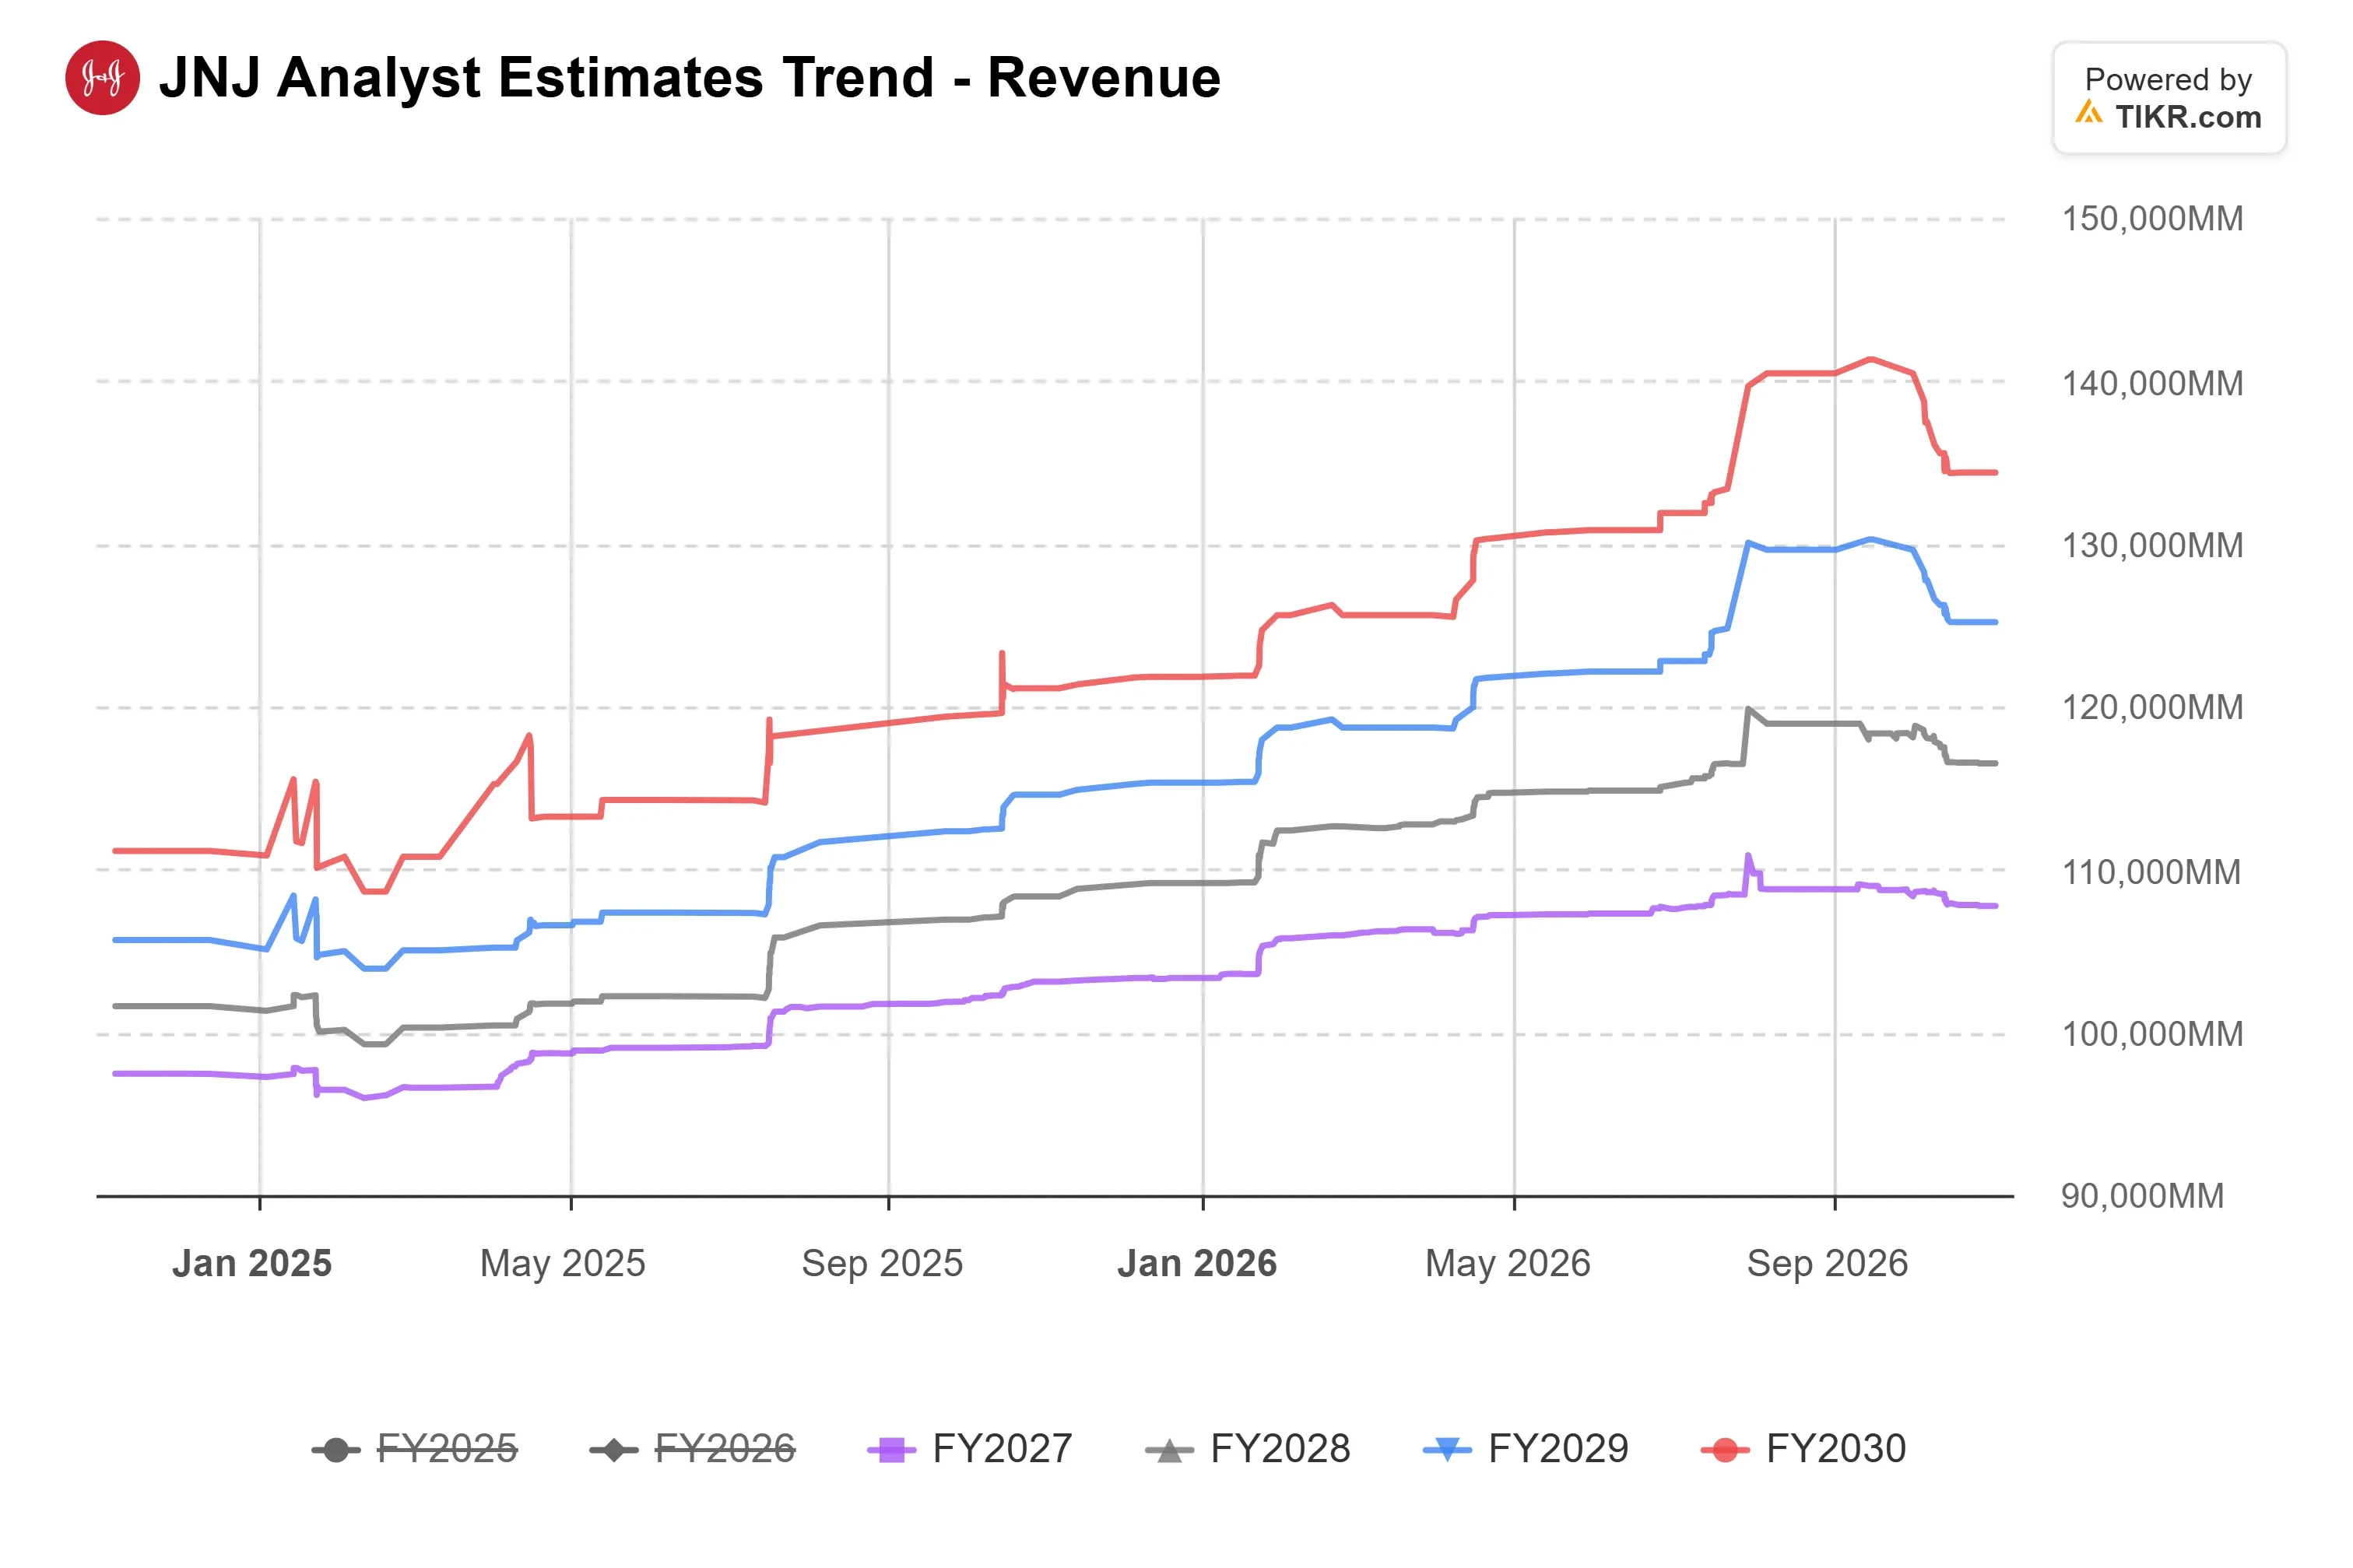
The TIKR model’s mid case points to around $342 by December 31, 2030, about 5.5% a year from $273.20. The Street’s long-range view isn’t moving up to help. TIKR consensus for 2030 revenue sits near $134 billion, about 5% below its September 30 level, though it now draws on ten analysts instead of three.
CEO Joaquin Duato said on the call that additional data supporting Impella and OTTAVA in robotic surgery “are not yet fully reflected in our growth.” The upside case is Impella returning to growth and Javelin winning approval. The downside is a PROTECT IV miss in 2027, which would be a second negative randomized readout for Impella in high-risk PCI.
Conclusion
Schmid said Abiomed should be “back to growth in short order.” The fourth-quarter report is the first test. A return to growth would support J&J’s reading of CHIP-BCIS3. Another decline would leave the Impella case resting on PROTECT IV.
So what is Johnson & Johnson stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Johnson & Johnson could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Johnson & Johnson on TIKR Free →
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!