Key Stats for Intel Stock
- Current Price: $107.08
- Target Price (Mid): ~$437
- Street Target: ~$118
- Potential Total Return: ~308%
- Annualized IRR: ~39% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Intel Corporation (INTC) closed at $107.08 on October 8, 2026, down 5.34%. The drop came in a chip selloff that Yahoo Finance tied to a Financial Times report questioning OpenAI’s revenue. Intel was among the session’s steepest decliners, falling more than 6% intraday alongside Arm Holdings (ARM) and Marvell Technology (MRVL).
Intel itself issued no news that day. Its latest release was the October 6 notice that it will report third-quarter results after the close on October 29, per its investor relations materials. Shares are still up 194.4% over the past year, but they sit 24.02% below their one-year peak.

See historical and forward estimates for Intel stock (It’s free!) >>>
Intel Won’t Name Foundry Customers, Even at Its Analyst Day
That policy is one reason outside headlines move the stock so much. At Deutsche Bank’s technology conference on August 26, EVP and CFO David Zinsner said CEO Lip-Bu Tan “does not want to be announcing customers on the foundry side.” He added that announcing them is “not done in the foundry industry.” He told investors not to expect customer names even at the Analyst Day, which he expects sometime in 2027. Customers can still announce deals themselves.
Intel did confirm in April that it joined Elon Musk’s Terafab project as a partner. Since Musk disclosed talks with Taiwan Semiconductor Manufacturing (TSM) on October 3, though, updates on Intel’s role have come from Musk’s posts and Tan’s remarks to reporters, not from disclosed contract terms.
Revenue Beats Are the Signal Intel Controls
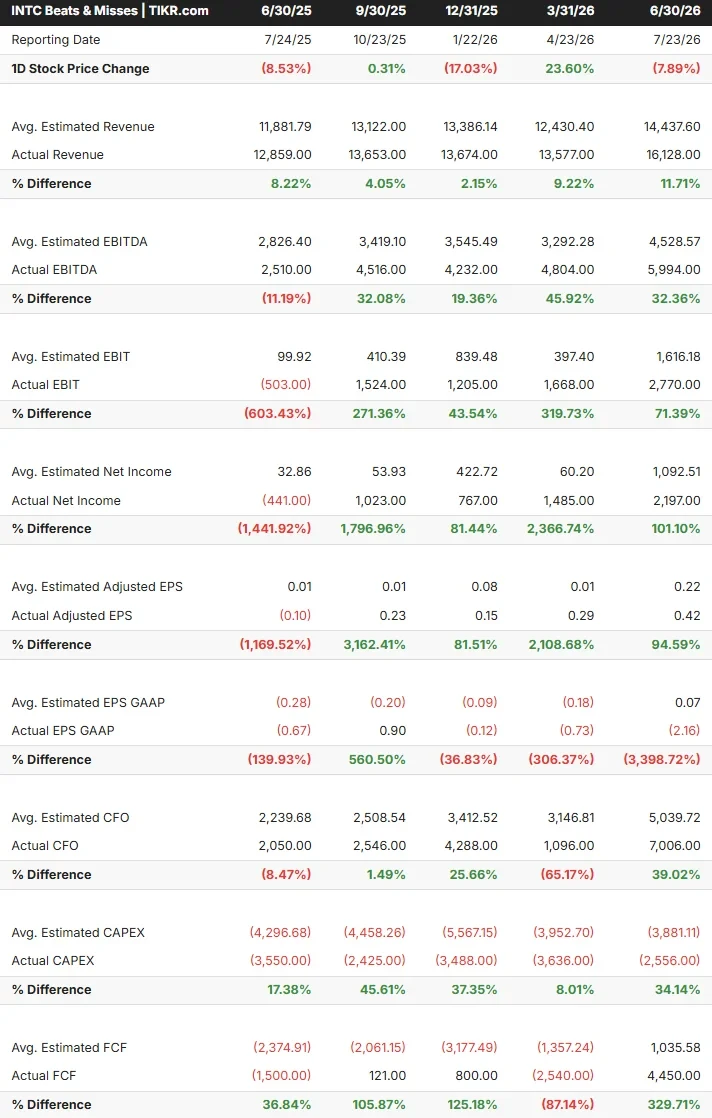
Intel’s reported numbers keep beating expectations. Revenue beat consensus in each of the last five reported quarters, per TIKR. Q2 2026 revenue reached $16.13 billion, up 25.42% year over year and 11.71% above estimates. Adjusted EPS of $0.42 nearly doubled the $0.22 consensus. On a GAAP basis, though, EPS was a loss of $2.16 against a $0.07 estimate.
Zinsner described part of that strength as a supply choice. Memory costs hurt PC demand, but he called the weaker client business “probably the best thing we could have given the data center demand,” because it freed capacity for servers.
Spending is the open question. Zinsner has said 2027 CapEx will rise significantly, but when his teams submitted a number, he said, “I’ve told them, no.” Consensus still models negative free cash flow in 2026 and 2027, turning positive in 2028, per TIKR.
See how Intel performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
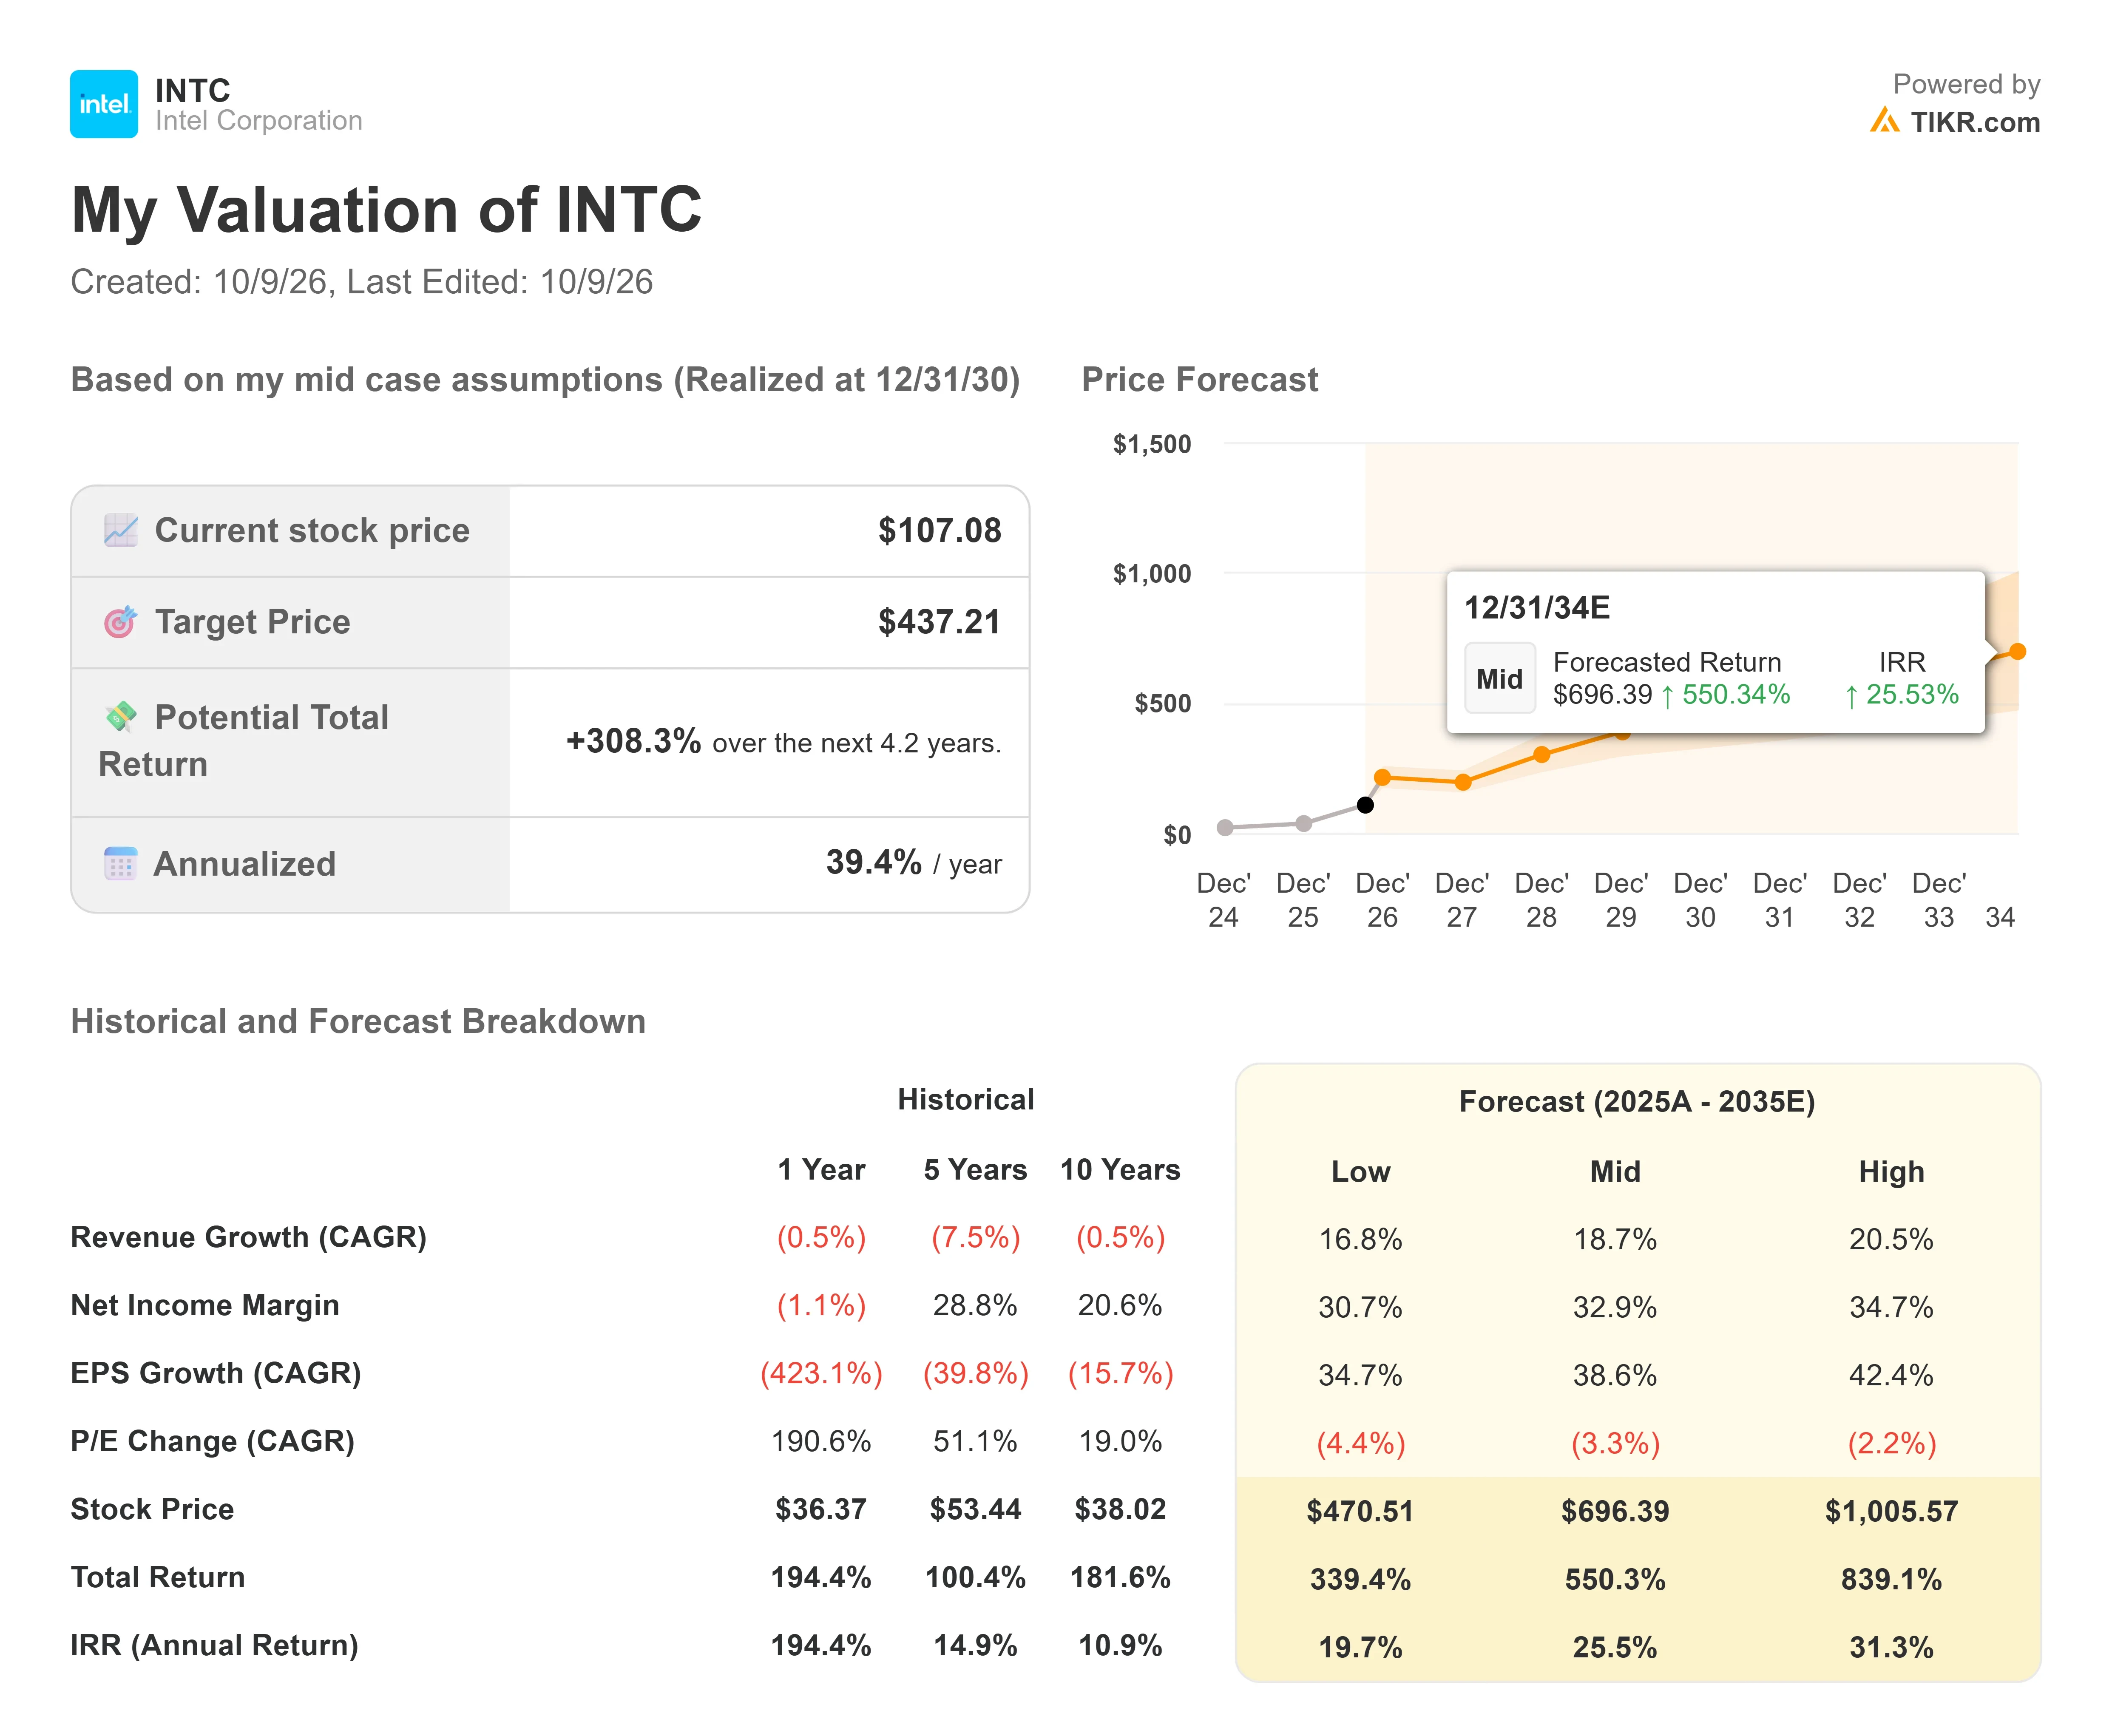
- Current Price: $107.08
- Target Price (Mid): ~$437
- Potential Total Return: ~308%
- Annualized IRR: ~39% / year
See analysts’ growth forecasts and price targets for Intel stock (It’s free!) >>>
TIKR’s mid-case is a scenario, not a forecast. Over the model’s 2025 to 2035 window, it assumes around 19% annual revenue growth, a net margin near 33%, and a P/E that contracts about 3% a year. For comparison, consensus revenue through 2030 grows around 17% a year, though only seven analysts cover 2030.
The multiple is the biggest swing factor. Intel trades at 63x NTM P/E, compared with 19x for NVIDIA (NVDA) and 56x for Advanced Micro Devices (AMD), and a 3% annual contraction keeps most of whatever premium the stock carries. Analysts are more cautious, with 14 Buy, 1 Outperform, 32 Hold, 1 Underperform, and 1 Sell ratings. The upside comes if interest in Intel’s foundry turns into signed volume. The downside comes if the premium shrinks toward peers before earnings catch up.
Conclusion
October 29 is Intel’s chance to answer with its own numbers. Consensus expects about $16.4 billion in third-quarter revenue. A beat would make six straight quarters, and a print at or above the $16.8 billion top of guidance would be a clear one. The 2027 CapEx signal matters just as much. Spending that keeps the 2028 free cash flow turn in consensus intact supports the multiple, while a large jump without new revenue visibility puts it under pressure.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Intel stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intel could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!