


Key Takeaways
- Marvell Technology is down 51% from its June high, and most of the drop since Oct. 28 tracks its all-stock deal for Lumentum and the Democratic sweep in Congress.
- B. Riley cut its price target to $250 from $275 on Nov. 9, its second cut in a week, and kept its Buy rating.
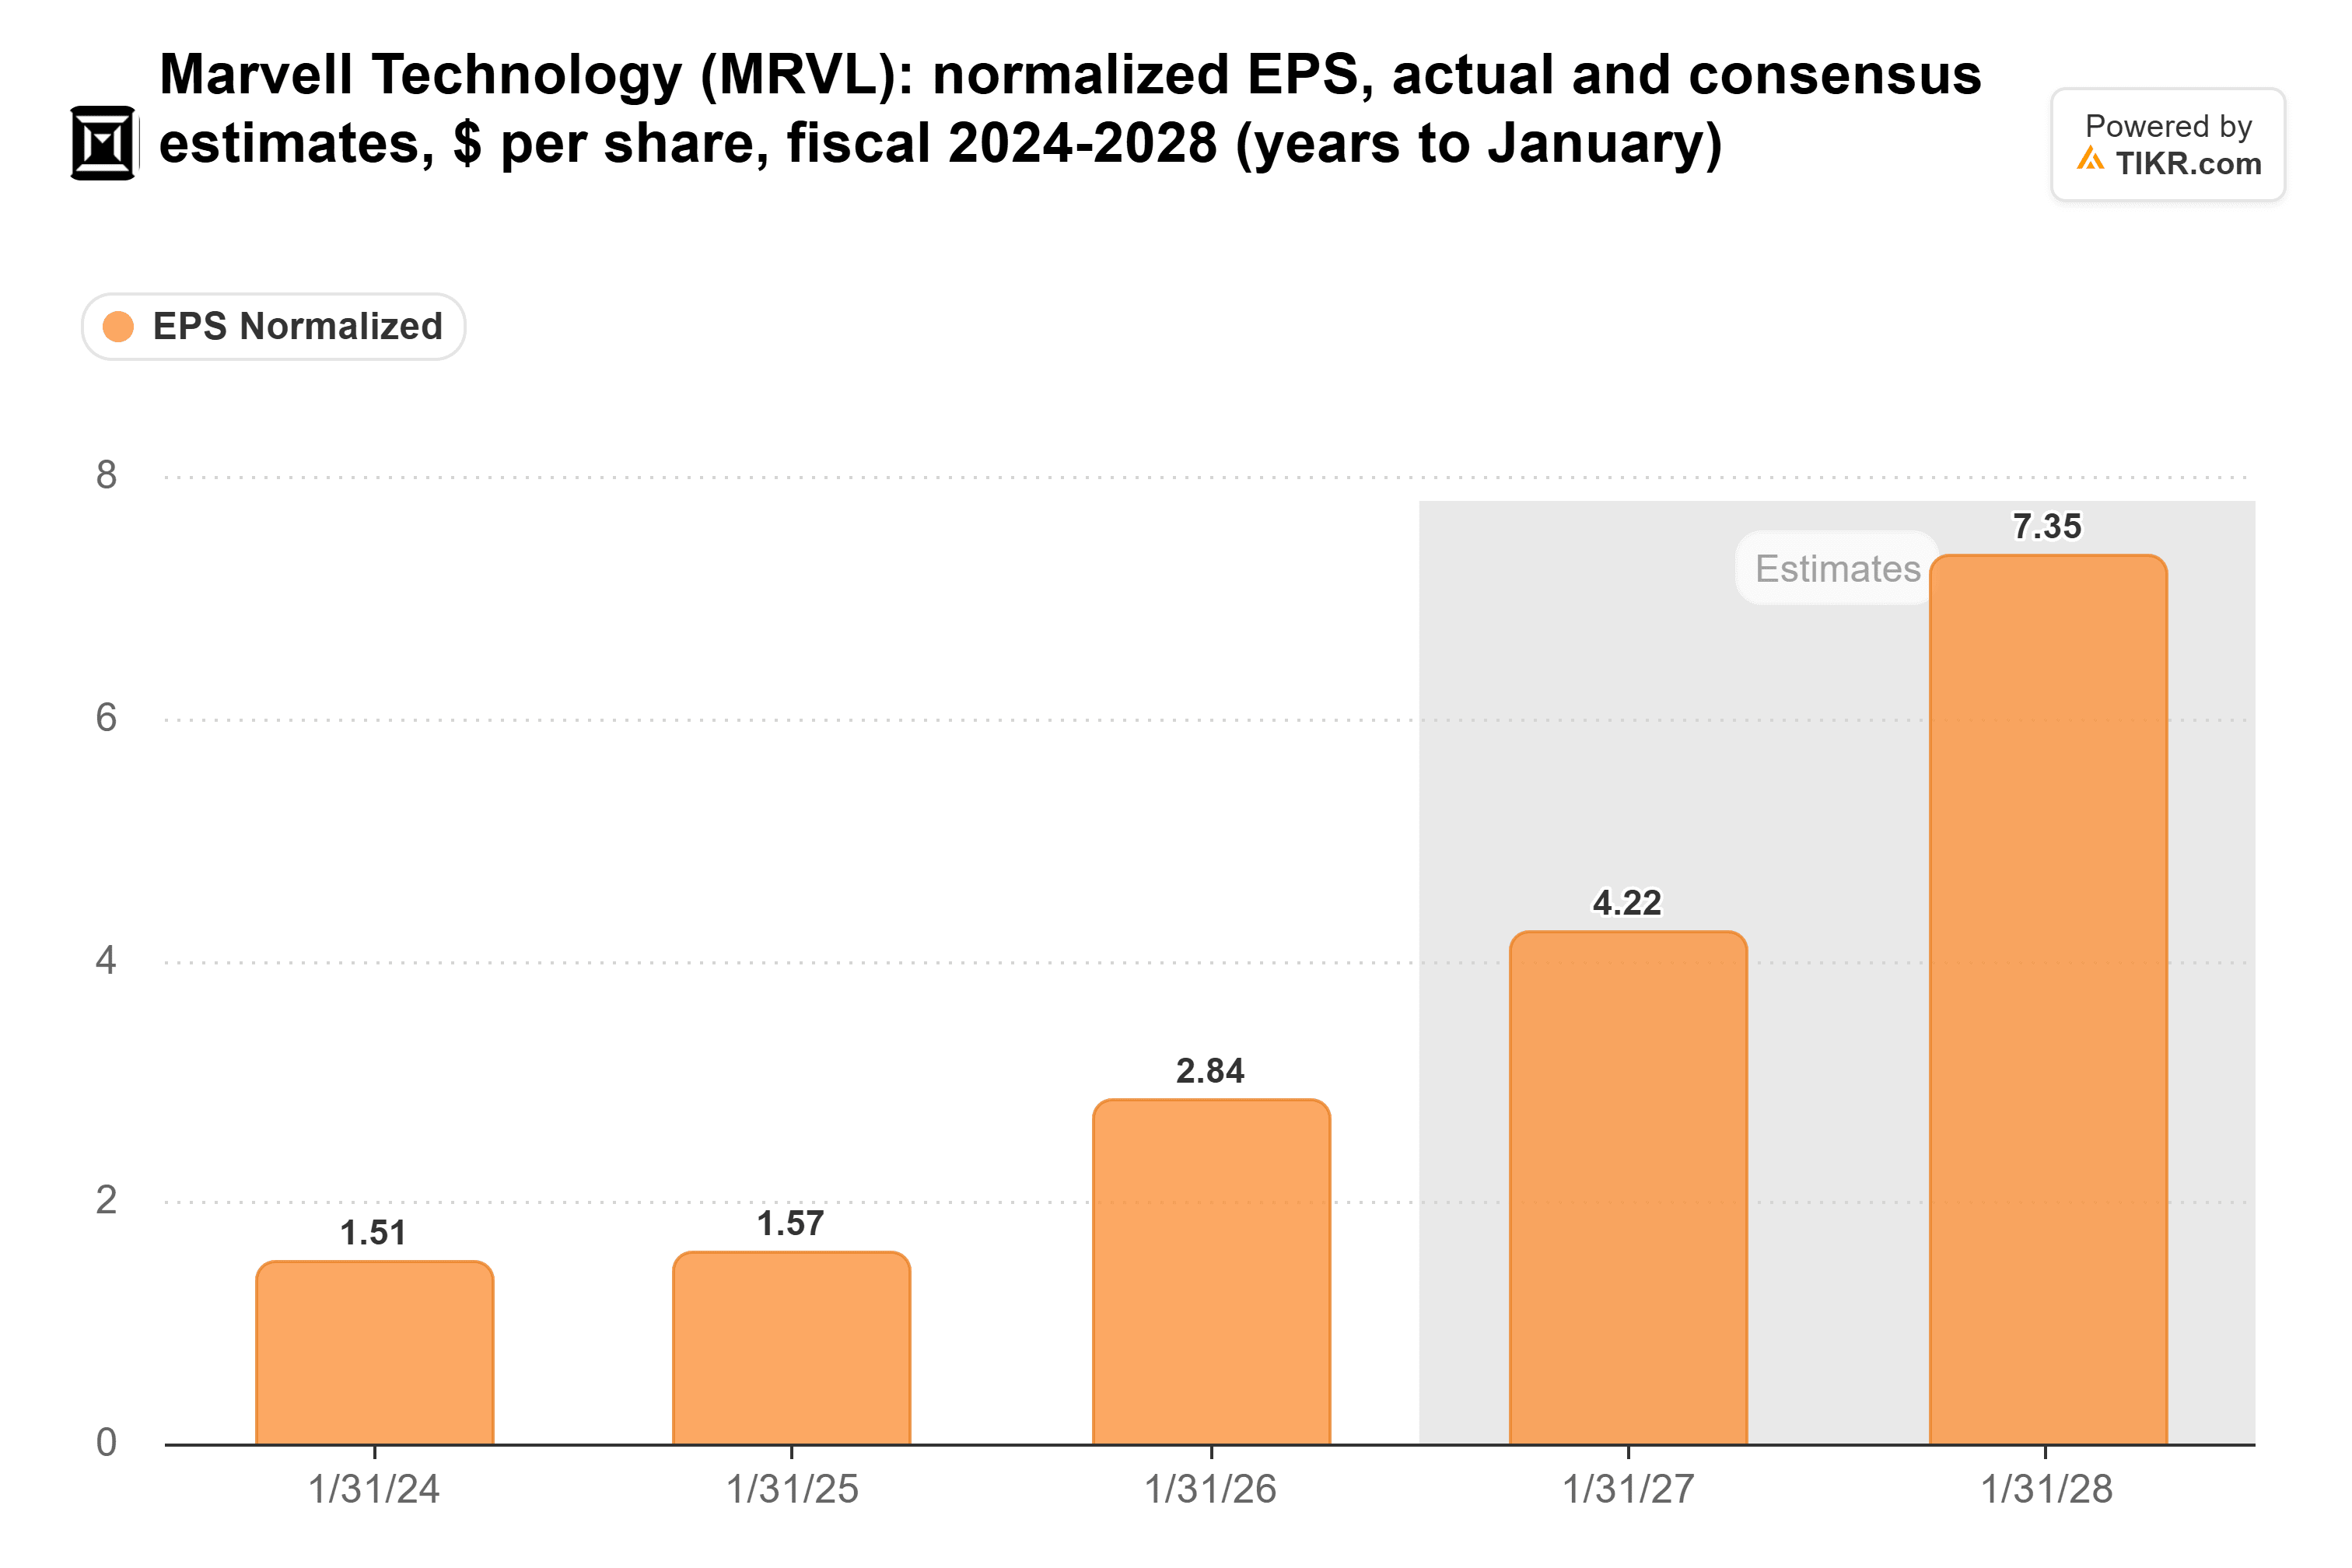
- Analysts’ consensus earnings estimate for the fiscal year ending January 2028 has risen to $7.35 a share from about $6.24 90 days ago, even as the stock fell.
- At 25x forward earnings at the Nov. 6 close, the stock looked priced for the worst of the Lumentum deal, which puts B. Riley’s $250 within reach if Marvell’s Dec. 1 report holds up.
Marvell Technology (MRVL) is down 51% from its June high, and the latest leg down came after it agreed to buy Lumentum (LITE) in an all-stock deal on Nov. 2. On Nov. 9, B. Riley cut its price target for the second time in a week, to $250 from $275, and kept its Buy rating. Even after a 9.5% rebound that day, as tech stocks rallied with the broader market, that target sits 62% above Marvell’s $154.60 close.
A $115 billion deal, then an election
Lumentum holders get 4.5 Marvell shares for each of theirs, in a deal valuing Lumentum at $115 billion including debt. Marvell CEO Matt Murphy called the shift to optical connections “an opportunity that comes along once in a generation.” The stock fell 13% that day. Then Democrats won both chambers of Congress in the Nov. 3 midterms, some on pledges to get tougher on data-center construction. Marvell fell 7% on Nov. 4 and another 16% on Nov. 5 as AI stocks sold off.
The business itself looks intact: Marvell said in the deal release that third-quarter revenue is tracking the midpoint of its $3.15 billion guidance, and it narrowed the range to plus or minus 2% from 5%.
TIKR tracks 44 analysts on Marvell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
B. Riley trimmed twice and still says buy
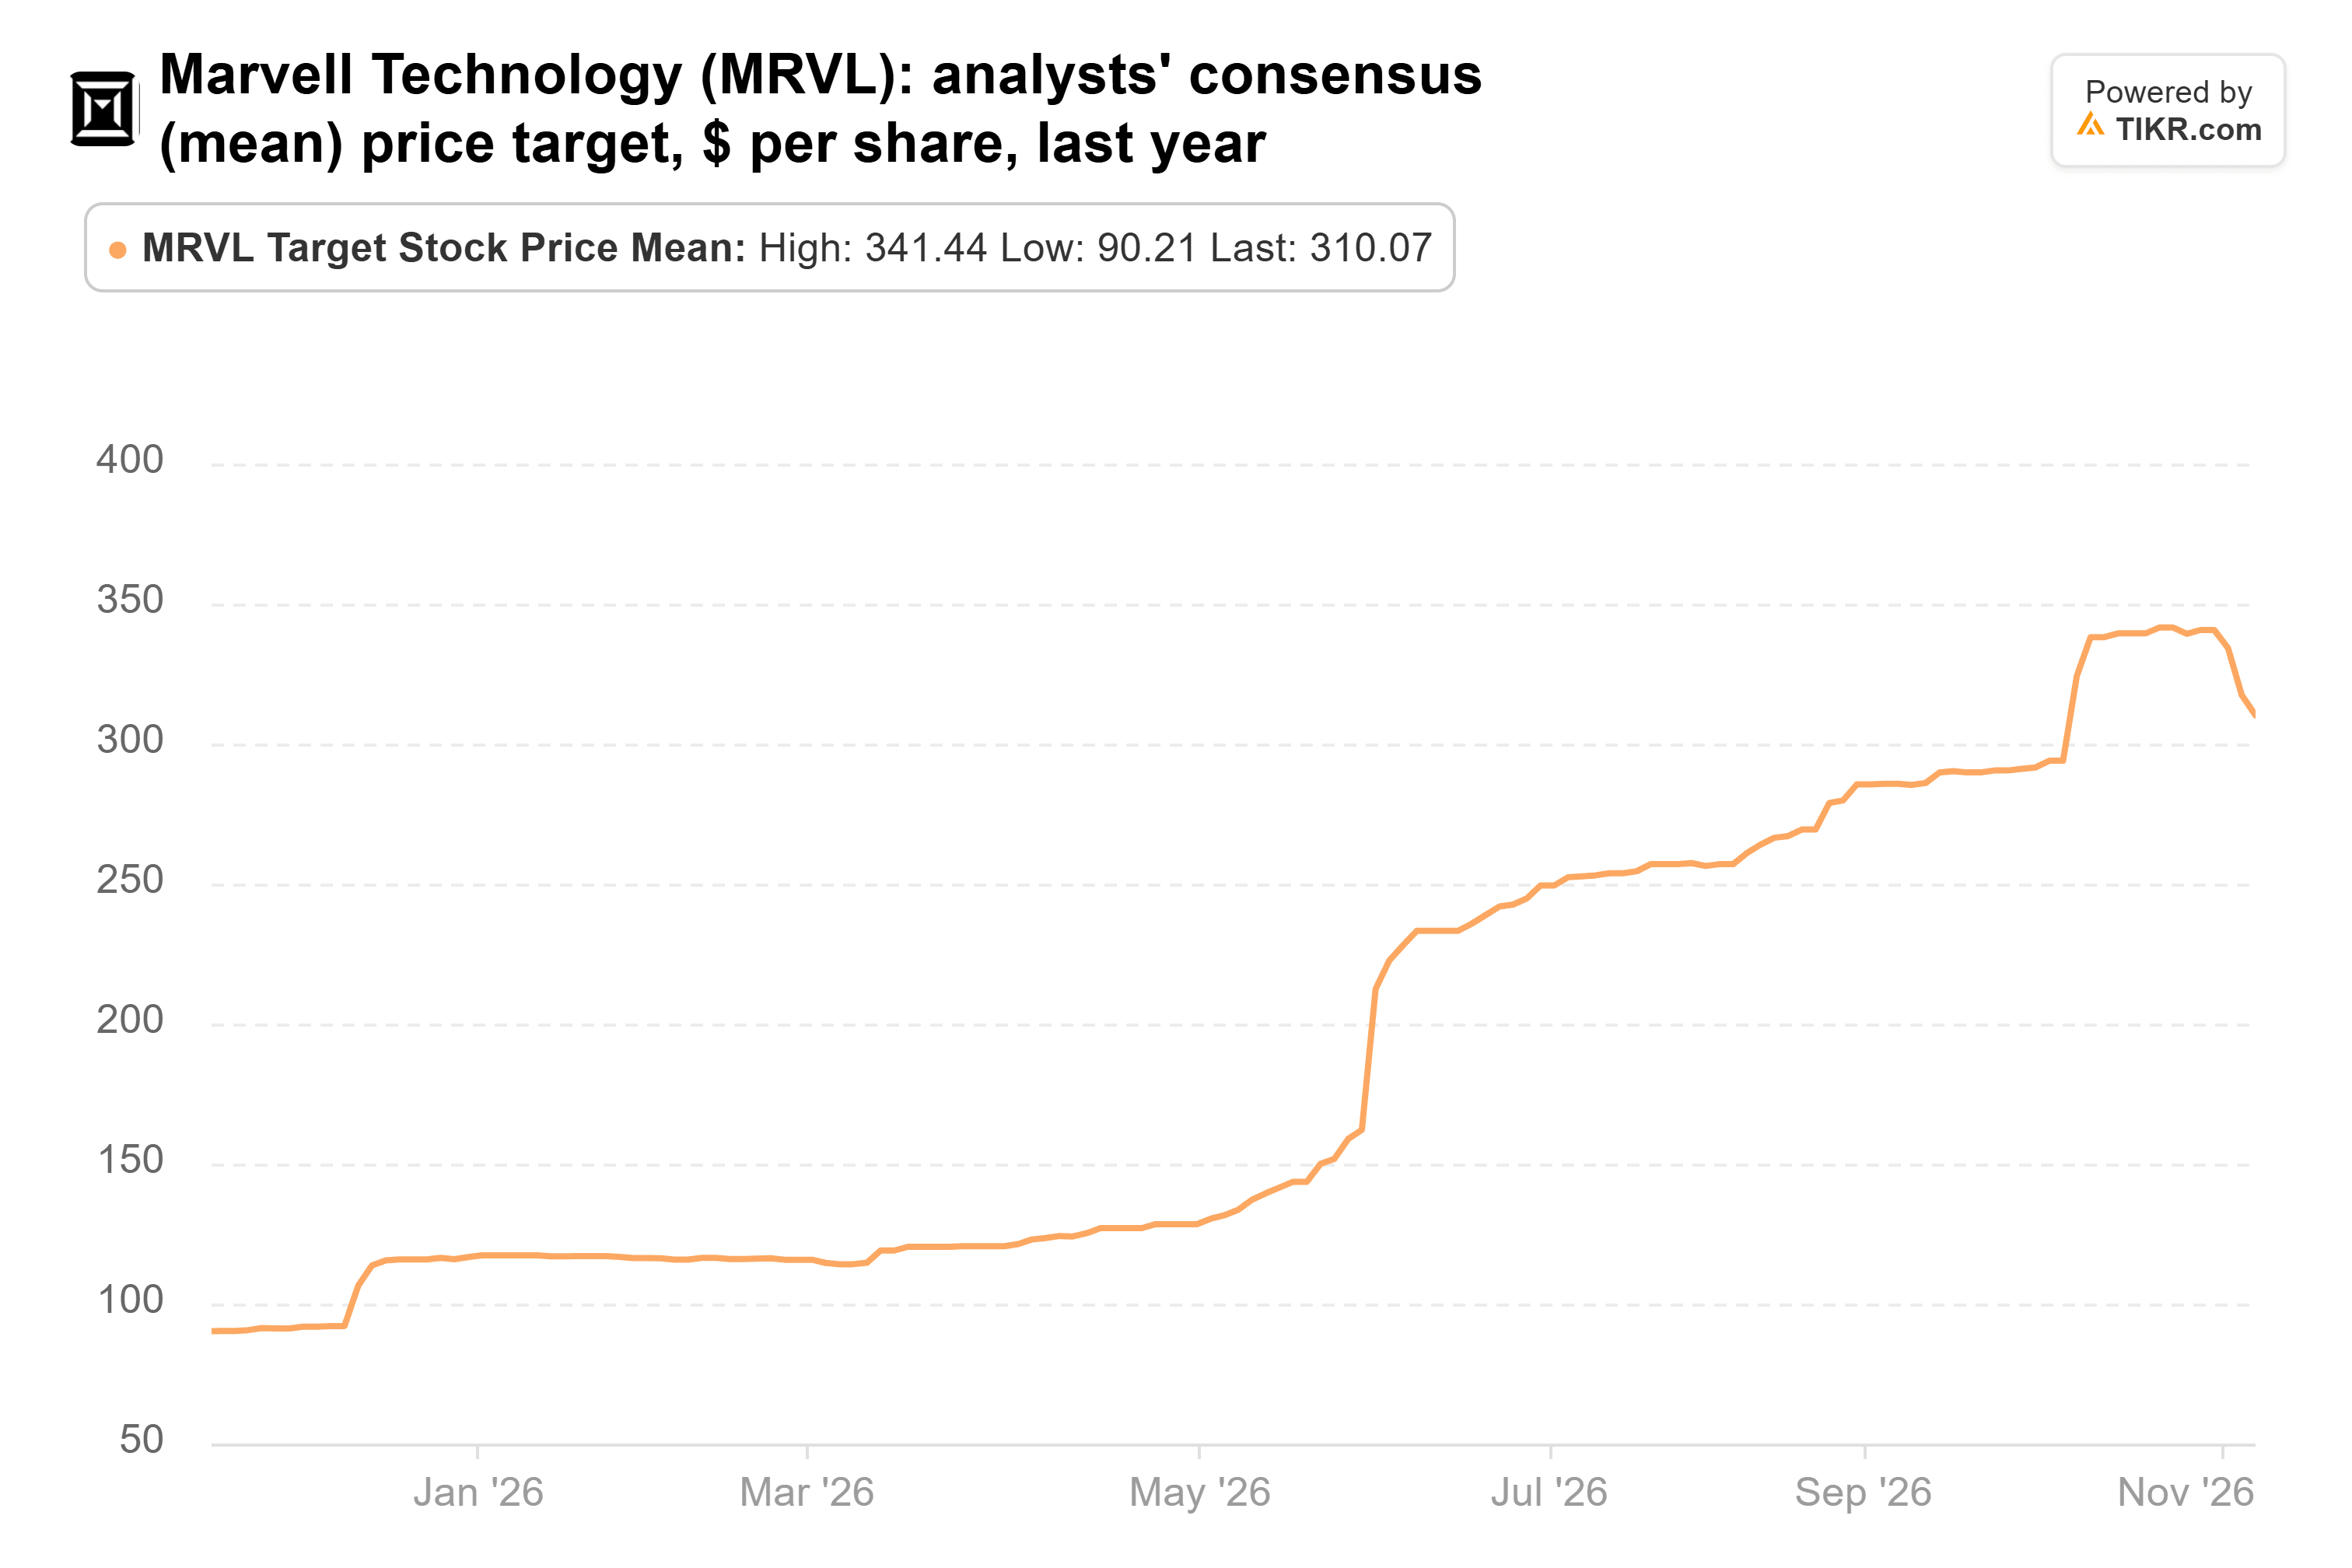
Craig Ellis cut B. Riley’s target to $275 from $365 on Nov. 3, after the deal. The firm cut again on Nov. 9, lowering targets on 13 chip stocks over the risk that AI data-center projects get pushed out after the election. It warned that near-term estimates may have peaked, but said chip valuations already sit near past crisis lows. The $250 matches RBC Capital’s and sits 19% below the $310 consensus, with TD Cowen’s $175 the lowest of the 41 targets TIKR tracks. The consensus has slipped from its October peak but remains far above the $90 of a year ago:
What $250 asks for
Analysts haven’t cut estimates yet. The consensus for the fiscal year ending January 2028 is $7.35 a share, up from about $6.24 90 days ago, while this fiscal year’s $4.22 has edged up too:
At the Nov. 6 close, Marvell traded at 25x forward earnings, well below its five-year average of 33x:
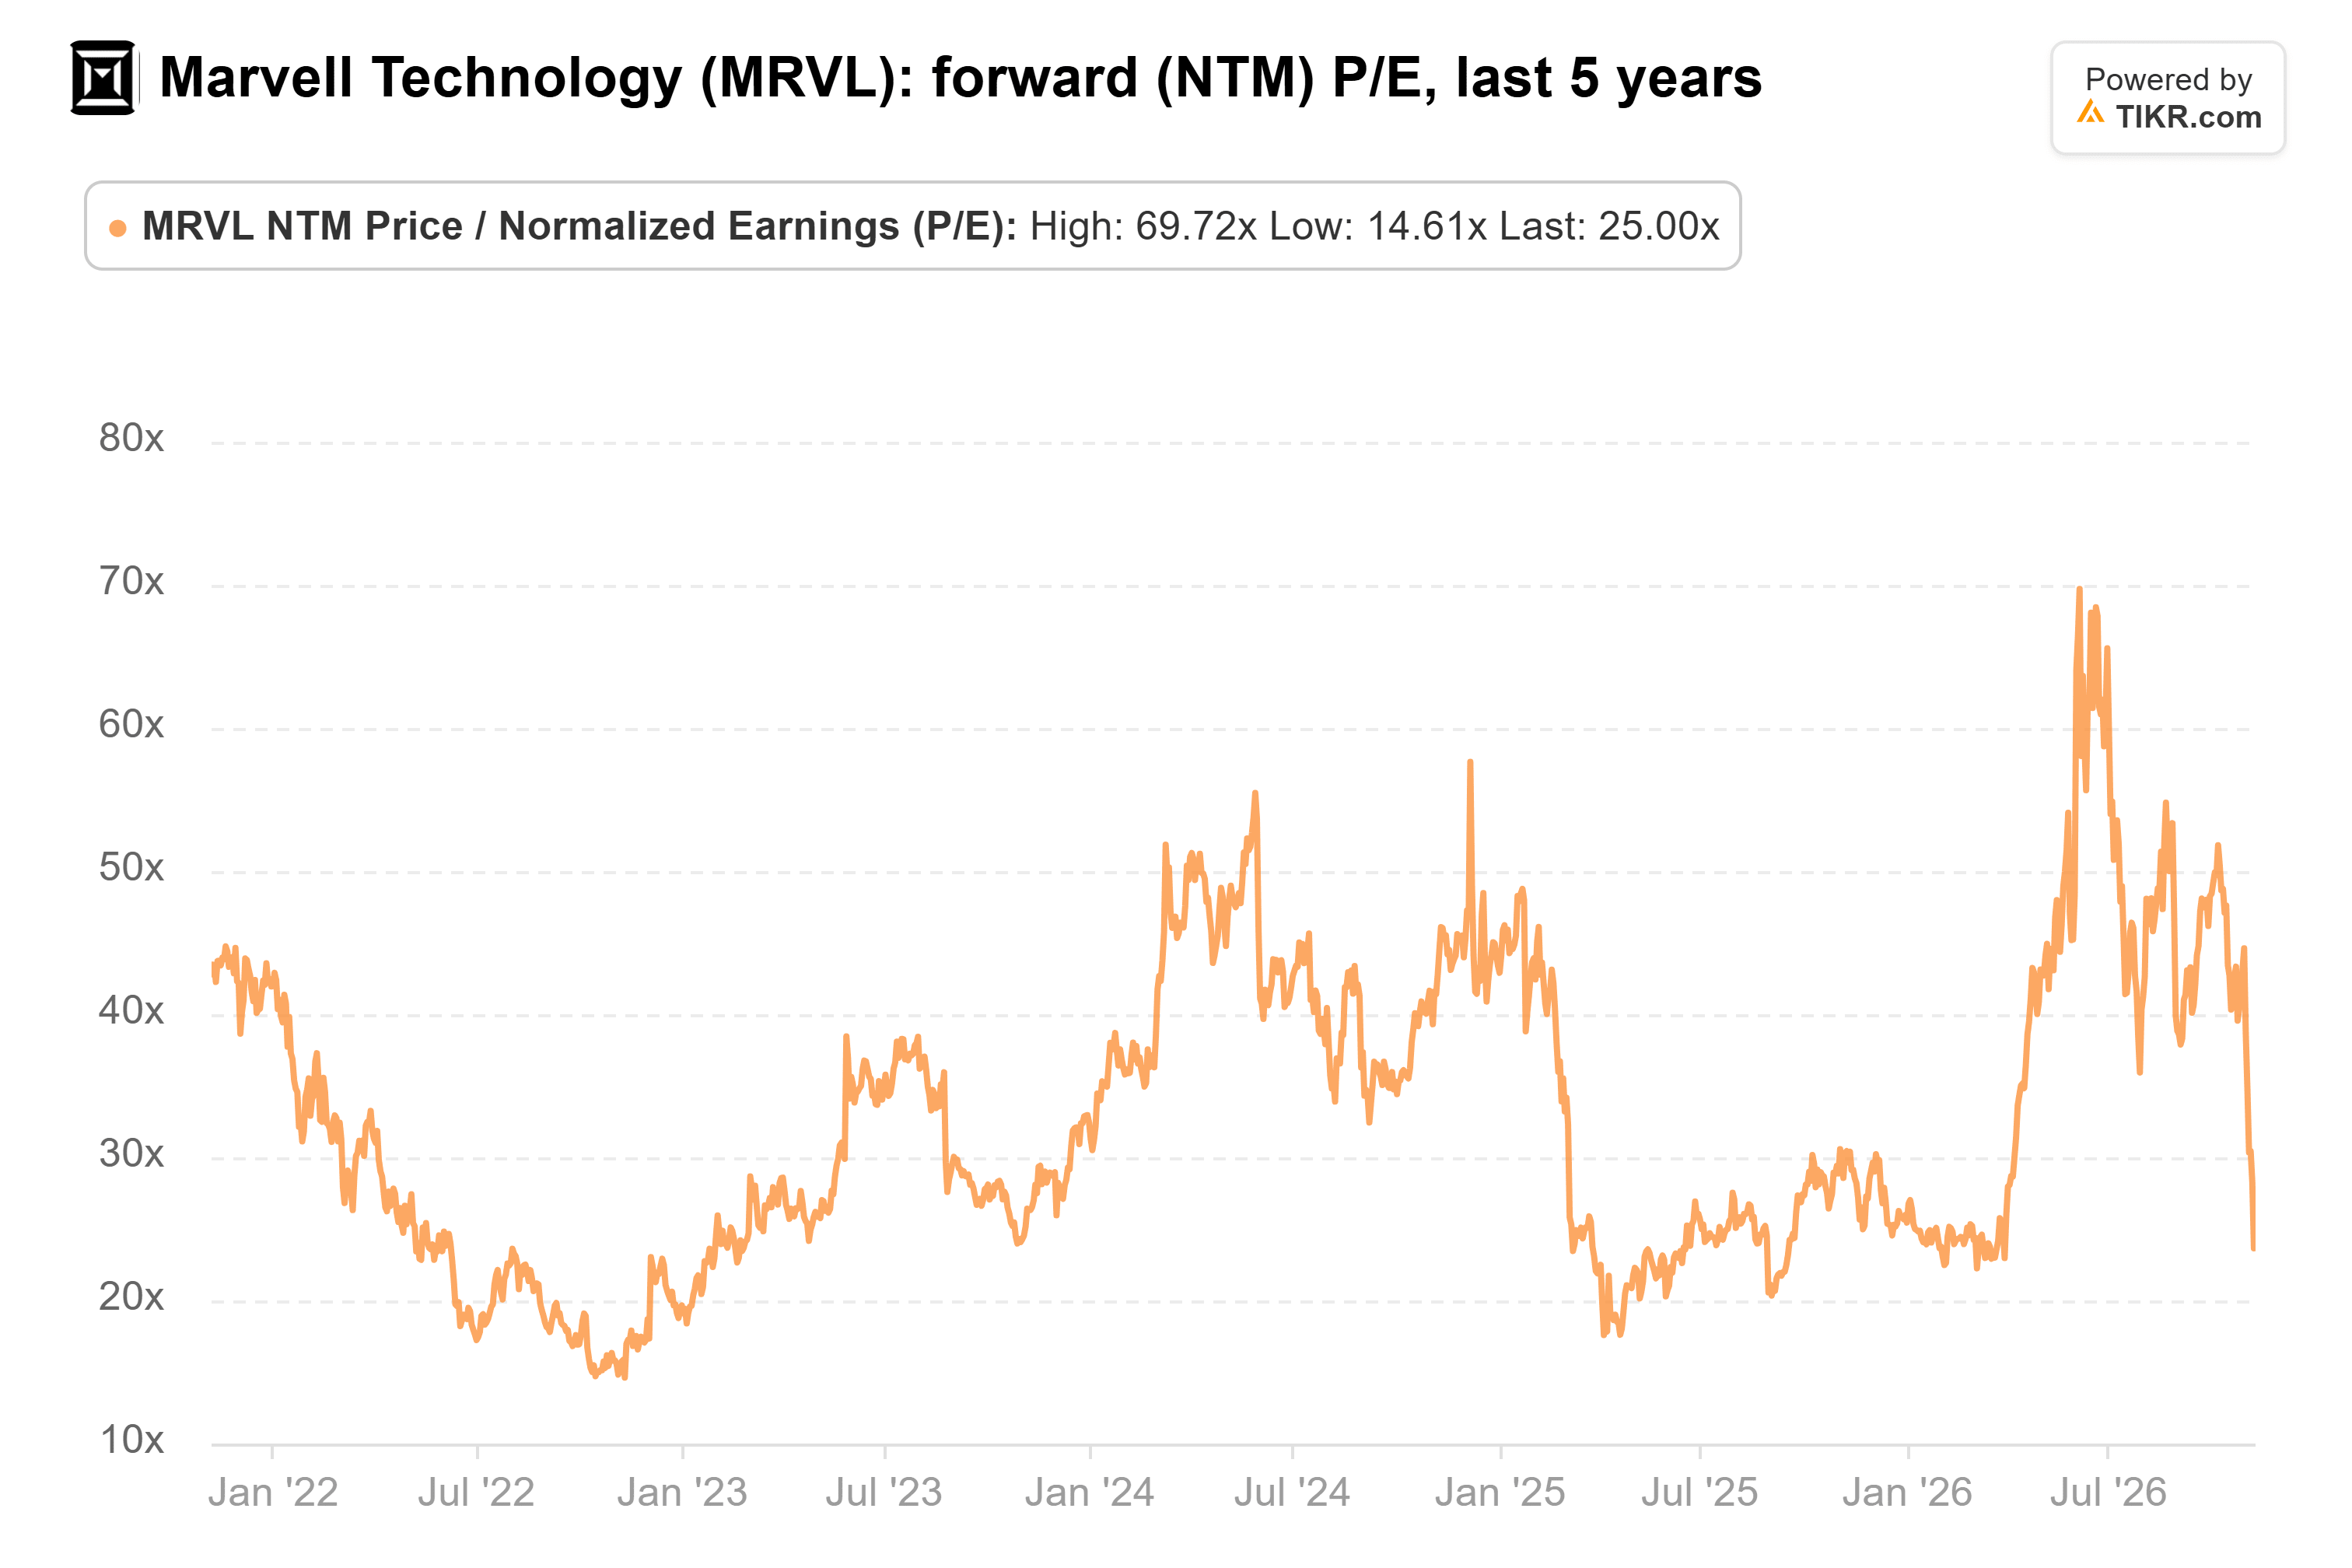
B. Riley’s $250 works out to 44x those earnings, far short of June’s 70x. On fiscal 2028’s $7.35, though, $250 is about 34x, near its five-year average, so the target needs that estimate to hold.
Dilution is the catch
Marvell’s holders give up about a third of the company to get Lumentum, and the deal still needs shareholders and regulators to sign off, China’s review among them. Closing isn’t expected until the first half of 2028, so it barely touches the estimates above. Management expects it to add to non-GAAP earnings per share in its first year after closing.
The numbers side with B. Riley. A 25x multiple on rising estimates prices in the worst of a deal that hasn’t closed. Marvell reports its fiscal third quarter after the close on Dec. 1. Revenue at the guidance midpoint plus a reaffirmed fiscal 2028 outlook of about $20 billion would put $250 within reach.
So what is Marvell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





